
 Timber Laminating Adhesives Market | 2026-2036
Timber Laminating Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Timber Laminating Adhesives Market Outlook
Southeast Asia is rewriting the supply map for timber laminating adhesives as Vietnam and Indonesia expand engineered wood manufacturing clusters. H.B. Fuller Company leverages its PUR technology portfolio to dominate structural bonding applications in North American mass timber projects. Henkel AG & Co. KGaA anchors European demand through cold-cure adhesive systems optimized for CLT production lines. Sika AG competes on construction-grade epoxy formulations that sustain load-bearing performance across humid climates.
Timber laminating adhesives are thermosetting or reactive polymer systems formulated to bond wood laminates under heat, pressure, or moisture-cure conditions, typically achieving shear strengths exceeding 6 MPa for structural certification. Their primary purpose is to create engineered wood products—glulam beams, cross-laminated timber panels, and laminated veneer lumber—that substitute steel and concrete in load-bearing applications. PUR adhesives lead in structural segments due to superior moisture resistance and European EN 15425 compliance, while PVA dominates furniture and non-structural panel bonding where cost sensitivity shapes procurement. UV-curable systems represent the fastest-growing technology tier as flooring manufacturers adopt inline cure processes to eliminate press-time bottlenecks.
EPA formaldehyde emission standards under TSCA Title VI and the EU Construction Products Regulation shape adhesive formulation mandates across major demand centers. The EU Ecolabel and Nordic Swan certification schemes reward low-isocyanate PUR systems, redirecting R&D investment toward bio-based polyols and hardened amine catalysts. Stakeholders must monitor evolving mass timber building codes in jurisdictions adopting tall wood construction allowances, as code recognition directly unlocks structural adhesive specification volumes.
Market Dynamics
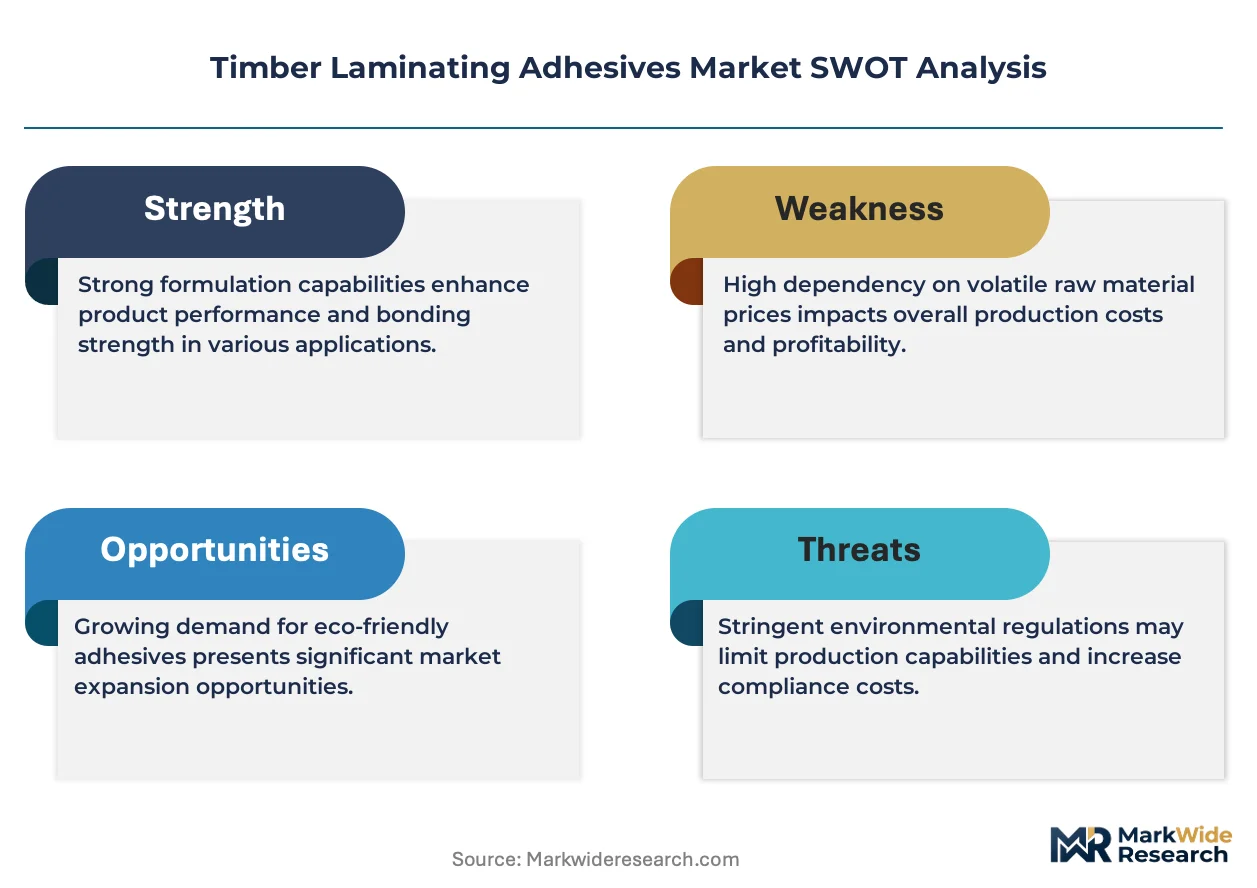
Cross-laminated timber construction codes are accelerating specification volumes for structural adhesives as jurisdictions expand tall wood allowances, while EU Ecolabel criteria redirect formulation chemistry toward bio-based feedstocks.
Growth Catalysts
- Mass Timber Building Codes:Jurisdictions adopting tall wood construction allowances unlock structural adhesive demand for CLT and glulam applications in commercial high-rises.
- EU Timber Regulation:Due diligence requirements for timber legality verification strengthen preference for certified adhesive systems in European engineered wood supply chains.
- Moisture-Cure PUR Systems:Cold-cure polyurethane adhesives optimized for automated CLT production lines reduce press cycle times and energy consumption.
Market Restraints
- Isocyanate Feedstock Volatility:MDI and polyol price swings compress margin stability for PUR adhesive manufacturers serving structural segments.
- Certification Timeline Friction:EN 15425 and ASTM D2559 structural certification cycles extend 18-24 months, delaying new product commercialization.
- Steel-Concrete Substitution Resistance:Conservative building codes and contractor familiarity with mineral-based materials slow adhesive-specified timber adoption in load-bearing applications.
Strategic Opportunities
- Vietnam Engineered Wood Clusters:Expanding plywood and LVL manufacturing capacity creates demand for formaldehyde-free adhesive systems meeting export market emission standards.
- UV-Curable Flooring Lines:Inline cure processes for laminate flooring eliminate press bottlenecks, enabling adhesive technology convergence with photoinitiator chemistry.
- US Inflation Reduction Act:Mass timber construction incentives in federal building programs accelerate specification of certified structural bonding systems.
Industry Challenges
- Formulation Chemist Shortage:Specialized expertise in thermoset polymer synthesis for wood substrates remains concentrated among aging technical workforces in Germany and Austria.
- Multi-Certification Burden:Manufacturers must simultaneously maintain EPA TSCA Title VI, CARB ATCM, and EU Ecolabel compliance, multiplying testing and documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Timber Laminating Adhesives Market |
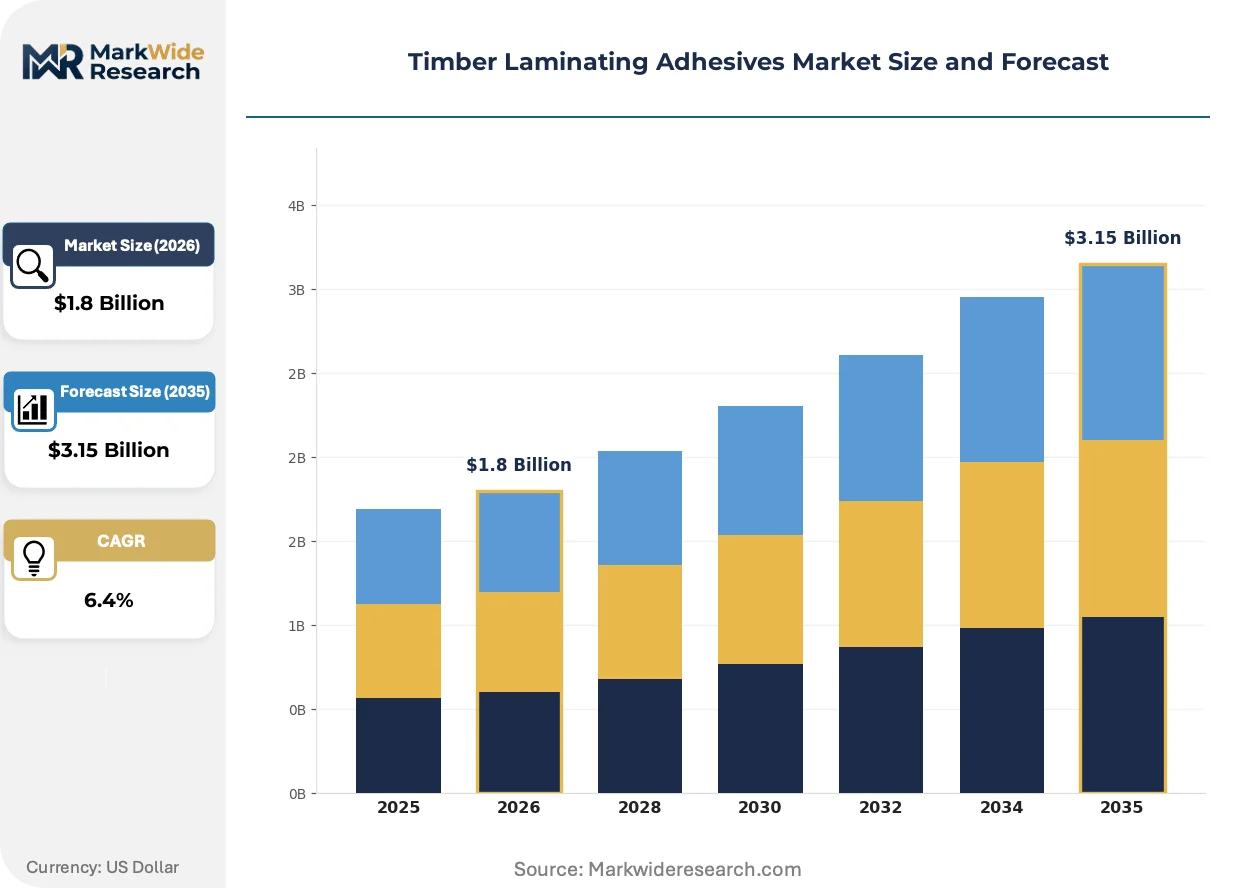
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PUR, PVA, Epoxy, UV-Curable Application: Construction, Furniture, Flooring, Panels End User: OEMs, Contractors, Retailers, Wholesalers Technology: Hot Melts, Cold Cure, Reactive, Non-Reactive |
| Companies Covered | H.B. Fuller Company, Henkel AG & Co. KGaA, Sika AG, 3M Company, Dow Inc., Arkema, Ashland Inc., BASF SE, Franklin International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Timber Laminating Adhesives Market Strategic Shifts
Adhesive formulation is pivoting toward low-carbon chemistry as regulatory thresholds tighten and mass timber construction scales, compressing development cycles for next-generation bonding systems.
Inline spectroscopic cure monitoring is digitizing quality assurance in engineered wood manufacturing. Flooring and panel producers deploy near-infrared sensors to verify adhesive polymerization in real time, eliminating destructive testing and reducing press hold times. This technology is digitizing process control workflows that previously relied on batch sampling and laboratory validation.
REACH restrictions on aromatic isocyanates are forcing reformulation of conventional PUR systems across European CLT production. Manufacturers substitute aliphatic isocyanates and hardened amine catalysts to maintain EN 15425 compliance while reducing occupational exposure hazards. German and Austrian adhesive suppliers bear the steepest adaptation costs given their concentration in structural bonding markets.
Buyer consolidation among North American mass timber contractors is compressing adhesive procurement cycles and elevating technical service expectations. Large-scale CLT fabricators now demand dedicated formulation support and just-in-time delivery, displacing traditional distributor relationships. This pattern is most pronounced in Pacific Northwest construction corridors where integrated design-build firms dominate project pipelines.
Timber Laminating Adhesives Market Segmentation
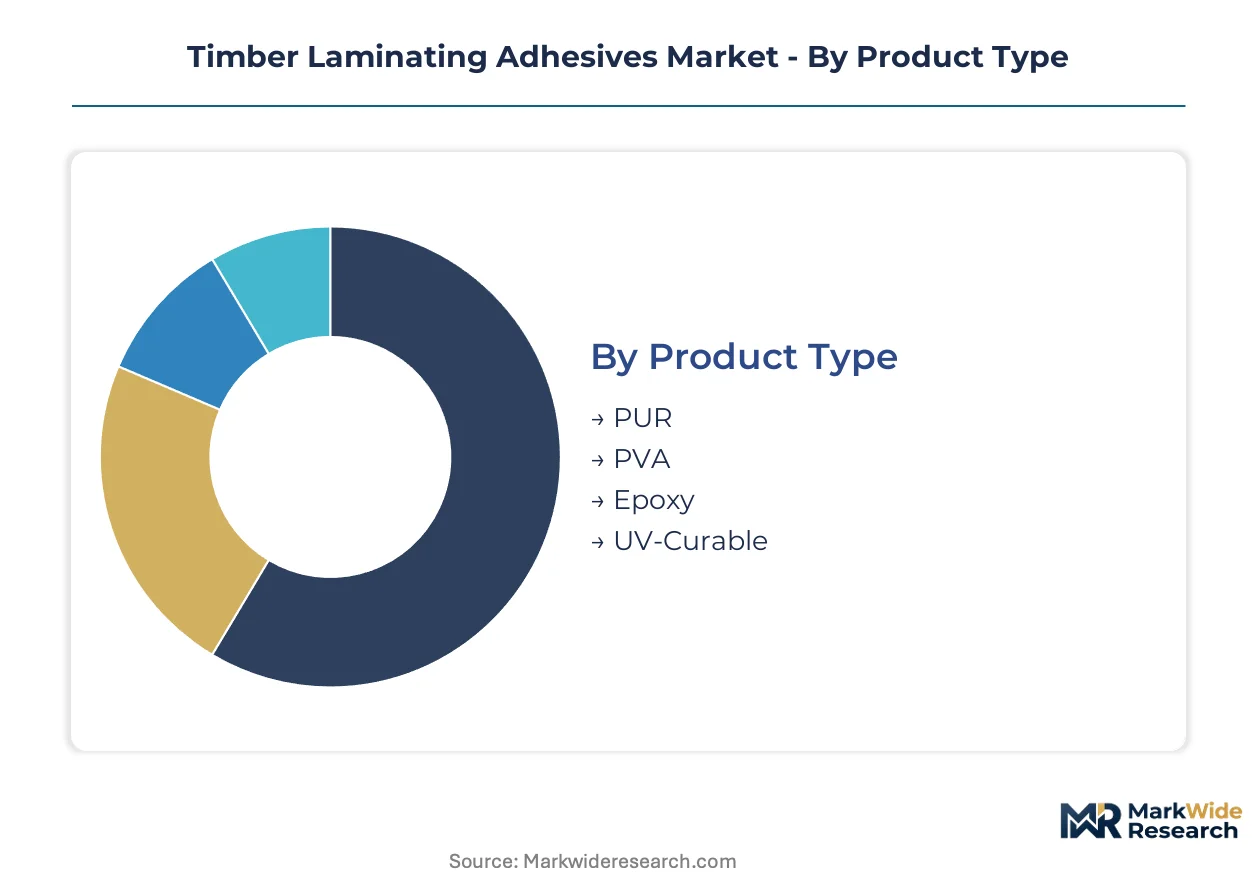
Timber laminating adhesives serve radically different performance requirements across structural and decorative applications. Segmentation reveals how formulation chemistry, cure mechanisms, and distribution channels align with end-use certification demands and production economics.
Product Type:
Mature polyurethane systems dominate structural certification portfolios, while emerging photopolymer platforms reshape flooring manufacturing velocity.
- PUR:Moisture-cure polyurethane formulations achieve EN 15425 and ASTM D2559 compliance for load-bearing glulam and CLT assemblies. Demand concentrates in German and Austrian engineered wood clusters where automated production lines favor cold-cure systems with sub-30-minute press cycles.
- PVA:Polyvinyl acetate emulsions serve furniture and non-structural panel bonding where cost sensitivity outweighs moisture resistance requirements. European cabinetry manufacturers specify low-formaldehyde PVA grades to meet EU Ecolabel criteria without PUR price premiums.
- Epoxy:Two-component systems deliver superior creep resistance for heavy timber bridge decks and marine applications.
- UV-Curable:Acrylate-based photopolymers enable inline cure processes for laminate flooring, eliminating press bottlenecks.
PUR retains volume leadership; UV-Curable holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-grade structural bonding from commodity panel assembly.
- Construction:Cross-laminated timber and glulam beams in commercial high-rises demand adhesives with documented shear strength exceeding 6 MPa and formaldehyde emissions below EPA TSCA Title VI thresholds. Pacific Northwest mass timber contractors in the United States specify certified systems for projects qualifying for federal incentives.
- Flooring:Laminate and engineered hardwood producers adopt UV-curable and hot-melt systems to accelerate line speeds. Vietnamese manufacturing clusters serving export markets prioritize low-VOC formulations compliant with CARB ATCM Phase 2.
- Furniture:Decorative laminating for cabinetry and millwork emphasizes aesthetic glue-line quality and sandability.
- Panels:Plywood and OSB manufacturing utilizes urea-formaldehyde and melamine-urea resins for interior-grade structural sheathing.
Construction commands premium pricing; Flooring is expanding most quickly through manufacturing automation.
End User:
Customer type determines technical service intensity and procurement scale.
- OEMs:Integrated engineered wood manufacturers in Austria and Germany maintain captive adhesive formulation expertise and direct supplier relationships. These facilities demand just-in-time delivery and dedicated R&D support for production line optimization.
- Contractors:Mass timber erection specialists in the United States specify certified structural adhesives for CLT installation, requiring documentation chains for building code approval.
- Retailers:Hardware and building material distributors serve small-scale carpentry and repair markets with consumer-grade PVA and epoxy formulations.
- Wholesalers:Regional distributors aggregate volume for mid-sized panel producers and furniture manufacturers.
OEMs retain volume leadership; Contractors hold the steepest expansion curve as tall wood construction codes proliferate.
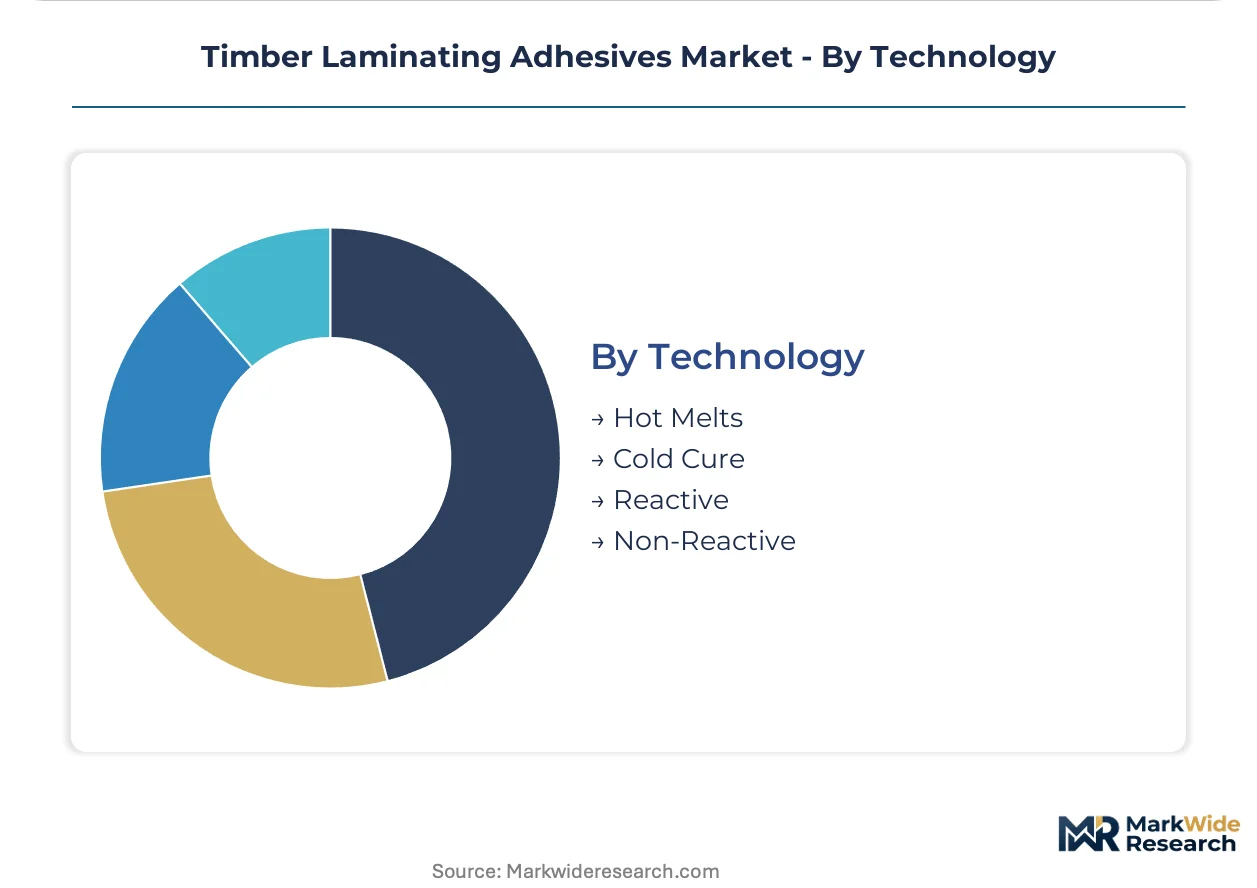
Technology:
Volume concentration favors reactive systems, while margin capture shifts toward specialized cure mechanisms.
- Reactive:PUR and epoxy systems polymerize through moisture or chemical catalysts to form irreversible bonds. German adhesive suppliers dominate this segment through decades of EN 15425 certification experience and hardened amine catalyst expertise.
- Cold Cure:Ambient-temperature polyurethane systems reduce energy consumption in CLT production lines. Austrian manufacturers pioneered these formulations for automated layup presses.
- Hot Melts:Thermoplastic adhesives for edge banding and temporary assembly offer rapid set times without clamping.
- Non-Reactive:PVA and pressure-sensitive adhesives serve repositionable and reversible bonding applications.
Reactive retains volume leadership; Cold Cure holds the steepest expansion curve through energy efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA formaldehyde emission standards under TSCA Title VI anchor North American demand architecture, while REACH restrictions on aromatic isocyanates reshape European formulation chemistry. Mass timber building codes in specific jurisdictions unlock structural adhesive volumes through certified procurement mandates.
United States
Pacific Northwest mass timber contractors specify certified PUR systems for federal incentive-qualifying projects. The Inflation Reduction Act channels construction investment toward engineered wood assemblies. Oregon and Washington fabrication clusters absorb cold-cure adhesive volumes for automated CLT production lines.
Germany
EN 15425 certification requirements concentrate structural adhesive demand among Bavarian and Baden-Württemberg engineered wood manufacturers. ECHA REACH compliance deadlines force aliphatic isocyanate substitution in conventional PUR formulations. The Black Forest region sustains captive formulation expertise for thermoset polymer synthesis.
Austria
Automated CLT production lines in Upper Austria pioneered ambient-temperature polyurethane systems for layup press optimization. EU Ecolabel criteria redirect R&D toward bio-based polyol feedstocks. Styrian adhesive suppliers maintain hardened amine catalyst specialization for moisture-cure applications.
Vietnam
Expanding plywood and LVL manufacturing clusters in Binh Duong Province create demand for formaldehyde-free adhesive systems. CARB ATCM Phase 2 compliance requirements shape export-market formulation specifications. Ho Chi Minh City industrial zones attract adhesive distributors serving ASEAN engineered wood producers.
Canada
British Columbia tall wood construction allowances accelerate structural adhesive specification for commercial high-rise applications. Health Canada emission guidelines align with EPA TSCA Title VI thresholds for cross-border supply chains. Vancouver mass timber design-build firms consolidate procurement around certified bonding systems.
Timber Laminating Adhesives Market Competitive Environment
Specialized adhesive formulators and diversified chemical conglomerates split the market along certification-depth and scale vectors. European suppliers concentrate structural bonding expertise around EN 15425 compliance, while North American players leverage PUR technology portfolios for mass timber applications. Three archetypes dominate: certification-heavy specialists, diversified materials giants, and regional distribution-focused operators. Capacity expansion in Southeast Asian manufacturing clusters and strategic technology licensing for UV-curable platforms represent the dominant competitive moves.
Within the certification-specialist tier, H.B. Fuller Company and Henkel AG & Co. KGaA exemplify divergent geographic anchoring strategies. H.B. Fuller occupies a position tied to North American structural applications, while Henkel represents European cold-cure system optimization. Sika AG sits within the construction-grade epoxy segment, anchoring load-bearing performance positioning across humid climate specifications.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Sika AG |
| 3M Company |
| Dow Inc. |
| Arkema |
| Ashland Inc. |
| BASF SE |
| Franklin International |
| Others |
Value Chain & Pricing Dynamics
Rhine-Alpine corridor freight rates transmit MDI and polyol cost volatility directly into German adhesive pricing, compressing margins for PUR formulators while amplifying price spreads between EN 15425-certified structural grades and commodity panel bonding tiers.
Pricing Analysis
Geographic price spreads between Bavarian CLT manufacturers and Vietnamese plywood exporters exceed certification-grade differentials. Three-tier pricing structure across EN 15425-certified structural, CARB ATCM-compliant standard, and economy furniture grades anchors the model. Price differentiation hinges on certification level and volume scale. Pricing pressure stems from isocyanate feedstock volatility squeezing PUR margins. Furniture OEMs exhibit highest price sensitivity; mass timber contractors absorb premium for code-compliant structural bonding.
Supply Chain Analysis
Upstream MDI and polyol production clusters in Germany, Belgium, and the Netherlands feed European adhesive formulators. Raw material dependencies center on aromatic isocyanates, bio-based polyols, and hardened amine catalysts. Single-source vulnerability concentrates in aliphatic isocyanate alternatives under REACH transition. Distribution runs through direct supplier relationships with Austrian and German engineered wood OEMs, bypassing traditional wholesale channels for structural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation support subscriptions outpace hardware revenue growth as CLT fabricators demand dedicated R&D partnerships and just-in-time delivery guarantees.
For Market Incumbents: Harden EN 15425 certification portfolios against emerging UV-curable entrants in flooring segments. Deepen backward integration into bio-based polyol feedstocks to hedge MDI price volatility. Expand captive formulation expertise in Upper Austria to defend against Asian cost-competitive PUR suppliers. For New Entrants and Emerging Players: Vietnam's Binh Duong Province engineered wood clusters offer the most penetrable white-space for formaldehyde-free adhesive systems. Target CARB ATCM Phase 2-compliant PVA and PUR grades for export-oriented LVL manufacturers. Pursue licensing partnerships with European catalyst specialists to shortcut EN 15425 certification timelines. For Investors and Strategic Acquirers: Cold-cure polyurethane specialists with automated CLT line integration capabilities represent the priority acquisition archetype. Long-term viability hinges on mass timber building code proliferation across North American jurisdictions. Monitor Oregon and Washington State tall wood construction allowance adoptions as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polyols | Reduces REACH compliance costs for German PUR formulators serving EN 15425 markets. |
| UV-Curable Platform Licensing | Accelerates Vietnamese flooring manufacturers past press-bottleneck constraints. |
| Long-Term Supply Agreement with CLT OEMs | Locks in volume commitments from Pacific Northwest mass timber contractors. |
| Joint Venture in Southeast Asian Manufacturing | Captures Binh Duong Province plywood cluster demand for CARB-compliant adhesives. |
| Green Manufacturing Transition | Secures EU Ecolabel preference for low-isocyanate PUR systems in Austrian CLT lines. |
Study Parameters
The analysis maps PUR, PVA, epoxy, and UV-curable adhesive sub-sectors, each validated through formulation chemists, engineered wood plant managers, and procurement leads at CLT fabricators. Primary interviews with technical R&D directors and distribution channel partners combined with secondary validation from customs/trade data, SEC 10-K filings, and Cefic industry reports. Bottom-up volume triangulation against top-down market sizing anchored forecast reliability.
Assumptions held fixed include current EPA TSCA Title VI and EU Ecolabel emission thresholds, while mass timber building code adoption rates and REACH aromatic isocyanate restriction timelines varied across scenarios. Segmentation dimensions modeled include adhesive chemistry, cure mechanism, application certification grade, and regional production hub concentration. CAGRs derived from adhesive volume intensity per engineered wood product type and production capacity expansion trajectories. Forecast inputs incorporated CLT press line automation adoption and bio-based feedstock substitution elasticities.
Macroeconomic conditions sit as an overlay; deviation in construction investment cycles, freight rate volatility, or isocyanate commodity pricing would shift the trajectory. Forecasts reflect assumptions about regulatory stability and certification timeline continuity. Specific risks include accelerated REACH restrictions, trade disruption in Southeast Asian supply corridors, and conservative building code revisions. Cross-checking against engineered wood production statistics from national industry associations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
High Temperature Adhesives and Sealants Market
Adhesives & Sealants
North America Electronics Adhesives Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
Global Elastic Adhesive Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Latex Binders Market
Adhesives & Sealants
2K Epoxy Adhesives Market