
 Middle East and Africa Human Fibrin Glue Market | 2026-2036
Middle East and Africa Human Fibrin Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Human Fibrin Glue Market Foresight
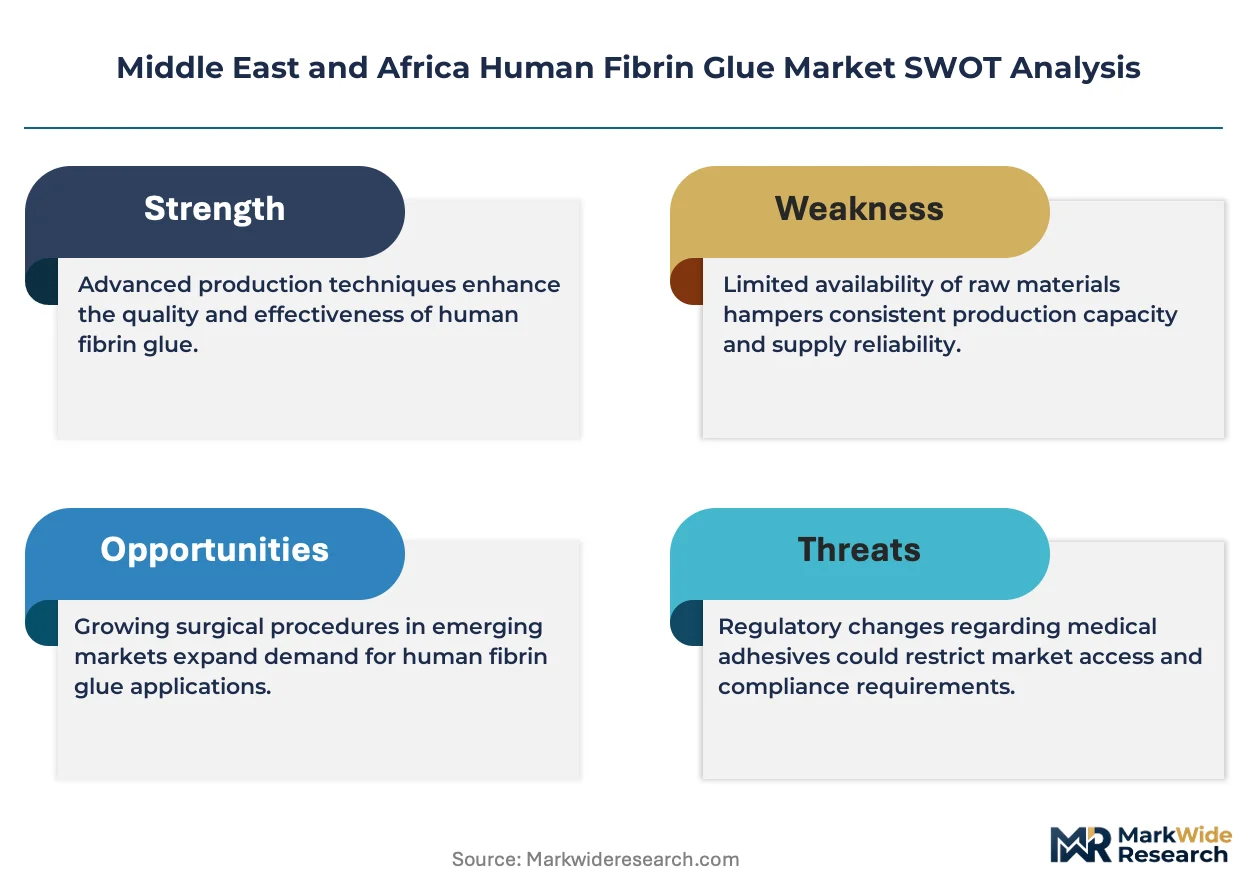
Hospital procurement consortiums across the Gulf Cooperation Council are reshaping how human fibrin glue reaches surgical suites. Baxter International Inc. leverages its plasma-derived biologics infrastructure to sustain supply continuity across Saudi Arabia and the UAE. Johnson & Johnson competes through its broad surgical portfolio, while Grifols S.A. anchors its position with specialized hemostasis manufacturing expertise in the region.
Human fibrin glue comprises a two-component biological adhesive combining fibrinogen and thrombin, typically derived from pooled human plasma, that polymerizes upon mixing to form a biodegradable clot mimicking final stages of natural coagulation. Liquid formulations dominate current hospital purchasing due to established compatibility with laparoscopic applicators, though spray delivery systems represent the fastest-growing configuration as minimally invasive surgical volumes expand across Middle Eastern tertiary centers. Orthopedic surgery applications command significant margin pools given the complexity of joint reconstruction procedures, while cardiovascular procedures remain a concentrated demand segment in South African and Egyptian academic medical centers.
Saudi Arabia's SFDA and South Africa's SAHPRA enforce divergent biologics stability and viral inactivation standards, compelling manufacturers to maintain separate dossier strategies for Gulf and sub-Saharan markets. The EU MDR equivalency requirements referenced by several Gulf national regulators further complicate market access timelines for non-CE-marked products. Stakeholders must monitor evolving local content mandates and government hospital tender reforms that increasingly favor regional distributors with cold-chain capabilities.
Market Dynamics
Hospital procurement consortiums across the Gulf Cooperation Council are consolidating purchasing power and forcing manufacturers to reconfigure distribution networks around cold-chain logistics capabilities rather than traditional wholesale relationships.
Growth Catalysts
- Cardiac procedure volume expansion:South African academic medical centers are scaling open-heart surgery programs, creating concentrated demand for hemostatic sealants in high-complexity cardiovascular interventions.
- SFDA biologics pathway maturation:Saudi Arabia's streamlined plasma-derived product registration is reducing time-to-market for compliant suppliers, accelerating product availability in Gulf surgical suites.
- Laparoscopic platform proliferation:Minimally invasive surgical suites across UAE tertiary hospitals are standardizing spray-applicator compatible fibrin glue configurations, driving format preference shifts.
Market Restraints
- Plasma supply concentration:Regional dependence on imported plasma raw material exposes manufacturers to US and EU collection center output volatility and cross-border shipping disruptions.
- EU MDR equivalency barriers:Gulf national regulators referencing CE marking requirements create dossier duplication burdens for non-European manufacturers seeking multi-country market access.
- Synthetic sealant substitution:Polyethylene glycol-based surgical adhesives are capturing select orthopedic applications where immunogenicity concerns drive clinician preference away from human-derived products.
Strategic Opportunities
- Egyptian public hospital modernization:Cairo and Alexandria teaching hospitals are upgrading surgical infrastructure with World Bank health sector financing, creating procurement windows for advanced hemostasis products.
- Medical tourism hub development:Dubai Health Authority and Saudi Vision 2030 healthcare investments are attracting complex reconstructive cases requiring specialized adhesive applications.
- Local content mandates:Saudi and UAE government tender reforms favoring regional distributors with in-country cold-chain capabilities create partnership opportunities for international manufacturers.
Industry Challenges
- Viral inactivation protocol divergence:SAHPRA and SFDA maintain non-harmonized pathogen reduction standards, forcing manufacturers to run separate validation studies for sub-Saharan and Gulf market access.
- Spray applicator technical integration:Laparoscopic delivery system compatibility testing with diverse surgical robot platforms consumes significant R&D resources and delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Human Fibrin Glue Market |
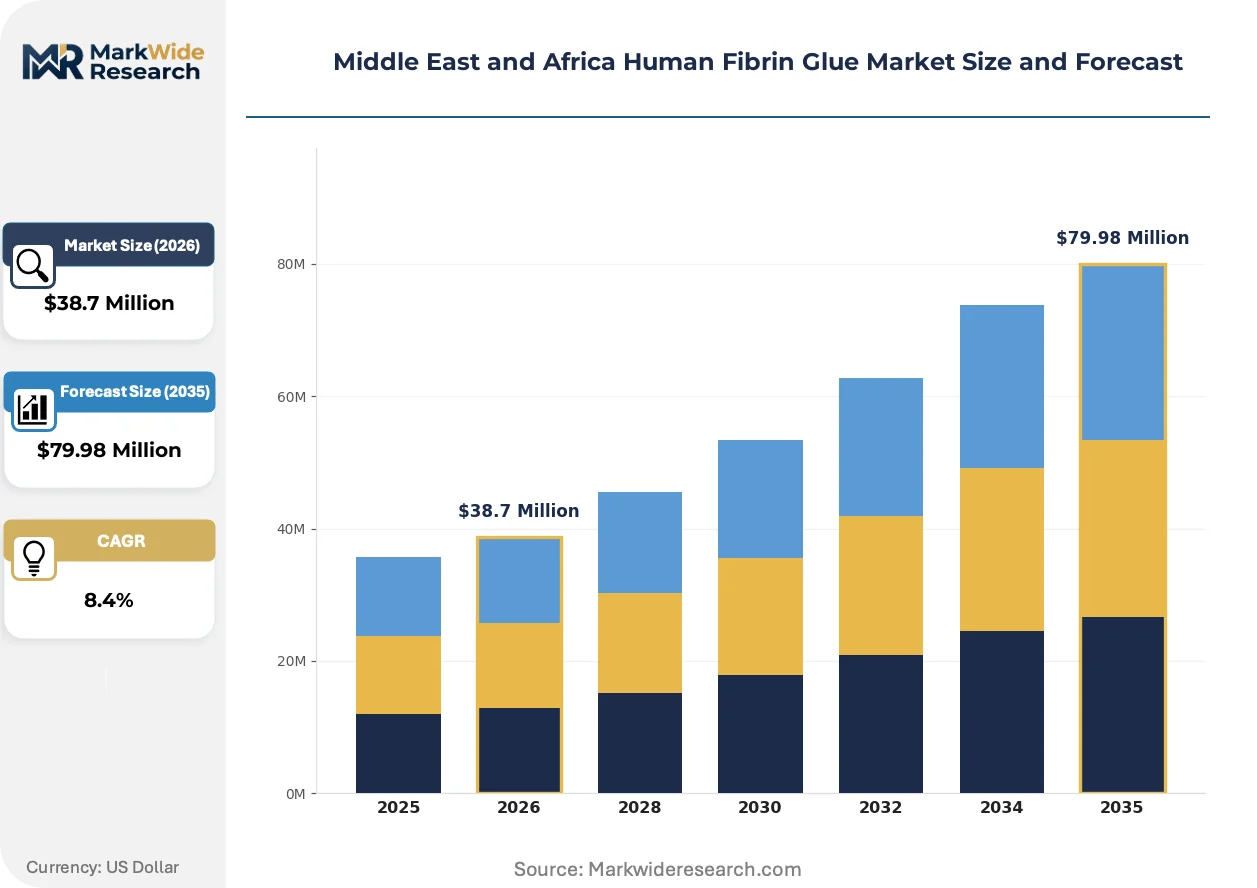
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $79.98 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Spray, Patch, Gel Application: Wound Closure, Soft Tissue Adhesion, Orthopedic Surgery, Cardiovascular Procedures End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | Baxter International Inc., Johnson & Johnson, Grifols S.A., CSL Behring, Takeda Pharmaceutical Company Ltd, Pfizer Inc., Octapharma AG, Saudi Pharmaceutical Industries, GC Pharma, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Human Fibrin Glue Market Shifts & Advancements
Spray delivery configurations are displacing traditional liquid applicators across Middle Eastern tertiary surgical centers, while regulatory fragmentation between Gulf and sub-Saharan markets forces parallel compliance investments.
Pre-filled dual-chamber syringe systems with integrated mixing mechanisms are rendering obsolete manual fibrinogen-thrombin preparation protocols in high-volume cardiac surgery units. Saudi Arabian and Emirati cardiac centers are adopting these closed-system formats to reduce operative time and contamination risk. The shift is compressing demand for conventional vial-based reconstitution products and favoring suppliers with integrated device-drug combination expertise.
SFDA's 2023 biologics stability testing guidelines now mandate extended real-time shelf-life validation for plasma-derived adhesives, extending registration timelines by twelve to eighteen months for new market entrants. Manufacturers are responding by establishing dedicated Gulf regulatory affairs functions and pre-submission consultation programs. The policy most heavily impacts spray-dried fibrinogen formulations where accelerated stability protocols previously shortened development cycles.
Consolidated purchasing through Gulf Cooperation Council hospital group procurement organizations is displacing individual hospital tender processes for high-value surgical supplies. Regional distributor networks with temperature-controlled warehousing and direct-to-suite logistics are capturing contract awards previously fragmented across multiple wholesalers. The transformation is most visible in UAE and Saudi Arabia where government hospital privatization programs centralize buying authority under new operating company structures.
Middle East and Africa Human Fibrin Glue Market Segmentation
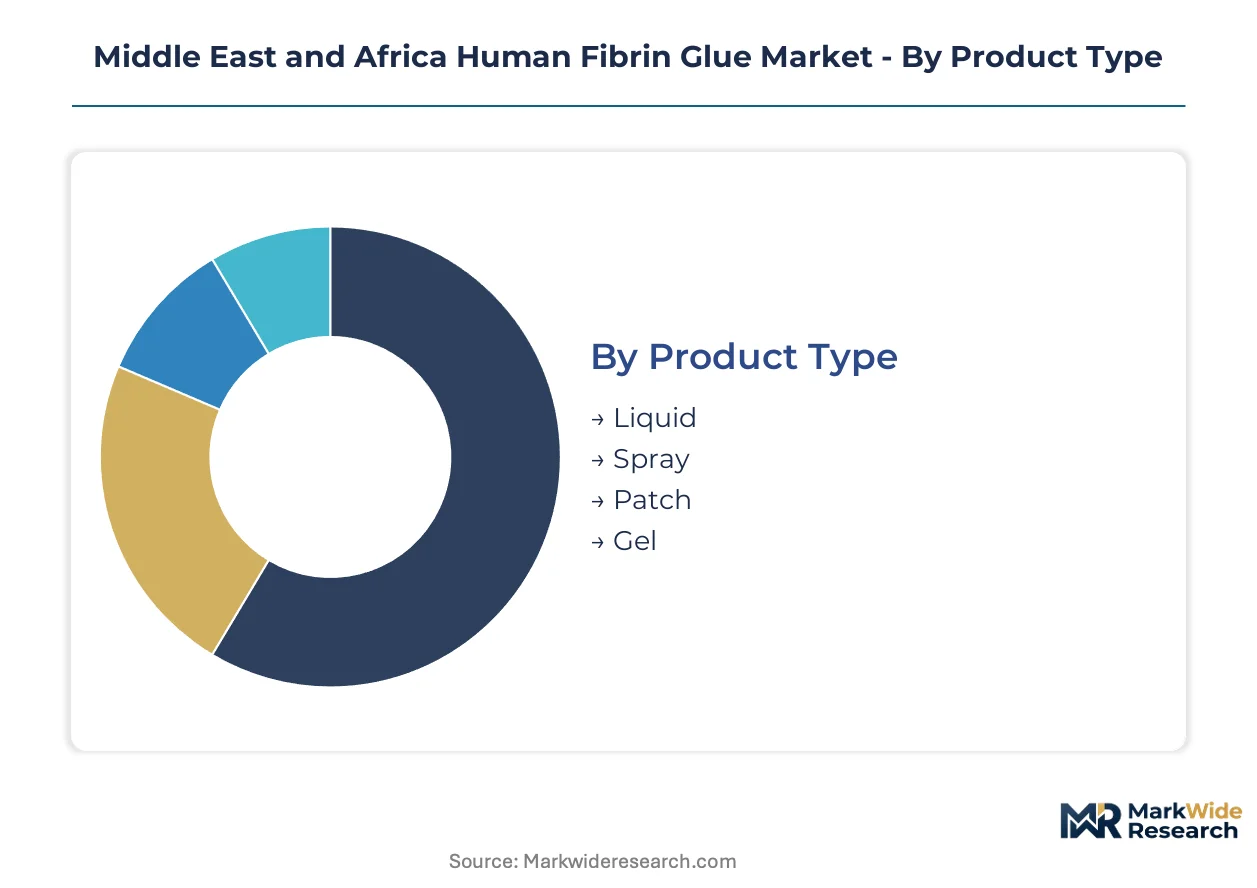
Human fibrin glue segmentation in the Middle East and Africa reflects divergent clinical workflows across Gulf tertiary centers and sub-Saharan surgical facilities. Configuration preferences vary sharply by procedure complexity, cold-chain infrastructure maturity, and procurement consolidation patterns.
Product Type:
Cost tier differentiation separates commodity liquid formats from premium spray and patch configurations requiring specialized applicator systems.
- Liquid:Standard two-component vial systems requiring manual fibrinogen-thrombin reconstitution dominate Egyptian and South African public hospital procurement due to lower unit economics and established nursing protocols. Demand concentrates in high-volume general surgery units where cost sensitivity outweighs preparation time constraints.
- Spray:Laparoscopic-compatible aerosolized delivery systems polymerize fibrinogen-thrombin mixtures through pressurized applicators, gaining preference in UAE and Saudi Arabian cardiac centers where operative time reduction justifies premium positioning. Dubai Health Authority tertiary facilities are standardizing spray configurations for minimally invasive valve repairs.
- Patch:Pre-formed fibrinogen-impregnated matrices activate upon contact with physiological fluids, serving trauma stabilization in South African academic medical centers with limited mixing capabilities.
- Gel:Viscous formulations suit ENT and neurosurgical applications requiring precise placement without flow migration, finding niche adoption in Israeli and Lebanese private hospitals.
Liquid commands the established base. The steepest expansion runs through Spray.
Application:
Procedure complexity and reimbursement tiering determine adhesive selection across cardiovascular, orthopedic, and soft tissue interventions.
- Wound Closure:Surface sealing applications in trauma and emergency settings utilize liquid fibrin glue for hemostasis in South African provincial hospitals and Nigerian teaching centers, with SAHPRA registration pathways favoring established plasma-derived formats over novel synthetic alternatives.
- Soft Tissue Adhesion:Hernia mesh fixation and plastic surgery applications in Dubai and Jeddah medical tourism hubs drive demand for spray configurations with controlled polymerization rates, where aesthetic outcomes influence clinician preference.
- Orthopedic Surgery:Joint reconstruction procedures in Cairo and Alexandria teaching hospitals generate concentrated consumption of high-concentration fibrinogen formulations for suture line reinforcement in arthroplasty.
- Cardiovascular Procedures:Open-heart surgery programs at Groote Schuur Hospital and King Faisal Specialist Hospital anchor regional demand for rapid-clotting sealants in aortic and coronary interventions.
Cardiovascular Procedures anchor premium pricing. Soft Tissue Adhesion gains share fastest.
End User:
Customer type stratification reflects capital intensity, case complexity, and cold-chain reliability requirements.
- Hospitals:Tertiary academic centers and government facilities across the Gulf Cooperation Council and South Africa consolidate procurement through group purchasing organizations, with Saudi Arabia's NUPCO and UAE's SEHA dominating volume allocation.
- Clinics:Outpatient surgical facilities in Morocco and Tunisia utilize lower-volume liquid configurations for minor procedures, constrained by refrigeration limitations and intermittent supply continuity.
- Ambulatory Surgical Centers:Day-case facilities in Dubai Healthcare City and Riyadh are adopting pre-filled dual-chamber systems to reduce pharmacy preparation burden and turnover time.
- Research Institutions:Cairo University and University of Cape Town medical schools drive investigational use of novel fibrinogen concentrations for tissue engineering applications.
Hospitals command the established base. Ambulatory Surgical Centers represent the fastest-growing trajectory.
Distribution Channel:
Supply concentration and regulatory custody requirements reshape route-to-market structures across the region.
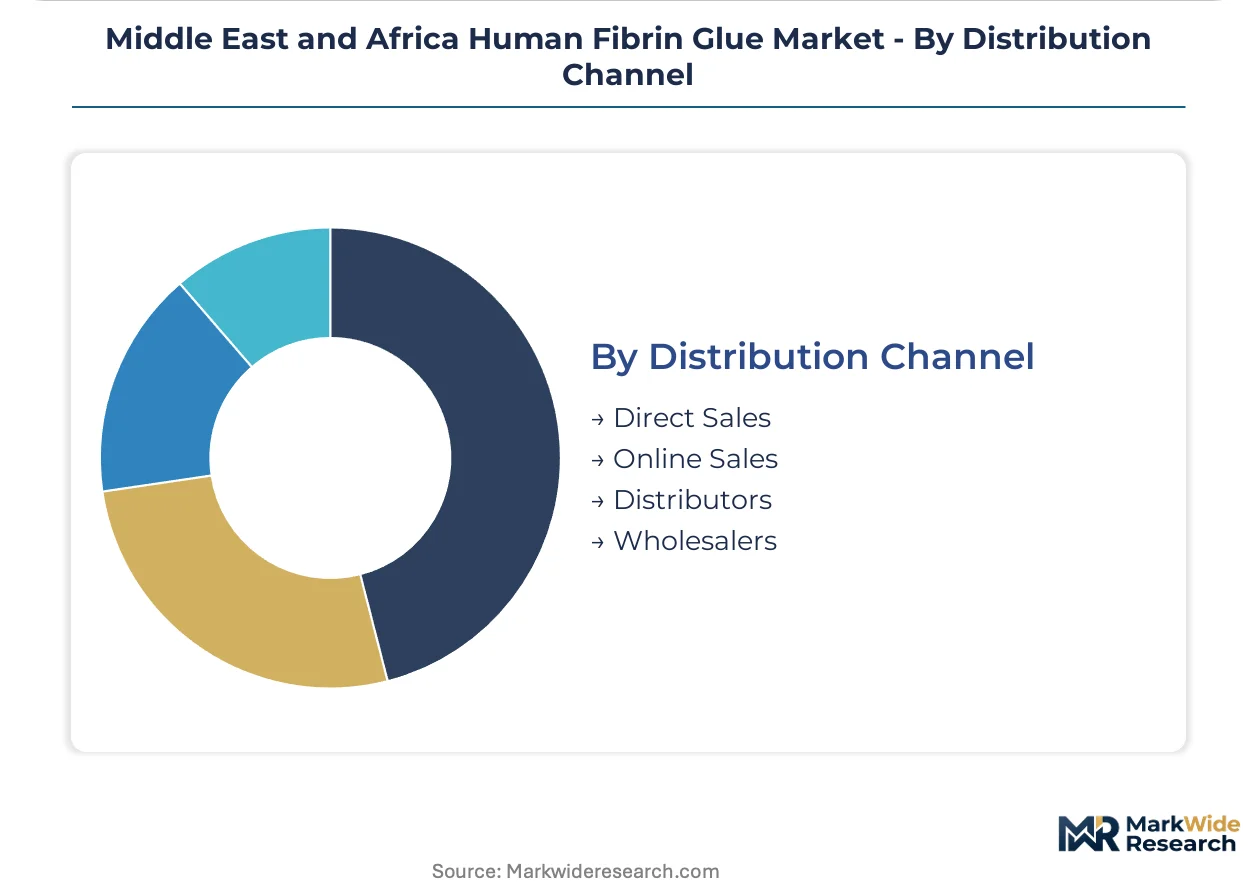
- Direct Sales:Manufacturer-to-hospital relationships dominate high-value cardiac surgery product flows in Saudi Arabia and the UAE, with Baxter and Grifols maintaining dedicated Gulf regulatory affairs and cold-chain field teams.
- Distributors:Regional wholesalers with temperature-controlled warehousing capture government tender awards in Egypt, Jordan, and Kenya, where fragmented hospital networks prevent direct sales economics.
- Online Sales:B2B procurement platforms are emerging for consumable replenishment in South African private hospital groups, though plasma-derived biologics remain excluded from pure e-commerce channels due to cold-chain custody requirements.
- Wholesalers:Traditional pharmaceutical wholesalers serve secondary cities and rural facilities in Nigeria and Ethiopia with limited specialist surgical volume.
Distributors command the established base. Direct Sales climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Gulf Cooperation Council tertiary centers while South African public hospitals operate under severe cost compression. This asymmetry shapes divergent product configurations and distribution strategies across the region.
Saudi Arabia
King Faisal Specialist Hospital and Saudi German Hospital anchor demand for spray-applicator fibrin glue in complex cardiac and reconstructive procedures. SFDA's 2023 biologics stability guidelines now mandate extended real-time shelf-life validation, extending registration timelines for new entrants. Riyadh and Jeddah medical clusters are consolidating procurement through NUPCO, favoring suppliers with dedicated Gulf regulatory affairs teams.
United Arab Emirates
Dubai Health Authority tertiary facilities are standardizing spray configurations for minimally invasive valve repairs and soft tissue adhesion procedures. MOHAP maintains reference to EU MDR equivalency requirements, creating dossier burdens for non-CE-marked products. Dubai Healthcare City and Abu Dhabi SEHA hospital networks are centralizing buying authority under new operating company structures.
South Africa
Groote Schuur Hospital and academic medical centers in Cape Town and Johannesburg are scaling open-heart surgery programs, creating concentrated demand for rapid-clotting sealants. SAHPRA enforces viral inactivation standards divergent from Gulf regulators, forcing separate validation studies. Provincial hospital networks remain cost-constrained, favoring liquid reconstitution formats over premium spray systems.
Egypt
Cairo and Alexandria teaching hospitals are upgrading surgical infrastructure with World Bank health sector financing, creating procurement windows for advanced hemostasis products. The country's national pharmaceutical regulator maintains registration pathways favoring established plasma-derived formats over novel synthetic alternatives. Cairo University medical school drives investigational use of novel fibrinogen concentrations for tissue engineering applications.
Israel
Private hospitals in Tel Aviv and Haifa utilize viscous gel formulations for ENT and neurosurgical applications requiring precise placement without flow migration. The national health regulator enforces stringent biologics import standards aligned with European pharmacopeia. Israeli medical centers serve as technology evaluation hubs for laparoscopic delivery system compatibility with diverse surgical robot platforms.
Middle East and Africa Human Fibrin Glue Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with concentrated plasma-derived manufacturing expertise. The vendor base organizes around three strategic archetypes: multinational plasma fractionators with Gulf regulatory infrastructure, diversified surgical portfolio holders, and regional distributors with cold-chain capabilities. Consolidation pressures are accelerating through hospital procurement consortiums and government tender reforms favoring in-country logistics partners.
Within the plasma fractionator tier, Baxter International Inc., Grifols S.A., and CSL Behring exemplify divergent approaches to Gulf market access. Baxter leverages its plasma-derived biologics infrastructure to sustain supply continuity across Saudi Arabia and the UAE. Grifols anchors its position with specialized hemostasis manufacturing expertise and dedicated regional regulatory functions. CSL Behring occupies a position emphasizing viral safety validation protocols aligned with SFDA and SAHPRA requirements.
| Leading Market Players |
|---|
| Baxter International Inc. |
| Johnson & Johnson |
| Grifols S.A. |
| CSL Behring |
| Takeda Pharmaceutical Company Ltd |
| Pfizer Inc. |
| Octapharma AG |
| Saudi Pharmaceutical Industries |
| GC Pharma |
| Others |
Supply & Pricing Matrix
Undercapacity in Gulf cold-chain plasma fractionation is forcing manufacturers to absorb premium logistics costs while maintaining dual-dossier compliance investments for SFDA and SAHPRA divergence. This utilization squeeze compresses margins on standard liquid formats while amplifying pricing power for spray-applicator configurations in Saudi and Emirati cardiac centers.
Pricing Analysis
Customization-premium spreads separate standard liquid vial systems from configured-to-order spray delivery platforms with integrated laparoscopic compatibility. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and cold-chain custody requirements. Cost compression in Egyptian and South African public hospital tiers is intensifying because procurement consortiums are consolidating volume and squeezing supplier margins. Government facilities in sub-Saharan Africa exhibit highest price sensitivity; Dubai Health Authority tertiary centers show lowest sensitivity due to medical tourism revenue offsets.
Supply Chain Analysis
Tariff exposure between US plasma collection centers and Gulf manufacturing hubs dominates supply chain risk calculus for regional fibrin glue distributors. Manufacturing concentrates in the United States, Spain, and Switzerland; raw material sourcing draws from US and EU plasma collection networks with limited African or Middle Eastern collection infrastructure. Single-source vulnerability in thrombin enzyme supply creates formulation bottlenecks during cross-border shipping disruptions. Distribution runs through regional cold-chain specialists with direct-to-suite logistics capabilities rather than traditional pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa human fibrin glue market sits in early-cycle expansion, with spray-applicator adoption in Gulf cardiac centers and Egyptian hospital modernization serving as penetration tailwinds.
For Market Incumbents: Build regulatory moat through dedicated SFDA and SAHPRA affairs functions with pre-submission consultation programs. Synthetic sealant substitution in orthopedic applications threatens plasma-derived volume; defend by deepening backward integration into plasma collection partnerships and accelerating spray-dried fibrinogen stability validation.
For New Entrants and Emerging Players: Pursue Egyptian public hospital procurement windows created by World Bank health sector financing, where established plasma-derived formats face limited synthetic competition. Ambulatory surgical centers in Riyadh and Dubai Healthcare City represent the most penetrable segment. Go-to-market angle: partner with regional cold-chain distributors possessing NUPCO and SEHA contract relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across spray-applicator device-drug combination development. Long-term viability favors platform integrators with integrated regulatory and logistics infrastructure over component specialists. Acquisition target archetype: regional distributors with government tender relationships and temperature-controlled warehousing. Signal to watch: SFDA biologics pathway maturation accelerating registration timelines for compliant suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Pre-Submission Consultation Program | Reduces registration timelines by twelve to eighteen months for plasma-derived adhesives. |
| Spray-Applicator Laparoscopic Compatibility Testing | Enables standardization across UAE tertiary hospital minimally invasive surgical suites. |
| Regional Cold-Chain Distribution Partnership | Captures NUPCO and SEHA consolidated procurement awards in Saudi Arabia and UAE. |
| Egyptian Public Hospital Modernization Alignment | Positions suppliers for World Bank-financed Cairo and Alexandria teaching hospital upgrades. |
| Dual-Chamber Pre-Filled System Development | Reduces operative time and contamination risk in high-volume cardiac surgery units. |
Research Methodology
A spread of perspectives from hospital procurement managers, biomedical engineers, regulatory affairs specialists, and plasma fractionation executives converged on the working assumptions. Primary interviews combined with secondary validation from SFDA biologics guidelines, SAHPRA viral inactivation standards, hospital procurement databases, and GPO contract repositories. Bottom-up demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Demand-supply-balance framing anchored the analytical approach, with segmentation across product type, application, end user, and distribution channel dimensions modeled throughout the forecast period. CAGRs derived from procedure volume trajectories, regulatory pathway maturation rates, and procurement consolidation patterns. Industry-specific inputs included cardiac surgery program expansion data from Groote Schuur Hospital and King Faisal Specialist Hospital, plus spray-applicator adoption curves from Dubai Health Authority facilities.
Macroeconomic conditions sit as an overlay; deviation in Gulf medical tourism flows, World Bank health financing commitments, or plasma collection center output would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization progress and cold-chain infrastructure investment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Global Cyanoacrylate Adhesives Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
Bio-Based Adhesives Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Global Medical Adhesives Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Russia Sealants Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
India Adhesives Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market