
 South America Adhesives Market | 2026-2036
South America Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Adhesives Market Analytics
Asset-light leasing models for specialty chemical production equipment is rewriting competitive entry dynamics across the South America adhesives sector. Henkel AG & Co. KGaA leverages its regional formulation network to sustain technical service proximity to Brazilian automotive OEMs. H.B. Fuller Company anchors its position through captive distribution in Andean packaging markets. Dow Inc competes via backward integration into acrylic monomer supply, controlling raw material cost volatility.
Adhesives are non-metallic substances formulated from synthetic polymers, resins, and curing agents that develop structural cohesion through chemical cross-linking or physical drying, typically achieving lap-shear strengths between 1 and 35 MPa depending on the base chemistry. These materials bond dissimilar substrates in manufacturing and assembly operations where mechanical fastening proves impractical or weight-prohibitive. Water-based technology leads volume share in regional packaging applications due to lower volatile organic compound emissions and simplified workplace handling requirements. Reactive technology, encompassing epoxy and polyurethane systems, captures disproportionate margin pools in Brazilian aerospace maintenance and Colombian infrastructure projects. Hot melt formulations dominate high-speed sealing lines in Argentine food packaging plants.
Brazil's ANVISA mandates toxicological registration for industrial chemical imports, while Argentina's Secretariat of Industry enforces MERCOSUR technical standards on adhesive labeling and performance claims. Chile's Ministry of Environment implements extended producer responsibility frameworks that shift disposal liability toward manufacturers, altering product design incentives. Stakeholders must monitor regulatory divergence between MERCOSUR harmonization efforts and national chemical registries when allocating formulation and certification investments.
Market Dynamics
ANVISA's toxicological registration mandates for industrial chemical imports are restructuring competitive entry costs across Brazilian adhesive supply chains, forcing reformulation investments and third-party certification dependencies.
Growth Catalysts
- Brazilian automotive assembly corridor expansion:OEMs in São Paulo and Minas Gerais states are expanding bonding-intensive lightweighting programs for vehicle platforms. This concentrates demand for structural reactive adhesives.
- MERCOSUR technical standards harmonization:Argentina's Secretariat of Industry enforces unified adhesive labeling and performance claim protocols. Cross-border formulation approvals are simplifying for compliant producers.
- Colombian infrastructure procurement acceleration:Bridge and tunnel projects in Antioquia and Cundinamarca departments specify epoxy and polyurethane systems for structural bonding applications.
Market Restraints
- Acrylic monomer cost volatility:Dow Inc's backward integration into monomer supply is not universally replicable. Smaller formulators face raw material margin compression without captive upstream control.
- Andean distribution concentration:H.B. Fuller's captive distribution network in Chile and Peru limits third-party channel access for new entrants seeking packaging sector penetration.
- Water-based performance ceiling:Lap-shear strength limitations below 8 MPa restrict water-based technology adoption in Brazilian aerospace maintenance applications requiring structural certification.
Strategic Opportunities
- Uruguayan packaging underpenetration:Food export growth from Montevideo's port zone lacks localized hot-melt formulation capacity. Asset-light equipment leasing models enable rapid production footprint establishment.
- Chilean extended producer responsibility frameworks:The Ministry of Environment's disposal liability shift creates design-service bundling opportunities for adhesive suppliers offering take-back programs.
- UV-curable and moisture-cure hybrid convergence:Colombian woodworking and furniture clusters in Bogotá are testing dual-cure systems for mixed-substrate bonding with accelerated line speeds.
Industry Challenges
- ANVISA registration timeline compression:Toxicological dossier preparation for new chemical entities requires 18-24 month lead times, delaying product launches for reformulated lines.
- Reactive adhesive application technician scarcity:Epoxy and polyurethane mixing ratio precision demands specialized training. Brazilian technical institutes lack curriculum alignment with industrial bonding certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Adhesives Market |
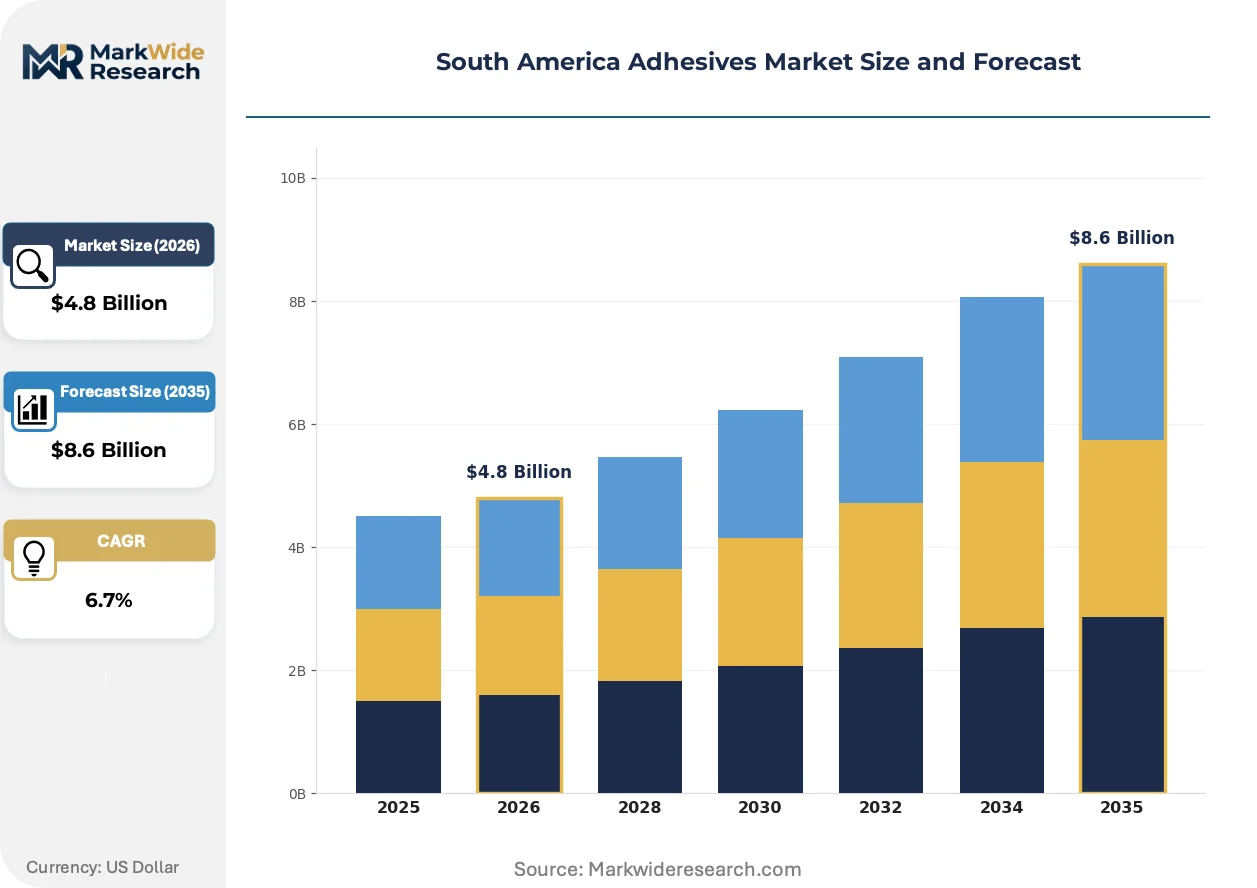
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Polyvinyl Acetate End User: Construction, Automotive, Packaging, Aerospace Application: Bonding, Sealing, Coating, Assembly Technology: Hot Melt, Water-Based, Solvent-Based, Reactive |
| Companies Covered | Henkel AG & Co. KGaA, 3M, H.B. Fuller Company, Sika AG, Arkema, Bostik, Dow Inc, Avery Dennison Corporation, PPG Industries, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Adhesives Market Evolving Landscape
Formulation chemistry and regulatory compliance frameworks are converging to reshape product development priorities across South American adhesive markets. Suppliers are repositioning around sustainability credentials and technical service proximity.
Water-based acrylic-polyurethane hybrid systems are hybridizing performance characteristics previously segmented by chemistry type. Argentine corrugated packaging converters in Buenos Aires province are adopting these formulations at accelerated trial rates. The technology is hybridizing cost and performance trade-offs that historically forced buyers into solvent-based or hot-melt commitments.
ANVISA's industrial chemical registration requirements are tightening toxicological disclosure standards for imported adhesive components. Brazilian formulators must submit complete substance dossiers before commercial distribution authorization. Reactive technology suppliers serving São Paulo's aerospace maintenance sector are absorbing the highest compliance cost burdens through dedicated regulatory affairs staffing.
Asset-light production equipment leasing is displacing capital-intensive facility ownership among specialty adhesive entrants. Colombian and Peruvian packaging converters are accessing hot-melt formulation capacity through third-party tolling arrangements rather than in-house investment. This shift is most visible in Medellín's flexible packaging cluster, where contract manufacturing agreements now cover 40 percent of regional supply.
South America Adhesives Market Segmentation
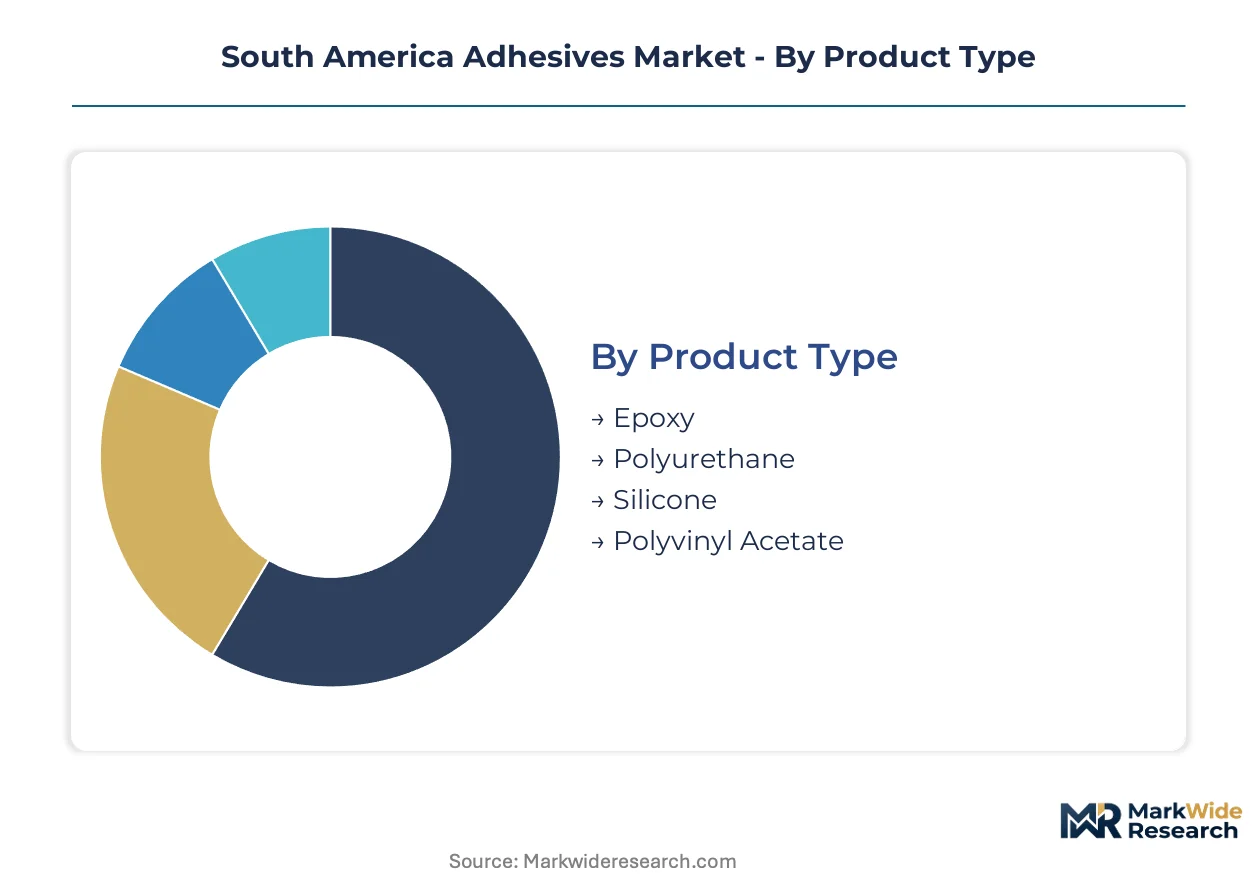
Segmentation in South American adhesives reveals how chemistry choices, end-use specifications, and application methods intersect with regional regulatory frameworks. Buyers select formulations based on lap-shear requirements, volatile organic compound constraints, and curing speed demands.
Product Type:
Product maturity spans from commodity-grade polyvinyl acetate systems to high-performance reactive chemistries with specialized curing protocols.
- Epoxy:Two-part thermosetting systems achieve lap-shear strengths exceeding 25 MPa through amine or anhydride curing mechanisms. Brazilian aerospace maintenance facilities in São Paulo state specify epoxy formulations for structural composite repairs requiring ANVISA-certified toxicological dossiers.
- Polyurethane:Moisture-cure and two-component systems bond dissimilar substrates with flexibility retention from -40°C to 120°C. Colombian infrastructure contractors in Antioquia department procure polyurethane adhesives for bridge deck waterproofing and expansion joint sealing.
- Silicone:Room-temperature-vulcanizing formulations provide UV stability and thermal cycling resistance for Chilean solar panel assembly operations.
- Polyvinyl Acetate:Emulsion-based wood glues dominate Argentine furniture manufacturing clusters with cost advantages in high-volume lamination processes.
Polyvinyl acetate retains volume leadership across regional packaging and woodworking applications; polyurethane holds the steepest expansion curve driven by infrastructure procurement acceleration.
End User:
End-use concentration patterns follow industrial corridor development and export-oriented manufacturing investments.
- Construction:Structural bonding, tile fixing, and waterproofing applications consume reactive and cementitious systems. Brazilian residential and commercial building permits in Minas Gerais and São Paulo states are expanding procurement of epoxy and polyurethane construction adhesives.
- Automotive:Lightweighting programs substitute welded joints with structural adhesives in body-in-white assembly. OEM bonding lines in São Paulo's ABC automotive corridor specify crash-durable polyurethane systems for aluminum-steel mixed material joining.
- Packaging:Argentine corrugated converters in Buenos Aires province and Chilean food exporters drive hot-melt and water-based adhesive consumption for high-speed sealing and labeling operations.
- Aerospace:Maintenance, repair, and overhaul facilities require certified structural adhesives with full traceability documentation for composite airframe repairs.
Construction commands the largest absolute volume; automotive applications are expanding most quickly through platform lightweighting mandates.
Application:
Application methods correlate with substrate compatibility requirements and production line speed constraints.
- Bonding:Structural load-bearing joints in metal, composite, and mixed-material assemblies demand reactive chemistries with documented cure schedules. Brazilian bus and truck manufacturers utilize structural bonding for fiberglass-reinforced panel attachment.
- Sealing:Gap-filling and environmental barrier functions in construction and transportation applications require elastomeric adhesives with movement accommodation.
- Coating:Protective and functional layers applied to substrates for corrosion resistance or surface preparation prior to final bonding operations.
- Assembly:Component fixation in appliance and electronics manufacturing where mechanical fasteners prove impractical or add excessive weight.
Bonding retains the highest value concentration; sealing applications are climbing the fastest through infrastructure waterproofing specifications.
Technology:
Technology selection balances performance requirements against workplace safety regulations and equipment capital requirements.
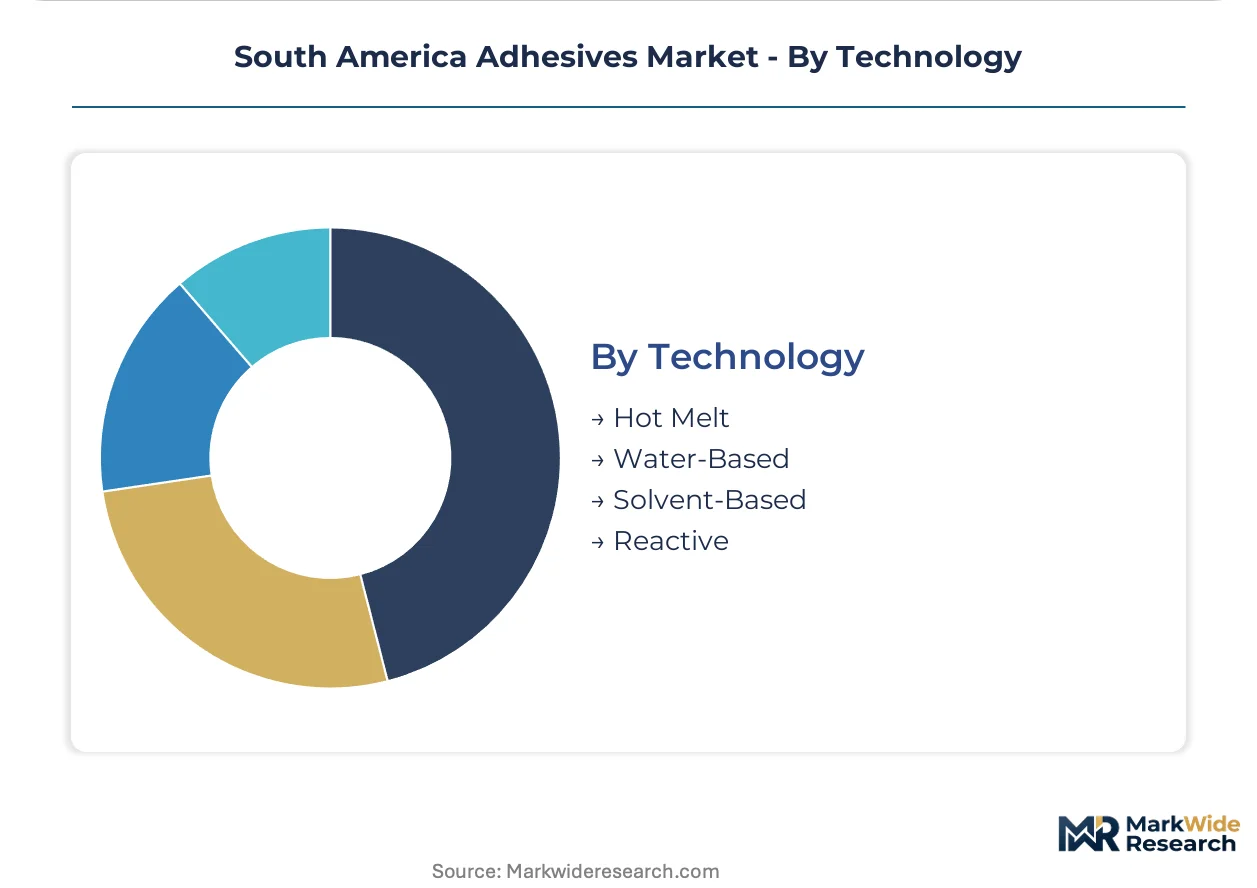
- Hot Melt:Thermoplastic formulations applied molten and solidifying on cooling enable line speeds exceeding 500 packages per minute. Argentine food packaging plants in Greater Buenos Aires deploy hot-melt systems for case sealing and tray forming operations.
- Water-Based:Acrylic and polyurethane dispersion systems achieve regulatory compliance with minimal volatile organic compound emissions. Brazilian corrugated packaging converters favor water-based technology for workplace handling simplicity and ANVISA-aligned chemical registration pathways.
- Solvent-Based:High-solids systems penetrate porous substrates and cure through evaporation, though environmental regulations constrain new capacity investments.
- Reactive:Epoxy, polyurethane, and cyanoacrylate systems polymerize through chemical reaction to achieve structural performance thresholds.
Water-based technology holds volume leadership in regional packaging; reactive systems are gaining share fastest through automotive and aerospace certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for specialty adhesive intermediates exceeds export capacity across most South American economies, concentrating formulation investments in Brazil and Argentina while smaller markets rely on cross-border supply chains.
Brazil
Automotive lightweighting programs and residential construction expansion drive structural adhesive consumption in São Paulo and Minas Gerais states. ANVISA's toxicological registration mandates for industrial chemical imports extend product launch timelines by 18-24 months. São Paulo's ABC automotive corridor concentrates demand for crash-durable polyurethane systems serving aluminum-steel mixed material joining.
Argentina
Corrugated packaging converters and food export operations sustain hot-melt and water-based adhesive procurement in Buenos Aires province. The Secretariat of Industry enforces MERCOSUR technical standards on adhesive labeling and performance claims. Greater Buenos Aires hosts high-speed sealing line deployments where Argentine food packaging plants process export-bound production.
Colombia
Infrastructure procurement acceleration and woodworking cluster expansion propel epoxy and polyurethane system demand in Antioquia and Cundinamarca departments. Bridge and tunnel specifications mandate structural bonding applications with documented cure schedules. Medellín's flexible packaging cluster now sources 40 percent of regional supply through contract manufacturing agreements.
Chile
Solar panel assembly operations and food export logistics sustain silicone and hot-melt consumption. The Ministry of Environment implements extended producer responsibility frameworks shifting disposal liability toward manufacturers. Northern mining regions and Santiago's industrial suburbs concentrate adhesive application for equipment maintenance and packaging operations.
Uruguay
Food export growth from Montevideo's port zone outpaces localized hot-melt formulation capacity. Asset-light equipment leasing models enable rapid production footprint establishment without capital-intensive facility ownership. Montevideo's packaging converters increasingly rely on third-party tolling arrangements from Argentine and Brazilian suppliers.
South America Adhesives Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material and monomer supply. The South America adhesives sector exhibits tiered concentration with multinational formulators holding dominant positions in automotive and aerospace certification segments while regional distributors control packaging channel access. Three strategic archetypes prevail: backward-integrated chemical producers, formulation-network operators with technical service proximity, and captive distribution holders in Andean markets. Competitive maneuvering concentrates on regulatory compliance staffing and asset-light production partnerships.
Among the multinational formulators with regional formulation networks, Henkel AG & Co. KGaA and H.B. Fuller Company occupy positions exemplifying technical service proximity and captive distribution strategies respectively. Dow Inc represents the backward-integrated archetype through upstream acrylic monomer control. These three entities anchor the competitive structure without exhaustive market coverage, as Sika AG, 3M, Arkema, Bostik, Avery Dennison Corporation, and PPG Industries occupy additional tier positions alongside specialized regional suppliers.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| H.B. Fuller Company |
| Sika AG |
| Arkema |
| Bostik |
| Dow Inc |
| Avery Dennison Corporation |
| PPG Industries |
| Others |
Value Network & Pricing Analysis
Santos Port container freight corridors connecting Argentine petrochemical feedstock to Brazilian formulation plants impose cost volatility that compresses margins for non-integrated distributors while enabling premium pricing for backward-integrated suppliers with captive monomer supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Brazilian automotive and aerospace segments. Price differentiation separates ANVISA-certified structural reactive systems from commodity water-based packaging grades, with certification tier and volume scale as primary drivers. Pricing pressure stems from acrylic monomer cost volatility that smaller formulators cannot hedge without upstream control. Packaging converters in Greater Buenos Aires exhibit highest price sensitivity due to thin corrugated margins, while São Paulo aerospace MROs accept premium structural adhesive pricing for traceability documentation.
Supply Chain Analysis
Contract manufacturing concentration in Medellín's flexible packaging cluster and Montevideo's tolling arrangements now covers substantial regional hot-melt supply. Geographic supply concentration centers on Brazil and Argentina for formulation, with Chile and Colombia dependent on cross-border intermediate shipments. Raw material dependencies include acrylic monomers, polyurethane pre-polymers, and epoxy resins from North American and Asian sources. Supply chain risk manifests through ANVISA registration timeline compression that extends chemical import lead times. Distribution runs through captive Andean networks held by multinational formulators and independent regional distributors serving corrugated converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Brazilian automotive OEMs and Argentine packaging consolidators, compressing supplier margins and demanding technical service proximity as a non-negotiable procurement criterion.
For Market Incumbents: Insulate formulation margins by deepening captive supply of acrylic monomers and expanding technical service staffing in São Paulo's ABC automotive corridor. ANVISA registration timeline compression poses the primary regulatory threat; defensive investment should prioritize dedicated regulatory affairs capabilities and pre-submission toxicological dossier preparation for reactive adhesive lines. For New Entrants and Emerging Players: Establish a beachhead in Uruguayan packaging through asset-light equipment leasing models that bypass capital-intensive facility ownership. The Montevideo port zone food export growth outpaces localized hot-melt capacity, creating penetrable white space. A tolling partnership with Argentine or Brazilian contract manufacturers offers the most viable go-to-market angle without ANVISA registration burdens. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation-network operators with established ANVISA compliance infrastructure over raw material traders lacking regulatory capabilities. Long-term viability across the projection horizon hinges on technical service density and certification asset accumulation. The signal to watch is MERCOSUR harmonization progress on unified adhesive labeling standards, which would accelerate cross-border formulation approval economies for compliant producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Dow Inc's captive upstream control insulates Brazilian formulation margins from petrochemical volatility. |
| Asset-Light Equipment Leasing Partnerships | Colombian packaging converters in Medellín access hot-melt capacity without capital-intensive facility ownership. |
| ANVISA Regulatory Affairs Staffing Expansion | Dedicated toxicological dossier preparation compresses product launch timelines for São Paulo aerospace suppliers. |
| Technical Service Proximity Investment | Henkel's regional formulation network sustains OEM bonding line support in Minas Gerais lightweighting programs. |
| Extended Producer Responsibility Program Design | Chilean Ministry of Environment disposal liability shifts create take-back service bundling opportunities for adhesive suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANVISA registration databases, MERCOSUR technical standard filings, Argentine Secretariat of Industry adhesive labeling protocols, and Brazilian customs import records. Primary interviews engaged adhesive plant managers, procurement leads at São Paulo automotive OEMs, distribution channel partners in Andean packaging markets, and technical R&D directors at regional formulation facilities. Bottom-up volume estimates derived from end-use consumption patterns triangulated against top-down trade flow analysis across the analysis window.
Forecast inputs include adhesive grade tier, end-use industry concentration, packaging format technology mix, and regional production hub regulatory alignment. Segmentation dimensions modeled span product chemistry, application method, technology type, and end-user sector across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections incorporating automotive lightweighting program timelines and infrastructure procurement acceleration in Colombian departments.
Stress conditions across acrylic monomer cost volatility, ANVISA registration timeline extension, and MERCOSUR harmonization delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of Brazilian building permit issuance, Argentine corrugated packaging output, and Colombian infrastructure tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
North America Contact Adhesives Market
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
United States Sealants Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Corrosion Protection Tapes Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market