
 North America Pressure Sensitive Adhesives (PSA) Market | 2026-2036
North America Pressure Sensitive Adhesives (PSA) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pressure Sensitive Adhesives (PSA) Market Analytics
Asset-light leasing models for coating equipment and toll manufacturing arrangements is rewriting competitive entry dynamics in North America. H.B. Fuller Company leverages its regional distribution network to sustain service density across automotive corridors. Avery Dennison Corporation anchors label-grade supply through backward integration into film substrates. Dow competes on hot melt technology leadership with proprietary metallocene catalyst platforms.
Pressure sensitive adhesives are viscoelastic materials that bond to surfaces upon light pressure without solvent activation or heat curing, typically formulated from acrylics, rubbers, or silicones with glass transition temperatures between minus 60 and 20 degrees Celsius to achieve tack, peel adhesion, and shear resistance simultaneously. Their primary commercial purpose is to enable reversible or permanent joining in high-speed converting operations where mechanical fasteners or thermal processes prove impractical. Water-based acrylics dominate volume in labeling applications where food-contact compliance and low odor properties command premium positioning, while hot melt systems capture the fastest expansion in e-commerce packaging tapes driven by line-speed requirements and immediate bond formation. Solvent-based grades retain niche dominance in medical applications where sterilization resistance and skin-biocompatibility standards create defensible margin pools despite regulatory pressure.
The EPA enforces VOC content limits under 40 CFR Part 59 that directly constrain solvent-based formulation choices across US manufacturing facilities. OSHA workplace exposure standards for isocyanates and other reactive components shape handling protocols and capital allocation decisions in PSA production plants. Health Canada's PMRA evaluates adhesive components in food-contact labeling applications, creating dual-jurisdiction compliance burdens for cross-border suppliers. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California and New York that threaten to impose end-of-life collection costs on tape and label substrates.
Market Dynamics
EPA enforcement of 40 CFR Part 59 VOC limits is forcing solvent-based PSA converters toward water-based and hot melt alternatives, compressing formulation flexibility while opening capital allocation toward compliant coating infrastructure.
Growth Catalysts
- E-commerce packaging acceleration:Fulfillment centers in Georgia and Tennessee require high-speed tape application systems that bond instantly without thermal curing, pulling hot melt PSA volumes.
- Automotive lightweighting mandates:Michigan and Ohio manufacturers substitute mechanical fasteners with structural PSA tapes to reduce vehicle mass and assembly complexity.
- Clean Air Act compliance deadlines:EPA emission thresholds push converters toward water-based acrylics, expanding addressable market for compliant formulation suppliers.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and rubber block copolymer prices fluctuate with crude oil indices, compressing margin predictability for formulation houses.
- Midwest coating capacity concentration:Toll manufacturing and asset-light leasing models cluster around Chicago and Detroit, creating geographic supply risk during regional logistics disruptions.
- Solvent-based medical grade lock-in:Sterilization resistance requirements for skin-contact applications prevent full migration away from VOC-emitting formulations despite regulatory pressure.
Strategic Opportunities
- Mexico nearshoring expansion:Automotive and electronics assembly growth in Querétaro and Baja California creates demand for localized PSA supply chains with NAFTA-compliant origin documentation.
- Extended producer responsibility frameworks:California and New York state-level end-of-life collection mandates for label substrates create service-revenue potential for integrated take-back programs.
- RFID-enabled smart label convergence:Avery Dennison and converter partnerships embed pressure-sensitive antennas for inventory tracking, opening premium positioning in pharmaceutical cold chain.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in viscoelastic design and glass transition temperature optimization concentrates among retiring practitioners, constraining R&D velocity.
- Multi-jurisdiction compliance synchronization:Health Canada PMRA food-contact evaluations run parallel to FDA assessments, doubling timeline uncertainty for cross-border label launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pressure Sensitive Adhesives (PSA) Market |
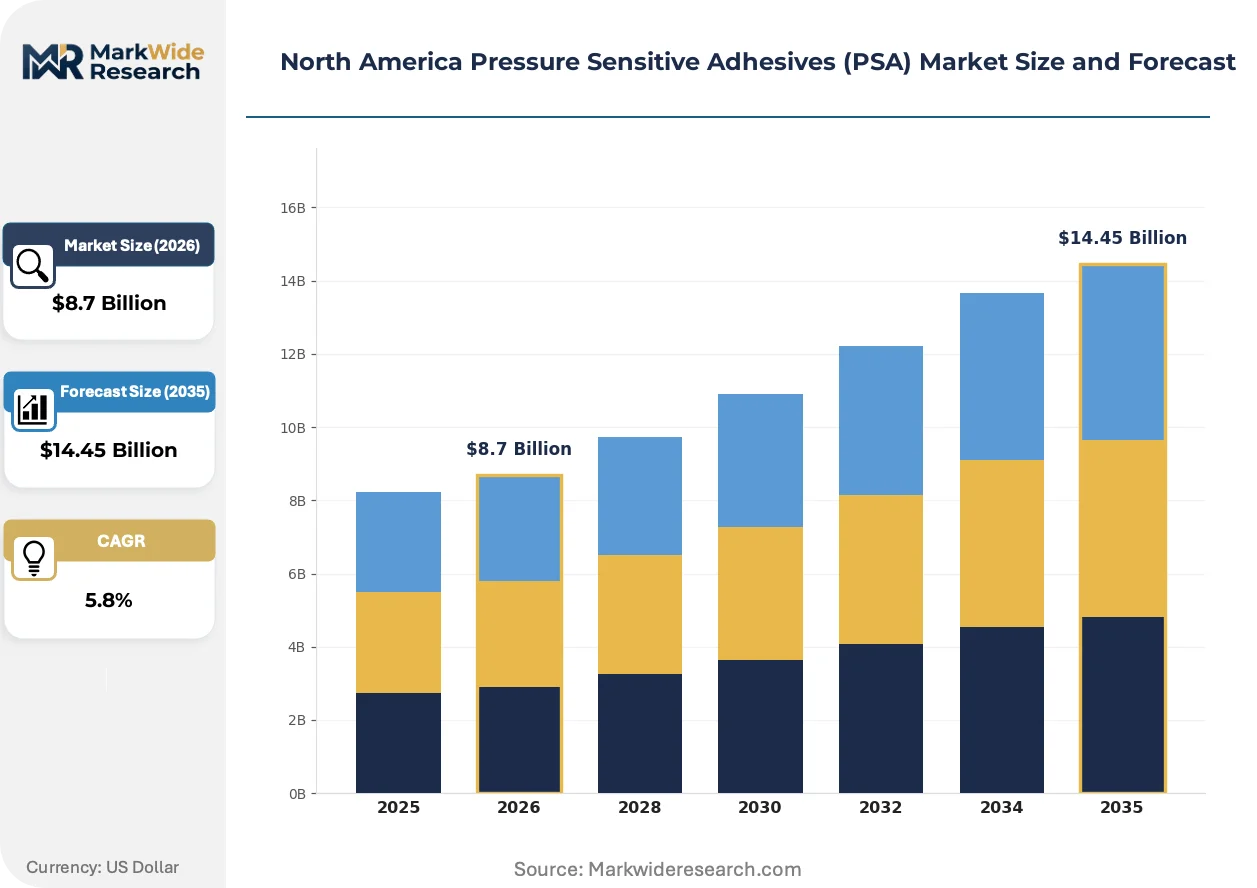
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Reactive End User: Packaging, Automotive, Electronics, Construction Application: Labeling, Tapes, Graphics, Medical Technology: Digital Printing, Thermal Transfer, Flexographic, Offset |
| Companies Covered | 3M, Arkema Group, H.B. Fuller Company, Dow, Henkel AG & Co. KGaA, Avery Dennison Corporation, Ashland, Sika AG, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pressure Sensitive Adhesives (PSA) Market Evolving Landscape
Digitalization of coating operations and regulatory chemistry disclosure requirements are compressing traditional development cycles while enabling precision customization at production scale.
UV-curable PSA technology is virtualizing thermal drying infrastructure in narrow-web label converting. Mid-tier packaging printers in North Carolina and Wisconsin adopt hybrid UV/LED curing lines to eliminate solvent recovery systems and reduce energy intensity. This shift is virtualizing the capital barrier between specialty and commodity converters, enabling smaller players to compete on short-run customization.
EPA's expanded enforcement of 40 CFR Part 59 Subpart F is mandating mass-balance documentation for solvent content across coating operations. Formulators must now maintain chain-of-custody records from resin receipt to finished adhesive, increasing administrative burden but creating audit-ready suppliers with preferred-vendor status. Medical tape manufacturers face the steepest compliance gradient given sterilization-grade solvent retention requirements.
Brand owners now specify adhesive performance through sustainability scorecards rather than technical datasheets alone. Procurement teams at CPG headquarters in Cincinnati and Minneapolis weight carbon footprint and recyclability compatibility alongside peel adhesion metrics. This behavioral pivot rewards converters with third-party certified bio-based content, particularly in food labeling segments where end-consumer messaging value exceeds formulation cost premiums.
North America Pressure Sensitive Adhesives (PSA) Market Segmentation
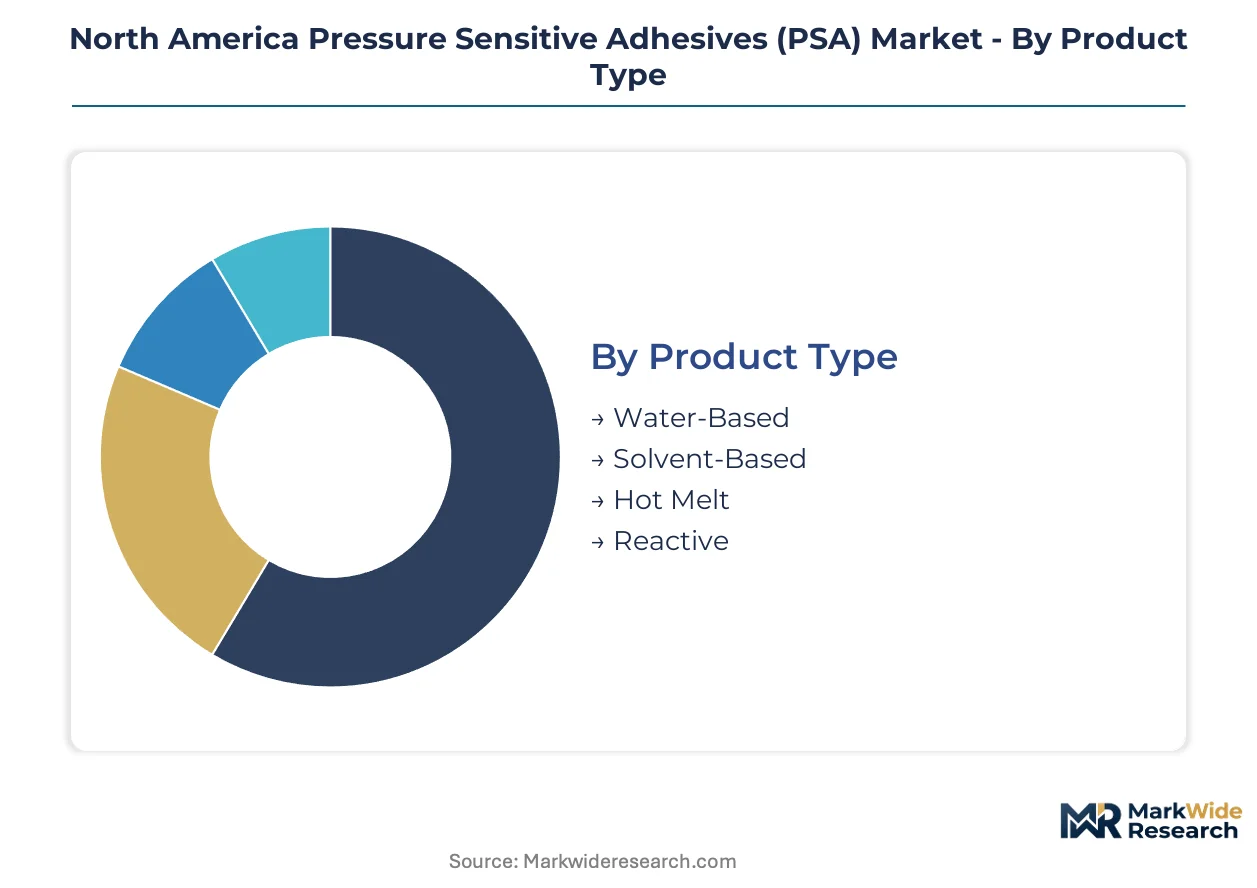
Segmentation in North American PSA markets reveals how formulation chemistry, end-use durability requirements, and converting technology intersect to create distinct competitive arenas. Each dimension carries different margin profiles, regulatory exposure, and capital intensity thresholds that shape supplier positioning.
Product Type:
Cost tier stratification across formulation systems determines capital requirements, regulatory compliance burden, and pricing power in converting negotiations.
- Water-Based:Acrylic emulsions suspended in aqueous carriers achieve food-contact compliance through low residual monomer content. Demand concentrates in labeling applications across the US Southeast, where Atlanta and Charlotte packaging hubs prioritize odor-free substrates for consumer goods.
- Solvent-Based:Solutions of natural rubber or synthetic elastomers in organic carriers deliver sterilization resistance and skin biocompatibility for medical-grade tapes. Michigan and Ohio automotive suppliers retain limited solvent capacity for structural bonding where hot melt shear resistance proves insufficient.
- Hot Melt:Thermoplastic block copolymers applied molten and set on cooling enable immediate bond formation at line speeds exceeding water-based drying cycles.
- Reactive:Moisture-curing polyurethanes and UV-acrylates form crosslinked networks delivering elevated temperature resistance for electronics assembly in Querétaro manufacturing zones.
Water-based acrylics hold installed capacity. Hot melt systems are rotating up the share rankings.
End User:
Application durability requirements and volume scale separate commodity converters from specialty formulation houses across customer segments.
- Packaging:E-commerce fulfillment centers in Georgia and Tennessee demand instant-bond hot melt tapes compatible with automated case sealers operating at 40+ cases per minute. Water-based acrylics retain share in corrugated labeling where recyclability certification commands procurement preference.
- Automotive:Structural PSA tapes substitute mechanical fasteners in Michigan and Ohio assembly plants, reducing vehicle mass while accommodating mixed-material joining. OEM specifications require 10-year durability validation and crash-load adhesion retention.
- Electronics:Thin-film bonding for displays and battery assembly demands clean-room compatible formulations with ionic purity below 50 ppm.
- Construction:Weatherproofing membranes and flooring installation systems require elevated temperature resistance and plasticizer migration resistance.
Packaging commands absolute volume scale. Automotive delivers the steepest margin expansion trajectory.
Application:
Functional performance specifications and regulatory exposure create divergent margin pools across adhesive deployment modes.
- Labeling:Face stock adhesion to paper and film substrates requires balanced tack and removability for variable information printing. FDA food-contact evaluations and Health Canada PMRA parallel assessments create dual-jurisdiction compliance timelines for cross-border CPG launches.
- Tapes:Carrier-backed systems span masking, electrical insulation, and packaging reinforcement with divergent backing material requirements. E-commerce acceleration in US Southeast distribution corridors is expanding gummed paper and reinforced filament tape volumes.
- Graphics:Vehicle wraps and signage applications demand repositionability during installation with long-term outdoor durability.
- Medical:Skin-contact adhesives must demonstrate ISO 10993 biocompatibility and gamma sterilization resistance, locking formulations into solvent-based systems despite EPA VOC pressure.
Labeling anchors production throughput. Medical commands pricing premium sustainability.
Technology:
Print method compatibility and converting speed requirements determine adhesive rheology specifications and coating equipment configuration.
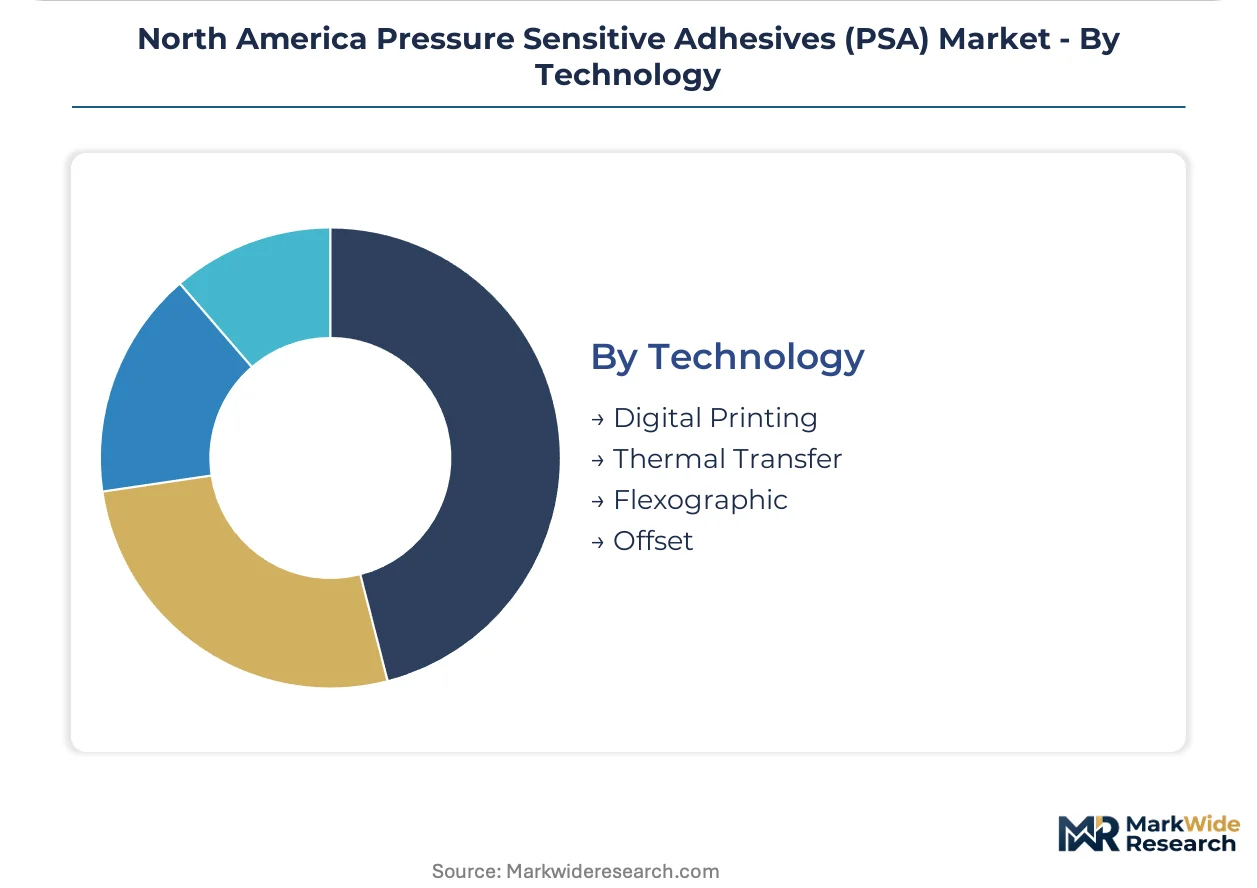
- Digital Printing:Inkjet and toner-based variable data printing on pressure-sensitive labels requires low-surface-energy adhesives compatible with silicone release liners. North Carolina and Wisconsin mid-tier converters adopt hybrid UV/LED curing to eliminate solvent recovery infrastructure.
- Thermal Transfer:Wax-resin ribbon imaging on barcode labels demands smudge-resistant adhesive surfaces with controlled thermal conductivity for clean edge definition.
- Flexographic:Rotary letterpress analog printing on wide-web label stock maintains cost leadership in high-volume beverage and food labeling.
- Offset:Lithographic transfer of oil-based inks onto PSA substrates persists in security printing and pharmaceutical booklet labels requiring fine-line resolution.
Digital printing is climbing the fastest in converter investment priority. Flexographic retains legacy volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of 40 CFR Part 59 VOC limits and state-level extended producer responsibility frameworks are redirecting PSA manufacturing investment toward compliant coating corridors. The United States anchors regional volume through automotive lightweighting mandates and e-commerce packaging acceleration. Canada and Mexico present nearshoring arbitrage opportunities with divergent regulatory timelines.
United States
Michigan and Ohio automotive OEMs are expanding structural PSA tape consumption for mixed-material vehicle assembly. The EPA's Clean Air Act deadlines under 40 CFR Part 59 Subpart F are forcing solvent-based converters toward water-based capital equipment. Atlanta and Charlotte packaging hubs in the US Southeast concentrate hot melt demand from fulfillment centers requiring instant-bond line speeds.
Canada
Health Canada's PMRA parallel assessments for food-contact labeling adhesives create dual-jurisdiction compliance burdens for cross-border CPG launches. The country's national environmental regulator maintains VOC content limits that lag EPA enforcement intensity, preserving limited solvent-based flexibility. Ontario and Quebec manufacturing corridors supply automotive assembly plants with cold-weather formulated tapes.
Mexico
Automotive and electronics assembly growth in Querétaro and Baja California is pulling localized PSA supply chain investment with NAFTA-compliant origin documentation requirements. The country's federal environmental authority enforces emissions standards that permit solvent-based medical-grade production unavailable in US facilities. Toll manufacturing arrangements cluster around Mexico City Metro for US brand owner cost arbitrage.
North America Pressure Sensitive Adhesives (PSA) Market Competitive Landscape
On the supply side, the industry is consolidating around formulation houses with captive resin production and distribution density across automotive corridors. The vendor base separates into three strategic archetypes: integrated chemical conglomerates with catalyst technology leadership, specialty adhesive houses with regional service networks, and toll converters with asset-light leasing models. Dominant competitive moves include backward integration into film substrates and strategic partnerships for RFID-enabled smart label convergence.
Among US-based diversified manufacturers, 3M and Dow exemplify integrated archetypes with proprietary technology platforms. H.B. Fuller Company represents the specialty adhesive house model with regional distribution density. Avery Dennison Corporation anchors the premium label-grade segment through in-house film substrate production. These three occupy positions across distinct competitive vectors rather than direct overlap.
| Leading Market Players |
|---|
| 3M |
| Arkema Group |
| H.B. Fuller Company |
| Dow |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| Ashland |
| Sika AG |
| Wacker Chemie AG |
| Others |
Value Network & Pricing Analysis
Acrylic monomer and rubber block copolymer concentration in Gulf Coast petrochemical corridors feeds directly into margin pools at formulation houses serving Michigan and Ohio automotive corridors. Water-based acrylic converters capture premium positioning through EPA-compliant capital equipment, while solvent-based medical-grade suppliers defend pricing power through sterilization-resistance specifications that resist full migration.
Pricing Analysis
Certification level creates the primary spread between medical-grade solvent formulations and commodity packaging tapes. Three-tier pricing structure across premium, standard, and economy levels segments by FDA food-contact compliance, automotive OEM validation status, and volume contract scale. Pricing pressure stems from petrochemical feedstock volatility compressing margin predictability for mid-tier formulation houses. E-commerce fulfillment centers in Georgia and Tennessee exhibit highest price sensitivity, while medical device OEMs in Minnesota and Massachusetts show least sensitivity due to sterilization-grade lock-in.
Supply Chain Analysis
Acrylic monomer production concentrates in Texas and Louisiana petrochemical complexes, with rubber block copolymers sourcing from South Korea and Japan. Raw material dependencies span crude oil derivatives, metallocene catalysts, and silicone precursors. Supply chain risk centers on tariff exposure for Asian elastomer imports under evolving trade frameworks. Distribution runs through Chicago and Detroit toll manufacturing clusters, with asset-light leasing models enabling rapid capacity scaling without fixed capital commitment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards incumbents with regulatory entrenchment through EPA compliance documentation and OEM validation timelines that create switching costs. Network effects concentrate among suppliers with backward integration into film substrates and captive resin production.
For Market Incumbents: Pre-empt emerging water-based formulation competitors by accelerating coating equipment leasing partnerships in Atlanta and Charlotte packaging corridors. Secure toll manufacturing exclusivity agreements before asset-light models proliferate. Invest in NAFTA-compliant origin documentation capabilities to capture Mexico nearshoring volumes in Querétaro automotive zones.
For New Entrants and Emerging Players: Pursue specialty medical-grade solvent formulations where sterilization resistance requirements prevent incumbent migration, despite EPA pressure. Target RFID-enabled smart label convergence partnerships with pharmaceutical cold chain operators in North Carolina. Lead with UV-curable technology offerings that eliminate solvent recovery infrastructure for mid-tier Wisconsin converters.
For Investors and Strategic Acquirers: Capital is best deployed toward formulation houses with captive resin production and established automotive OEM validation status. Long-term viability hinges on regulatory compliance entrenchment and geographic density across US Southeast packaging hubs. Monitor EPA enforcement intensity for 40 CFR Part 59 Subpart F as inflection indicator for water-based capital equipment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Substrates | Avery Dennison's captive supply of label-grade films creates margin defense against commodity converters. |
| UV-Curable Coating Line Adoption | North Carolina converters eliminate solvent recovery systems through hybrid UV/LED curing infrastructure. |
| NAFTA-Compliant Mexico Capacity | Querétaro toll manufacturing serves automotive OEMs with localized supply chain and origin documentation. |
| Extended Producer Responsibility Programs | California and New York mandates create service-revenue streams for integrated label take-back operations. |
| RFID-Enabled Smart Label Partnerships | Pharmaceutical cold chain tracking embeds pressure-sensitive antennas with premium positioning potential. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement records, customs trade data, and ACC industry reports. Interviews with coating plant managers, automotive OEM procurement leads, distribution channel partners, and technical R&D directors at formulation houses inform demand-side validation. Bottom-up capacity modeling triangulates against top-down consumption estimates derived from end-use industry production data.
Forecast inputs include formulation chemistry migration rates, automotive lightweighting content-per-vehicle trajectories, and e-commerce packaging velocity indices across the analysis window. Segmentation dimensions span product type, end-use industry, application mode, and converting technology. CAGRs derive from regression analysis against macroeconomic drivers and regulatory compliance timeline assumptions.
Macroeconomic conditions sit as an overlay; deviation in crude oil indices, automotive production schedules, or EPA enforcement intensity would shift the trajectory. Cross-checking against ACC capacity utilization surveys and OEM adhesive specification databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
Global EVA Adhesives Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Anaerobic Adhesives Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Automotive Adhesives and Sealants Market
Adhesives & Sealants
North America Construction Adhesives and Sealants Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Adhesive Resin Market