
 Vietnam Construction Chemicals Market | 2026-2036
Vietnam Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Construction Chemicals Market Analytics
Technical advisory and jobsite application support is hardening into a distinct revenue layer alongside product sales. Mapei Vietnam Co. Ltd. leverages its localized formulation labs to anchor specification relationships with tier-one contractors. BASF Vietnam Co. Ltd. sustains R&D intensity in polycarboxylate ether superplasticizers, competing for megaproject tenders in the north. Sika Limited (Vietnam) dominates the repair and waterproofing channel through direct technical service teams embedded at major construction sites.
Construction chemicals encompass specialty formulations—concrete admixtures, cement additives, protective coatings, and sealants—engineered to modify setting time, compressive strength, durability, or chemical resistance in built structures. These products typically incorporate acrylic, epoxy, polyurethane, or silane-based active ingredients dosed at 0.5% to 5% by weight of cementitious binder, serving to extend service life and reduce maintenance cycles in aggressive tropical climates. Concrete admixtures command the deepest specification ties with ready-mix producers, while waterproofing applications absorb disproportionate margin pools from basement and tunnel contracts. Polymer-based technology leads product development pipelines as formulators phase out solvent carriers to meet indoor air quality limits.
Vietnam's Ministry of Construction enforces QCVN building codes that mandate minimum durability grades for coastal and flood-zone structures, directly elevating demand for corrosion-inhibiting admixtures and crystalline waterproofing systems. BIS-equivalent conformity assessment procedures for imported construction chemicals create compliance friction that favors domestic blending operations with certified quality management systems. The central bank's prudential caps on real estate lending and provincial land-use masterplans will determine which urban corridors sustain chemical offtake momentum. Stakeholders must monitor infrastructure budget execution rates and state-owned enterprise contractor liquidity positions to anticipate specification-grade demand shifts.
Market Dynamics
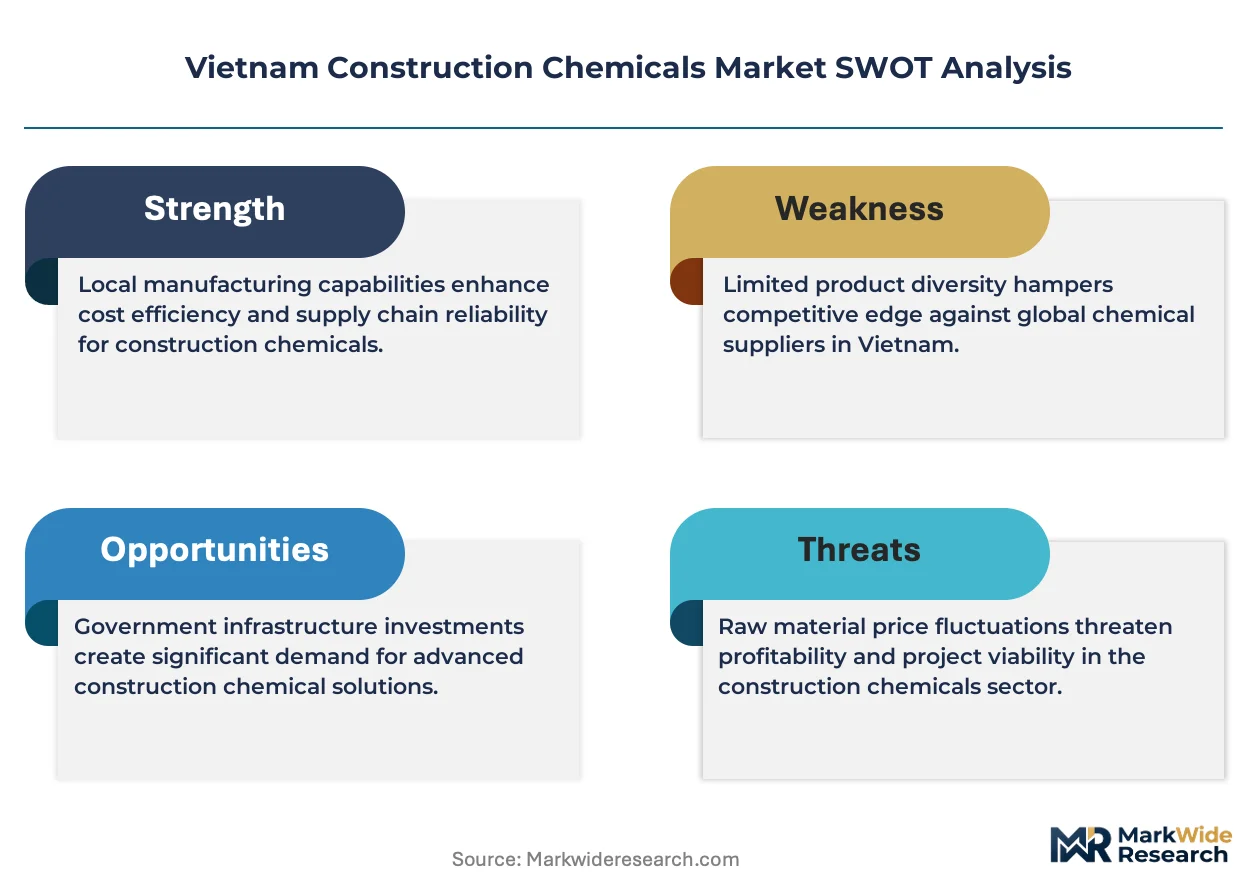
Vietnam's construction chemicals sector faces intensifying specification pressure as QCVN energy efficiency codes force formulators to reformulate solvent-based systems for low-VOC compliance. Domestic blending operations with certified quality management systems capture procurement share from import-dependent distributors.
Growth Catalysts
- QCVN Building Code Enforcement:Vietnam's Ministry of Construction mandates minimum durability grades for coastal structures, elevating demand for corrosion-inhibiting admixtures in flood-zone construction.
- Red River Delta Infrastructure Pipeline:Industrial park construction and transport corridor upgrades concentrate concrete admixture offtake in the northern economic corridor.
- High-Rise Waterproofing Procurement:Residential developers in Ho Chi Minh City and Hanoi are expanding specification of crystalline waterproofing systems for basement and podium structures.
Market Restraints
- Import Compliance Friction:BIS-equivalent conformity assessment procedures for foreign construction chemicals create certification delays that disadvantage non-domestic suppliers.
- Real Estate Lending Caps:The State Bank of Vietnam's prudential limits on property sector credit constrain developer liquidity and specification-grade chemical procurement cycles.
- Epoxy Resin Cost Volatility:Protective coatings formulators face margin compression from fluctuating petrochemical feedstock prices in polymer-based systems.
Strategic Opportunities
- Mekong Delta Underpenetration:Southern provinces outside the Red River corridor show low specification-grade chemical penetration, offering first-mover positioning for localized technical service teams.
- Repair and Rehabilitation Channel:Aging infrastructure stock in Hanoi and Ho Chi Minh City creates aftermarket demand for injection grouts and structural strengthening systems.
- Polymer-Silane Convergence:Hybrid waterproofing chemistries combining polyurethane backbone with silane crosslinking chemistry enable premium positioning for tunnel and marine applications.
Industry Challenges
- Formulation Chemist Scarcity:Domestic talent pools lack depth in polycarboxylate ether superplasticizer synthesis and tropical-durability testing protocols.
- Jobsite Application Training Gap:Tier-two contractors struggle with proper dosing and curing protocols for crystalline waterproofing systems, generating warranty disputes and specification downgrades.
- Multi-Tier Certification Complexity:Navigating QCVN compliance alongside project-specific green building ratings fragments quality assurance workflows for formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Construction Chemicals Market |
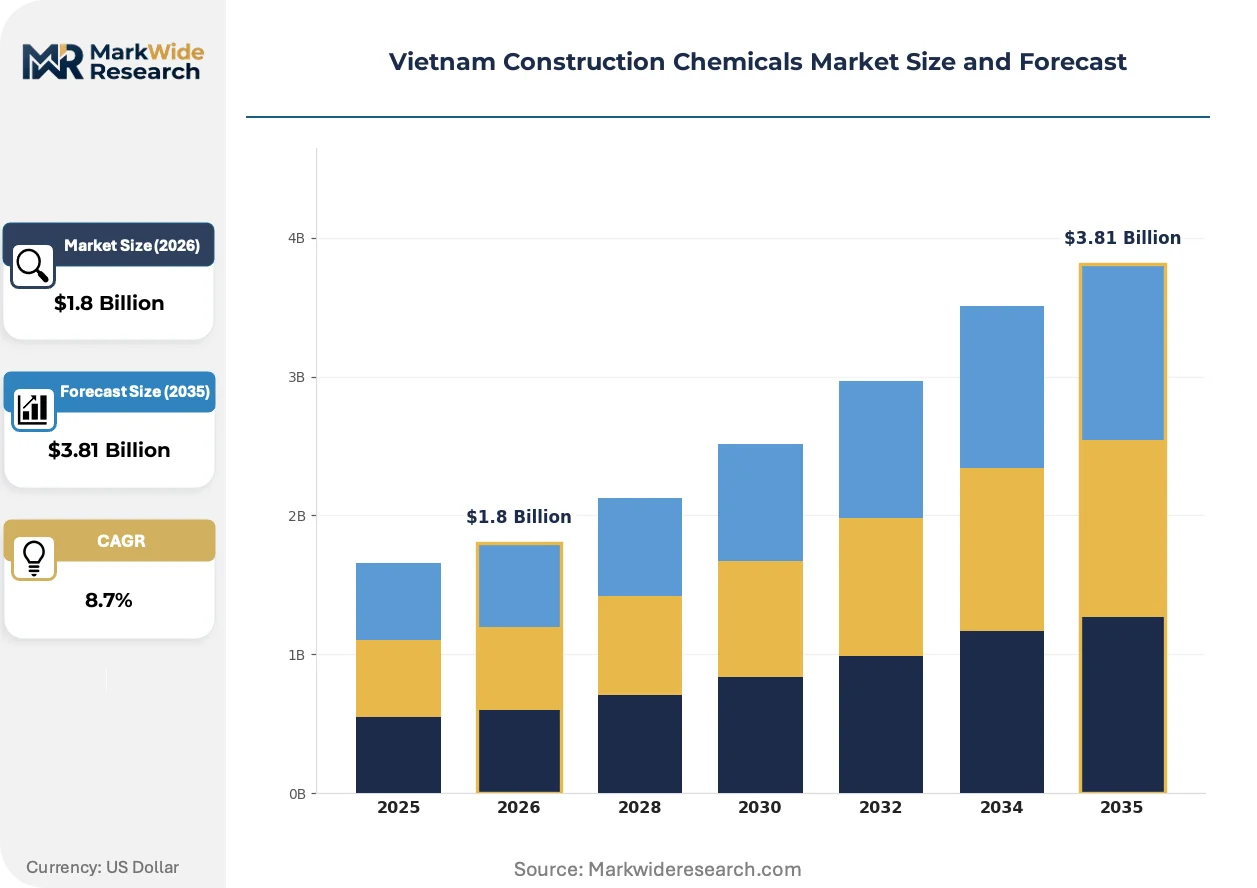
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement Additives, Concrete Admixtures, Protective Coatings, Sealants End User: Residential, Commercial, Industrial, Infrastructure Application: Flooring, Waterproofing, Repair, Surface Treatment Technology: Polymer-based, Solvent-based, Water-based, Others |
| Companies Covered | Mapei Vietnam Co. Ltd., Ecolab Vietnam Co. Ltd., BASF Vietnam Co. Ltd., Dow Chemical Vietnam LLC, Fosroc Vietnam, Sika Limited (Vietnam), Solenis Vietnam Company Limited, GCP Vietnam Company Limited, Bestmix Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Construction Chemicals Market Evolving Landscape
Formulation technology in Vietnam is pivoting toward waterborne and hybrid polymer systems as regulatory pressure compounds with developer sustainability mandates. Technical service capabilities are becoming the primary competitive differentiator beyond product specifications.
Polycarboxylate ether superplasticizer technology is decentralizing specification authority from centralized ready-mix producers toward project-specific consulting engineers. Major infrastructure tenders in the Red River Delta now require PCE-compatible mix designs with extended slump retention. This shift is decentralizing procurement decisions from volume-contract frameworks toward job-specific performance guarantees.
Vietnam's Ministry of Construction QCVN standards mandate progressive reductions in solvent content for interior-grade coatings and sealants. Formulators must revalidate product lines through revised emission testing protocols. The waterproofing segment bears the heaviest compliance burden, with crystalline and cementitious systems displacing bituminous membranes in basement specifications.
Specification authority is migrating from contractor procurement departments toward project consulting engineers and owner technical representatives. Tier-one developers in Ho Chi Minh City now require independent third-party testing of admixture performance claims before contract award. This behavioral shift compresses switching cycles and elevates the value of localized formulation laboratories with rapid batch adjustment capabilities.
Vietnam Construction Chemicals Market Segmentation
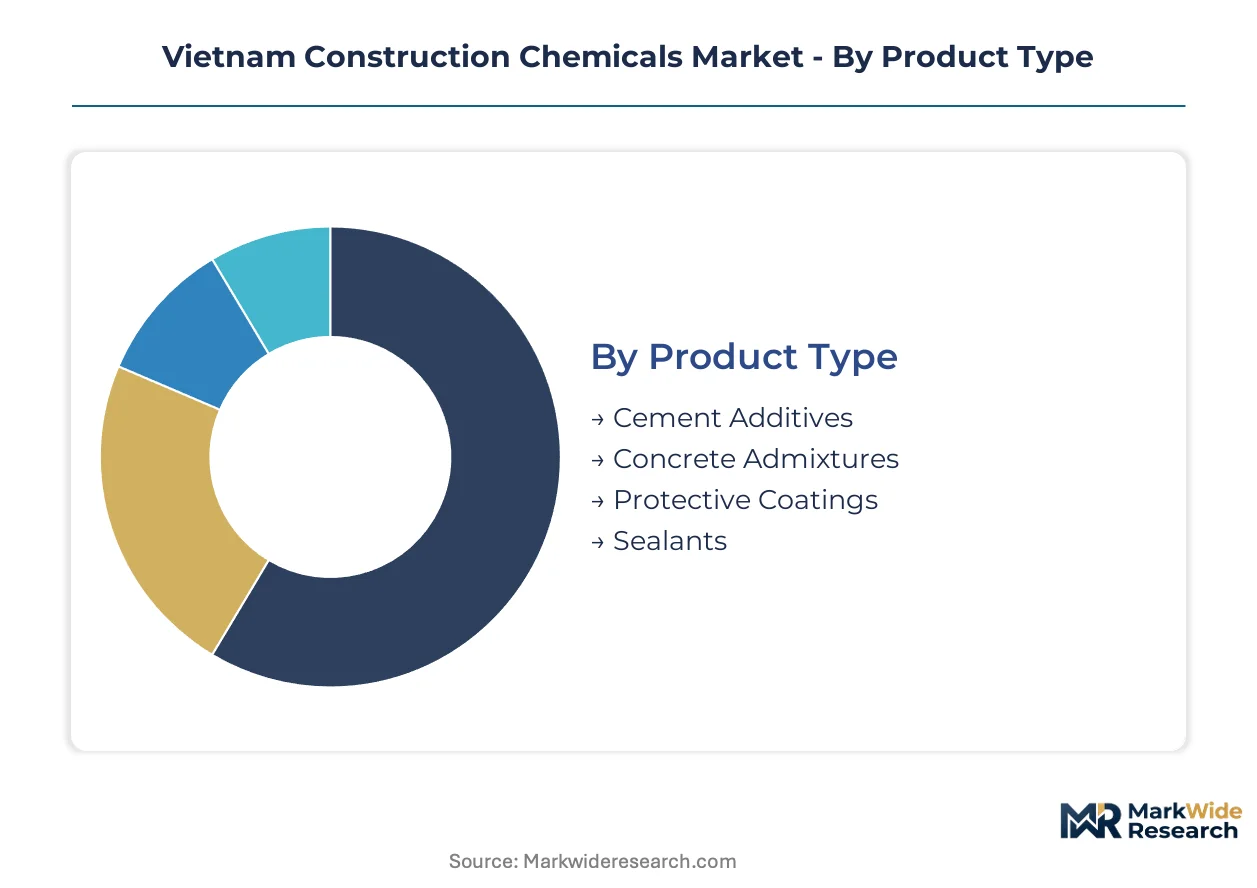
Segmentation in Vietnam's construction chemicals market reveals how QCVN compliance burdens concentrate differently across product categories. Specification authority migrates toward segments requiring certified quality management systems and localized technical validation.
Product Type:
QCVN conformity assessment procedures from Vietnam's Ministry of Construction impose tiered certification friction across product categories, with imported formulations facing extended revalidation timelines.
- Concrete Admixtures:Polycarboxylate ether and naphthalene-based formulations modify setting time and compressive strength in ready-mix applications. Demand concentrates in the Red River Delta corridor where industrial park construction absorbs bulk volumes for high-specification infrastructure. QCVN durability mandates for coastal structures elevate specification of corrosion-inhibiting variants.
- Protective Coatings:Epoxy, polyurethane, and acrylic systems provide chemical resistance and aesthetic finish to concrete and steel substrates. Reformulation pressure intensifies as QCVN standards phase out solvent carriers for low-VOC compliance in interior-grade specifications. Margin compression from petrochemical feedstock volatility constrains formulator flexibility.
- Cement Additives:Grinding aids and performance enhancers optimize clinker efficiency in integrated cement operations.
- Sealants:Elastomeric joint fillers accommodate structural movement in high-rise podium and basement applications.
Leading the category by volume: Concrete Admixtures. Expanding most quickly: Protective Coatings.
End User:
Procurement authority fragments across end-user segments as tier-one developers internalize technical specification while state-owned contractors operate under centralized framework agreements.
- Infrastructure:Transport corridor upgrades and flood-zone marine works mandate certified durability grades under QCVN codes. The Red River Delta pipeline concentrates admixture offtake through state-owned enterprise contractors with established technical service relationships. Extended slump retention specifications in megaproject tenders decentralize procurement toward job-specific performance guarantees.
- Residential:High-rise developers in Ho Chi Minh City and Hanoi specify crystalline waterproofing systems for basement and podium structures. Prudential lending caps from the State Bank of Vietnam constrain developer liquidity and compress specification-grade chemical procurement cycles. Independent third-party testing requirements before contract award elevate switching costs.
- Commercial:Office and retail construction drives demand for aesthetic finishes and rapid-curing flooring systems.
- Industrial:Manufacturing facility construction requires chemical-resistant coatings and heavy-duty joint sealants.
Dominant by procurement value: Infrastructure. Gaining share fastest: Residential.
Application:
Margin pools concentrate disproportionately in applications requiring embedded technical service and warranty-backed performance guarantees.
- Waterproofing:Crystalline, cementitious, and bituminous systems protect basement, tunnel, and marine structures from hydrostatic pressure. Crystalline technology displaces solvent-based membranes in Ho Chi Minh City high-rise specifications as QCVN indoor air quality limits tighten. Tier-two contractor application training gaps generate warranty disputes and specification downgrades.
- Repair:Injection grouts, structural strengthening composites, and surface preparation systems address aging infrastructure stock in Hanoi and Ho Chi Minh City. Aftermarket demand accelerates as warranty periods expire on decade-old commercial and residential construction. Technical advisory services harden into distinct revenue layers alongside product sales.
- Flooring:Self-leveling compounds and decorative coatings serve commercial and industrial wear surfaces.
- Surface Treatment:Curing compounds and densifiers extend concrete service life in aggressive tropical climates.
Capturing the deepest margins: Waterproofing. Climbing the fastest: Repair.
Technology:
Formulation pipelines pivot toward hybrid systems as regulatory pressure compounds with developer sustainability mandates and indoor air quality specifications.
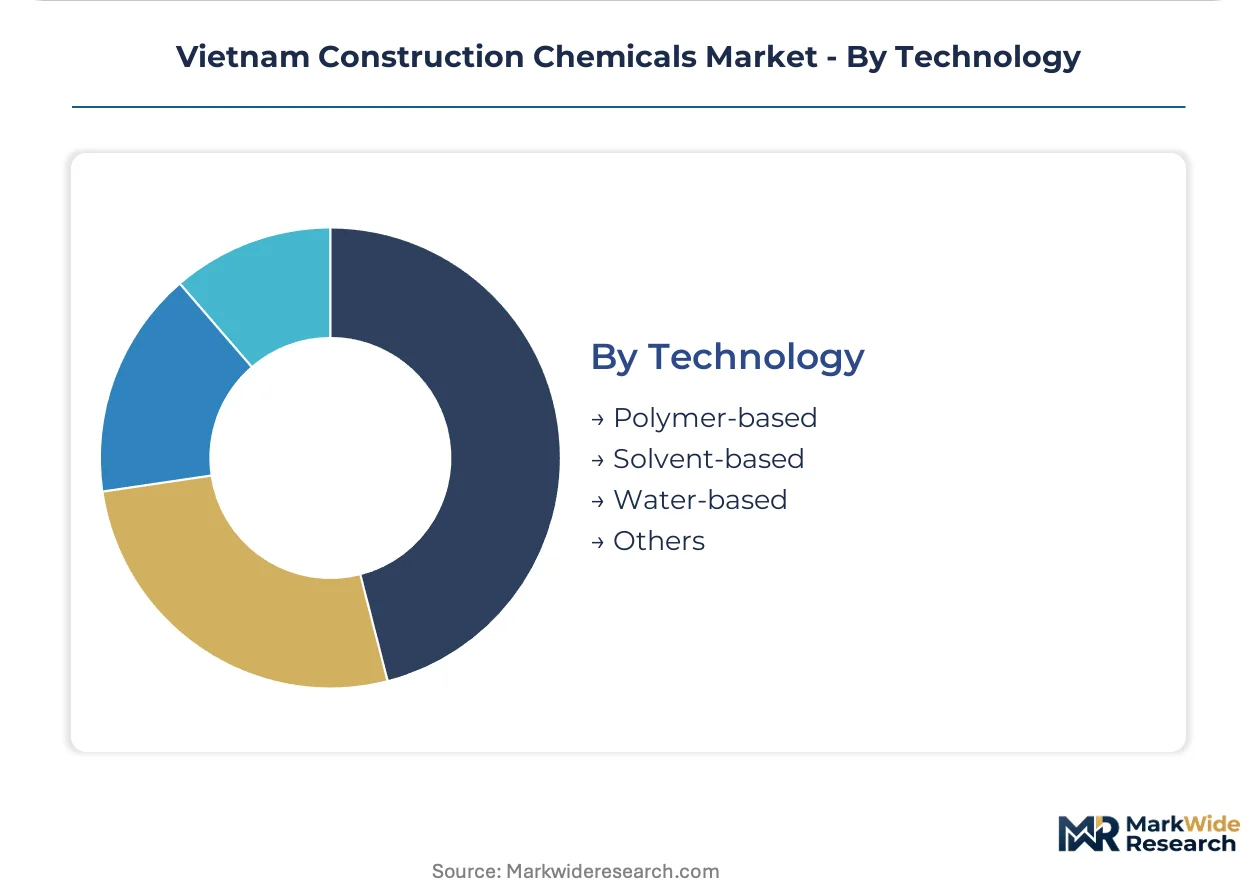
- Polymer-based:Acrylic, epoxy, polyurethane, and silane-active chemistries deliver elasticity, adhesion, and chemical resistance in protective and waterproofing applications. Hybrid polymer-silane convergence enables premium positioning for tunnel and marine specifications requiring combined hydrophobicity and mechanical durability. Technology leadership concentrates specification authority with formulators maintaining localized synthesis and batch adjustment capabilities.
- Water-based:Reduced-VOC emulsions and dispersions replace solvent carriers in interior-grade coatings and sealants. QCVN emission testing protocols force product line revalidation, favoring domestic blending operations with certified quality management systems over import-dependent distributors.
- Solvent-based:Conventional carrier systems face phased compliance pressure under progressive QCVN reduction mandates.
- Others:Cementitious and inorganic systems serve cost-sensitive specifications with lower performance requirements.
Commanding specification priority: Polymer-based. Steepest expansion trajectory: Water-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Red River Delta corridor anchors Vietnam's construction chemicals demand, with Hanoi and Hai Phong industrial zones absorbing bulk volumes of concrete admixtures for transport infrastructure megaprojects. Provincial land-use masterplans and state-owned enterprise contractor networks determine regional offtake patterns.
Red River Delta
Industrial park construction and flood-zone marine works concentrate specification-grade admixture procurement through state-owned contractors. Vietnam's Ministry of Construction QCVN durability mandates for coastal structures elevate corrosion-inhibiting formulations in Hai Phong port expansions. Extended slump retention specifications decentralize procurement toward job-specific performance guarantees in Bac Ninh and Hung Yen manufacturing corridors.
Southeast Region
Ho Chi Minh City high-rise developers specify crystalline waterproofing systems for basement and podium structures at accelerating rates. The State Bank of Vietnam's prudential lending caps constrain developer liquidity and compress procurement cycles in Binh Duong and Dong Nai satellite industrial zones. Independent third-party testing requirements before contract award elevate switching costs for tier-one residential projects.
Central Coast
Da Nang and Quang Nam infrastructure upgrades absorb moderate admixture volumes for transport corridor modernization. QCVN building energy efficiency codes push formulators toward low-VOC polymer systems in hospitality and commercial developments. The East-West Economic Corridor links to Lao Bao border infrastructure create intermittent demand spikes for certified durability-grade materials.
Mekong Delta
Southern provinces outside core economic corridors show low specification-grade chemical penetration relative to construction activity. Provincial contractor networks favor cost-sensitive cementitious systems over polymer-based waterproofing in Can Tho and An Giang residential developments. First-mover positioning opportunities exist for localized technical service teams addressing application training gaps.
Vietnam Construction Chemicals Market Competitive Landscape
Capital-heavy producers compete with asset-light technical service specialists across Vietnam's construction chemicals sector. Domestic blending operations with certified quality management systems capture procurement share from import-dependent distributors facing BIS-equivalent conformity friction. Three archetypes dominate: multinational formulators with localized R&D facilities, regional distributors with specification relationships, and domestic blenders with QCVN compliance advantages. Competitive moves concentrate on technical advisory embedding at megaproject sites and backward integration into polymer synthesis.
Among multinational formulators, Mapei Vietnam Co. Ltd., BASF Vietnam Co. Ltd., and Sika Limited (Vietnam) exemplify the technical-service-anchored archetype. These entities occupy positions where localized formulation laboratories and direct jobsite application support harden into distinct revenue layers beyond product sales. Their presence represents the premium-tier vector where specification authority migrates toward project consulting engineers requiring rapid batch adjustment capabilities and warranty-backed performance guarantees.
| Leading Market Players |
|---|
| Mapei Vietnam Co. Ltd. |
| Ecolab Vietnam Co. Ltd. |
| BASF Vietnam Co. Ltd. |
| Dow Chemical Vietnam LLC |
| Fosroc Vietnam |
| Sika Limited (Vietnam) |
| Solenis Vietnam Company Limited |
| GCP Vietnam Company Limited |
| Bestmix Corporation |
| Others |
Value Network & Pricing Analysis
Formulation chemist scarcity in Vietnam's Red River Delta widens spreads between premium-certified and economy-grade admixture pricing tiers. Labor-cost differentials between domestic blending operations and import-dependent distributors compound these gaps as QCVN compliance burdens concentrate specification authority.
Pricing Analysis
Performance guarantees tied to extended slump retention anchor value-based pricing in megaproject tenders. Three-tier pricing structure across premium-certified, standard-grade, and economy-level admixtures stratifies by QCVN conformity depth and technical service bundling. Cost compression in economy tiers intensifies as domestic blenders exploit BIS-equivalent friction to undercut import-dependent distributors. State-owned enterprise contractors show highest price sensitivity; tier-one developers with independent third-party testing requirements exhibit lowest.
Supply Chain Analysis
Direct-to-contractor channels anchored by embedded technical service teams handle specification-grade admixture demand in northern industrial corridors. Raw material sourcing draws from China for polycarboxylate ether monomers, South Korea for epoxy intermediates, and Thailand for acrylic dispersions. Single-source vulnerability in PCE superplasticizer precursor supply creates exposure to petrochemical feedstock volatility. Distribution runs through domestic blending facilities with certified quality management systems, displacing import-dependent distributor networks facing extended conformity assessment timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's construction chemicals sector is consolidating around technical service capabilities as QCVN compliance costs and formulation complexity force smaller import-dependent distributors toward exit. The State Bank of Vietnam's prudential lending caps accelerate this pressure by compressing developer liquidity and specification-grade procurement cycles.
For Market Incumbents: To counter domestic blending operations with QCVN compliance advantages, anchor specification relationships through localized formulation laboratories with rapid batch adjustment capabilities. Deepen backward integration into polymer synthesis to secure captive supply of polycarboxylate ether monomers and reduce exposure to Chinese petrochemical feedstock volatility. Prioritize embedding technical advisory teams at Red River Delta megaproject sites to harden switching costs. For New Entrants and Emerging Players: A mid-market price-point gap between premium multinational formulations and economy-grade cementitious systems creates entry space for hybrid polymer-silane waterproofing positioned at standard-tier pricing. Target Mekong Delta provinces outside core economic corridors where specification-grade chemical penetration remains low and application training gaps generate warranty disputes. Lead with localized jobsite support capabilities rather than product specifications to differentiate from import-dependent distributors. For Investors and Strategic Acquirers: The window for entry favors domestic blending operations with certified quality management systems and established QCVN validation pathways. Long-term viability hinges on technical service density rather than manufacturing scale, favoring acquisition targets with embedded contractor relationships over asset-heavy production facilities. Monitor infrastructure budget execution rates and state-owned enterprise contractor liquidity positions as inflection indicators for specification-grade demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive supply of PCE monomers reduces Chinese petrochemical feedstock exposure for formulators. |
| Localized Formulation Laboratory Expansion | Rapid batch adjustment capabilities anchor specification relationships with tier-one contractors in Hanoi. |
| Technical Service Team Embedding | Direct jobsite presence hardens switching costs against domestic blending competitors in Red River Delta. |
| QCVN Certification Investment | Conformity assessment depth differentiates premium positioning from economy-grade cementitious competitors. |
| Mekong Delta Distribution Partnership | First-mover technical service coverage addresses application training gaps in underpenetrated southern provinces. |
Research Methodology
Document review covered customs and trade databases, Vietnam Ministry of Construction QCVN regulatory filings, and cement industry association reports, complemented by interviews with plant managers at ready-mix operations, procurement leads at tier-one residential developers, technical R&D directors at multinational formulators, and distribution channel partners. Secondary validation drew from SEC filings of global chemical producers, ACC regional construction forecasts, and industrial park development databases. Bottom-up volume estimates from project-level admixture specifications were cross-referenced against top-down cement consumption trends to triangulate market sizing.
Historical consumption patterns were cross-referenced against panel input from specification engineers and contractor procurement heads to build the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry channel, regional production hub, and application complexity tier. CAGRs were derived from trend extrapolation of QCVN compliance adoption curves and infrastructure budget execution trajectories. Industry-specific forecast inputs incorporated polycarboxylate ether specification penetration rates and crystalline waterproofing displacement of bituminous membrane systems.
Inputs from state-owned enterprise contractors and provincial industrial park authorities were available through the study window; gaps in private developer liquidity data and tier-two contractor application failure rates introduce uncertainty bands around residential segment projections. Forecasts reflect assumptions regarding QCVN enforcement consistency and central bank prudential policy stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
Wood Adhesives Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
South America Sealants Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
Europe, Middle-East and Africa Hot-Melt Adhesives Market