
 Construction Adhesives and Sealants Chemical Market | 2026-2036
Construction Adhesives and Sealants Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Adhesives and Sealants Chemical Market Outlook
The capital-intensity divergence between fully integrated resin producers and formulation-only specialists is redrawing competitive boundaries across the construction adhesives and sealants chemical sector. Henkel AG & Co. KGaA leverages its captive epoxy and polyurethane resin capabilities to control raw material quality and cost positions in European commercial construction. Sika AG anchors its position through deep vertical integration into silicone polymer production, sustaining margin pools that formulation competitors cannot replicate. BASF SE competes from the opposite direction, extending its commodity chemical base into tailored adhesive systems for infrastructure projects.
Construction adhesives and sealants chemicals encompass formulated bonding and gap-filling compounds based on polyurethane, silicone, epoxy, and acrylic polymer systems, typically supplied with viscosity ranging from 5,000 to 500,000 centipoise and cure mechanisms activated by moisture, heat, or two-part catalysis, serving primarily to transfer structural loads, accommodate thermal movement, and prevent moisture ingress in built environments. Polyurethane formulations dominate residential and commercial construction applications due to their superior adhesion to porous substrates and flexibility across temperature extremes, while silicone sealants command premium positions in infrastructure and facade sealing where UV stability and joint movement accommodation prove critical. Epoxy systems occupy specialized niches in industrial flooring and structural bonding, where high compressive strength and chemical resistance justify their higher material cost and more demanding surface preparation requirements.
The EPA regulates VOC emissions from architectural coatings and sealants under 40 CFR Part 59, while OSHA sets worker exposure limits for isocyanates and other reactive components during application, collectively pushing manufacturers toward waterborne and low-isocyanate formulations. REACH registration requirements in Europe and China's GB standards for construction chemicals add compliance layers that favor larger players with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving state-level green building codes and procurement specifications that increasingly mandate Environmental Product Declarations, as these will determine which chemistries qualify for publicly funded infrastructure work.
Market Dynamics
The construction adhesives and sealants chemical market is undergoing fundamental restructuring as REACH and EU Green Deal regulations force wholesale reformulation away from solvent-borne systems toward waterborne and low-VOC alternatives, compressing legacy product margins while rewarding early movers with compliant portfolios.
Growth Catalysts
- Urban Renewal Infrastructure:China's high-speed rail expansion and city retrofit programs are consuming industrial-scale volumes of polyurethane and silicone sealants for structural bonding and expansion joint sealing.
- Low-Emission Mandates:The EU Green Deal's tightening VOC limits are accelerating replacement cycles in European commercial construction as building codes disqualify conventional formulations from public procurement.
- Polyurethane Performance Advantages:Superior adhesion to porous substrates and flexibility across temperature extremes is driving specification upgrades in North American residential envelope systems.
Market Restraints
- Petrochemical Feedstock Volatility:Propylene oxide and MDI pricing swings compress formulation margins, particularly for polyurethane specialists without backward integration into basic chemicals.
- Isocyanate Regulatory Friction:OSHA's strict worker exposure limits for isocyanates during application add compliance costs and restrict spray application methods in US commercial projects.
- Silicone Supply Concentration:Silane and silicone polymer production concentrates among a handful of integrated chemical producers, creating bottleneck risks for sealant formulators.
Strategic Opportunities
- India's Infrastructure Build-Out:The country's PLI scheme for construction chemicals and smart cities mission create entry points for compliant adhesive systems in metro rail and airport terminals.
- Environmental Product Declaration Tailwinds:LEED v4.1 and BREEAM certification mandates in Germany and France are creating specification premiums for third-party-validated low-carbon formulations.
- Hybrid Technology Convergence:Silane-terminated polyurethane hybrids are capturing share in facade sealing by combining silicone UV stability with polyurethane substrate adhesion.
Industry Challenges
- Formulation Chemist Scarcity:The specialized knowledge required to balance cure kinetics, rheology, and regulatory compliance across polymer systems is concentrating among senior technical staff at established players.
- Certification Timeline Compression:EPD and HPD documentation requirements for green building projects extend product development cycles by 12-18 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Adhesives and Sealants Chemical Market |
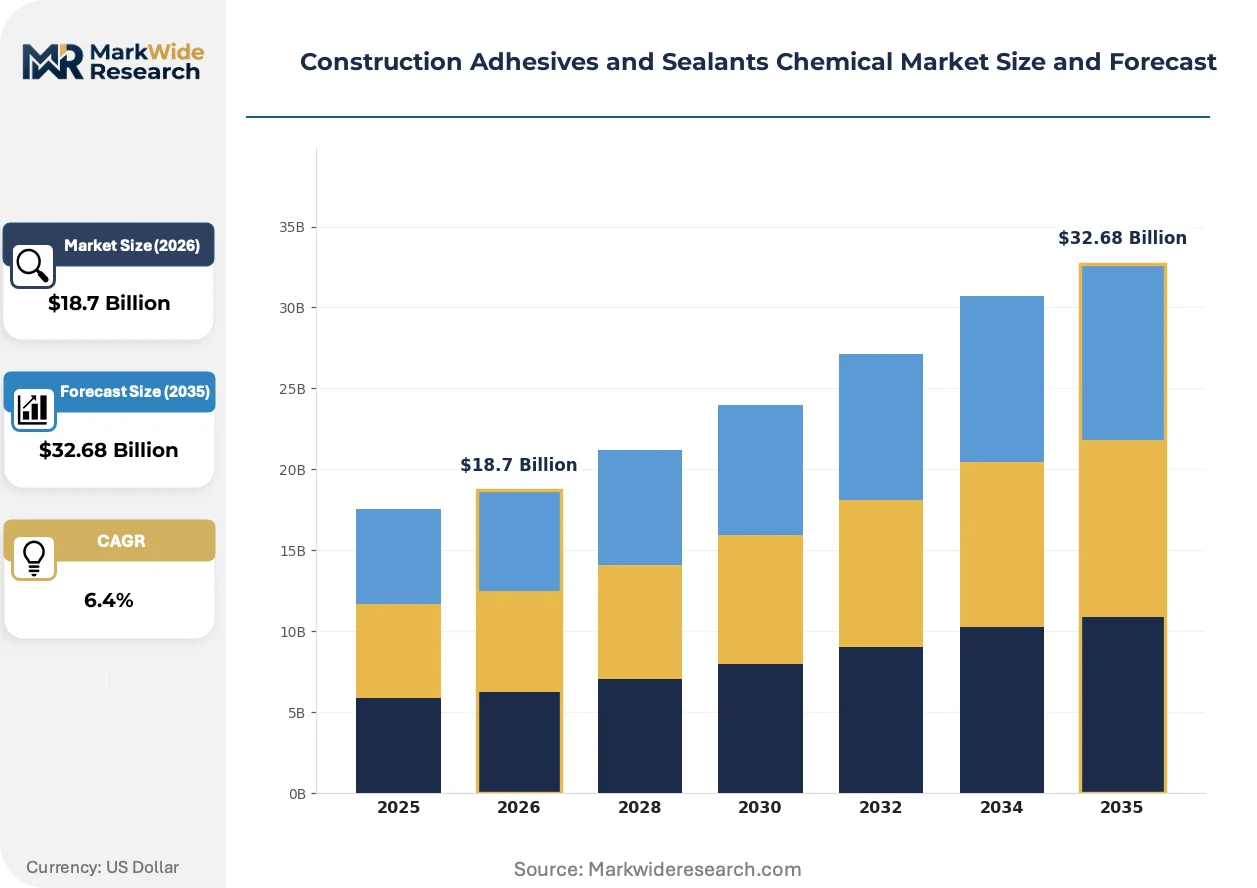
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Epoxy, Acrylic Application: Residential Construction, Commercial Construction, Industrial Applications, Infrastructure Projects End User: Contractors, DIY Enthusiasts, Manufacturers, Architects Packaging Type: Tubes, Pails, Bags, Cartridges |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, 3M, H.B. Fuller Company, Arkema, Dow Inc., BASF SE, Wacker Chemie AG, Mapei SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Adhesives and Sealants Chemical Market Strategic Shifts
Waterborne adhesive technology is fragmenting competitive positions as incumbent solvent-borne specialists face capability gaps in emulsion polymerization and film-forming aid selection. Formulators with captive resin synthesis expertise are capturing specification share in premium architectural segments.
Hybrid polymer chemistry is fragmenting traditional technology boundaries in the sealant category. Silane-terminated polyethers and polyurethanes are displacing conventional silicones in expansion joint applications where paintability and primerless adhesion matter. German facade contractors and Japanese rail infrastructure projects are specifying these systems at accelerating rates, compressing pure-play silicone margins in mid-tier performance segments.
REACH authorization requirements for substances of very high concern are fragmenting raw material sourcing strategies across European formulation. The sunset date pressures for certain plasticizers and tin catalysts are forcing reformulation investments that smaller competitors cannot absorb. Construction chemical divisions at integrated resin producers are internalizing polymer supply to control SVHC exposure, while independent formulators face escalating third-party certification costs for imported intermediates.
Consolidation among European general contractors is fragmenting procurement leverage downstream in the adhesive supply chain. Skanska, Bouygues, and Vinci are centralizing specification authority at group level, displacing project-level material selection. This concentrates volume with formulation partners capable of pan-European logistics and harmonized technical service, squeezing regional distributors and local applicator networks in France, Germany, and the Nordic markets.
Construction Adhesives and Sealants Chemical Market Segmentation
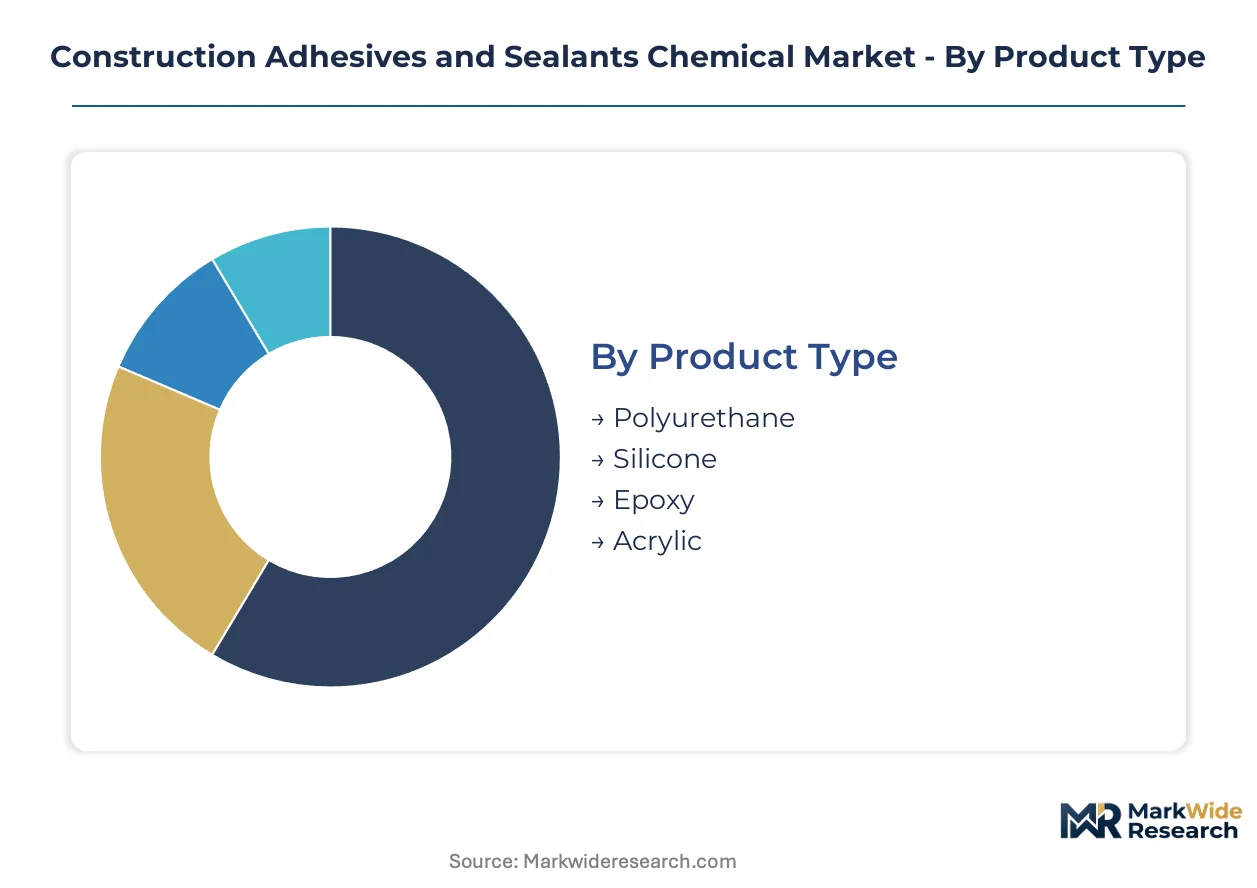
Segmentation in construction adhesives and sealants chemicals reveals divergent margin profiles across polymer chemistries and packaging formats. Specification authority varies sharply between contractor-driven bulk procurement and architect-influenced premium selections.
Product Type:
Polyurethane and silicone formulations dominate export volumes to infrastructure-heavy markets, while epoxy and acrylic systems serve more localized specialty applications.
- Polyurethane:These moisture-cure or two-part systems bond porous substrates with superior flexibility across temperature extremes. Chinese high-speed rail expansion and North American residential envelope upgrades are consuming industrial-scale volumes. The segment anchors revenue concentration due to substrate versatility.
- Silicone:UV-stable formulations accommodate thermal movement in facade sealing and expansion joints. German and French infrastructure specifications favor these systems for 50-year service life guarantees. Premium pricing reflects concentrated silane feedstock supply.
- Epoxy:High compressive strength systems serve industrial flooring and structural bonding where chemical resistance justifies demanding surface preparation protocols.
- Acrylic:Waterborne emulsions address interior finishing and paintable sealant niches with lower VOC profiles than solvent alternatives.
Polyurethane holds the largest share; momentum sits with silicone as infrastructure specifications tighten.
Application:
Volume concentration tracks construction cycle intensity, with infrastructure projects commanding longest procurement lead times and residential work showing highest price sensitivity.
- Residential Construction:Adhesive systems for subfloor bonding, window installation, and weatherproofing demand rapid cure speeds compatible with compressed build schedules. North American single-family housing starts drive specification upgrades toward higher-performance polyurethane envelope systems.
- Commercial Construction:Curtain wall installation and interior finishing require fire-rated and low-VOC formulations compliant with LEED certification pathways. EU Green Deal procurement rules are disqualifying conventional solvent-borne products from public tenders.
- Industrial Applications:Chemical-resistant flooring and equipment anchoring specify epoxy systems with defined compressive strength ratings.
- Infrastructure Projects:Bridge expansion joints and tunnel waterproofing consume bulk silicone and hybrid sealant volumes.
Residential commands volume leadership; infrastructure projects are climbing the fastest as fiscal stimulus concentrates on transport networks.
End User:
Procurement authority fragments across project phases, with architects influencing specification at design stage and contractors controlling final material selection.
- Contractors:General and specialty trades prioritize open-time latitude and cold-weather cure reliability to maintain schedule compliance. Skanska, Bouygues, and Vinci are centralizing pan-European procurement authority at holding-company level.
- DIY Enthusiasts:Retail cartridge sales favor pre-mixed, tool-free application formats with explicit substrate compatibility labeling.
- Manufacturers:Prefabricated building component producers specify adhesives for panel bonding and module weatherproofing with factory-controlled cure conditions.
- Architects:Design professionals mandate Environmental Product Declarations and HPD documentation for green building certification compliance.
Contractors hold the largest share; architects are gaining specification influence fastest as EPD requirements harden.
Packaging Type:
Format selection correlates with application scale and labor skill level, from precision cartridge dispensing to bulk pail systems for mechanized application.
- Tubes:Squeeze formats serve small-scale repair and touch-up work with minimal tooling investment.
- Pails:Bulk containers support high-volume commercial flooring and waterproofing with trowel or spray application methods.
- Bags:Flexible packaging reduces shipping cube for powder or two-part systems requiring field mixing.
- Cartridges:Standardized 300ml and 600ml formats dominate professional sealant application with caulking gun compatibility across silicone, polyurethane, and hybrid chemistries.
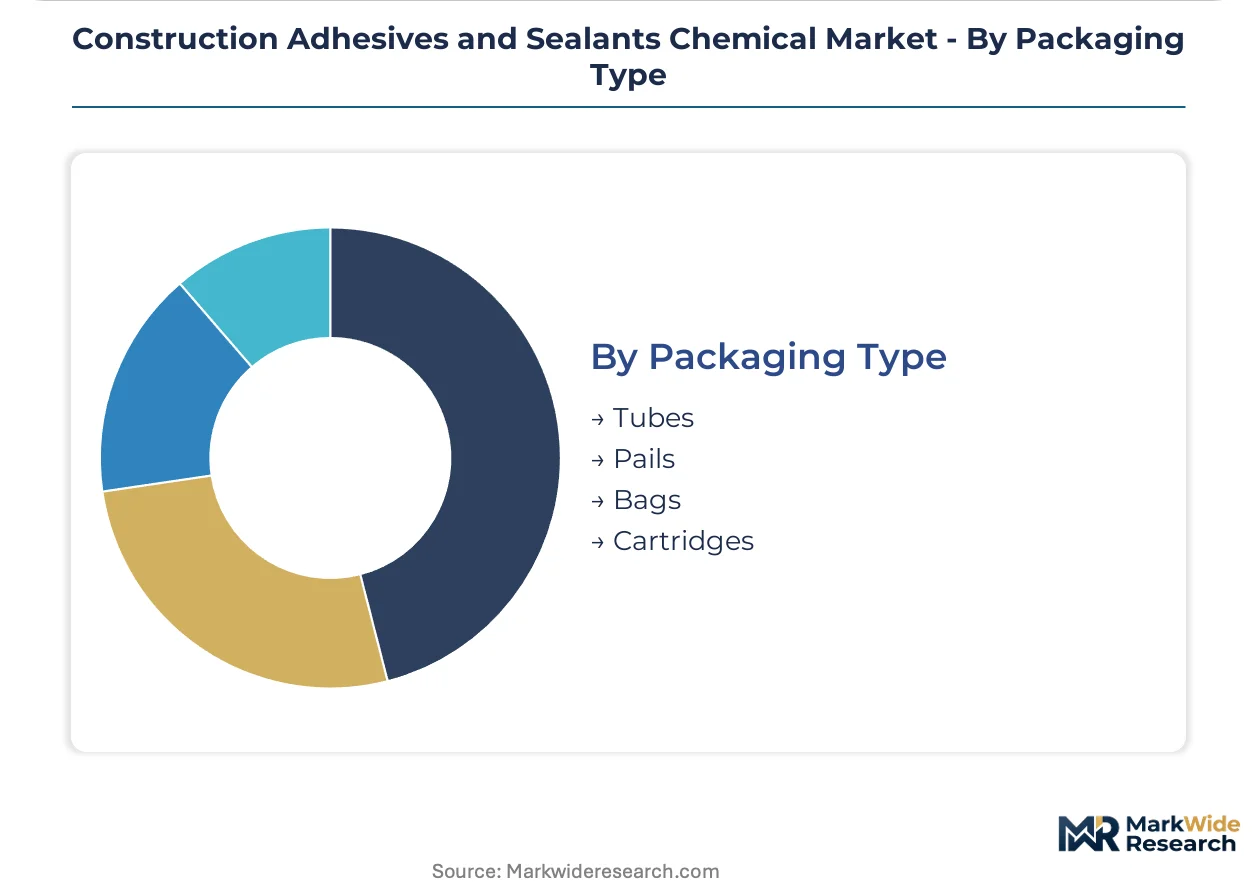
Cartridges hold the largest share; pail formats are expanding most quickly as commercial project scale increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal divergent regional positions in construction adhesives and sealants chemicals. China and Germany maintain net export surpluses in polyurethane intermediates and silicone polymers, while India and the United States absorb significant import volumes to bridge domestic formulation gaps.
China
High-speed rail expansion and urban renewal programs in Shanghai and Guangzhou consume industrial-scale volumes of polyurethane and silicone sealants. GB standards for construction chemicals mandate VOC limits that align with EU Green Deal benchmarks, accelerating reformulation investments. The Yangtze River Delta cluster concentrates domestic silicone polymer production, with Wacker Chemie and local producers expanding silane capacity in Zhangjiagang.
United States
Residential envelope upgrades and commercial curtain wall retrofits drive specification shifts toward low-VOC polyurethane systems. EPA regulations under 40 CFR Part 59 tighten architectural sealant emissions limits, while OSHA exposure rules for isocyanates restrict spray application methods. The Southeast construction corridor spanning Florida and Georgia anchors demand concentration, with Atlanta and Miami metro areas consuming bulk adhesive volumes for multifamily housing.
Germany
Facade sealing and infrastructure joint specifications favor 50-year service life silicone systems in Berlin and Munich commercial projects. REACH authorization timelines for substances of very high concern force tin catalyst and phthalate plasticizer phase-outs, advantaging integrated producers with captive polymer synthesis. The Rhine-Ruhr industrial belt hosts formulation R&D concentration, with Leverkusen and Ludwigshafen chemical parks supplying epoxy and polyurethane intermediates downstream.
India
Metro rail expansion in Delhi, Mumbai, and Bangalore creates specification entry points for hybrid sealant technologies. The PLI scheme for construction chemicals offers production-linked incentives that attract joint venture investments from European formulators. Gujarat's chemical manufacturing cluster in Vadodara and Vapi is expanding silane and specialty monomer capacity to reduce import dependence for sealant raw materials.
Japan
Seismic-resistant structural bonding specifications in Tokyo and Osaka commercial towers demand high-performance epoxy and modified silicone systems. METI carbon neutrality roadmaps pressure building material suppliers toward Environmental Product Declaration compliance for public procurement eligibility. The Kansai region's Osaka-Kobe manufacturing corridor maintains formulation expertise concentration, with Nagoya-area chemical producers supplying acrylic emulsion intermediates for interior finishing applications.
Construction Adhesives and Sealants Chemical Market Competitive Environment
Concentration sits with integrated resin producers possessing captive polymer synthesis capabilities. Three to five multinational chemical groups control bulk silicone polymer and isocyanate supply, creating tiered access for formulation specialists downstream. Strategic archetypes separate backward-integrated resin producers from formulation-only competitors and hybrid technology specialists. Dominant competitive moves include pan-European logistics consolidation and waterborne formulation capability acquisitions.
Among European-integrated chemical groups, Henkel AG & Co. KGaA, Sika AG, and BASF SE exemplify divergent vertical positioning. Henkel leverages captive epoxy and polyurethane resin production to control raw material quality positions in commercial construction. Sika anchors its market presence through in-house silicone polymer manufacturing, sustaining margin structures that formulation competitors cannot replicate. BASF extends its commodity chemical base into tailored adhesive systems for infrastructure applications, competing from the upstream direction against specialty formulators.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| 3M |
| H.B. Fuller Company |
| Arkema |
| Dow Inc. |
| BASF SE |
| Wacker Chemie AG |
| Mapei SpA |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day silane inventory cycles at European formulators concentrate pricing power with integrated silicone polymer producers in Germany and China, compressing margins for specification houses lacking backward integration into feedstock synthesis. This lead-time band tightens further when REACH authorization deadlines for tin catalysts force emergency sourcing from qualified suppliers, amplifying cost pass-through to infrastructure contractors.
Pricing Analysis
Configured-to-order pricing for project-specific hybrid sealants commands spreads exceeding standard cartridge formulations, reflecting formulation chemist labor and accelerated EPD documentation. Pricing stratifies across premium architectural certification tiers, standard commercial grades, and economy residential cartridges, with differentiation anchored in LEED compliance depth and declared service life guarantees. Cost compression in standard polyurethane tiers is intensifying because MDI and propylene oxide volatility transfers directly to spot-contracted formulators. Residential contractors exhibit highest price sensitivity, while infrastructure procurement teams prioritize 50-year performance warranties over unit economics.
Supply Chain Analysis
Strait of Malacca transit risk concentrates silane monomer flows from Zhangjiagang and Singapore, exposing sealant formulators to logistics disruption during peak construction seasons. Supply concentrates in China, Germany, and the United States for polyurethane intermediates, silicone polymers, and epoxy resins respectively, with raw material sourcing drawing from propylene oxide, methylenediphenyl diisocyanate, and silane feedstocks. Single-source vulnerability concentrates in silane catalyst supply, where three producers control global merchant volume. Distribution runs through pan-European logistics platforms serving consolidated general contractors, displacing regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and applicator training programs represent faster-expanding revenue layers than base chemical sales, as Skanska and Vinci centralize procurement around formulation partners offering certified installation support.
For Market Incumbents: Secure captive silane polymer capacity or long-term offtake agreements with Yangtze River Delta producers before REACH sunset dates eliminate qualified catalyst suppliers. Defend specification position by embedding EPD documentation services into standard product offerings, neutralizing smaller competitors lacking dedicated regulatory affairs teams. For New Entrants and Emerging Players: Technical service gaps in hybrid sealant application training for Indian metro rail contractors create entry points where European incumbents under-invest in field support. Target Gujarat's expanding chemical manufacturing cluster through joint ventures with local silane producers, leveraging PLI scheme incentives to offset capital requirements. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because formulation chemist scarcity concentrates among senior technical staff at established players, making specialist acquisition the primary capacity expansion route. Watch hybrid technology patent filings as the inflection signal indicating which integrated producers are capturing silane-terminated polyurethane architecture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Monomers | Captive supply from Zhangjiagang or Leverkusen insulates margin pools from merchant market volatility. |
| Environmental Product Declaration Investment | Third-party-validated documentation qualifies formulations for German and French public infrastructure tenders. |
| Hybrid Technology Licensing | Silane-terminated polyurethane patents capture specification share in Japanese rail and German facade applications. |
| Pan-European Logistics Consolidation | Harmonized distribution platforms align with Skanska and Vinci centralized procurement authority. |
| Waterborne Formulation Acquisition | Emulsion polymerization capabilities fill capability gaps for solvent-borne specialists facing EU Green Deal phase-outs. |
Study Parameters
A spread of perspectives from plant managers at integrated resin producers, procurement leads at downstream general contractors, distribution channel partners, and technical R&D directors converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined with secondary validation from customs and trade data, Cefic construction chemical reports, SEC 10-K disclosures, and GB standards documentation. Bottom-up formulation demand modeling and top-down chemical consumption triangulation anchored the analytical framework.
Segmentation dimensions modeled include polymer chemistry tier, end-use application intensity, packaging format scale, and regional production hub concentration across the projection horizon. CAGRs derived from installed base replacement cycles and specification upgrade velocities, with inputs from high-speed rail construction schedules and green building code adoption trajectories.
Underlying assumptions cover REACH authorization timelines and VOC limit enforcement intensity, with deviation risk concentrated in isocyanate regulatory friction and silane supply concentration. Practitioners should keep alternative scenarios live as EU Green Deal procurement rules and China's dual carbon policy implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Global Bone Cement and Glue Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Removable Adhesive Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Australia Adhesives Market