
 Global Butyl Acrylate Market | 2026-2036
Global Butyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Butyl Acrylate Market Foresight
Modular formulation services is decoupling bulk butyl acrylate procurement from technical support contracts, letting mid-size buyers mix standard and specialty grades without long-term supply agreements. BASF SE leverages its integrated acrylic acid chain to sustain margin control across European coating hubs. Dow Inc. anchors North American supply through its Gulf Coast manufacturing complex. Wanhua Chemical competes on scale in Asia-Pacific emulsion markets.
Butyl acrylate is an acrylic ester monomer with a molecular formula C7H12O2, produced through esterification of acrylic acid with n-butanol, serving primarily as a softening co-monomer in emulsion polymers for pressure-sensitive adhesives and architectural coatings. Standard butyl acrylate occupies the volume core of the product type structure due to its cost position in water-based paint formulations. Paints and coatings applications command the deepest margin pools where performance specifications for weather resistance and gloss retention justify premium grade substitution.
REACH registration requirements in Europe and EPA toxic substance reporting in the United States constrain monomer purity thresholds and emission profiles at production facilities. China's MEE enforces wastewater discharge standards that elevate capital costs for emulsion polymerization plants. Stakeholders must monitor regulatory divergence between jurisdictions to align product certification investments with regional demand corridors.
Market Dynamics
Water-based adhesive formulations are displacing solvent-borne systems across packaging and automotive applications, tightening purity specifications for butyl acrylate monomers and compressing formulation service margins.
Growth Catalysts
- REACH compliance deadlines:European formulators accelerate emulsion polymerization upgrades to meet 2027 registration thresholds, pulling technical-grade butyl acrylate into coating hubs in Germany and the Netherlands.
- Pressure-sensitive adhesive demand:E-commerce logistics in India and Southeast Asia consume tape and label stock at rates exceeding domestic acrylic ester capacity, opening import corridors for standard-grade material.
- Automotive lightweighting:Structural bonding applications in electric vehicle battery module assembly specify low-VOC acrylic adhesives, routing specialty butyl acrylate grades into tier-one supplier networks.
Market Restraints
- Acrylic acid feedstock volatility:Propylene oxidation unit outages at naphtha crackers in the US Gulf Coast transmit price spikes directly to butyl acrylate contract structures.
- Supply concentration in China:Wanhua Chemical and satellite producers control 60% of Asia-Pacific emulsion-grade capacity, exposing buyers to export quota unpredictability during environmental inspection cycles.
- 2-Ethylhexyl acrylate substitution:Higher Tg monomers displace butyl acrylate in exterior architectural coatings where glass transition temperature requirements exceed -40°C.
Strategic Opportunities
- India construction chemicals:National infrastructure spending on affordable housing and metro rail expansion creates unserved demand for water-based sealants and waterproofing membranes.
- Bio-based acrylic acid pathways:Fermentation-derived acrylic acid from sugar feedstocks, validated under EU Green Deal criteria, offers margin differentiation for specialty butyl acrylate positioned toward premium coating brands.
- Modular toll manufacturing:Regional emulsion polymerizers in Poland and Mexico now offer batch-scale formulation services, letting mid-size buyers bypass minimum order quantities from integrated producers.
Industry Challenges
- Emulsion polymerization process control:Temperature excursion risks during semi-batch operations require specialized reactor engineering talent scarce outside legacy acrylics manufacturing clusters.
- MEE wastewater discharge compliance:Chinese provincial environmental bureaus impose real-time monitoring requirements that extend commissioning timelines for new polymerization plants by 8-14 months.
- Cross-border REACH dossier harmonization:Divergent substance evaluation protocols between ECHA and China's MEE force dual registration investments for suppliers serving both jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Butyl Acrylate Market |
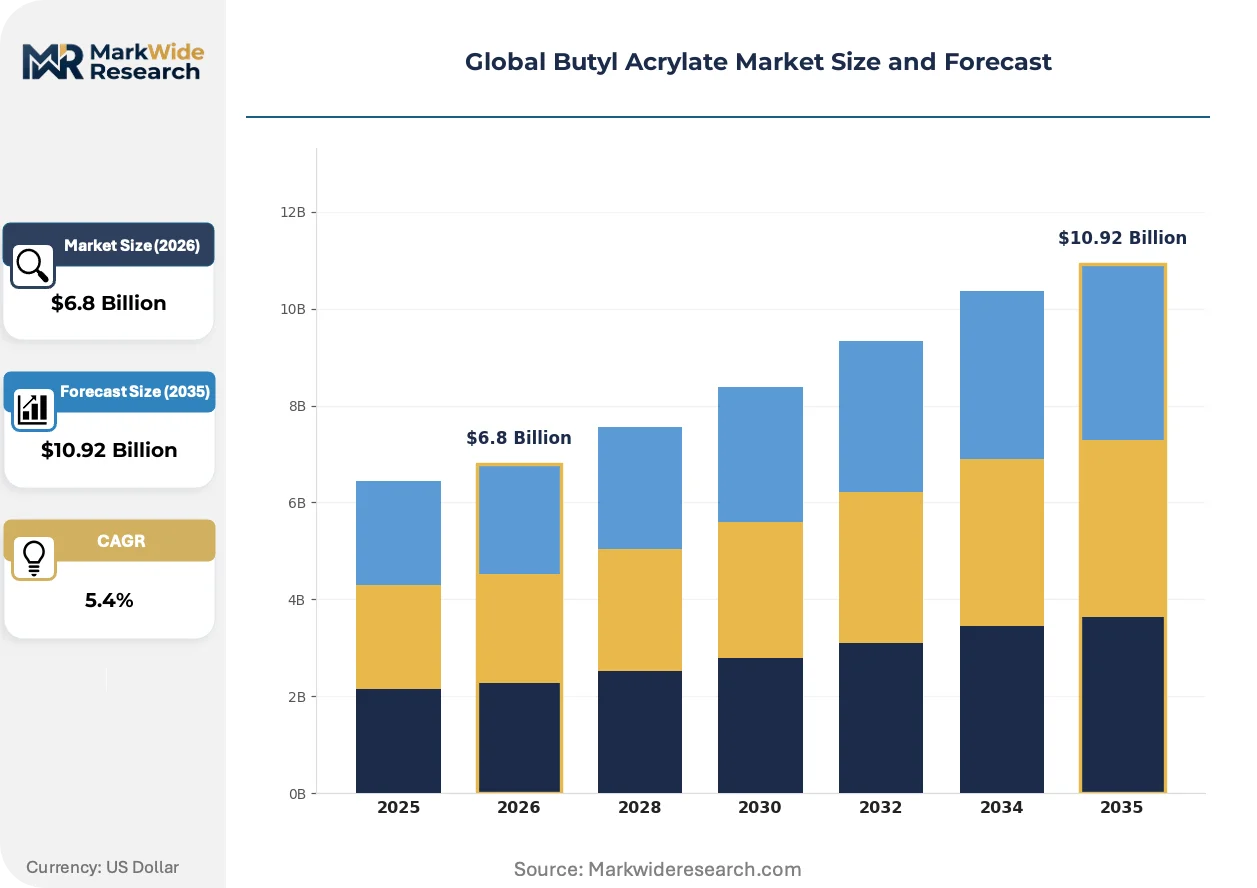
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Butyl Acrylate, Hydroxy Butyl Acrylate, Carboxyl Butyl Acrylate, Specialty Butyl Acrylate, Modified Butyl Acrylate Application: Adhesives & Sealants, Paints & Coatings, Textile Finishing, Leather Finishing, Printing Inks End Use Industry: Construction, Automotive Suppliers, Packaging Manufacturers, Textile Processing, Paper & Board Production Form: Emulsion, Solution, Powder, Bulk Liquid |
| Companies Covered | Nippon Shokubai Co., Ltd., Mitsubishi Chemical, BASF SE, Wanhua Chemical, Evonik Industries AG, Arkema S.A., LG Chem Ltd., Formosa Plastics Corporation, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Butyl Acrylate Market Shifts & Advancements
Acrylic ester chemistry is bifurcating into commodity-scale emulsion feedstocks and performance-tuned specialty monomers, with digital process control and regulatory automation reshaping how specifications propagate through supply chains.
Continuous stirred-tank reactor (CSTR) technology with inline NIR spectroscopy is electrifying batch consistency in butyl acrylate production, enabling real-time molecular weight control during emulsion polymerization. Tier-one adhesive formulators in Germany and Japan are retrofitting legacy semi-batch lines with CSTR skids to reduce off-specification losses. This technology is electrifying margin compression for commodity-grade producers unable to justify comparable automation capex.
China's MEE enforcement of GB 31572-2015 volatile organic compound emission limits is forcing emulsion polymerization plants in Shandong and Jiangsu provinces to install thermal oxidizers and closed-loop solvent recovery systems. Capital costs for compliant reactor trains have risen 25-40% since 2022, accelerating consolidation among mid-scale Chinese butyl acrylate derivative producers. Specialty-grade suppliers with pre-installed abatement infrastructure capture displaced volume from decommissioned regional competitors.
Specification-grade purchasing contracts are fragmenting bulk procurement relationships as automotive OEMs and packaging converters unbundle technical service from monomer supply. Buyers in France and South Korea now source standard butyl acrylate through commodity traders while retaining formulation consultants for application-specific emulsion design. This pattern concentrates in automotive adhesive supply chains where just-in-time delivery requirements conflict with integrated producer minimum order structures.
Global Butyl Acrylate Market Segmentation
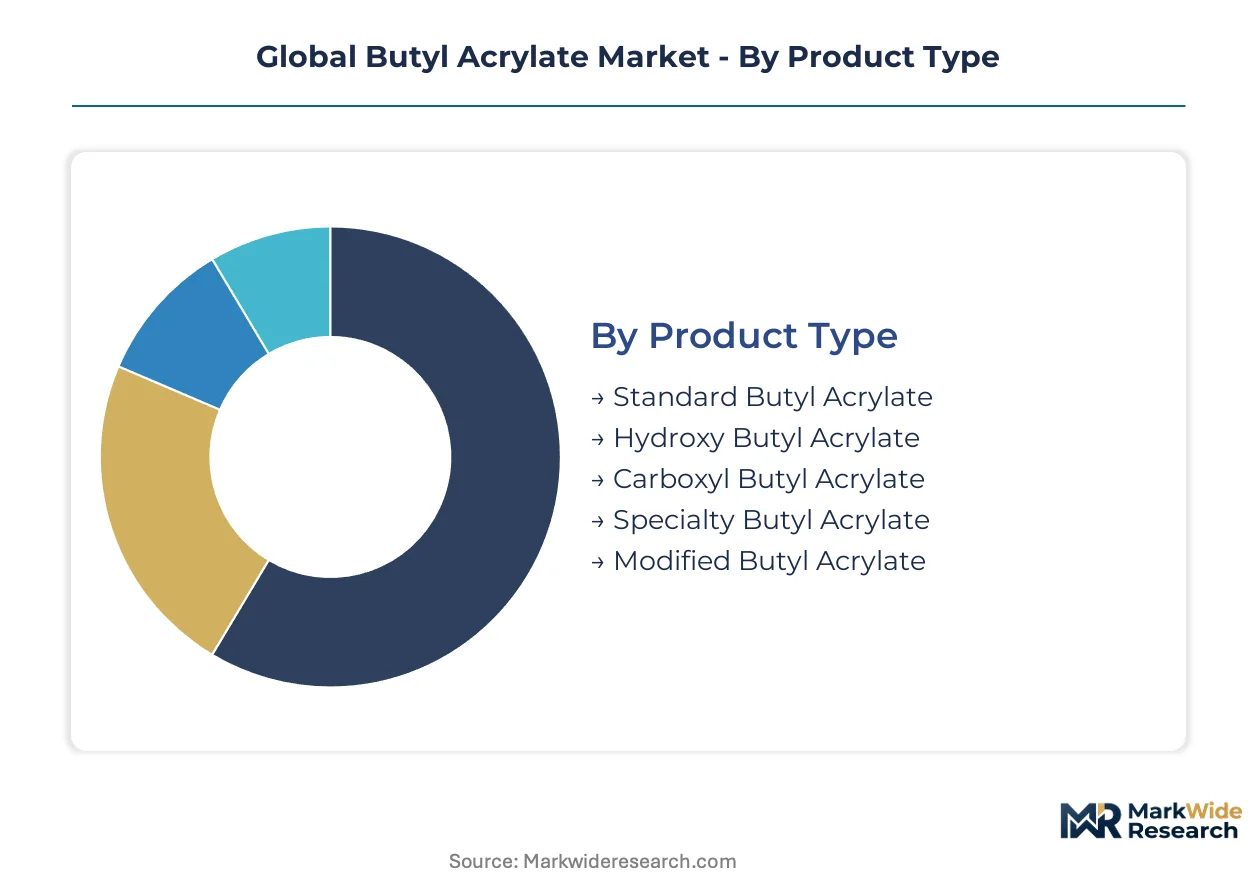
Butyl acrylate specifications diverge sharply between commodity emulsion feedstocks and performance-tuned specialty grades. Procurement patterns now track this split, with bulk buyers separating monomer supply from technical formulation services.
Product Type:
Customization intensity varies from off-the-shelf commodity esters to engineered monomers with functional side chains, reshaping how buyers match grade selection to end-use performance thresholds.
- Standard Butyl Acrylate:The baseline C7H12O2 ester produced through acrylic acid esterification with n-butanol, serving as the primary softening co-monomer in water-based pressure-sensitive adhesives. Demand concentrates in China's packaging tape manufacturing clusters where e-commerce logistics expansion outpaces domestic acrylic ester capacity, pulling import volumes through Shanghai and Ningbo ports.
- Specialty Butyl Acrylate:Purified grades with controlled impurity profiles and narrow molecular weight distribution for automotive adhesive specifications requiring low-VOC compliance. German tier-one suppliers specify these grades for electric vehicle battery module bonding applications where REACH registration thresholds and OEM warranty terms justify premium positioning over standard material.
- Hydroxy Butyl Acrylate:Functional monomer incorporating hydroxyl groups for crosslinkable coating systems.
- Carboxyl Butyl Acrylate:Acid-functional variant enabling improved substrate adhesion in primer formulations.
- Modified Butyl Acrylate:Custom-derivatized grades for niche performance specifications in industrial coatings.
Most installed capacity flows through Standard Butyl Acrylate. Expansion is steepest in Specialty Butyl Acrylate.
Application:
Formulation complexity escalates from simple bulk emulsions to multi-component systems with precise rheology control, concentrating margin capture in segments with specification-grade purchasing.
- Paints & Coatings:Architectural and industrial formulations consuming butyl acrylate as the primary film-forming co-monomer for weather resistance and gloss retention. Demand clusters in Germany and the Netherlands where REACH compliance deadlines accelerate emulsion polymerization upgrades, routing technical-grade material into coating hubs serving Western European construction recovery.
- Adhesives & Sealants:Pressure-sensitive tape, label stock, and structural bonding systems specifying butyl acrylate for tack and peel strength. India's e-commerce logistics sector consumes these materials at rates exceeding domestic acrylic ester capacity, opening import corridors for standard-grade monomer from Middle Eastern and Southeast Asian producers.
- Textile Finishing:Fabric softening and hand-modification treatments in apparel manufacturing.
- Leather Finishing:Coating binders for upholstery and automotive interior applications.
- Printing Inks:Flexographic and gravure formulations requiring specific viscosity profiles.
Volume leadership sits with Paints & Coatings. Value expansion runs fastest in Adhesives & Sealants.
End Use Industry:
Customer scale ranges from multinational OEMs with captive formulation capabilities to regional processors dependent on toll manufacturing services.
- Construction:Waterproofing membranes, sealants, and architectural coatings for residential and commercial building. India's national infrastructure spending on affordable housing and metro rail expansion creates unserved demand for water-based sealants, with procurement concentrating in Mumbai, Delhi, and Bangalore construction chemical distribution networks.
- Automotive Suppliers:Tier-one and tier-two manufacturers of interior trim, structural adhesives, and battery module assemblies. Specifications for electric vehicle lightweighting specify low-VOC acrylic adhesives, routing specialty butyl acrylate grades into supplier networks serving German and Japanese OEM production platforms.
- Packaging Manufacturers:Corrugated box sealing, flexible film lamination, and label stock production.
- Textile Processing:Fabric finishing mills in Bangladesh and Vietnam apparel supply chains.
- Paper & Board Production:Surface sizing and coating binders for packaging grades.
Construction commands the deepest volume pools. Automotive Suppliers show the steepest specification upgrade trajectory.
Form:
Physical state determines logistics economics and formulation integration methods, with emulsion dominance reflecting water-based chemistry trends.
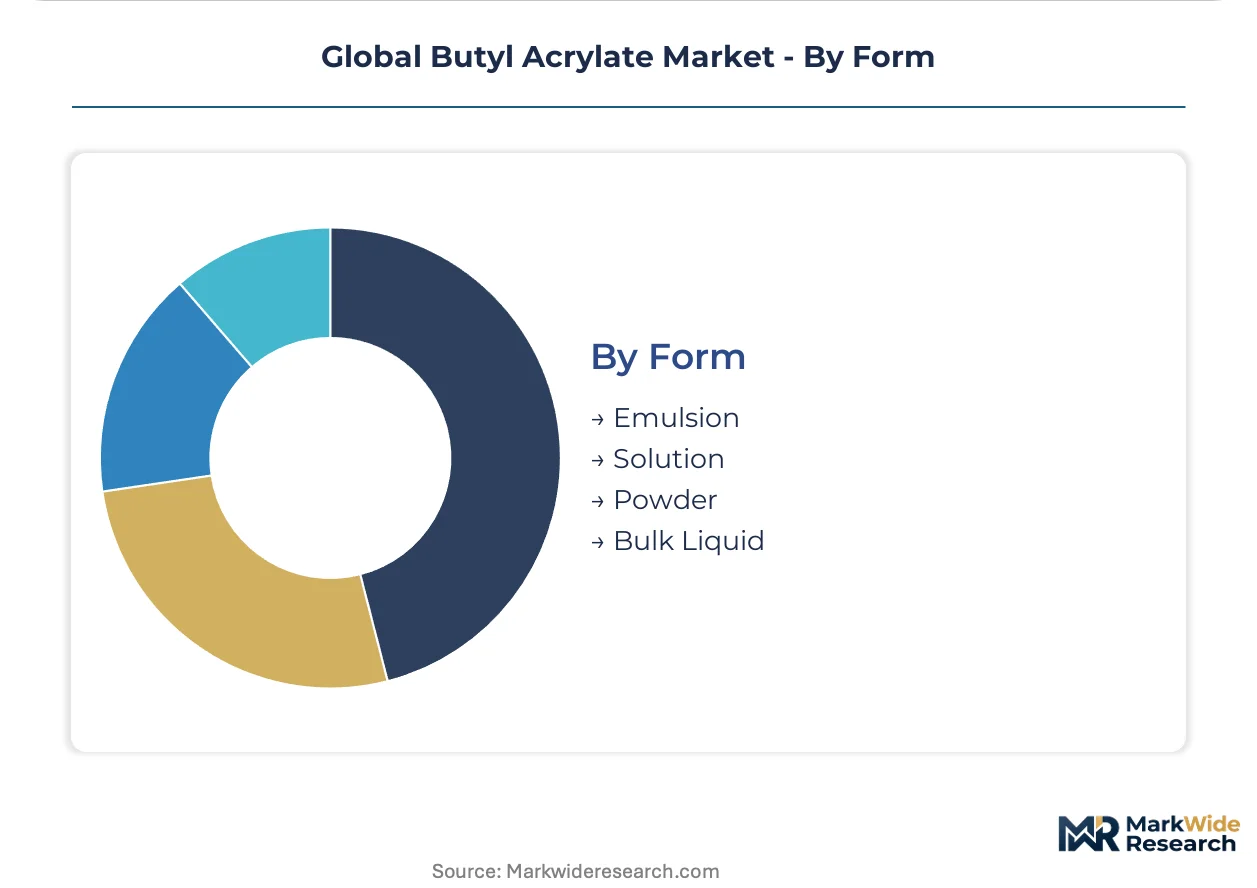
- Emulsion:Pre-polymerized aqueous dispersions ready for direct formulation integration. China's MEE enforcement of GB 31572-2015 VOC emission limits forces Shandong and Jiangsu polymerization plants to install thermal oxidizers, raising capital costs and accelerating consolidation among mid-scale derivative producers.
- Bulk Liquid:Unpolymerized monomer shipped in tank containers for captive emulsion production. Regional polymerizers in Poland and Mexico now offer batch-scale toll manufacturing, letting mid-size buyers bypass minimum order quantities from integrated producers while retaining formulation flexibility.
- Solution:Solvent-borne systems for specialty coating applications.
- Powder:Spray-dried emulsions for dry-mix construction chemical integration.
Emulsion carries the bulk of current throughput. Bulk Liquid is gaining share fastest among buyers with in-house polymerization capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Butyl acrylate production scaled first in Germany and the United States during the 1960s acrylics expansion, establishing the technical standards and purification protocols that now govern global trade. Today, manufacturing clusters span three continents with regulatory divergence shaping regional competitive dynamics.
China
E-commerce logistics in Zhejiang and Jiangsu provinces consume pressure-sensitive adhesive tape at rates exceeding domestic acrylic ester capacity. China's MEE enforces GB 31572-2015 VOC emission limits that force Shandong polymerization plants to install thermal oxidizers. Qingdao and Ningbo port complexes route standard-grade butyl acrylate imports to packaging manufacturers serving Southeast Asian export markets.
Germany
Automotive tier-one suppliers in Stuttgart and Munich specify low-VOC acrylic adhesives for electric vehicle battery module bonding. REACH registration deadlines through 2027 accelerate emulsion polymerization upgrades across North Rhine-Westphalia. The Ludwigshafen chemical cluster anchors coating formulation hubs serving Western European construction recovery.
United States
Pressure-sensitive label stock producers in Ohio and Wisconsin drive consumption of technical-grade monomer for logistics applications. EPA toxic substance reporting constrains purity thresholds and emission profiles at Gulf Coast production facilities. The Texas-Louisiana petrochemical corridor transmits propylene oxidation price volatility directly to butyl acrylate contract structures.
India
National infrastructure spending on affordable housing and metro rail expansion in Mumbai and Delhi creates unserved demand for water-based sealants. BIS certification requirements for construction chemicals elevate quality barriers for imported emulsion formulations. Bangalore construction chemical distribution networks concentrate procurement for waterproofing membrane applications.
Japan
Automotive interior trim manufacturers in Aichi Prefecture specify specialty grades with narrow molecular weight distribution for structural bonding. METI chemical substance management frameworks align with REACH-equivalent purity standards for export-qualified production. The Osaka-Kobe industrial zone maintains legacy acrylics manufacturing expertise for semi-batch reactor operations.
Global Butyl Acrylate Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical conglomerates with captive acrylic acid supply. BASF SE and Dow Inc. anchor the premium tier through backward integration into propylene oxidation, while Asian producers compete on emulsion-grade scale. Three archetypes dominate: integrated chemical majors with full acrylic acid chains, regional emulsion specialists with toll manufacturing flexibility, and packaging-focused derivative producers in high-growth logistics corridors. Capacity expansion and modular formulation partnerships constitute the dominant competitive moves.
Among German-based chemical majors, BASF SE and Evonik Industries AG occupy positions anchored by Ludwigshafen and Marl production complexes. Wanhua Chemical represents the scale-driven archetype with Asia-Pacific emulsion market penetration. Dow Inc. exemplifies Gulf Coast-integrated supply security for North American coating and adhesive formulators. These three companies illustrate how geographic production clustering aligns with regional regulatory compliance investments.
| Leading Market Players |
|---|
| Nippon Shokubai Co., Ltd. |
| Mitsubishi Chemical |
| BASF SE |
| Wanhua Chemical |
| Evonik Industries AG |
| Arkema S.A. |
| LG Chem Ltd. |
| Formosa Plastics Corporation |
| Dow Inc. |
| Others |
Supply & Pricing Matrix
Propylene oxidation feedstock costs transmit directly from Gulf Coast naphtha crackers through acrylic acid intermediates to butyl acrylate contract structures, stratifying end-prices across premium REACH-registered specialty grades, standard technical grades for packaging adhesives, and economy emulsion feedstocks serving Asian tape manufacturers.
Pricing Analysis
Contract-based long-term offtake dominates procurement relationships for integrated producers serving automotive adhesive formulators, while spot-market transactions concentrate among packaging tape manufacturers in China and India. Price differentiation hinges on REACH registration status and volume scale, with German tier-one suppliers least sensitive due to OEM warranty compliance requirements. Cost compression in standard-grade material is intensifying because Wanhua Chemical and satellite producers control sixty percent of Asia-Pacific emulsion-grade capacity, exposing buyers to export quota unpredictability.
Supply Chain Analysis
Specialized reactor engineering talent for semi-batch emulsion polymerization operations concentrates in legacy acrylics manufacturing clusters around Ludwigshafen, Houston, and Osaka-Kobe, constraining rapid capacity expansion outside these geographies. Manufacturing concentrates in China, Germany, and the United States, with acrylic acid feedstock drawing from propylene oxidation units tethered to regional petrochemical corridors. Single-source vulnerability runs through Chinese environmental inspection cycles that trigger export quota unpredictability. Distribution runs through integrated chemical majors with captive supply chains and regional toll manufacturers offering batch-scale flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH registration deadlines through 2027 accelerate emulsion polymerization upgrades across European coating hubs, pulling technical-grade butyl acrylate into formulation networks serving German and Dutch construction recovery.
For Market Incumbents: Deepen backward integration into propylene oxidation to insulate margin structures from feedstock volatility transmitted through Gulf Coast naphtha cracker outages. Expand specialty-grade capacity in Ludwigshafen and Marl production complexes to capture specification upgrade premiums from electric vehicle battery module bonding applications, defending against 2-ethylhexyl acrylate substitution in exterior architectural coatings. For New Entrants and Emerging Players: Launch via modular toll manufacturing partnerships in Poland and Mexico to bypass minimum order quantities from integrated producers while serving mid-size buyers with batch-scale formulation flexibility. Target India's construction chemicals sector where national infrastructure spending on affordable housing and metro rail expansion creates unserved demand for water-based sealants and waterproofing membranes. For Investors and Strategic Acquirers: Consolidation pressure builds where Chinese MEE wastewater discharge compliance has extended commissioning timelines for new polymerization plants by eight to fourteen months, stranding mid-scale derivative producers without pre-installed abatement infrastructure. Acquisition candidates include regional emulsion specialists with toll manufacturing flexibility and REACH-registered specialty-grade capabilities. Monitor divergence between ECHA and China's MEE substance evaluation protocols as an inflection indicator for dual registration investment burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acrylic acid production insulates BASF and Dow from propylene oxidation price spikes at Gulf Coast crackers. |
| Green Manufacturing Transition | Fermentation-derived acrylic acid from sugar feedstocks validated under EU Green Deal criteria offers margin differentiation for specialty grades. |
| Capacity Expansion | Wanhua Chemical leverages scale position in Asia-Pacific emulsion markets to serve e-commerce logistics growth in Zhejiang and Jiangsu. |
| Long-term Supply Agreement | Automotive tier-one suppliers in Stuttgart and Munich lock in low-VOC acrylic adhesive specifications for electric vehicle platforms. |
| Joint Venture | Regional polymerizers in Poland and Mexico partner with mid-size buyers to offer batch-scale formulation services bypassing MOQ constraints. |
Research Methodology
Direct dialogue with plant managers at emulsion polymerization facilities, procurement leads at downstream automotive and packaging OEMs, distribution channel partners in European coating hubs, and technical R&D directors at adhesive formulators grounded qualitative assessments. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical majors, and ECHA REACH registration databases. Bottom-up capacity and consumption estimates triangulated against top-down macroeconomic drivers across the analysis window.
Segment-level outputs across the projection horizon reflect modeled dimensions including grade tier (standard versus specialty versus hydroxy-functional), end-use industry (construction, automotive suppliers, packaging manufacturers), packaging format (bulk liquid, emulsion, powder), and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive lightweighting penetration rates and e-commerce logistics expansion trajectories. Forecast inputs included REACH registration compliance timelines and Chinese MEE environmental inspection cycle intensity.
Several conditions sit outside the modeled scope, including unforeseen propylene oxidation unit outages, abrupt shifts in Chinese export quota administration, and accelerated 2-ethylhexyl acrylate substitution in coating formulations. Forecasts reflect assumptions about regulatory enforcement continuity and feedstock price volatility ranges. Material deviation in REACH dossier harmonization progress or MEE inspection cycle severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Dicyanamide Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
Sodium Tungstate Dihydrate Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Calcium Carbonate Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Triazine Market
Bulk Chemicals
Sodium Molybdate Market