
 Construction Bolts Market | 2026-2036
Construction Bolts Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Bolts Market Analytics
The capital-intensity divergence between integrated fastener producers and regional distributors is unwinding competitive stability in the construction bolts sector. Hilti Corporation leverages its captive manufacturing of alloy-grade structural anchors to sustain premium positioning across European infrastructure tenders. Adolf Würth GmbH & Co. KG anchors its volume base through dense distributor networks serving German residential builders. Bossard Holding AG differentiates via digital inventory management systems that control just-in-time delivery for industrial contractors.
Construction bolts are threaded mechanical fasteners manufactured to specified tensile strengths, typically formed through cold forging or hot forging of carbon steel and alloy blanks, then heat-treated to achieve grade-marked performance classes for load-bearing structural connections. Anchor bolts dominate commercial infrastructure applications where seismic-rated embedment secures steel columns to concrete foundations. Stainless steel material grades command durable margin pools in coastal and chemical-exposed environments, while galvanized coating types retain volume leadership across standard building applications due to cost-effective corrosion protection.
The European Committee for Standardization enforces EN 15048 and EN 14399 for structural bolting assemblies, compelling manufacturers to maintain batch traceability and mechanical testing documentation for CE marking compliance. India's Bureau of Indian Standards mandates IS 3757 and IS 6623 for high-strength structural bolts used in bridge and power transmission projects, creating certification barriers for uncertified imports. Stakeholders must monitor evolving carbon-border adjustment mechanisms and domestic content incentives that are restructuring supplier qualification criteria across major procurement channels.
Market Dynamics
Carbon-border adjustment mechanisms are restructuring supplier qualification criteria across major procurement channels for structural bolting assemblies. Manufacturers must now document embodied carbon in alloy-grade production to retain access to European infrastructure tenders and Indian industrial corridor contracts.
Growth Catalysts
- EN 15048 traceability mandates:European structural bolting standards now require batch-level mechanical testing documentation, compelling contractors to source exclusively from CE-marked suppliers with certified heat-treatment records.
- Seismic-rated embedment demand:Southeast Asian infrastructure megaprojects specify premium-grade anchor bolts for steel-to-concrete column connections in high-rise commercial developments.
- Stainless steel coastal specifications:Chemical-exposed environments and marine construction sites in India's industrial corridors are specifying 316-grade material for durable corrosion resistance.
Market Restraints
- Alloy steel input volatility:Nickel and chromium price swings directly compress margins on heat-treated high-strength grades specified for bridge and power transmission projects.
- Certification timeline friction:India's BIS IS 3757 and IS 6623 approval processes for high-strength structural bolts create six-to-twelve month barriers for uncertified import suppliers.
- Mechanical fastening substitution:Welded connections and post-installed adhesive anchors are capturing share in secondary structural applications where load requirements permit.
Strategic Opportunities
- Digital inventory integration:Just-in-time delivery platforms for industrial contractors enable distributors to capture value through real-time consumption tracking and automated replenishment.
- Domestic content incentives:India's PLI scheme for specialty steel downstream products rewards local fastener manufacturing with cost-competitive alloy feedstock access.
- Galvanized coating upgrades:Hot-dip and mechanical zinc specifications for standard building applications offer volume-scale margin recovery as coating technology improves.
Industry Challenges
- Heat-treatment skill scarcity:Qualified furnace operators and metallurgical technicians capable of achieving grade-marked performance classes are concentrated among legacy producers.
- Cold forging capex intensity:Multi-station header equipment for large-diameter structural bolts requires seven-figure capital commitments with extended depreciation horizons.
- Legacy ERP integration:Batch traceability systems for EN 15048 compliance must interface with decades-old contractor procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Bolts Market |
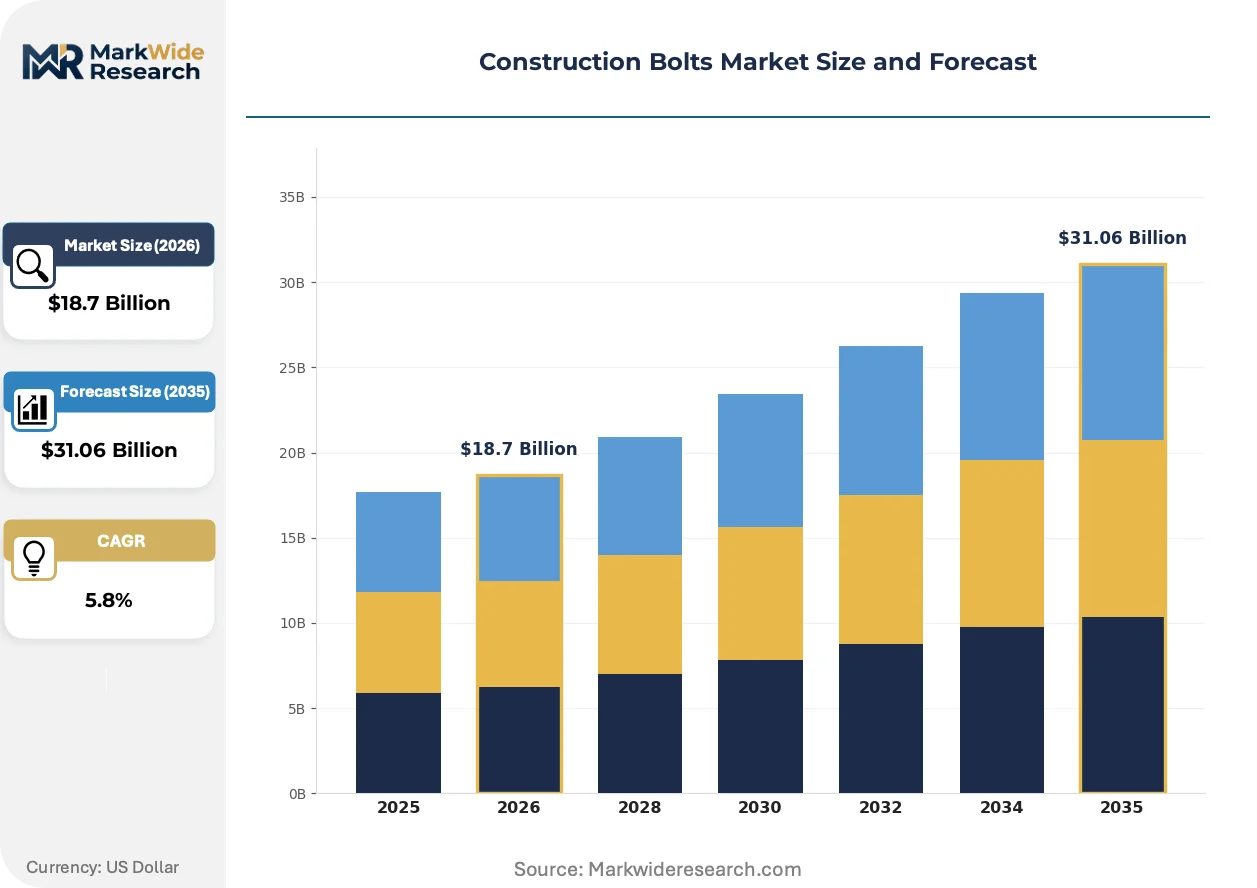
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anchor Bolts, Hex Bolts, Carriage Bolts, Lag Bolts Material: Steel, Stainless Steel, Alloy, Plastic Coating Type: Galvanized, Painted, Uncoated, Zinc Plated Application: Building, Infrastructure, Industrial, Residential |
| Companies Covered | Dokka Fasteners AS, Bossard Holding AG, Hilti Corporation, Birmingham Fastener & Supply, Inc., BACO Enterprises Inc., Illinois Tool Works Inc., Stanley Black & Decker, Inc., EJOT Holding GmbH & Co. KG, Adolf Würth GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Bolts Market Evolving Landscape
Material science advances and digital supply chain tools are compressing traditional procurement cycles while elevating performance specifications for load-bearing connections. Three developments are restructuring competitive requirements.
Additive-manufactured bolt prototypes are fragmenting conventional forging economics for low-volume, geometrically complex anchor configurations. Offshore wind foundation contractors in the North Sea are piloting topology-optimized embedment designs that reduce material mass while maintaining tensile ratings. This technology is fragmenting the historical volume-moat held by cold-forging specialists serving custom infrastructure specifications.
The EU Green Deal's embodied carbon reporting requirements are tightening documentation obligations for structural steel fasteners entering European public works. Manufacturers must now certify cradle-to-gate emissions for alloy-grade production to qualify for infrastructure tenders in Germany, France, and the Netherlands. German general contractors are consolidating supplier panels to pre-qualified domestic producers with verified environmental product declarations.
Consolidated buying consortia among Nordic residential developers are compressing distributor margins through multi-year framework agreements with direct mill sourcing. These procurement pools bypass traditional wholesale channels for standardized galvanized hex bolts in high-rise timber construction. Finland and Sweden now exhibit the most advanced buyer concentration in European residential structural fastening.
Construction Bolts Market Segmentation
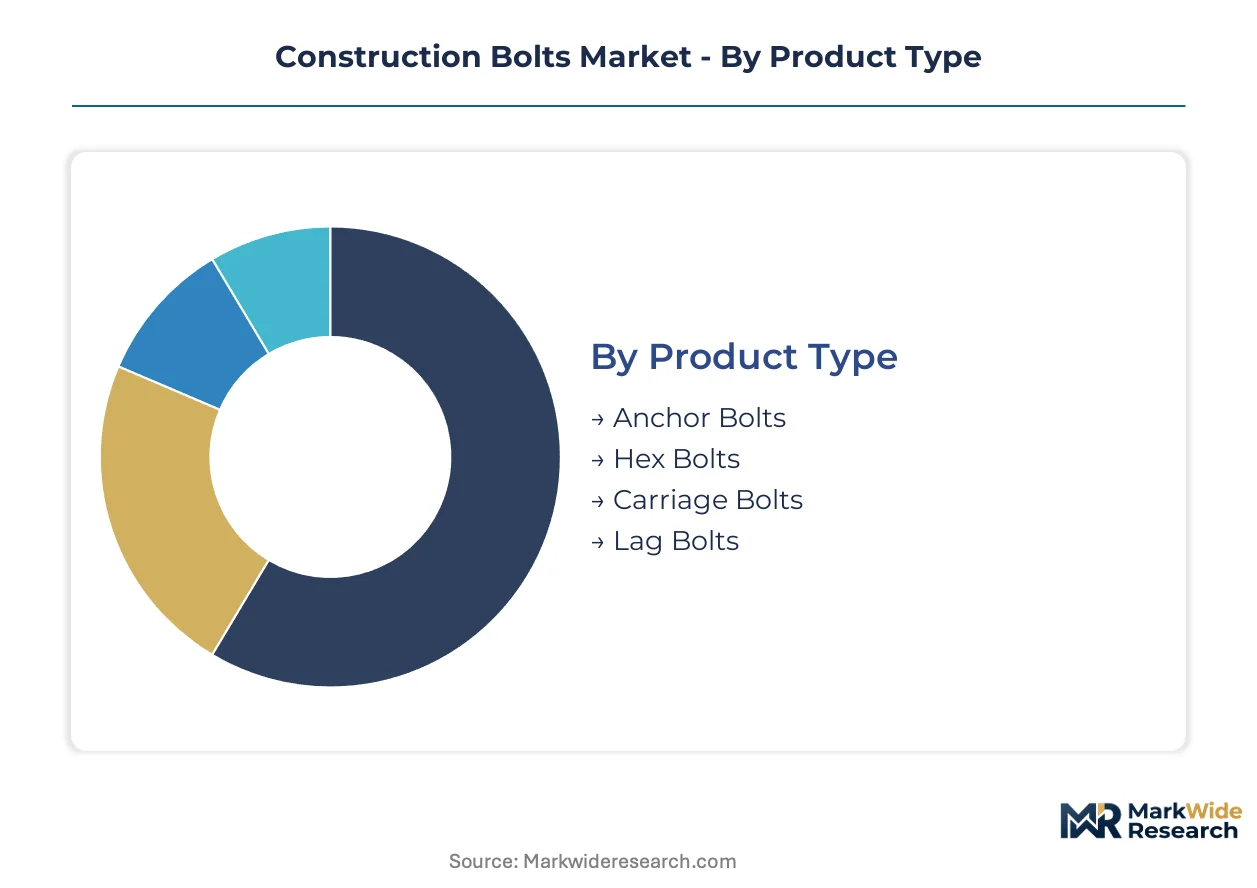
Segmentation in construction bolts reveals how specification requirements fragment procurement channels. Material grades and coating types determine whether orders flow through mill-direct contracts, specialized distributors, or general building supply retailers.
Product Type:
Channel mix varies sharply by product type, with infrastructure-grade anchors commanding direct mill relationships while standardized hex bolts move through wholesale distributors.
- Anchor Bolts:Cast or forged embedment fasteners with threaded extensions for securing structural steel to concrete foundations. Seismic-rated specifications in Southeast Asian commercial towers are absorbing premium-grade production capacity from certified heat-treatment facilities.
- Hex Bolts:Six-sided head fasteners produced through multi-station cold forging for general structural connections. Nordic residential developers are consolidating procurement through direct mill frameworks that bypass traditional wholesale channels for standardized galvanized grades.
- Carriage Bolts:Round-headed fasteners with square necks designed for timber-to-timber connections in exposed architectural applications.
- Lag Bolts:Heavy wood screws with hex heads for structural timber assemblies in residential and light commercial framing.
Anchor bolts dominate installed base in commercial infrastructure. Hex bolts represent the fastest-growing trajectory through consolidated buyer consortia.
Material:
Cost tier stratification separates commodity carbon steel from premium alloy and stainless grades with divergent margin structures.
- Steel:Cold-forged carbon grades dominate volume production for standard building applications. Indian PLI scheme incentives for specialty steel downstream products are reshaping domestic sourcing economics for heat-treated structural grades.
- Stainless Steel:316-grade austenitic alloys specified for marine and chemical-exposed environments. Coastal construction in India's industrial corridors is specifying this material for durable corrosion resistance in foundation embedments.
- Alloy:Heat-treated chromium-nickel grades achieving grade-marked performance classes for bridge and power transmission projects.
- Plastic:Non-metallic fasteners for electrical isolation and lightweight secondary applications in corrosive environments.
Steel commands volume leadership across standard building applications. Stainless steel is where expansion concentrates in coastal and chemical-exposed specifications.
Coating Type:
Application environment dictates coating selection, with protective specifications carrying certification requirements that filter supplier pools.
- Galvanized:Hot-dip zinc coating providing cost-effective corrosion protection for standard outdoor exposure. EN 15048 batch traceability mandates are compelling contractors to source exclusively from CE-marked suppliers with certified coating documentation.
- Painted:Epoxy or polyester coatings for aesthetic integration in exposed architectural steelwork.
- Uncoated:Bare steel for interior dry environments where corrosion risk is negligible and cost minimization dominates.
- Zinc Plated:Electroplated thin-film protection for interior applications requiring moderate corrosion resistance with precise dimensional tolerances.
Galvanized coatings retain installed base leadership across general building applications. Hot-dip specifications are climbing the fastest as coating technology improves durability thresholds.
Application:
Customer type and project scale determine whether procurement flows through distributor networks or direct manufacturer relationships.
- Infrastructure:Bridge, power transmission, and transportation projects requiring certified high-strength grades. India's BIS IS 3757 and IS 6623 certification timelines create six-to-twelve month barriers for uncertified import suppliers.
- Industrial:Manufacturing facility construction with just-in-time delivery requirements. Digital inventory management platforms are capturing value through real-time consumption tracking for industrial contractors.
- Building:Commercial high-rise and institutional construction with seismic-rated specifications.
- Residential:Single-family and multi-family housing with standardized galvanized hex bolt requirements.
Infrastructure applications dominate premium-grade demand. Industrial procurement is gaining share fastest through digital supply chain integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium-grade anchor bolts command 40% pricing spreads in Germany against standard galvanized hex bolts in India, reflecting divergent certification burdens and alloy input access across procurement channels.
United States
Bridge rehabilitation megaprojects and data center construction are absorbing high-strength structural grades. OSHA and AISC standards enforce traceability for seismic-rated connections in California and Pacific Northwest infrastructure. Texas and Gulf Coast industrial corridors concentrate demand for corrosion-resistant specifications in petrochemical facility expansions.
Germany
Offshore wind foundation contractors in the North Sea are piloting topology-optimized embedment designs with reduced material mass. The EU Green Deal's embodied carbon reporting requirements tighten documentation obligations for alloy-grade production entering public works. Bavaria and Baden-Württemberg host the densest concentration of CE-marked heat-treatment facilities serving European tenders.
India
Industrial corridor buildouts across Gujarat and Maharashtra are specifying 316-grade stainless steel for coastal foundation embedments. BIS IS 3757 and IS 6623 certification timelines create six-to-twelve month barriers for uncertified import suppliers. The PLI scheme for specialty steel downstream products rewards domestic fastener manufacturing with cost-competitive alloy feedstock access.
China
Infrastructure stimulus targeting western provinces and high-speed rail extensions sustains volume demand for carbon steel structural grades. GB standards and MIIT regulations govern mechanical performance classes for bridge and power transmission applications. Yangtze River Delta forging clusters supply standardized hex bolts for Belt and Road construction exports.
United Arab Emirates
Expo legacy developments and NEOM construction are specifying premium-grade anchor bolts for steel-to-concrete connections in commercial towers. MOHAP and municipal building codes reference EN 15048 equivalent standards for structural bolting in high-rise applications. Dubai and Abu Dhabi procurement channels favor suppliers with verified environmental product declarations for government tenders.
Construction Bolts Market Competitive Landscape
Concentration sits with integrated fastener producers possessing captive heat-treatment capacity and CE-marking certification infrastructure. The vendor base fragments across regional distributors serving residential builders with standardized galvanized grades. Three archetypes dominate: alloy-grade specialists with metallurgical R&D capabilities, volume distributors leveraging dense logistics networks, and digital-integrated platforms capturing industrial just-in-time contracts. Capacity expansion and certification pre-qualification constitute the dominant competitive moves.
Among European-integrated specialists, Hilti Corporation, Bossard Holding AG, and Adolf Würth GmbH & Co. KG exemplify divergent positioning strategies. Hilti anchors premium-tier positioning through structural anchor manufacturing. Bossard occupies a position within digital inventory management systems for industrial contractor procurement. Würth exemplifies volume-scale distribution density serving German residential construction channels.
| Leading Market Players |
|---|
| Dokka Fasteners AS |
| Bossard Holding AG |
| Hilti Corporation |
| Birmingham Fastener & Supply, Inc. |
| BACO Enterprises Inc. |
| Illinois Tool Works Inc. |
| Stanley Black & Decker, Inc. |
| EJOT Holding GmbH & Co. KG |
| Adolf Würth GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
EN 15048 batch traceability mandates simultaneously gate supplier qualification and enable price differentiation across European infrastructure procurement, forcing contractors to pay premiums for CE-marked documentation or absorb certification delays. This regulatory filter concentrates pricing power among integrated producers with captive heat-treatment capacity while fragmenting margin pools for distributors serving price-sensitive residential channels.
Pricing Analysis
Configured-to-order anchor bolts for seismic-rated infrastructure specifications command substantial premiums over standard galvanized hex bolts moving through wholesale channels. Three-tier pricing structure across premium, standard, and economy levels reflects divergent certification burdens, with alloy-grade heat-treated production capturing durable margins from bridge contractors while commodity carbon grades face compression from Nordic buyer consortia. Price differentiation stems from CE-marking documentation and volume scale, with residential developers exhibiting highest sensitivity and offshore wind contractors least. Cost compression in standardized hex bolts is intensifying because consolidated procurement pools bypass traditional distribution markups.
Supply Chain Analysis
Inventory buffers for EN 15048-compliant heat-treated grades extend lead times beyond commodity carbon steel equivalents, compressing working capital efficiency for distributors serving just-in-time industrial contracts. Supply concentrates in Germany, India, and China, with forging clusters in Bavaria and the Yangtze River Delta feeding distinct certification regimes. Raw material flows draw from nickel-chromium alloy feedstock and hot-rolled carbon steel billets, with coating chemicals sourced from specialized chemical processors. Single-source vulnerability concentrates in qualified furnace operators capable of achieving grade-marked performance classes. Distribution runs through mill-direct frameworks for infrastructure-grade anchors and dense wholesale networks for residential galvanized grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a regulatory entrenchment story. CE-marking certification infrastructure and BIS approval timelines create switching costs that cement incumbent positions while raising barriers for uncertified import suppliers.
For Market Incumbents: Compound defensive positioning by deepening backward integration into alloy feedstock through India's PLI scheme incentives and expanding heat-treatment capacity in CE-marking jurisdictions. Adhesive anchor substitution in secondary structural applications threatens volume in standard grades, making certification moat reinforcement the priority lever against mechanical fastening displacement.
For New Entrants and Emerging Players: Lead with digital inventory platforms targeting industrial contractor procurement in undersupplied Southeast Asian megaproject corridors. India's industrial corridor buildouts present the most penetrable geography given domestic content incentives and BIS certification barriers that favor local production partnerships over import competition.
For Investors and Strategic Acquirers: EU Green Deal embodied carbon reporting requirements reshape the acquisition landscape toward domestic European producers with verified environmental product declarations. Long-term viability centers on specialty fastener manufacturing with metallurgical R&D capabilities rather than commodity distribution. The signal to watch is carbon-border adjustment mechanism implementation scope expanding beyond current pilot programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Capacity Expansion | Captures premium-grade demand from seismic-rated infrastructure specifications in Southeast Asian commercial towers. |
| CE-Marking Certification Investment | Secures access to German, French, and Dutch public works tenders under tightening EN 15048 documentation mandates. |
| Digital Inventory Platform Integration | Enables just-in-time delivery contracts with industrial contractors through real-time consumption tracking systems. |
| Domestic Manufacturing Localization | Qualifies for India's PLI scheme incentives while circumventing BIS IS 3757 certification timeline barriers. |
| Environmental Product Declaration Development | Meets UAE government tender requirements for verified embodied carbon documentation in high-rise construction. |
Research Methodology
Initial hypotheses were tested against primary input from heat-treatment facility operators, procurement managers at infrastructure contractors, fastener distribution channel heads, and metallurgical R&D directors and refined through secondary validation against SEC filings from listed industrial distributors, EN 15048 certification databases, Indian BIS approval registries, and customs trade data for alloy steel fastener imports. Bottom-up volume estimates from product-type and application segmentations were triangulated against top-down macroeconomic indicators for construction activity.
Variance decomposition across material grade, coating type, end-use application, and regional regulatory cluster informed the analytical framework. CAGRs were derived from segment-level growth trajectories weighted by base-year value shares, with inputs including infrastructure project pipeline databases, residential construction permit flows, and industrial facility investment announcements. Price elasticity assumptions reflected documented buyer behavior from consolidated procurement consortia and distributor margin disclosures.
Forecasts assume regulatory continuity in EN 15048, BIS IS 3757, and OSHA/AISC traceability regimes; material policy shifts would require re-modeling. Alloy input price volatility and mechanical fastening substitution rates constitute specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Europe Ready-Mix Concrete Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Building Acoustic Insulation Market