
 Absorption Chillers Market | 2026-2036
Absorption Chillers Market Size, Share, and Industry Trends Forecast 2026-2036
Absorption Chillers Market Analysis
ASHRAE Standard 90.1 compliance is redrawing competitive access for absorption chiller suppliers bidding on North American institutional and commercial projects. Johnson Controls leverages its building automation integration to bundle absorption systems with centralized plant controls. Thermax Limited anchors its position through captive manufacturing of LiBr solutions and heat exchanger cores in India. Trane Technologies competes on chiller-plant optimization software that pairs with its absorption equipment.
Absorption chillers are thermally activated cooling machines that use a refrigerant-absorbent pair—typically lithium bromide and water or ammonia and water—to produce chilled water through heat-driven desorption and condensation cycles, with cooling capacities ranging from small modular units below 100 kW to centralized plants exceeding 10 MW. These systems serve commercial and industrial facilities where waste heat, solar thermal, or cogeneration output can substitute electrically driven compression cooling. Double-effect technology captures the dominant share of value owing to its higher coefficient of performance and suitability for large district cooling and industrial process loads. Modular installation types are gaining traction among end users seeking phased capacity expansion without full central plant commitment. The LiBr water technology segment leads in unit shipments across humid climates where crystallization risks are managed through advanced controls.
The EPA SNAP program and EU F-Gas Regulation are tightening refrigerant choices and pushing facility operators toward thermally driven alternatives that avoid high-GWP working fluids entirely. China's GB energy efficiency standards and India's BEE labeling mandate are raising minimum performance thresholds for cooling equipment procured in public and commercial buildings. Stakeholders must track how national building codes integrate waste-heat recovery incentives and whether local utility rate structures reward thermal cooling displacement of peak electrical demand.
Market Dynamics
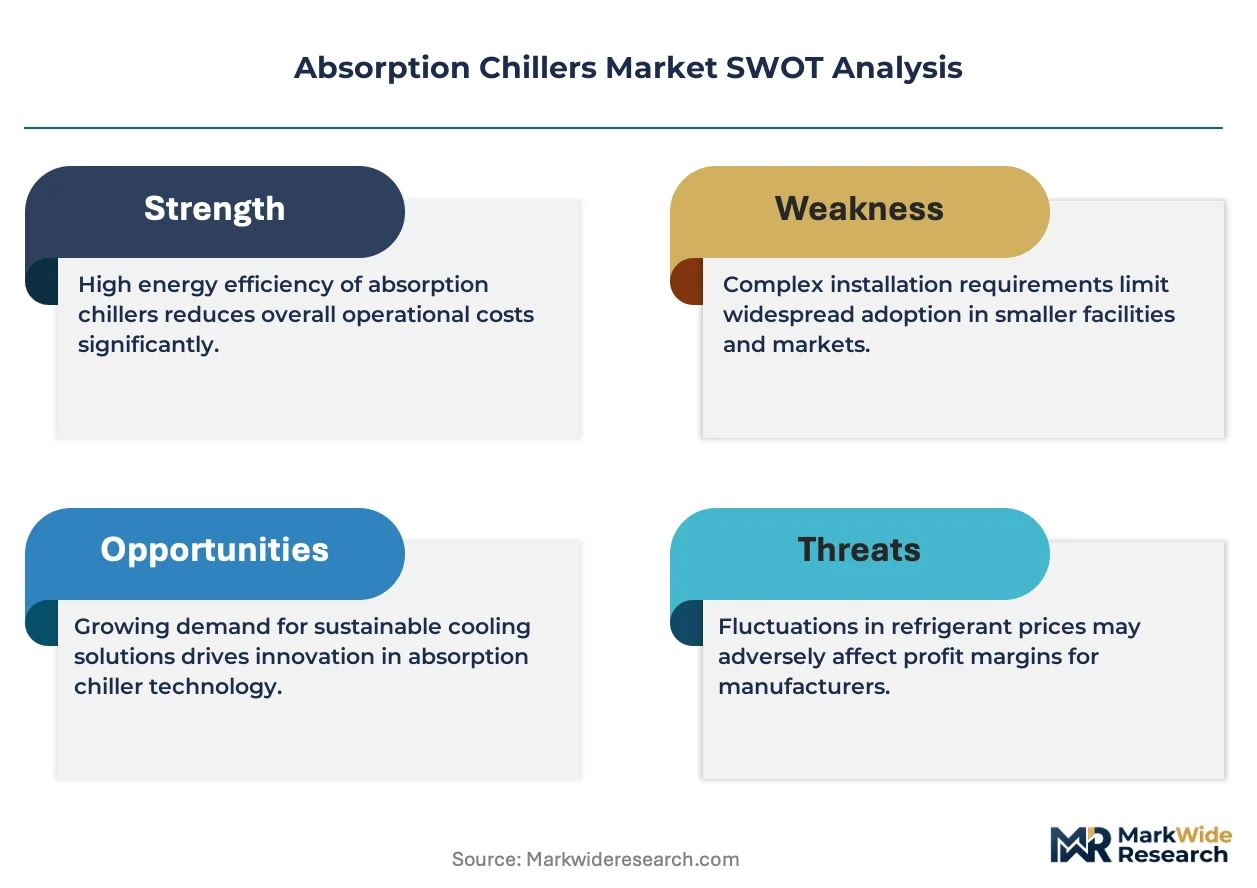
The EU F-Gas Regulation is compressing refrigerant choices across European cooling infrastructure, redirecting capital toward thermally driven alternatives that bypass synthetic working fluids entirely. This regulatory pressure is restructuring competitive access for equipment suppliers and reshaping project specifications in institutional and commercial segments.
Growth Catalysts
- Industrial waste-heat recovery:Manufacturing facilities in China and India are retrofitting cogeneration outputs to drive double-effect absorption cycles, displacing electrically powered compression cooling in process applications.
- ASHRAE Standard 90.1:Compliance mandates in North America are disqualifying conventional chillers from institutional bids, creating specification pathways for thermally activated systems in universities and healthcare campuses.
- District cooling densification:Middle Eastern utilities are procuring multi-megawatt absorption plants to serve urban masterplans, leveraging centralized thermal infrastructure over distributed electric chillers.
Market Restraints
- LiBr crystallization risk:Humid climate installations require advanced control systems to prevent absorbent precipitation, adding capital cost and operational complexity to water-based technology deployments.
- Copper and nickel price volatility:Heat exchanger cores depend on these metals, exposing manufacturers to input cost swings that compress margins on fixed-price project contracts.
- Steam quality requirements:Double-effect systems demand precise thermal input conditions, limiting retrofit feasibility in facilities with variable waste-heat profiles or degraded boiler infrastructure.
Strategic Opportunities
- Modular phased deployment:End users in Southeast Asia are specifying containerized absorption units that permit capacity expansion without central plant overhaul, reducing upfront commitment and permitting risk.
- Solar thermal pairing:Concentrated solar collector arrays are integrating with single-effect chillers in Mediterranean climates, creating zero-electricity cooling for agricultural processing and remote commercial loads.
- India's BEE labeling mandate:Public building procurement rules are creating certified demand pools for high-COP absorption equipment, favoring suppliers with indigenous manufacturing and local service networks.
Industry Challenges
- Absorbent chemistry expertise:The workforce shortage in lithium bromide solution management and corrosion inhibition is extending commissioning timelines and raising service contract premiums.
- Legacy BAS integration:Building automation protocols from the 1990s lack native communication modules for modern absorption chiller controllers, forcing costly middleware development or partial system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorption Chillers Market |
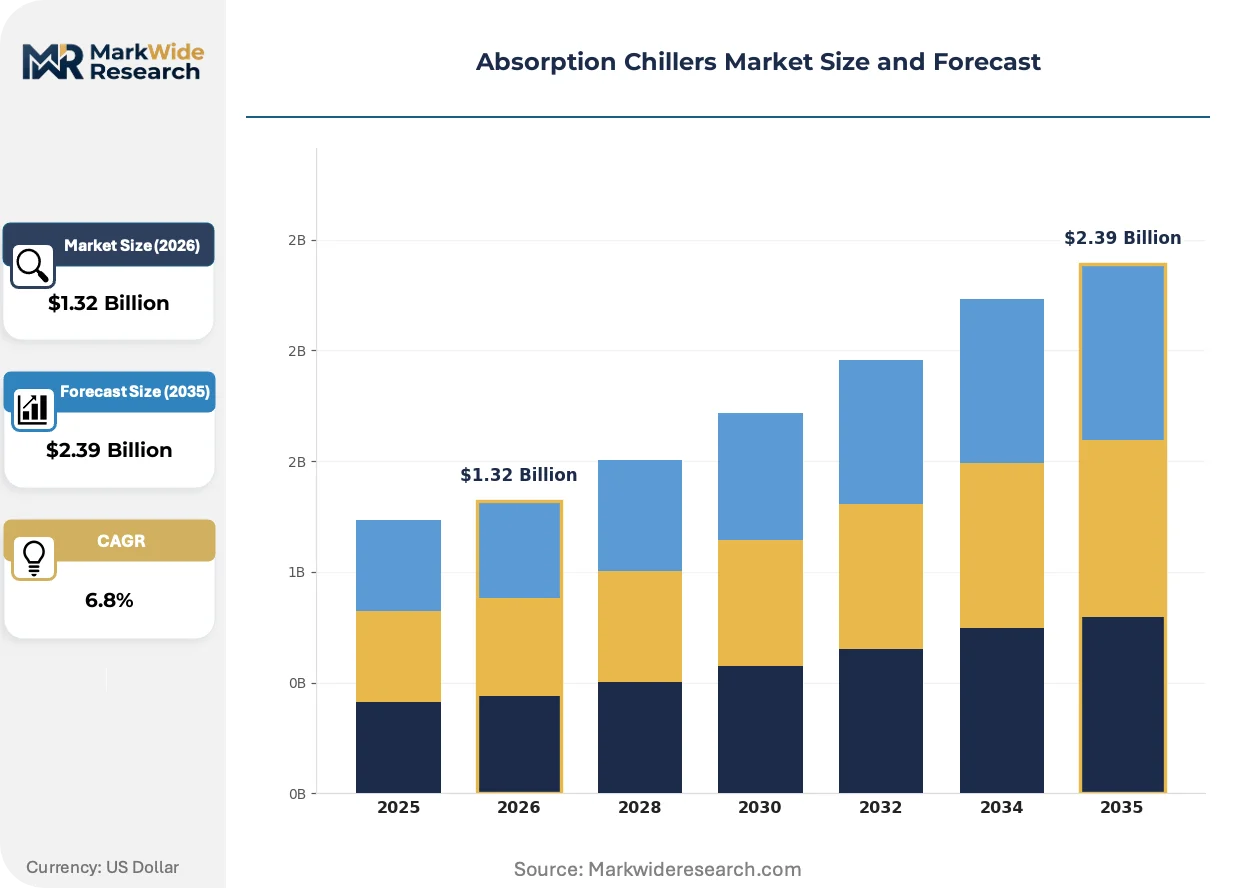
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Effect, Double-Effect, Multi-Effect, Tri-Generation End User: Commercial, Industrial, Residential, Institutional Technology: LiBr Water, Ammonia Water, H2O, Others Installation Type: Centralized, Decentralized, Modular, Portable |
| Companies Covered | Johnson Controls, Thermax Limited, Trane Technologies, BROAD Group, Carrier Global Corporation, Shuangliang Eco-Energy Systems, Hitachi, Daikin Industries, Yazaki Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorption Chillers Market Emerging Trajectories
Equipment architectures are fragmenting into specialized configurations as end users reject one-size-fits-all central plants. This specialization is accelerating control system sophistication and redefining supplier value propositions around thermal integration rather than standalone chiller sales.
Ammonia-water absorption technology is decomposing the historical dominance of lithium bromide systems in sub-zero cooling applications. Cold storage operators and chemical process facilities are specifying ammonia-based units for temperatures below 4°C, where LiBr crystallization risks become prohibitive. This shift is compressing the addressable market for water-based technologies in industrial refrigeration while opening specialized niches for ammonia equipment suppliers.
The EU F-Gas Regulation is banning high-GWP refrigerants in new commercial cooling equipment from 2025, eliminating hydrofluorocarbon options for electric chiller replacements. Facility operators in Germany, France, and the Netherlands are pre-emptively specifying thermally driven systems to avoid compliance transition costs and refrigerant supply uncertainty. This regulatory compression is most acute in district cooling networks and large hospital campuses where cooling loads are continuous and refrigerant volumes substantial.
Energy service companies are unbundling chiller plant performance guarantees from equipment supply contracts, selling cooling-as-a-service to industrial clients with waste-heat assets. This model transfers operational risk to the ESCO and aligns supplier incentives with measured thermal output rather than installed capacity. The arrangement is most visible in Indian textile processing and Gulf petrochemical complexes where fuel costs dominate lifecycle economics and capital constraints favor opex-based procurement.
Absorption Chillers Market Segmentation
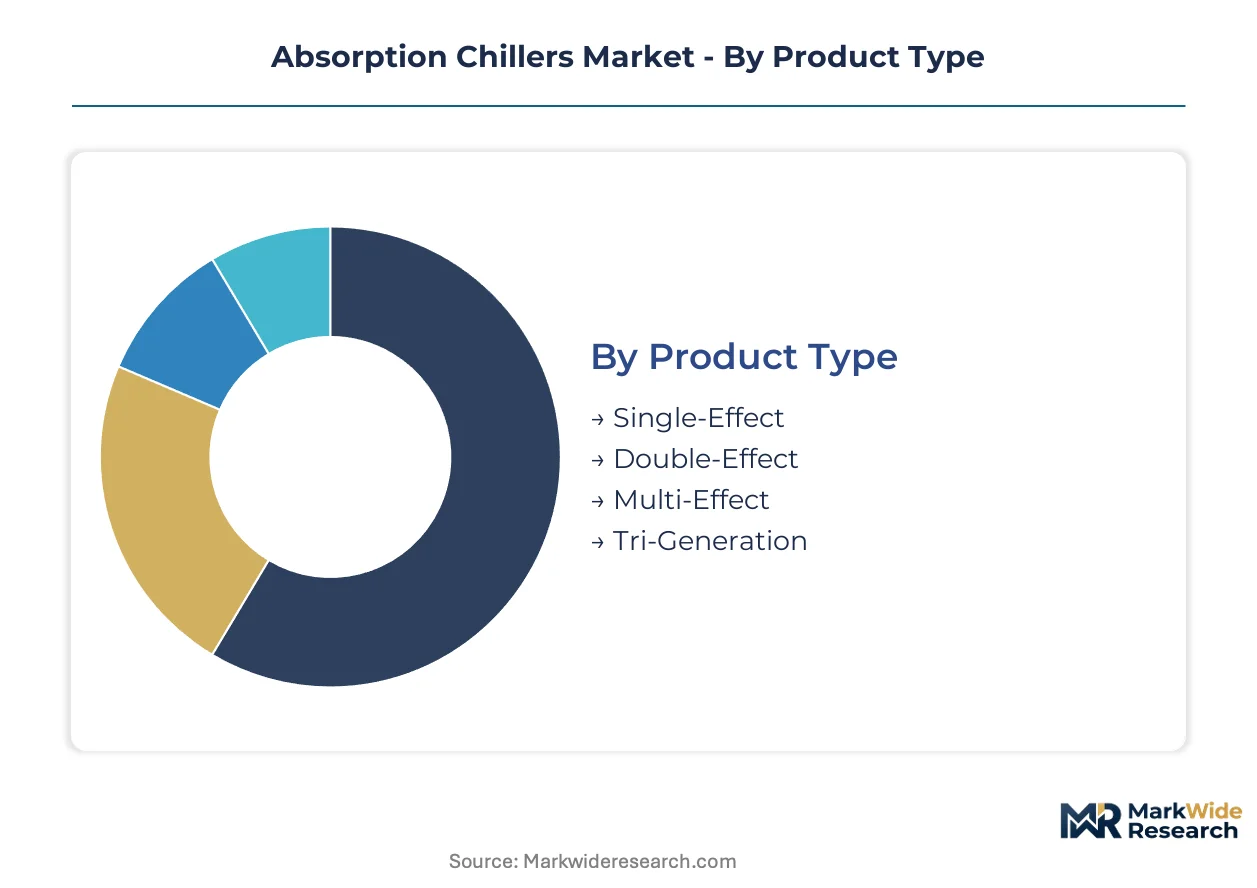
Absorption chiller procurement patterns diverge sharply across thermal source availability and facility scale. Suppliers configure margin capture around technology-effect combinations and installation complexity tiers rather than raw cooling capacity alone.
Product Type:
Margin pools concentrate in double-effect systems where higher COP ratings justify premium positioning against single-effect alternatives.
- Single-Effect:These units operate on low-grade heat sources below 90°C, utilizing single-stage desorption cycles with COP ratings near 0.7. Demand clusters in Mediterranean solar thermal installations and remote agricultural processing where heat source quality limits technology choice.
- Double-Effect:Dual-stage desorption cycles achieve COP ratings of 1.2-1.4 by cascading heat through high and low pressure generators. Manufacturing facilities in China and India specify these for cogeneration waste-heat recovery where steam quality exceeds 150°C.
- Multi-Effect:Triple-stage configurations push COP above 1.5 but require precise thermal input management. Gulf district cooling operators pilot these for megawatt-scale centralized plants.
- Tri-Generation:Combined cooling, heat and power systems integrate absorption cycles with on-site electricity generation. University campuses in Germany deploy these for carbon-neutral thermal infrastructure.
The dominant share belongs to Double-Effect, while Tri-Generation is closing the gap fastest.
End User:
Application scale determines whether procurement favors centralized plant investments or modular distributed units.
- Commercial:Office complexes and retail chains in India's BEE-mandated public buildings specify absorption systems for base-load cooling displacement. Procurement concentrates in facilities with adjacent cogeneration or solar thermal assets.
- Industrial:Petrochemical complexes and textile processors across the Gulf and Southeast Asia retrofit absorption chillers onto waste-heat streams. ESCO performance contracts dominate this segment.
- Residential:Small-capacity units serve luxury developments and district cooling tap-offs in Dubai and Riyadh masterplans. Volume remains constrained by first-cost premiums over compression cooling.
- Institutional:Hospital campuses and university districts in the US face ASHRAE 90.1 compliance deadlines. Thermally driven systems qualify for institutional bids where electric chillers face specification disqualification.
Industrial installations generate the highest revenue per project, though Institutional procurement is expanding most quickly.
Technology:
Working fluid chemistry dictates addressable temperature ranges and climate-specific deployment constraints.
- LiBr Water:Lithium bromide absorbent paired with water refrigerant dominates humid climate installations above 4°C. Crystallization risk requires advanced controls in high-humidity environments.
- Ammonia Water:Ammonia refrigerant enables sub-zero cooling to -30°C for cold storage and chemical process applications. Industrial refrigeration operators in Europe specify these where LiBr cannot reach required temperatures.
- H2O:Water-only systems serve specialized low-lift cooling applications with minimal temperature differential requirements.
- Others:Emerging absorbent pairs including ionic liquids and advanced salt solutions address corrosion and crystallization limitations in pilot deployments.
LiBr Water retains the largest installed base, while Ammonia Water is gaining share fastest in industrial refrigeration conversions.
Installation Type:
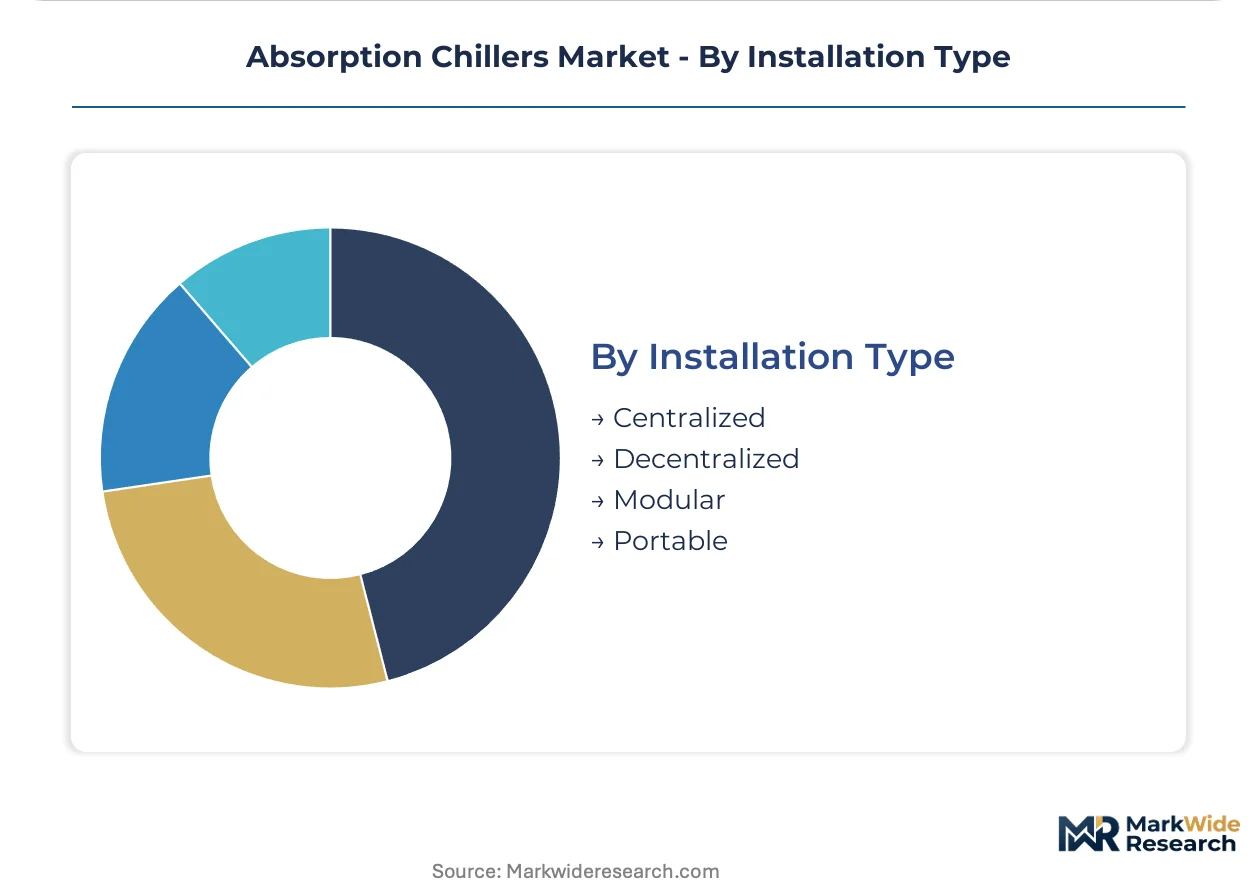
Capital commitment flexibility is restructuring procurement toward phased deployment models.
- Centralized:Multi-megawatt plants serve district cooling networks and large industrial campuses. Middle Eastern utilities procure these for urban masterplan thermal infrastructure.
- Decentralized:Building-level installations match capacity to individual facility loads without distribution network investment.
- Modular:Containerized units permit capacity expansion without central plant overhaul. Southeast Asian textile processors favor these for permitting risk reduction and phased capital deployment.
- Portable:Skid-mounted temporary cooling serves construction site offices and event infrastructure. Rental fleet operators maintain these for short-term industrial process support.
Centralized systems command the highest absolute margins, yet Modular configurations are climbing the fastest as end users reject full-commitment plant investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial facilities and district cooling operators in China, India, the United States, Germany, and the UAE concentrate procurement of absorption systems. Each geography applies distinct regulatory pressure and thermal infrastructure logic to equipment selection.
China
Petrochemical complexes in Shandong and Jiangsu provinces retrofit double-effect absorption chillers onto waste-heat streams from coal-gasification plants. MIIT's GB energy efficiency standards mandate minimum COP thresholds for cooling equipment in public buildings. The Yangtze River Delta hosts the densest cluster of industrial cogeneration-to-cooling conversions.
India
Textile processors in Gujarat and Tamil Nadu specify modular absorption units under ESCO performance contracts to displace grid-powered compression cooling. BEE labeling mandates for public building procurement create certified demand pools favoring high-efficiency equipment. The Delhi-Mumbai Industrial Corridor drives fastest project pipelines for waste-heat recovery installations.
United States
University campuses and hospital districts face ASHRAE Standard 90.1 compliance deadlines that disqualify conventional electric chillers from institutional bids. EPA SNAP program restrictions on high-GWP refrigerants push facility operators toward thermally driven alternatives. The Southeast and Texas Triangle concentrate retrofit activity in healthcare and education infrastructure.
Germany
Chemical process facilities and district heating operators pilot tri-generation systems integrating absorption cycles with on-site power generation. EU F-Gas Regulation bans on hydrofluorocarbon refrigerants from 2025 accelerate specification of thermally driven cooling. The Rhine-Ruhr and Bavarian industrial clusters lead centralized thermal infrastructure deployment.
United Arab Emirates
District cooling utilities in Dubai and Abu Dhabi procure multi-megawatt absorption plants to serve urban masterplans with centralized thermal infrastructure. MOHAP building efficiency codes and Dubai Supreme Council of Energy mandates drive specification of low-carbon cooling alternatives. The Al Maryah Island and Dubai South developments anchor procurement of large-capacity double-effect systems.
Absorption Chillers Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive building automation capabilities and specialized thermal equipment fabricators with regional manufacturing footprints. The market structure consolidates around suppliers capable of integrating absorption cycles with centralized plant controls and heat source optimization. Two strategic archetypes dominate: full-system integrators bundling chillers with building management platforms, and component specialists controlling absorbent chemistry and heat exchanger production in-house. Competitive moves concentrate on vertical integration into LiBr solution manufacturing and geographic expansion through modular product architectures.
Within the diversified conglomerate tier, Johnson Controls and Trane Technologies anchor positions through building automation integration and chiller-plant optimization software bundling. Thermax Limited exemplifies the regional specialist archetype with captive manufacturing of LiBr solutions and heat exchanger cores in India. BROAD Group occupies a position among Chinese industrial equipment suppliers with project-scale deployment capabilities. These three represent the competitive spectrum from global system integration to regional manufacturing depth.
| Leading Market Players |
|---|
| Johnson Controls |
| Thermax Limited |
| Trane Technologies |
| BROAD Group |
| Carrier Global Corporation |
| Shuangliang Eco-Energy Systems |
| Hitachi |
| Daikin Industries |
| Yazaki Corporation |
| Others |
Supply Flow & Price Mechanics
Lithium bromide solution substitution for conventional refrigerant working fluids simultaneously shifts procurement geography toward captive chemical manufacturers in India and China while compressing pricing power for equipment assemblers dependent on spot-market absorbent sourcing. This input transition rewards suppliers with backward integration into LiBr production while exposing modular fabricators to margin erosion from commodity-grade absorbent price swings.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange copper and nickel pricing dominate project procurement for double-effect absorption systems. Price differentiation hinges on COP certification tier under India's BEE labeling mandate and after-sales service bundling for crystallization-risk management. Pricing pressure stems from nickel price volatility on heat exchanger cores, compressing margins on fixed-price municipal contracts. Industrial ESCO clients demonstrate lowest price sensitivity due to performance-guarantee structures, while Southeast Asian modular buyers negotiate aggressively on upfront capital commitment.
Supply Chain Analysis
Strategic stockpiling of lithium bromide concentrate and copper-nickel alloy plate supersedes just-in-time preferences among absorption chiller fabricators facing six-month crystallization-stable inventory requirements. Manufacturing concentrates in India, China, and Germany, with captive LiBr solution production anchoring cost positions. Raw material dependencies encompass Chilean lithium carbonate, Indonesian nickel matte, and Kazakh copper cathode. Single-source vulnerability runs through Chinese rare-earth corrosion inhibitors. Distribution runs through EPC contractors and district cooling utilities for centralized plants, with modular units shipping direct to textile processors and hospital campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Absorption chillers occupy an early-cycle expansion position as EU F-Gas Regulation mandates and ASHRAE 90.1 compliance deadlines force refrigerant substitution toward thermally driven cooling across institutional and industrial infrastructure.
For Market Incumbents: Consolidate control over lithium bromide solution chemistry and heat exchanger core production to defend margin positions against modular entrants sourcing commodity components. Priority levers include captive manufacturing expansion in India to serve BEE-mandated public building procurement and certification investment for double-effect COP thresholds under China's GB standards. For New Entrants and Emerging Players: Differentiate on containerized modular architectures targeting Southeast Asian textile processors seeking phased capacity deployment without central plant commitment. The most penetrable white space sits in solar thermal pairing for Mediterranean agricultural processing, with go-to-market execution through energy service company performance contracting rather than equipment sales. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors suppliers with indigenous manufacturing footprints and captive absorbent chemistry capabilities. Long-term viability over the coming decade rests on vertical integration depth rather than standalone chiller assembly. The signal to watch is BEE labeling mandate expansion into commercial building codes beyond current public procurement rules.| Strategic Initiative | Industry Significance |
|---|---|
| Captive LiBr Solution Manufacturing | Backward integration into lithium bromide production secures cost stability against spot-market volatility for Indian and Chinese fabricators. |
| Modular Containerized Deployment | Phased capacity expansion without central plant overhaul reduces permitting risk for Southeast Asian textile and food processing clients. |
| Solar Thermal System Pairing | Concentrated solar collector integration creates zero-electricity cooling propositions for Mediterranean agricultural and remote commercial loads. |
| ESCO Performance Contracting | Cooling-as-a-service models transfer operational risk from capital-constrained industrial clients to suppliers with waste-heat optimization expertise. |
| BAS Protocol Integration | Native communication modules for legacy building automation systems reduce commissioning friction in North American healthcare and university retrofits. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across plant engineers at petrochemical complexes, procurement leads at district cooling utilities, ESCO contract managers, and aftermarket service directors. Secondary validation drew from MIIT GB standard filings, BEE labeling registry data, EU F-Gas Regulation implementation reports, and customs trade records for lithium bromide concentrate and heat exchanger alloy shipments. Bottom-up project pipeline enumeration triangulated against top-down equipment production estimates.
Across the analysis window, volume and value outputs reflect segmented modeling by technology effect tier, end-use application, installation type, and regional regulatory cluster. CAGRs derive from installation run-rate projections weighted by thermal source availability and compliance deadline phasing. Forecast inputs incorporate waste-heat recovery feasibility assessments at industrial facilities and solar thermal collector deployment curves for Mediterranean markets.
Decision-makers should treat outputs as directional under assumptions of sustained EU F-Gas enforcement and continued BEE labeling mandate expansion; material deviation in refrigerant phase-out timelines or lithium carbonate supply disruption would warrant model refresh. Revision becomes warranted when nickel price volatility crosses thresholds that compress project economics below ESCO return hurdles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Cold Trap Market
Cooling Systems
Seawater Condensers Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Roll Bond Evaporator Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
Dry Cooler Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Global Air Coolers Market