
 District Heating and Cooling Market | 2026-2036
District Heating and Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
District Heating and Cooling Market Analysis
The premium district energy tier anchored by fourth-generation low-temperature networks is rebalancing against legacy steam-based commodity systems in European cities. ENGIE leverages its integrated energy services platform to control large-scale district cooling concessions across French urban centers. Vattenfall anchors Nordic heat pump integration and deep geothermal sourcing for low-carbon district heating in Stockholm. Danfoss specializes in substation automation and demand-response controls that differentiate its hardware-software stack from pipe-centric competitors.
District heating and cooling denotes centralized thermal energy distribution through insulated piping networks delivering space heating, cooling, and domestic hot water to multiple buildings from shared generation plants operating at 70-120°C for heat and 5-7°C for chilled water. These systems eliminate individual on-site boilers and chillers, improving urban air quality and enabling renewable thermal aggregation at scale. Natural gas still dominates source type in legacy Eastern European networks, though waste heat recovery from power generation and industrial processes represents the fastest-expanding source category as cities pursue circular thermal economies. New build construction type captures concentrated investment in Chinese and Middle Eastern mega-developments, while retrofit activity in aging German and Polish systems constitutes the deepest margin pool for engineering services and pipe replacement.
The EU Green Deal and F-Gas Regulation shape product standards by accelerating refrigerant phase-downs in district cooling and mandating renewable content thresholds for district heat. EMA and national building codes in Germany through KBA-aligned energy efficiency standards, plus REACH chemical compliance for insulation materials, restrict market access for non-conforming equipment suppliers. Stakeholders must monitor how the EU AI Act and proposed building performance standards integrate automated load forecasting into mandatory compliance frameworks.
Market Dynamics
The EU Green Deal's building performance mandates are compressing payback periods for fourth-generation low-temperature networks while forcing legacy steam infrastructure into accelerated replacement cycles across European cities.
Growth Catalysts
- Waste heat recovery from data centers:Copenhagen, Stockholm, and Helsinki are capturing surplus thermal output from hyperscale computing facilities to feed municipal district heating loops, creating circular thermal economies that satisfy renewable content thresholds.
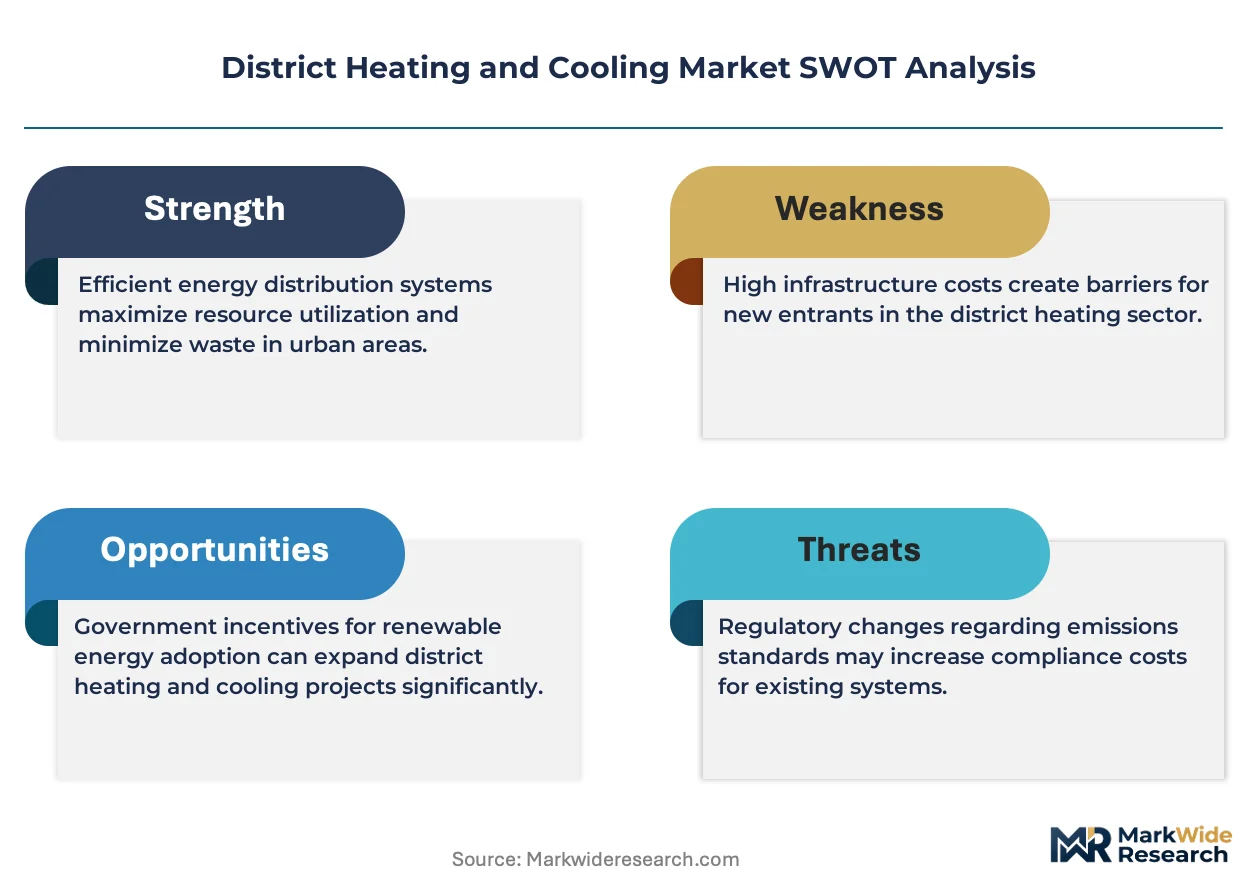
- F-Gas Regulation refrigerant phase-down:The EU's mandated reduction in hydrofluorocarbon use is accelerating district cooling adoption as centralized ammonia-based systems replace distributed fluorocarbon chillers in French and German commercial districts.
- Deep geothermal sourcing:Drilling advances are unlocking sedimentary basin heat for low-temperature networks in the Paris and Munich metropolitan areas, reducing dependence on natural gas peaking plants.
Market Restraints
- Copper and steel input volatility:Insulated piping networks require substantial metal tonnage, and price swings in commodity markets compress margins for engineering procurement construction contractors bidding fixed-price municipal tenders.
- Eastern European gas lock-in:Legacy Polish and Czech networks remain tethered to Russian-origin natural gas supply contracts, creating stranded asset risk as renewable thermal mandates tighten.
- Fourth-generation temperature incompatibility:Existing radiator systems in aging German housing stock cannot operate below 60°C flow temperatures, forcing costly terminal unit retrofits that delay network conversion.
Strategic Opportunities
- Chinese mega-development new build:Xiong'an New Area and other state-planned urban zones are mandating district energy in master plans, creating concentrated deployment opportunities without legacy retrofit friction.
- AI Act automated load forecasting:The EU's algorithmic accountability framework is creating compliance-driven demand for predictive control systems that optimize heat pump dispatch and thermal storage cycling.
- Industrial process heat integration:Steel and chemical facilities in the Rotterdam port cluster are exploring waste heat export to nearby residential districts, blurring the boundary between industrial and municipal thermal systems.
Industry Challenges
- Scarcity of low-temperature network design engineers:The specialized hydronic modeling and control systems expertise required for fourth-generation optimization outpaces vocational training program output in Germany and Poland.
- Legacy substation integration complexity:Retrofitting 1970s-era heat exchanger stations with demand-response controls requires custom mechanical adaptation that extends project timelines and inflates commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | District Heating and Cooling Market |
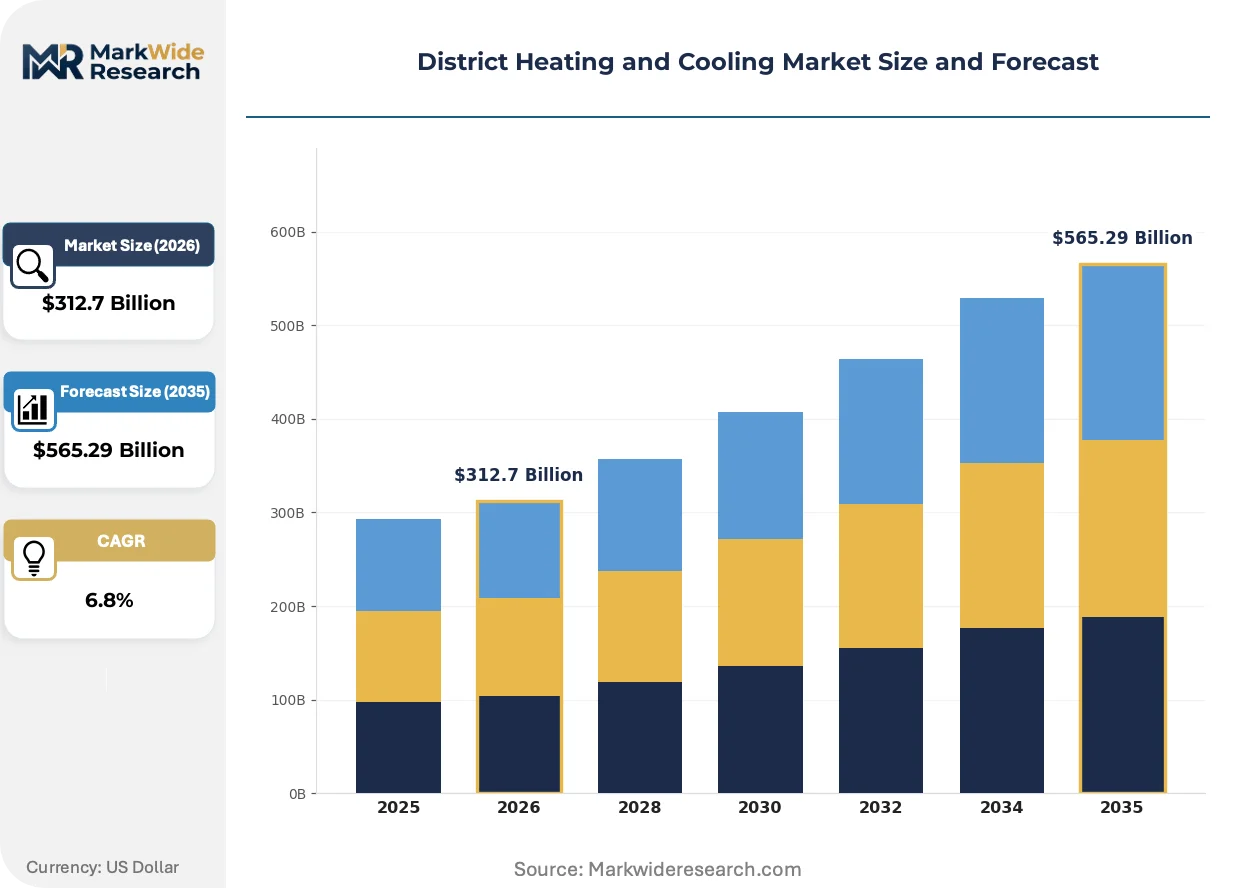
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Centralized, Decentralized, Hybrid, Distributed Source Type: Natural Gas, Biomass, Solar, Waste Heat Construction Type: New Build, Retrofit, Expansion, Maintenance End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | ENGIE, Vattenfall, Veolia, Fortum, Danfoss, E.ON, Alfa Laval, Statkraft, LOGSTOR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
District Heating and Cooling Market Emerging Trajectories
Digital twin modeling and predictive control architectures are displacing static hydraulic calculations as the design standard for new district energy infrastructure, compressing commissioning timelines and enabling real-time optimization.
Low-temperature heat pump arrays are expanding into fourth-generation district heating networks as the primary generation technology for new Scandinavian and Dutch systems. Municipal utilities in Denmark and Sweden are deploying seawater and wastewater source heat pumps at 30-40 MW thermal scale. This technology is expanding into markets previously dominated by biomass and waste-to-energy plants, compressing the cost premium for carbon-neutral heat supply.
The EU AI Act's risk classification framework is mandating algorithmic transparency for automated building energy management systems that interface with district network operators. Industrial consequence includes mandatory documentation of load forecasting model training data and decision logic for systems above 35 kW thermal connection capacity. Large commercial district cooling concessions in France and Germany are most affected, with ENGIE and municipal utilities restructuring procurement specifications to embed compliance-by-design in control system tenders.
Building owners are unbundling thermal energy supply contracts from facility management services, creating direct commercial relationships with district energy operators that bypass traditional mechanical contractor intermediaries. This channel disintermediation concentrates purchasing power in property portfolio managers and real estate investment trusts. The shift is most visible in the Netherlands and United Kingdom, where REITs with multi-site office holdings are negotiating master service agreements spanning multiple city networks.
District Heating and Cooling Market Segmentation
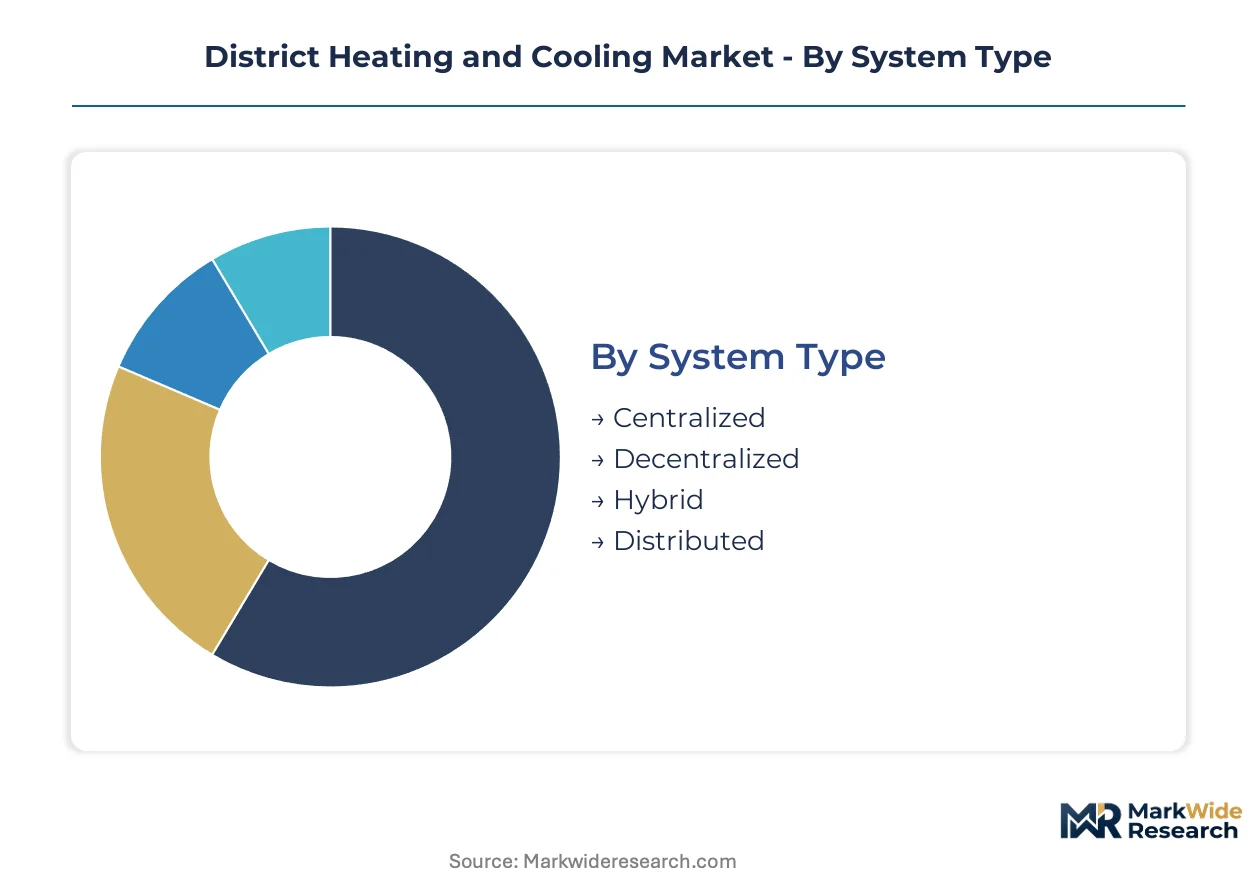
District energy infrastructure segments by thermal generation architecture, fuel sourcing, project lifecycle stage, and customer load profile. Each dimension shapes capital deployment patterns, technology selection, and regulatory compliance pathways for network operators and engineering contractors.
System Type:
Volume concentrates in centralized district heating plants serving dense urban cores, while premium margins accrue to distributed architectures that reduce transmission losses in suburban expansion zones.
- Centralized:Single large-scale generation facility feeds insulated piping networks spanning multiple city blocks, typically operating at 70-120°C flow temperatures. Copenhagen, Stockholm, and Helsinki municipal utilities anchor demand as they scale waste heat recovery from power generation and industrial clusters to serve historic city centers with radiator-compatible supply temperatures.
- Decentralized:Multiple smaller generation points reduce transmission capital and enable modular capacity expansion. Dutch and German suburban districts favor this architecture where lower heat density undermines centralized plant economics, though control system complexity raises operational overhead.
- Hybrid:Combines centralized baseload with distributed peaking to balance efficiency and resilience. Emerging deployment in Chinese state-planned urban zones seeking to integrate legacy coal infrastructure with renewable thermal sources.
- Distributed:Building-scale thermal plants serve micro-districts of 3-10 structures. UK and Netherlands residential developers specify these for garden-city extensions where full network buildout is capital-prohibitive.
Today's leader: Centralized. Tomorrow's challenger: Hybrid.
Source Type:
Fuel selection determines carbon intensity compliance and long-term supply security against volatile commodity markets and tightening EU Green Deal renewable content mandates.
- Natural Gas:Legacy dominant fuel for combined heat and power plants and peak-load boilers. Polish and Czech networks remain tethered to Russian-origin supply contracts, creating stranded asset exposure as renewable thermal thresholds tighten under EU regulations.
- Biomass:Wood chip and pellet combustion supplies baseload in Scandinavian and Baltic systems. Danish and Swedish municipal utilities have scaled this to 40-60% of district heat supply, though particulate emissions scrutiny is rising under ECHA air quality standards.
- Solar:Large-scale thermal collectors and photovoltaic-to-heat systems feed seasonal storage. Austrian and German alpine towns deploy solar district heating with borehole thermal storage to address summer production surplus.
- Waste Heat:Surplus thermal output from data centers, industrial processes, and wastewater treatment. Expanding most quickly as Paris, Munich, and Rotterdam port clusters develop circular thermal export agreements with municipal networks.
Natural Gas still dominates installed capacity. Waste Heat is gaining share fastest on renewable mandate compliance.
Construction Type:
Project lifecycle positioning separates capital-intensive greenfield development from margin-rich engineering services in aging infrastructure refurbishment.
- New Build:Integrated district energy in master-planned urban developments. Xiong'an New Area and Saudi giga-projects mandate centralized thermal infrastructure, eliminating retrofit friction and enabling fourth-generation low-temperature design from inception.
- Retrofit:Replacement of legacy steam piping and substation equipment in 1970s-era German and Polish systems. Constitutes the deepest margin pool for specialized contractors capable of live-network mechanical adaptation.
- Expansion:Network extension to adjacent buildings or districts. French and Dutch utilities pursue this in dense suburban corridors where heat demand density now supports pipeline economics.
- Maintenance:Scheduled pipe replacement, insulation renewal, and control system upgrades. Recurring revenue stream for municipal operators with century-long asset stewardship horizons.
New Build captures concentrated investment flows. Retrofit commands premium engineering margins.
End User:
Load profile diversity across customer segments determines network sizing, temperature requirements, and contract structuring for thermal energy sales.
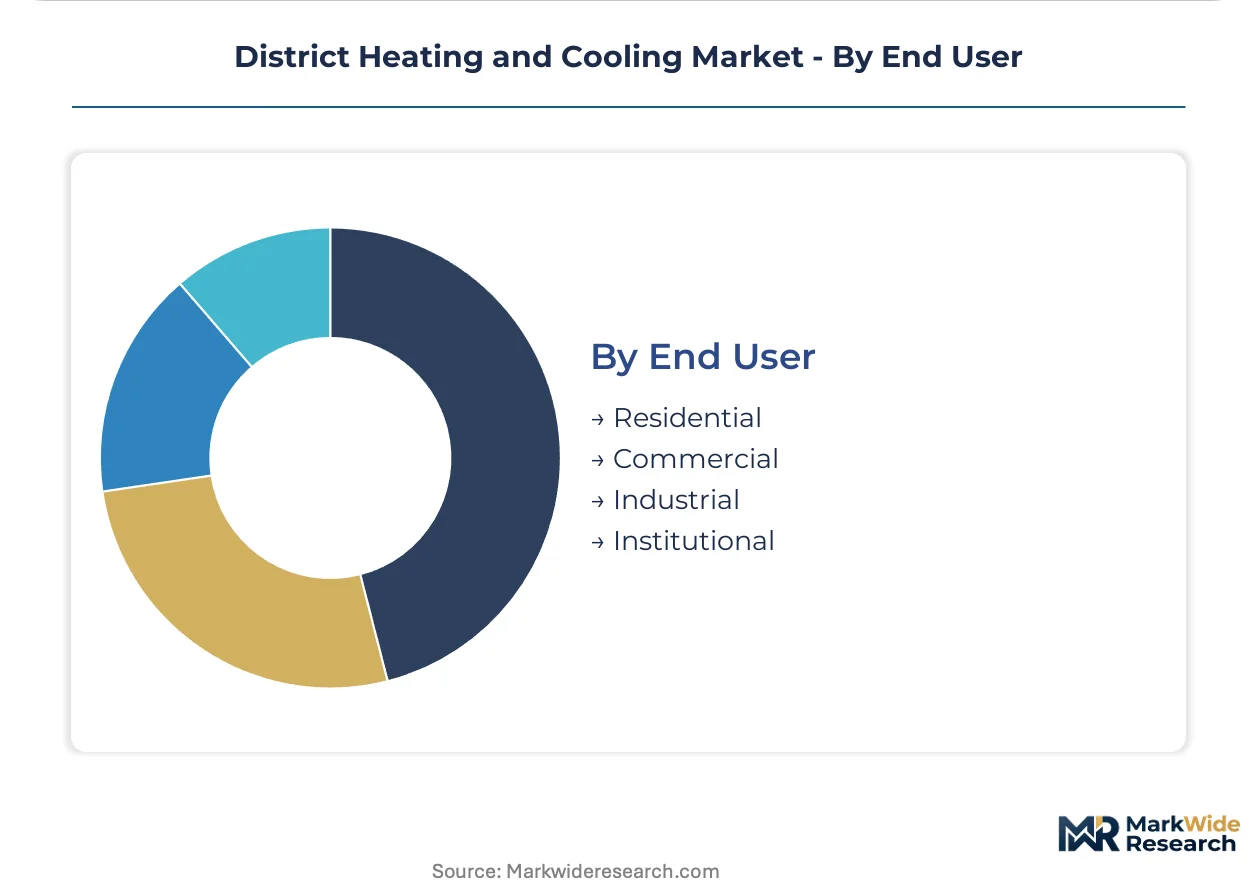
- Residential:Space heating and domestic hot water demand with pronounced seasonal variation. Nordic cities prioritize this segment for waste heat integration given compatible temperature requirements and political visibility of household energy costs.
- Commercial:Office, retail, and hospitality loads with significant cooling demand. French urban centers concentrate district cooling concessions here, with ENGIE and municipal utilities competing for multi-site property portfolio contracts.
- Industrial:Process heat and space conditioning for manufacturing facilities. Rotterdam and Antwerp port clusters explore waste heat export to nearby residential districts, blurring traditional municipal-industrial thermal boundaries.
- Institutional:Hospitals, universities, and government buildings with 24/7 baseload profiles. UK and Netherlands public sector procurement frameworks favor district energy for carbon reduction target compliance.
Residential anchors network scale. Commercial drives cooling technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized district energy engineers concentrate in Nordic municipal utilities and German engineering consultancies, creating talent pools that anchor regional competitive advantage. These workforce clusters enable fourth-generation network deployment and waste heat integration at scale.
Germany
KBA-aligned energy efficiency standards mandate building performance upgrades that accelerate legacy steam network replacement in Ruhr Valley cities. The EU Green Deal's renewable thermal thresholds force natural gas-dependent operators in Eastern Länder to pursue biomass and geothermal sourcing. Munich and Frankfurt metropolitan areas lead deep geothermal drilling for low-temperature district heating baseload.
France
Commercial cooling demand in Paris and Lyon business districts concentrates district cooling concession competition among integrated energy service providers. ANSM and CNIL oversight of automated building systems intersects with EU AI Act compliance requirements for load forecasting algorithms. ENGIE anchors large-scale concessions across Île-de-France urban centers.
Sweden
Waste heat recovery from Stockholm data centers feeds municipal district heating loops at renewable content thresholds required by national building codes. Vattenfall integrates heat pump arrays and deep geothermal sourcing for low-carbon heat supply in Nordic networks. Gothenburg and Malmö port clusters export thermal energy to adjacent residential districts.
China
Xiong'an New Area and other state-planned urban zones mandate district energy in master plans without legacy retrofit friction. NMPA and MIIT standards for building energy management create procurement specifications for centralized thermal infrastructure. Yangtze River Delta and Pearl River Delta mega-developments capture concentrated new build investment flows.
Denmark
Copenhagen's municipal utility scales waste heat capture from power generation and industrial clusters to serve historic city center heating loads. Danish building codes enforce radiator-compatible supply temperatures that maintain fourth-generation network compatibility. Aarhus and Odense deploy seawater source heat pumps at utility-scale thermal capacity.
District Heating and Cooling Market Vendor Landscape
Capital-heavy network operators compete with asset-light control system specialists for margin capture across the district energy value chain. The market structure tiers between integrated energy service platforms commanding municipal concessions and component suppliers differentiating through substation automation. Three archetypes dominate: concession-holding utilities with century-long asset horizons, engineering-procurement-construction contractors bidding fixed-price tenders, and hardware-software stack providers embedding predictive controls. Competitive moves concentrate on strategic partnerships for waste heat offtake agreements and portfolio diversification into cooling-as-a-service models.
Within the integrated utility tier, ENGIE and Vattenfall occupy positions spanning French urban cooling concessions and Nordic low-carbon heat networks respectively. Danfoss exemplifies the control systems archetype, anchoring demand-response hardware differentiation against pipe-centric competitors. These three entities represent the spectrum from energy service integration through thermal generation to substation automation, illustrating how specialization depth determines competitive positioning across network lifecycle stages.
| Leading Market Players |
|---|
| ENGIE |
| Vattenfall |
| Veolia |
| Fortum |
| Danfoss |
| E.ON |
| Alfa Laval |
| Statkraft |
| LOGSTOR |
| Others |
Supply Flow & Price Mechanics
EU Green Deal renewable content thresholds gate qualified supply access and premium-tier pricing power for fourth-generation network equipment. Municipal tenders in Denmark and Germany now require REACH-compliant insulation materials and CE-marked substation controls, compressing margins for non-conforming suppliers while enabling certified vendors to command 15-20% contract premiums.
Pricing Analysis
The bundled-vs-unbundled service split separates concession-holding utilities from component suppliers in margin capture. Project-based long-term offtake contracts dominate municipal procurement, with price differentiation driven by certification tier and after-sales service bundling. Cost compression in standard-grade piping is intensifying because Chinese manufacturers are scaling export capacity. Institutional buyers in the Netherlands and United Kingdom exhibit lowest price sensitivity due to carbon reduction mandates, while Eastern European gas-dependent operators face acute margin pressure from renewable thermal compliance costs.
Supply Chain Analysis
Domestic-content mandates in France and Germany are reshaping sourcing patterns for critical network components. Insulated pipe manufacturing concentrates in Denmark, Germany, and Poland, drawing from steel mills in the Ruhr Valley and copper smelters in Hamburg. Supply chain risk centers on single-source vulnerability for specialized low-temperature heat pump compressors sourced from Scandinavian suppliers. Distribution runs through engineering-procurement-construction contractors bidding fixed-price municipal tenders, with final-mile installation handled by regional mechanical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where waste heat recovery economics in Nordic cities outpace natural gas-dependent Eastern European networks on regulatory compliance cost differentials.
For Market Incumbents: Anchor concession renewal strategies in Paris and Stockholm through deep geothermal sourcing partnerships that lock in renewable content thresholds ahead of EU Green Deal tightening. Vertical integration into substation automation hardware defends margin position against Danfoss-type control specialists. Securing waste heat offtake agreements with hyperscale data centers in Copenhagen and Helsinki creates exclusive supply moats. For New Entrants and Emerging Players: Capture white-space opportunity in Chinese state-planned urban zones where Xiong'an New Area mandates eliminate legacy retrofit friction. Distributed micro-district architectures in UK garden-city extensions offer lowest competitive density. Lead with AI Act-compliant predictive control systems as a go-to-market wedge against incumbent static hydraulic designs. For Investors and Strategic Acquirers: Valuations sit cheapest among engineering-procurement-construction contractors with live-network retrofit expertise in aging German and Polish systems. Long-term viability over the next decade hinges on fourth-generation conversion capability and waste heat integration track records. The signal to watch is municipal tender specifications embedding algorithmic transparency requirements for automated load forecasting systems.| Strategic Initiative | Industry Significance |
|---|---|
| Waste Heat Recovery Partnership | Copenhagen data center thermal export agreements satisfy EU Green Deal renewable thresholds. |
| Deep Geothermal Drilling Expansion | Munich and Frankfurt metropolitan baseload sourcing reduces natural gas peaking dependence. |
| AI Act Compliance Integration | French commercial cooling concessions mandate algorithmic transparency in control system tenders. |
| Substation Automation Acquisition | Demand-response hardware differentiation compresses commissioning timelines for municipal operators. |
| Chinese Mega-Development Entry | Xiong'an New Area master plans enable fourth-generation design without retrofit friction. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary conversations with municipal utility planning officers, district energy EPC contractors, substation automation engineers, and real estate portfolio managers combined with secondary validation from EU ETS emissions databases, national building code filings, F-Gas Regulation compliance registries, and municipal tender documentation. Bottom-up project pipeline aggregation and top-down regulatory mandate sizing provided cross-check triangulation.
Historical reference periods anchored the projection horizon to established deployment trajectories in Nordic and German networks. The analytical framework modeled segmentation across system architecture, fuel sourcing, construction lifecycle stage, and end-user load profile, with regional regulatory cluster as an additional dimension. CAGRs were derived from capacity addition curves and technology substitution rates, incorporating waste heat availability forecasts and geothermal drilling success rates as industry-specific inputs.
Policy reversal, commodity price spikes, and technology cost misestimation are the dominant revision risks for district energy infrastructure forecasts. Forecasts reflect documented assumptions about EU Green Deal implementation pacing and F-Gas Regulation enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Global Evaporative Cooling Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Global Air Cooled Condenser Market
Cooling Systems
Transformer Oil Coolers Market
Cooling Systems
Cold Trap Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Annular Cooler Market
Cooling Systems
Three Phase Cooling Fans Market
Cooling Systems
Global Chiller Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Solar Ventilation Systems Market
Cooling Systems
Turbine Inlet Cooling Systems Market
Cooling Systems
Solar-Assisted Heat Pump Market