
 Cold Trap Market | 2026-2036
Cold Trap Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Trap Market Analytics
Closed-loop cryogenic refrigeration is tilting cold trap design away from liquid nitrogen dependency toward Stirling-cycle and Gifford-McMahon mechanical coolers. Thermo Fisher Scientific leverages its vacuum technology portfolio to anchor laboratory instrument bundles that include integrated trapping systems. SHI Cryogenics Group dominates superconducting magnet adjacent markets and extends that cryogenic expertise into high-capacity process traps for semiconductor fabs. Agilent Technologies competes through chromatography system integration, where cold traps function as pre-concentration modules rather than standalone units.
A cold trap is a vacuum apparatus that condenses vapors onto a chilled surface, typically operating between minus 196 degrees Celsius and minus 50 degrees Celsius depending on the cryogen or refrigeration method employed, primarily to protect vacuum pumps from corrosive or condensable contaminants. Mechanical traps using refrigeration compressors command the largest installed base due to lower operating costs, while cryogenic technology configurations capture the fastest replacement cycle as semiconductor nodes shrink below three nanometers and demand cleaner vacuum environments. Hybrid systems that combine adsorption media with active cooling are gaining traction in pharmaceutical lyophilization where product cross-contamination carries batch-destroying consequences.
The EPA enforces NESHAP standards that mandate volatile organic compound recovery rates above ninety-five percent in chemical processing, directly expanding demand for multi-stage trapping arrays. ISO 14644 cleanroom classifications and SEMI standards for semiconductor manufacturing equipment jointly determine surface finish specifications and materials of construction for traps deployed in wafer fabrication. REACH compliance in Europe restricts certain fluorinated refrigerants, pushing manufacturers toward hydrocarbon and natural refrigerant architectures. Stakeholders must monitor how refrigerant phase-down schedules interact with trap performance specifications across their installed base planning cycles.
Market Dynamics
Semiconductor fabrication node shrinkage below three nanometers is forcing vacuum equipment manufacturers to eliminate molecular contamination at previously tolerable levels, compressing cold trap replacement cycles and elevating specifications for surface finish and thermal uniformity.
Growth Catalysts
- EPA NESHAP Enforcement:The National Emission Standards for Hazardous Air Pollutants mandates volatile organic compound recovery rates above ninety-five percent in chemical processing, directly expanding demand for multi-stage trapping arrays in US petrochemical corridors.
- Taiwan Semiconductor Cluster:Fabrication facilities in Hsinchu and Tainan are expanding cold trap procurement for vacuum deposition chambers as advanced packaging capacity scales.
- Stirling-Cycle Mechanical Cooling:Closed-loop cryogenic refrigeration is displacing liquid nitrogen dependency in laboratory and process applications, reducing operating costs and supply chain vulnerability.
Market Restraints
- Refrigerant Phase-Down Schedules:REACH compliance in Europe restricts fluorinated refrigerants, forcing engineering redesigns toward hydrocarbon architectures with lower cooling capacity per unit volume.
- East Asian Supply Concentration:Critical cryocooler compressors and specialized vacuum flanges concentrate manufacturing in Japan and South Korea, creating vulnerability to regional logistics disruptions.
- Technical Performance Ceiling:Mechanical traps using refrigeration compressors face fundamental limits achieving temperatures below minus one hundred degrees Celsius without cascade systems.
Strategic Opportunities
- Indian Pharmaceutical Lyophilization:Contract manufacturing organizations in Hyderabad and Bengaluru are adopting hybrid cold trap systems combining adsorption media with active cooling to prevent batch-destroying cross-contamination.
- EU F-Gas Regulation Tailwind:The fluorinated gas phase-down creates replacement demand for natural refrigerant architectures in existing installed bases across German and French chemical processing.
- Chromatography System Convergence:Integration of cold traps as pre-concentration modules within analytical instrument bundles opens service contract and consumables revenue streams distinct from standalone equipment sales.
Industry Challenges
- Cryogenic System Integration Talent:Semiconductor fabs and pharmaceutical manufacturers face acute shortages of technicians qualified to commission and maintain ultra-high vacuum systems with integrated trapping stages.
- ISO 14644 Certification Timelines:Cleanroom classification compliance for wafer fabrication equipment extends validation cycles, delaying revenue recognition for trap suppliers serving new fab construction projects.
- Legacy Vacuum Infrastructure Compatibility:Retrofitting mechanical refrigeration traps into existing deposition chambers designed for liquid nitrogen operation requires custom flange adaptations and control system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Trap Market |
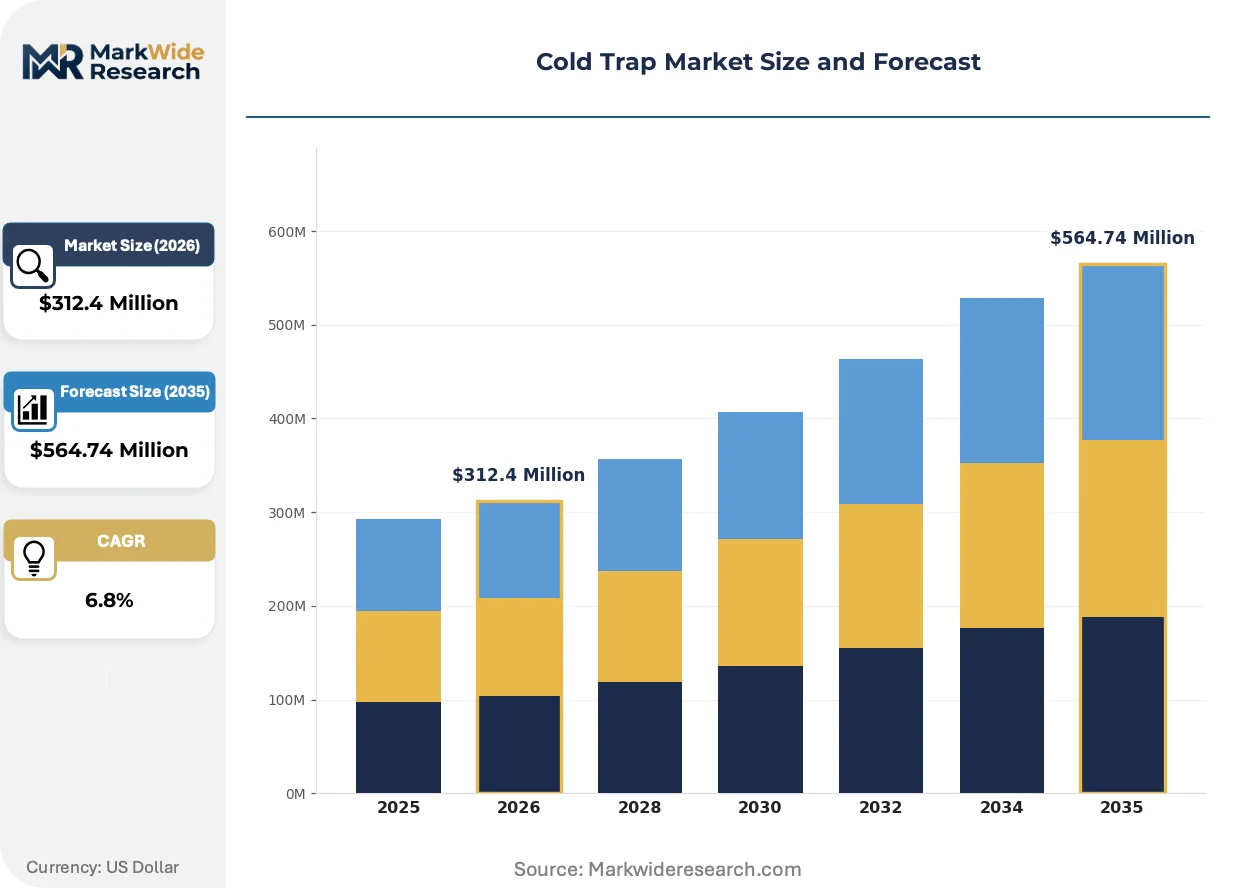
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Mechanical, Pneumatic, Electronic, Hybrid Application: Laboratory, Manufacturing, Chemical Processing, Oil Recovery Technology: Vacuum, Cryogenic, Refrigeration, Adsorption End User: Pharmaceuticals, Research Institutions, Food Industry, Aerospace |
| Companies Covered | Lake Shore Cryotronics, Thermo Fisher Scientific, SHI Cryogenics Group, Agilent Technologies, Buchi, Ulvac Cryogenics, Shimadzu, Labconco, SRI Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Trap Market Evolving Landscape
Cold trap architecture is converging around modularity and predictive thermal management as end-users demand equipment that adapts to process variability without engineering intervention.
Stirling-cycle cryocoolers are virtualizing the traditional liquid nitrogen supply chain by eliminating dewar logistics and venting losses. Semiconductor fabs in South Korea and Taiwan are adopting these mechanical systems for continuous deposition processes. The technology is virtualizing maintenance schedules through onboard vibration monitoring and remote diagnostics, compressing total cost of ownership calculations against cryogenic alternatives.
REACH restrictions on fluorinated greenhouse gases are forcing refrigerant architecture redesigns across European chemical processing installations. Manufacturers are engineering hydrocarbon and natural refrigerant alternatives with modified compressor tolerances and safety systems. Pharmaceutical lyophilization equipment in Germany and Switzerland faces the most acute retrofit pressure as existing F-gas inventories deplete.
Equipment buyers are consolidating vendor relationships around integrated vacuum system suppliers rather than standalone trap specialists. Semiconductor OEMs in East Asia now specify trapping stages as subsystems within larger chamber procurements, marginalizing independent trap manufacturers. This concentration is most visible in Taiwan, where TSMC and its packaging subcontractors negotiate enterprise-level service agreements spanning pumps, gauges, and thermal management components.
Cold Trap Market Segmentation
Cold trap procurement patterns diverge sharply across operational environments. Semiconductor fabs demand continuous-duty mechanical systems with predictive thermal management, while pharmaceutical batch processors prioritize hybrid architectures that eliminate cross-contamination risk.
Type:
Use cases span from precision laboratory work to heavy industrial chemical recovery, with each application imposing distinct thermal load and maintenance cycle requirements.
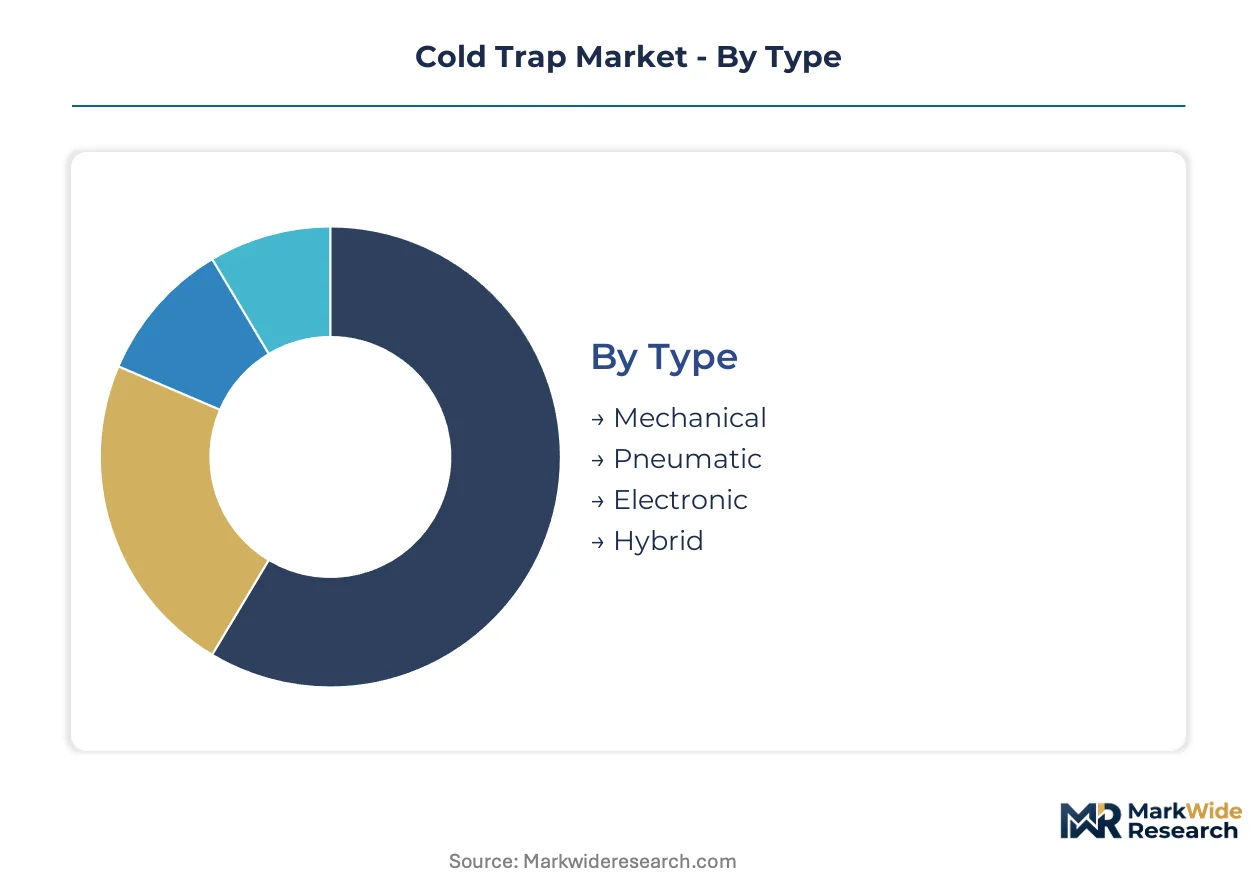
- Mechanical:Refrigeration compressors sustain temperatures between minus 100 and minus 50 degrees Celsius through closed-loop vapor compression cycles. Semiconductor fabrication facilities in Taiwan and South Korea specify these for vacuum deposition chambers where liquid nitrogen logistics prove unsustainable at scale.
- Hybrid:Active cooling combines with adsorption media to capture both condensable vapors and residual gases below mechanical trap limits. Pharmaceutical lyophilization lines in Hyderabad and Bengaluru deploy these configurations where batch-destroying cross-contamination carries regulatory consequences under CDSCO and US FDA inspection protocols.
- Pneumatic:Compressed gas expansion achieves rapid temperature pulldown for intermittent laboratory use.
- Electronic:Thermoelectric cooling modules serve portable field instruments with modest heat removal requirements.
The dominant share belongs to Mechanical, while Hybrid is closing the gap fastest.
Application:
Operating intensity and contamination tolerance determine architecture selection across process environments.
- Manufacturing:Continuous-duty systems in semiconductor wafer fabrication operate 24/7 with vibration-monitored Stirling-cycle cryocoolers replacing liquid nitrogen dewars. South Korean fabs in Pyeongtaek and Yongin lead procurement volume as advanced packaging capacity scales.
- Chemical Processing:Multi-stage trapping arrays recover volatile organic compounds above 95 percent to satisfy EPA NESHAP mandates in US Gulf Coast petrochemical corridors. REACH F-Gas Regulation in Europe forces refrigerant architecture redesigns toward hydrocarbon alternatives.
- Laboratory:Benchtop units with rapid-defrost cycles support analytical instrument pre-concentration modules.
- Oil Recovery:Vapor recovery units at wellhead sites condense hydrocarbon emissions for reinjection or fuel use.
Manufacturing commands installed base leadership, yet Chemical Processing is expanding most quickly.
Technology:
Thermal management methodologies compete on temperature reach, energy efficiency, and refrigerant compliance.
- Cryogenic:Liquid nitrogen and mechanical cryocoolers achieve minus 196 degrees Celsius for ultra-high vacuum protection. Taiwan's TSMC and packaging subcontractors specify these for sub-3 nanometer nodes where molecular contamination tolerances compress replacement cycles.
- Refrigeration:Vapor compression systems dominate cost-sensitive applications with moderate temperature requirements above minus 100 degrees Celsius.
- Vacuum:Pressure differential enhancement improves trapping efficiency in hybrid system designs.
- Adsorption:Zeolite and activated carbon media capture non-condensable gases below mechanical trap limits.
Cryogenic retains premium positioning, though Refrigeration is gaining share fastest on total cost-of-ownership advantages.
End User:
Regulatory stringency and process criticality drive specification divergence across buyer categories.
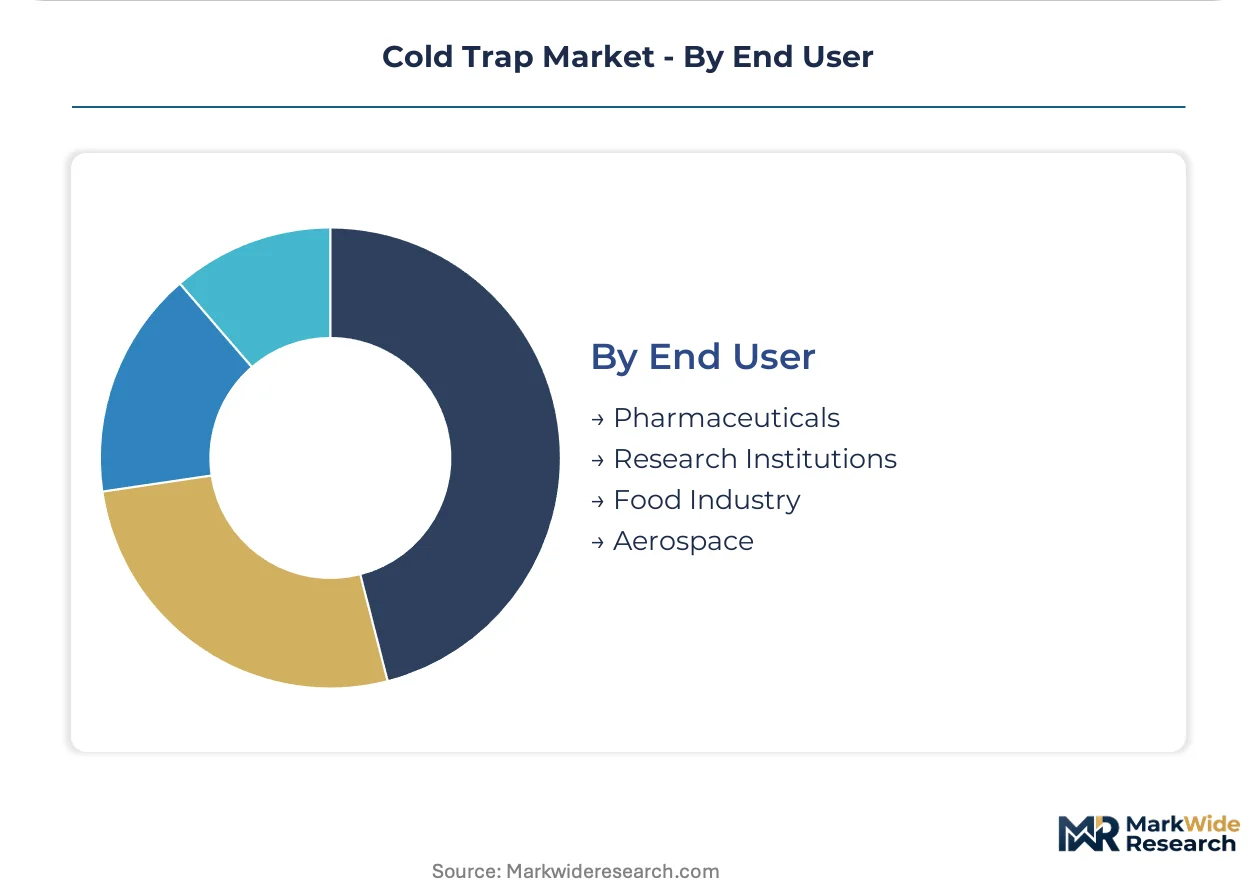
- Pharmaceuticals:Lyophilization equipment demands ISO 14644 cleanroom compliance and surface finishes that prevent product adhesion. German and Swiss manufacturers face acute F-gas phase-down pressure under EU regulation.
- Research Institutions:Universities and national laboratories prioritize modularity for multi-experiment flexibility.
- Food Industry:Freeze-drying operations balance moisture removal rates against flavor compound retention.
- Aerospace:Satellite testing chambers require extreme temperature uniformity for thermal vacuum qualification.
Pharmaceuticals anchor revenue concentration, while Research Institutions are climbing the fastest on federal funding expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabs and pharmaceutical manufacturers concentrate procurement in East Asian electronics clusters and European chemical processing corridors. Taiwan and South Korea drive volume through advanced packaging expansion. Germany and Switzerland face acute refrigerant compliance pressure. The United States anchors petrochemical demand through EPA-mandated recovery systems.
Taiwan
TSMC and its packaging subcontractors in Hsinchu and Tainan specify cryogenic cold traps for sub-3 nanometer vacuum deposition chambers. The island's EPA enforces industrial emissions standards that elevate trapping array specifications. Advanced packaging capacity scaling in Taichung Science Park compresses replacement cycles for molecular contamination control equipment.
South Korea
Samsung Electronics and SK Hynix fabs in Pyeongtaek and Yongin procure Stirling-cycle mechanical coolers to eliminate liquid nitrogen logistics. The Ministry of Environment administers Clean Air Conservation Act amendments tightening volatile organic compound recovery thresholds. Busan-Ulsan petrochemical complexes deploy multi-stage trapping arrays for Naphtha cracking emissions compliance.
Germany
BASF and Bayer chemical processing sites in Ludwigshafen and Leverkusen retrofit hydrocarbon refrigerant architectures under EU F-Gas Regulation phase-down schedules. The Federal Environment Agency enforces fluorinated gas containment and recovery mandates. Pharmaceutical lyophilization equipment manufacturers in Baden-Württemberg face acute retrofit pressure as existing refrigerant inventories deplete.
United States
EPA NESHAP enforcement mandates 95 percent volatile organic compound recovery in Gulf Coast petrochemical corridors from Houston to Baton Rouge. The National Emission Standards for Hazardous Air Pollutants directly expands demand for multi-stage trapping arrays. Semiconductor fabs in Arizona and Texas integrate cold traps as vacuum chamber subsystems within OEM procurement agreements.
Switzerland
Roche and Novartis pharmaceutical manufacturing in Basel demands ISO 14644 cleanroom-compliant hybrid cold trap systems for lyophilization. Swissmedic enforces batch integrity standards that elevate surface finish specifications. Contract manufacturing organizations in the Lake Geneva region adopt adsorption-media configurations to prevent cross-contamination under FDA and EMA inspection protocols.
Cold Trap Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Vacuum equipment OEMs bundle trapping stages within chamber procurements, marginalizing standalone manufacturers. Semiconductor fabs in Taiwan and South Korea negotiate enterprise-level service agreements spanning pumps, gauges, and thermal management. Strategic moves concentrate on refrigerant architecture redesigns and predictive thermal management integration.
Within the laboratory instrument tier, Thermo Fisher Scientific anchors vacuum technology portfolios that include integrated trapping systems. SHI Cryogenics Group occupies a position extending cryogenic expertise from superconducting magnet markets into high-capacity process traps. Agilent Technologies exemplifies chromatography system convergence, where cold traps function as pre-concentration modules rather than standalone units. These three represent distinct archetypes: diversified life science conglomerates, cryogenic specialists, and analytical instrument integrators.
| Leading Market Players |
|---|
| Lake Shore Cryotronics |
| Thermo Fisher Scientific |
| SHI Cryogenics Group |
| Agilent Technologies |
| Buchi |
| Ulvac Cryogenics |
| Shimadzu |
| Labconco |
| SRI Instruments |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Japanese cryocooler compressors determines both tiered pricing spreads across mechanical, hybrid, and cryogenic configurations and the elongated supply chain shape that semiconductor fabs must navigate. Buyers face asymmetric cost pass-through when specialized vacuum flanges from South Korea encounter logistics disruptions, forcing premium tier purchasers toward enterprise service agreements that internalize volatility while economy tier buyers absorb spot market exposure.
Pricing Analysis
Cost-plus contracts with stainless steel and refrigerant indexation dominate procurement between Taiwanese semiconductor OEMs and their vacuum subsystem suppliers. Price differentiation separates ISO 14644-certified cleanroom configurations from standard industrial grades, with surface finish specifications commanding substantial premiums. Pricing pressure stems from REACH F-Gas Regulation compliance costs that European pharmaceutical manufacturers are attempting to push upstream. Contract manufacturing organizations in India exhibit highest price sensitivity due to capital constraints, while Swiss pharmaceutical giants prioritize batch integrity over unit economics.
Supply Chain Analysis
Upstream feedstock for cryogenic cold traps draws from specialized aluminum alloy foundries in Japan, precision-machined vacuum flanges from South Korea, and compressor assemblies concentrated in German industrial clusters. Raw material dependencies include high-purity stainless steel tubing, rare-earth magnet materials for Stirling-cycle motors, and fluorinated refrigerant precursors now restricted under EU regulation. Single-source vulnerability concentrates in Japanese cryocooler compressor manufacturing, where earthquake exposure creates systemic risk. Distribution runs through OEM-integrated subsystem channels rather than independent trap specialists, with semiconductor equipment vendors in Taiwan and South Korea controlling downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
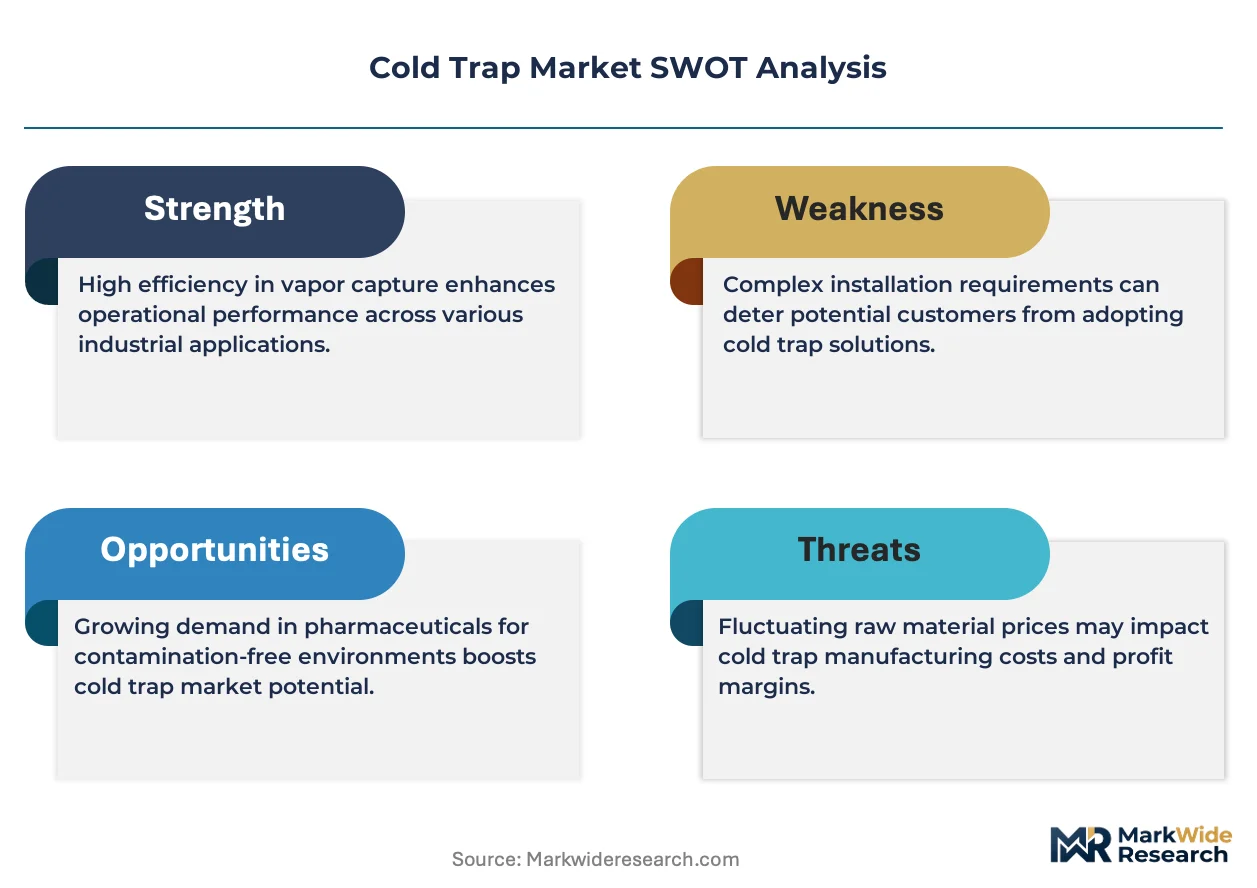
This market demands substitution defense against dry pump technologies that threaten to displace trapping stages in certain vacuum applications. Incumbents must navigate this threat while consolidating around integrated system architectures that raise switching costs.
For Market Incumbents: Build switching cost moats through predictive thermal management software integration that locks semiconductor fabs into proprietary diagnostics ecosystems. Deepen backward integration into cryocooler compressor manufacturing to reduce exposure to Japanese supply concentration. Defend against dry pump substitution by demonstrating molecular contamination performance at sub-3 nanometer nodes where alternative technologies fail.
For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical lyophilization where hybrid system demand outpaces established supplier capacity. Target contract manufacturing organizations in Hyderabad and Bengaluru with adsorption-media configurations that prevent cross-contamination under CDSCO inspection protocols. Pursue chromatography instrument integration partnerships rather than standalone equipment sales to bypass entrenched vacuum OEM relationships.
For Investors and Strategic Acquirers: The market sits at a refrigerant transition phase that favors cryogenic specialists with hydrocarbon architecture readiness over legacy fluorinated refrigerant portfolios. Long-term viability centers on semiconductor fab equipment suppliers with captive trapping technology and service contract density. Watch EPA NESHAP enforcement intensity in Gulf Coast petrochemical corridors as the inflection signal for multi-stage trapping array demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Architecture Redesign | EU F-Gas Regulation compliance opens replacement cycles across German chemical processing installations. |
| Predictive Thermal Management Integration | Onboard vibration monitoring virtualizes maintenance schedules for South Korean semiconductor fabs. |
| Chromatography System Convergence | Pre-concentration module positioning captures service contract revenue streams at Agilent and Thermo Fisher. |
| Hybrid System Development | Adsorption-media configurations prevent batch-destroying cross-contamination under FDA inspection protocols. |
| Enterprise Service Agreement Expansion | TSMC and packaging subcontractors in Taiwan negotiate multi-year contracts spanning pumps, gauges, and thermal management. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEMI equipment standards, EPA NESHAP enforcement records, and EU F-Gas Regulation implementation timelines. Primary interviews captured perspectives from vacuum equipment procurement managers at Taiwanese semiconductor fabs, cryogenic system commissioning technicians, pharmaceutical lyophilization engineers, and aftermarket service directors. Secondary validation drew from customs trade data for cryocooler compressor imports, SEC filings of diversified life science conglomerates, and cleanroom certification databases. Bottom-up unit economics triangulated against top-down semiconductor capital expenditure forecasts.
Forecast inputs span type segmentation across mechanical, hybrid, pneumatic, and electronic architectures; application intensity across manufacturing, chemical processing, laboratory, and oil recovery; technology methodology across cryogenic, refrigeration, vacuum enhancement, and adsorption; and end-user regulatory stringency across pharmaceuticals, research institutions, food industry, and aerospace. CAGRs were derived from replacement cycle compression analysis tied to semiconductor node shrinkage and refrigerant phase-down schedules. Industry-specific inputs include EPA enforcement intensity indices and REACH compliance cost pass-through assumptions.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or fluorinated refrigerant availability would shift the trajectory. Forecasts reflect documented assumptions regarding node transition timelines and regulatory enforcement consistency. Material shifts in dry pump technology performance or East Asian logistics resilience would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Air Source Heat Pump Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Solar Fan Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Chilled Water Storage System Market