
 Global Scroll and Absorption Chillers Market | 2026-2036
Global Scroll and Absorption Chillers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scroll and Absorption Chillers Market Intelligence
The modularization of cooling systems is restructuring buyer preferences for commercial and industrial applications. Carrier Corporation leverages its extensive distribution network to serve large-scale projects. Daikin Industries specializes in high-efficiency inverter scroll technology. Johnson Controls positions its absorption chillers for waste heat recovery opportunities in manufacturing.
Scroll and absorption chillers are systems that provide chilled water for cooling. Scroll chillers use a compressor with two interleaved scrolls for vapor compression, typically serving small to medium capacity needs. Absorption chillers utilize a heat source, often waste heat, with a water-lithium bromide solution to create a cooling effect. Among product types, scroll chillers command a significant share in commercial cooling, while absorption chillers are specified for industrial process cooling where waste heat is available.
Regulatory frameworks are a primary influence on product design and market access. The US EPA's refrigerant management programs and the EU's F-Gas Regulation mandate the phase-down of high GWP refrigerants. China's dual carbon goals also promote the adoption of energy-efficient absorption chillers. Stakeholder success will depend on navigating the complex trade-offs between refrigerant compliance, system efficiency, and total cost of ownership.
Market Dynamics
The market's central dynamic is the push-pull between stringent environmental regulations phasing out high-GWP refrigerants and the escalating demand for cooling capacity from energy-intensive sectors like data centers. This forces a continuous innovation cycle balancing compliance, efficiency, and cost.
Growth Catalysts
- Data Center Expansion:The proliferation of hyperscale data centers and edge computing facilities creates a consistent demand for high-density, reliable cooling systems, directly benefiting both scroll and absorption chiller segments.
- Chinese Industrial Policy:China's dual carbon goals and large-scale industrial construction projects actively promote the adoption of energy-efficient cooling technologies, particularly absorption chillers that can utilize industrial waste heat.
- EU F-Gas Regulation:This European framework's aggressive phase-down schedule for HFCs compels a market shift towards chillers using low-GWP refrigerants, including HFO-based scroll systems and ammonia-based absorption units.
Market Restraints
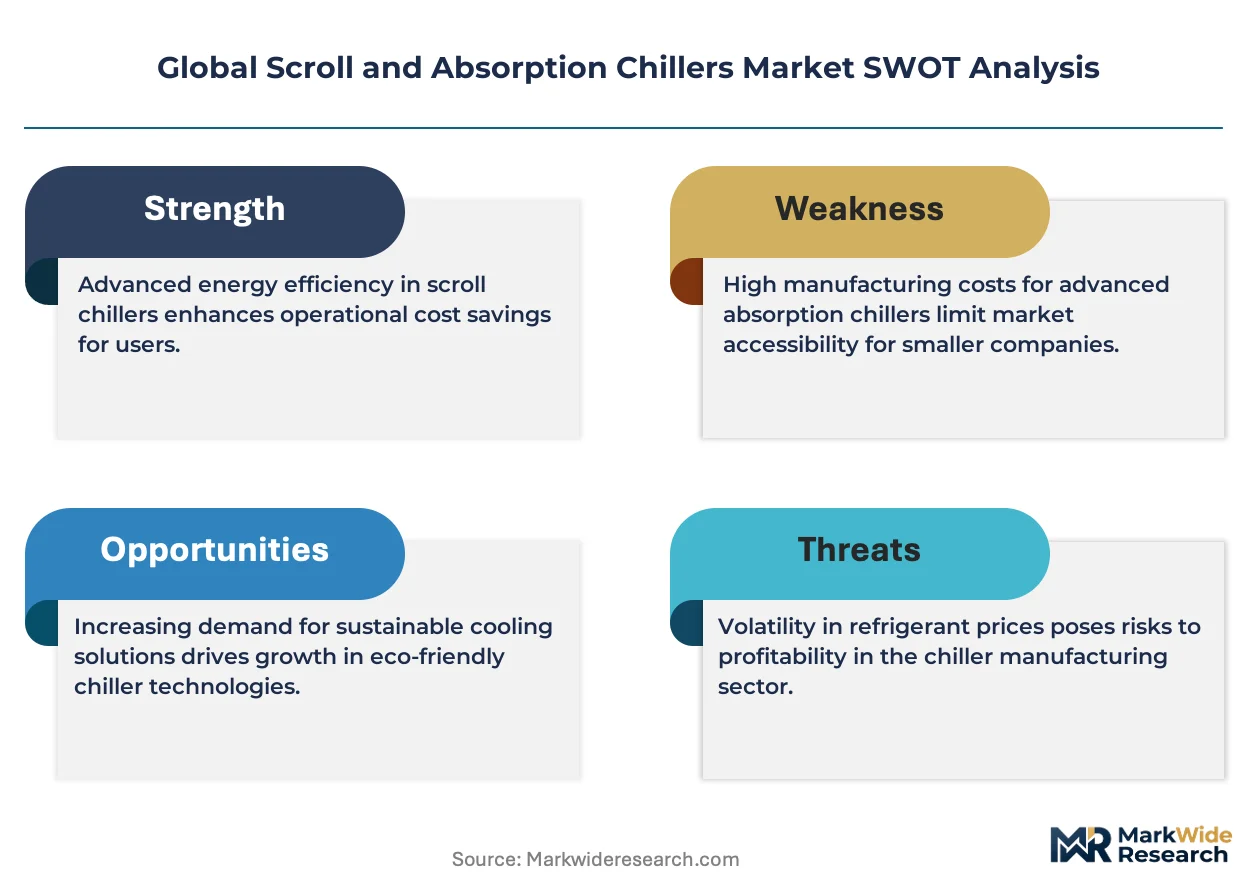
- High Initial Capital Outlay:Absorption chillers, despite their operational efficiency with waste heat, require a significantly higher upfront investment compared to conventional cooling systems, deterring adoption in capital-constrained projects.
- Waste Heat Source Dependency:The operational viability of absorption chillers is fundamentally tied to the availability of a consistent and sufficient waste heat source, limiting their application primarily to specific industrial or cogeneration facilities.
- Technical Complexity:The advanced design of high-efficiency scroll and absorption chillers requires specialized knowledge for installation, commissioning, and maintenance, creating a barrier in regions with a shortage of trained HVAC technicians.
Strategic Opportunities
- Hybrid System Integration:Combining scroll chillers with thermal energy storage (TES) systems presents an opportunity to manage peak electricity loads, offering building owners lower operating costs and enhanced grid stability.
- District Cooling in Emerging Economies:The development of district cooling networks in rapidly urbanizing areas of Southeast Asia and the Middle East opens a substantial new market for large-capacity absorption and scroll chillers.
- Waste Heat Monetization:Industrial facilities can leverage absorption chillers to convert waste heat, a liability, into a cooling asset, creating new revenue streams or cost savings and aligning with circular economy principles.
Industry Challenges
- Divergent Refrigerant Standards:Manufacturers face significant design and supply chain complexity in managing portfolios that must comply with different refrigerant regulations and phase-out timelines between the US, EU, and China.
- Technician Skill Gap:A shortage of technicians trained to service and optimize systems using new low-GWP refrigerants and advanced control logic hinders the performance and reliability of next-generation chiller installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scroll and Absorption Chillers Market |
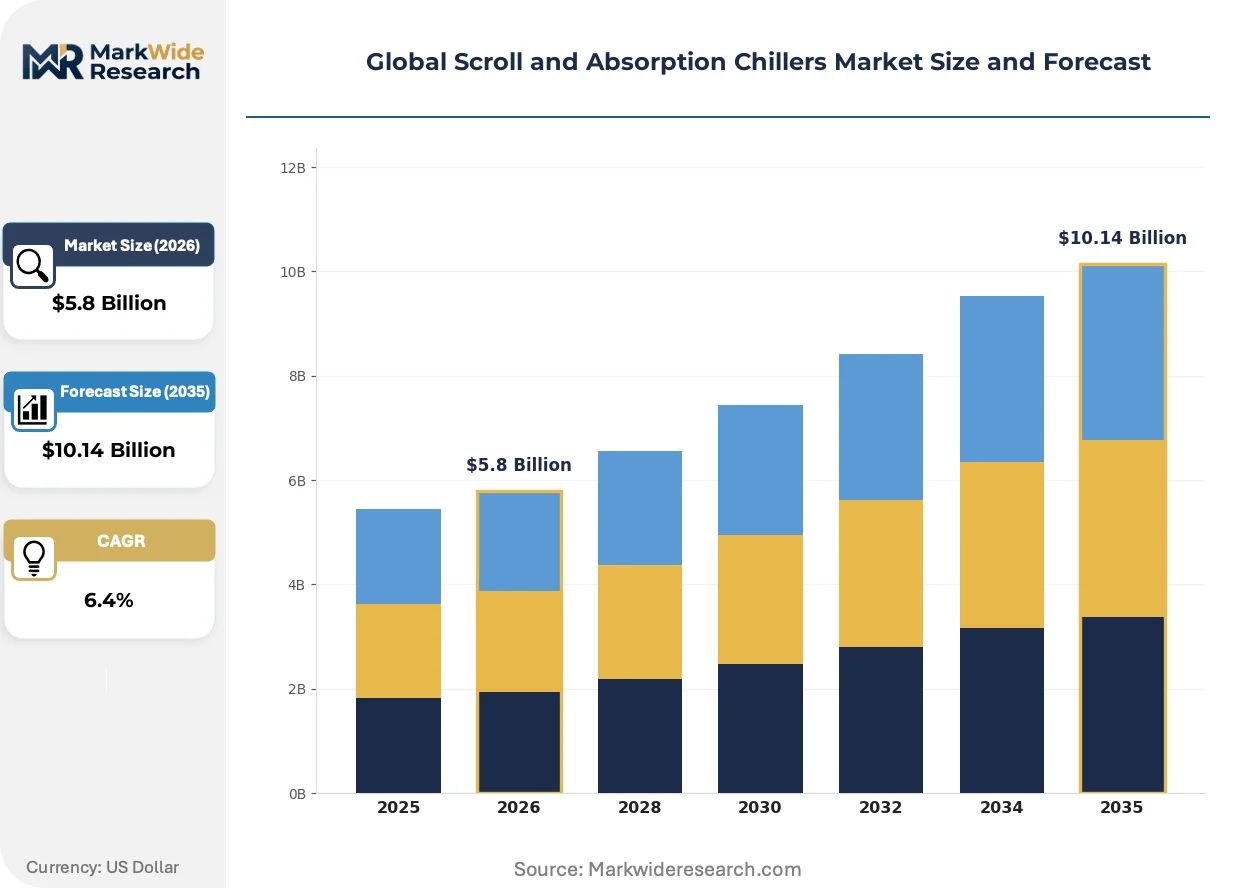
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scroll Chillers, Absorption Chillers, Centrifugal Chillers, Screw Chillers, Reciprocating Chillers Application: Commercial Cooling, Industrial Process Cooling, Data Centers, Pharmaceutical Manufacturing, Food & Beverage Processing, Power Generation Installation Type: Rooftop Units, Package Units, Modular Systems, Centralized Cooling Plants, Standalone Systems End User: Facilities Management, Manufacturing Plants, IT Infrastructure, Research Laboratories, Hospitality Venues, Educational Institutions |
| Companies Covered | Mitsubishi Electric Corporation, LG Electronics, Daikin Industries, Carrier Corporation, Yazaki Energy Systems, Johnson Controls, Broad Air Conditioning, Thermax, Trane Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scroll and Absorption Chillers Market Strategic Shifts & Innovations
The market is pivoting towards lifecycle performance, driven by regulatory pressures on refrigerants and customer focus on total cost of ownership. This shift prioritizes innovations that enhance not just point-in-time efficiency but also long-term reliability and environmental compliance.
Variable speed drive (VSD) technology allows chillers to precisely match cooling output to fluctuating building loads. Data centers and commercial buildings are rapidly adopting VSD-equipped scroll chillers to minimize energy consumption during partial-load conditions. The integration of VSDs is rewriting the efficiency benchmarks for small to medium-tonnage chillers, making fixed-speed models less competitive for new installations.
The US EPA's refrigerant management programs under the AIM Act are accelerating the transition away from high-GWP HFCs. This regulation directly impacts equipment design, forcing manufacturers to re-engineer scroll chillers for mildly flammable A2L or other low-GWP alternatives. The commercial HVAC segment is most affected, responding by investing heavily in safety-standard compliance and technician training for handling these new refrigerants.
A notable behavioral shift is the adoption of cooling-as-a-service (CaaS) business models. This model replaces large upfront capital expenditure with a recurring operational fee, disrupting the traditional equipment sales channel for both scroll and absorption chillers. The CaaS trend is most prominent in large commercial real estate portfolios and industrial applications where uptime and predictable costs are paramount.
Global Scroll and Absorption Chillers Market Segmentation
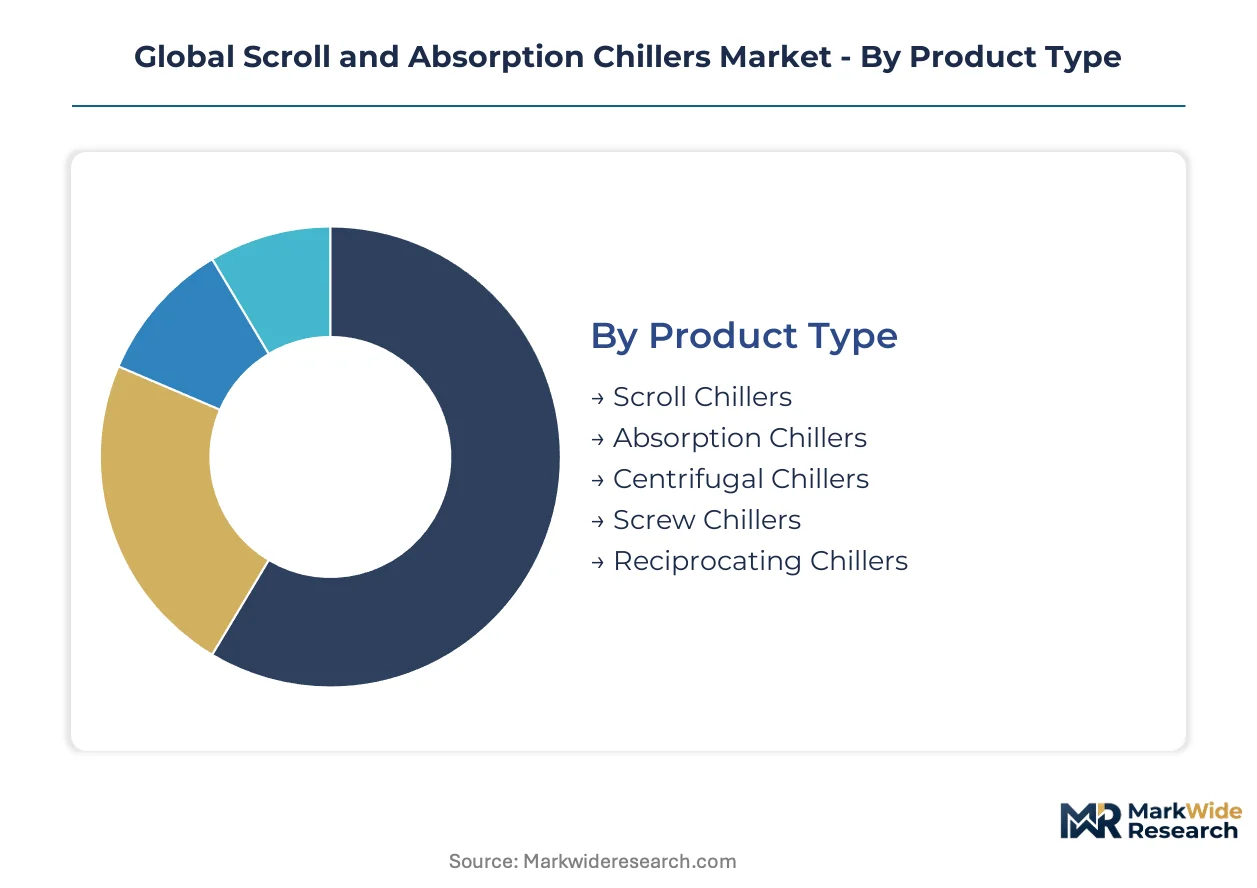
Segmentation provides critical insight into the varied technological preferences and operational demands shaping the global scroll and absorption chillers market. This analysis dissects the market by product type, application, installation method, and end-user, revealing distinct growth drivers and competitive landscapes within each category.
Product Type:
The Product Type segment reflects the spectrum from highly standardized, compact units to complex, custom-engineered cooling solutions.
- Scroll Chillers:These systems employ a compressor with two interleaved scrolls for vapor compression, primarily serving small to medium capacity needs. Demand for scroll chillers is high in the commercial HVAC segment, especially with the integration of variable speed drive technology for efficiency.
- Absorption Chillers:Utilizing a heat source, often waste heat, these chillers create a cooling effect with a water-lithium bromide solution. Absorption chillers are specified for industrial process cooling applications where a consistent waste heat source is readily available, aligning with China's dual carbon goals.
- Centrifugal Chillers:These chillers employ a centrifugal compressor to achieve high cooling capacities, often used in large commercial and industrial applications.
- Screw Chillers:Featuring helical screw rotors for compression, screw chillers offer good efficiency across varying loads for medium to large-scale cooling requirements.
- Reciprocating Chillers:These units feature piston-driven compressors, suitable for smaller cooling requirements but are increasingly displaced by more efficient chiller technologies.
Most installed capacity flows through Scroll Chillers. Expansion is steepest in Absorption Chillers.
Application:
Application segmentation highlights the diverse operational environments and varying cooling volume requirements across different sectors.
- Data Centers:These facilities require high-density, reliable cooling systems to manage significant heat generated by IT equipment. The proliferation of hyperscale data centers and edge computing facilities creates a consistent demand for specialized chiller solutions.
- Industrial Process Cooling:This application demands precise temperature control for various manufacturing processes, frequently leveraging absorption chillers that can utilize industrial waste heat. Manufacturing plants, particularly in China, are significant drivers for this segment.
- Commercial Cooling:This segment encompasses HVAC for office buildings, retail spaces, and other non-industrial facilities, primarily utilizing scroll chillers for comfort and climate control.
- Pharmaceutical Manufacturing:This sector requires stringent temperature and humidity control for drug production and storage, demanding reliable and often redundant chiller system performance.
- Food & Beverage Processing:This application needs consistent refrigeration and cooling for preservation and production processes across various stages of food and beverage manufacturing.
- Power Generation:Chillers are utilized in power plants for turbine inlet cooling or auxiliary cooling functions, enhancing efficiency and operational stability.
The largest revenue contributions stem from Commercial Cooling, with Data Centers demonstrating rapid adoption.
Installation Type:
Installation Type showcases the maturity and deployment flexibility of chiller systems, from traditional setups to advanced integrated solutions.
- Modular Systems:These systems comprise pre-engineered and scalable units that can be easily expanded or reconfigured to match changing cooling loads. The modularization of cooling systems is restructuring buyer preferences for commercial and industrial applications seeking flexibility.
- Centralized Cooling Plants:These plants serve large-scale facilities or district cooling networks from a single, integrated system. The development of district cooling networks in rapidly urbanizing areas of Southeast Asia and the Middle East opens a substantial new market for these large-capacity chillers.
- Rooftop Units:These are self-contained HVAC systems typically installed on building roofs, common for commercial and light industrial applications due to their ease of installation.
- Package Units:These integrated cooling systems house all components in a single enclosure, simplifying installation and commissioning for various commercial and industrial applications.
- Standalone Systems:These are individual chiller units operating independently, providing cooling for specific zones or smaller facilities without integration into a larger network.
Demand for Package Units remains consistent, while Modular Systems are experiencing significant uptake.
End User:
End User categories differentiate demand based on the specific operational needs and purchasing patterns of various customer types.
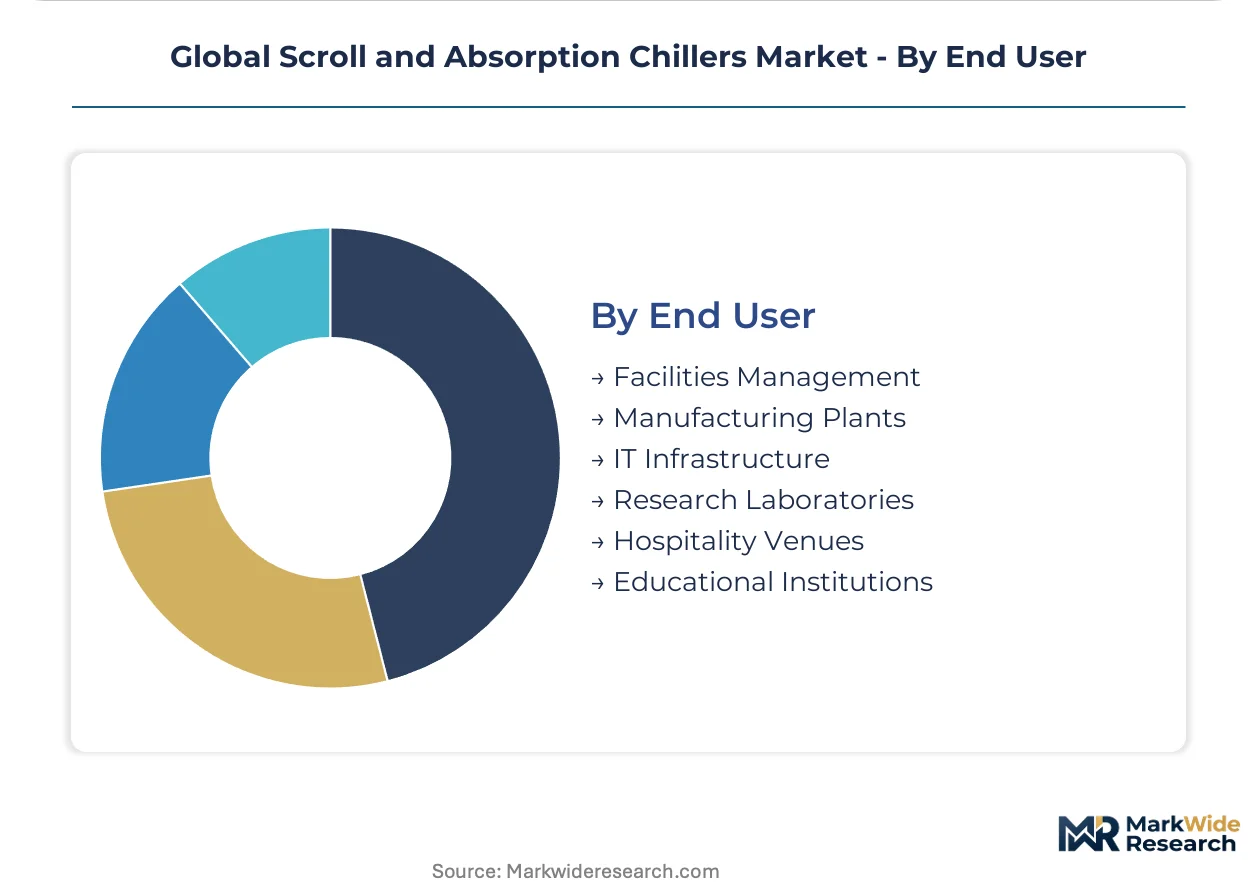
- Manufacturing Plants:These facilities utilize chillers for both industrial process cooling and comfort cooling within production environments. Manufacturing plants can monetize waste heat through the deployment of absorption chillers, aligning with circular economy principles.
- IT Infrastructure:This segment includes data centers and server rooms that require continuous, high-capacity cooling to prevent equipment overheating and ensure operational reliability. The expansion of IT infrastructure globally is a primary growth catalyst for chiller demand.
- Facilities Management:This sector involves managing the cooling needs of large commercial and institutional buildings, often through integrated HVAC systems and long-term maintenance contracts.
- Research Laboratories:These facilities require precise temperature control for sensitive experiments and equipment, demanding reliable chiller performance with tight operational tolerances.
- Hospitality Venues:Hotels, resorts, and convention centers use chillers for comfort cooling in guest areas, public spaces, and event halls, prioritizing quiet operation and energy efficiency.
- Educational Institutions:Universities and schools rely on chillers for climate control in classrooms, libraries, and administrative buildings, focusing on cost-effectiveness and energy efficiency for large campuses.
The dominant end-user segment is Manufacturing Plants, with IT Infrastructure showing pronounced growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global scroll and absorption chillers market originated with significant advancements in refrigeration technology in the United States and Europe during the 20th century. Early industrial applications and commercial HVAC systems drove initial market scaling. Today, diverse regional demands and regulatory landscapes shape the continued evolution of chiller deployment across continents.
United States
Data center expansion and commercial building retrofits drive demand for advanced chiller systems in the United States. The US EPA's refrigerant management programs under the AIM Act mandate a transition to low-GWP refrigerants. Major technology clusters in Northern Virginia and Texas continue to invest heavily in high-density cooling infrastructure.
China
China's rapid industrialization and large-scale commercial construction projects create substantial demand for both scroll and absorption chillers. The country's dual carbon goals actively promote energy-efficient cooling technologies, particularly absorption chillers utilizing waste heat. Manufacturing hubs like the Yangtze River Delta are significant consumers of process cooling.
Germany
Industrial process cooling and stringent energy efficiency standards underscore chiller demand in Germany. The EU's F-Gas Regulation pushes for the adoption of low-GWP refrigerants across the HVAC sector. Advanced manufacturing facilities in Bavaria and Baden-Württemberg require precise temperature control for production.
Japan
Energy conservation initiatives and high-density urban development characterize the chiller market in Japan. Policies from METI encourage the deployment of high-efficiency cooling systems in commercial and institutional buildings. Major metropolitan areas like Tokyo prioritize space-saving and quiet chiller solutions for urban infrastructure.
India
Commercial infrastructure development and expanding manufacturing capabilities fuel chiller market growth across India. Government initiatives, including PLI schemes, promote domestic manufacturing and energy-efficient industrial practices. New industrial corridors and smart city projects across states like Maharashtra and Gujarat require reliable cooling solutions.
Global Scroll and Absorption Chillers Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological sophistication and service integration in the chiller market. The market exhibits a tiered structure, with global HVAC solution providers and specialized industrial cooling manufacturers. Key archetypes include full-spectrum HVAC conglomerates, niche absorption chiller specialists, and regional scroll chiller producers. Companies pursue strategic partnerships for technology co-development and expand geographic reach to new construction markets.
Global HVAC solution providers like Daikin Industries, a Japanese corporation, exemplify innovation in high-efficiency inverter scroll technology. Carrier Corporation, a US-based entity, leverages its extensive distribution network for large-scale projects globally. Johnson Controls, also a US-based company, positions its absorption chillers for waste heat recovery, particularly within manufacturing. These entities showcase diverse strategies, from product-specific technological leadership to comprehensive solution provision and application-specific optimization, catering to varied market demands.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| LG Electronics |
| Daikin Industries |
| Carrier Corporation |
| Yazaki Energy Systems |
| Johnson Controls |
| Broad Air Conditioning |
| Thermax |
| Trane Technologies |
| Others |
Cost & Logistics Intelligence
A clear performance tiering between standard efficiency and high-efficiency chillers dictates both pricing and the complexity of the supply chain. This divergence is particularly evident in the integration of low-GWP refrigerant systems and advanced control technologies.
Pricing Analysis
Project-based pricing dominates the scroll and absorption chillers market, particularly for large-scale commercial and industrial applications. Price differentiation stems from system efficiency ratings and compliance with evolving refrigerant regulations like the EU's F-Gas. Pricing pressure stems from intense competition among manufacturers for standard scroll units. Commercial cooling buyers exhibit higher price sensitivity compared to hyperscale data centers seeking customized, high-reliability solutions.
Supply Chain Analysis
Compliance with international safety and performance certifications like CE marking and UL standards gates market access for chiller components. Geographic supply concentration for key components, including compressors and specialized heat exchangers, centers on China, Japan, and Germany. The supply chain relies on a consistent supply of refrigerants, creating vulnerability to phase-down schedules under the US EPA's AIM Act. Distribution runs through established networks of HVAC contractors and direct sales channels to large industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global chiller market presents a geographic-arbitrage opportunity, particularly leveraging China's lower manufacturing costs for absorption chillers against Europe's stringent F-Gas refrigerant regulations driving demand for new technologies.
For Market Incumbents: Extend investment in R&D for natural refrigerant-based scroll and absorption chillers to mitigate the threat of stricter global environmental regulations. Consolidate market share by acquiring specialized firms with expertise in A2L refrigerant handling and waste heat recovery technologies. This proactive approach counters emerging low-GWP technology entrants and addresses the ongoing phase-down of high-GWP refrigerants.
For New Entrants and Emerging Players: Specialized HVAC engineering firms represent a key channel to target underpenetrated district cooling networks in Southeast Asia. Focus on modular chiller systems designed for rapid deployment in edge computing facilities, offering flexible capacity. A go-to-market angle emphasizing Cooling-as-a-Service models can overcome high initial capital outlay barriers for smaller commercial clients.
For Investors and Strategic Acquirers: Consolidation pressure builds where refrigerant compliance costs and R&D demands strain smaller manufacturers. Long-term viability favors companies with deep expertise in high-efficiency absorption chillers or advanced scroll technology for data centers. Target specialized firms offering innovative waste heat recovery solutions or modular system integration. A signal to watch is the accelerating adoption rate of A2L refrigerants in new commercial installations.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Low-GWP Refrigerant R&D | Ensures compliance with EU F-Gas Regulation and US EPA AIM Act, maintaining market access. |
| Expand Modular Chiller Production | Addresses evolving buyer preferences for scalable and flexible cooling systems in commercial applications. |
| Acquire Waste Heat Recovery Specialists | Captures opportunities in industrial process cooling, leveraging existing manufacturing plant infrastructure. |
| Develop Cooling-as-a-Service Models | Disrupts traditional sales channels by reducing upfront capital expenditure for large commercial real estate. |
| Strengthen Data Center Cooling Portfolio | Meets escalating demand from hyperscale facilities requiring high-density, reliable chiller solutions. |
Research Approach
Bottom-up data center and industrial process cooling end-use modeling reconciled against top-down chiller manufacturer supply-side tracking forms the analytical core. This approach integrates primary interviews with HVAC engineers, facility managers, and refrigerant suppliers. Secondary validation draws from EPA reports, EU F-Gas Regulation documents, and industry association data, ensuring robust triangulation.
Historical trendline analysis across the analysis window informed the projection of future market trajectories. The framework models segmentation dimensions including product type, application, installation method, and end-user. Compound annual growth rates were derived from a multi-factor regression analysis. Key forecast inputs include data center capacity growth and industrial construction spending.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts and raw material price volatility. Forecasts reflect documented assumptions regarding technological advancements. A model refresh is warranted upon material change in global refrigerant policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Heat Pipe Market
Cooling Systems
Process Chillers Market
Cooling Systems
Portable Chiller Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Aftercoolers Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Global Chiller Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Transformer Oil Coolers Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Cryosystem Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market