
 Asia-Pacific Underground Coal Gasification Market | 2026-2036
Asia-Pacific Underground Coal Gasification Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Underground Coal Gasification Market Outlook
High-efficiency syngas output specifications are redrawing competitive benchmarks across the Asia-Pacific Underground Coal Gasification landscape. Adani Group leverages its integrated energy infrastructure to anchor large-scale project development in India's coal corridors. Linc Energy Ltd. sustains technology leadership through specialized drilling and controlled combustion expertise. Carbon Energy Limited differentiates by occupying the pilot-to-commercial transition segment with proprietary well-completion systems.
Underground coal gasification converts unmineable coal deposits into combustible syngas through in-situ controlled combustion, operating at subsurface temperatures between 800°C and 1,800°C with oxidant injection via drilled boreholes. The process yields synthesis gas for power generation, chemical feedstocks, or synthetic fuel production without conventional mining extraction. Fixed bed gasification dominates current deployment due to lower capital intensity and established engineering protocols, while plasma gasification represents the fastest-growing technology tier as operators pursue higher thermal efficiency and reduced environmental residuals. Chemical production applications command premium margin pools given syngas-to-methanol and syngas-to-ammonia value chains, whereas power generation absorbs the largest volume share through direct turbine integration.
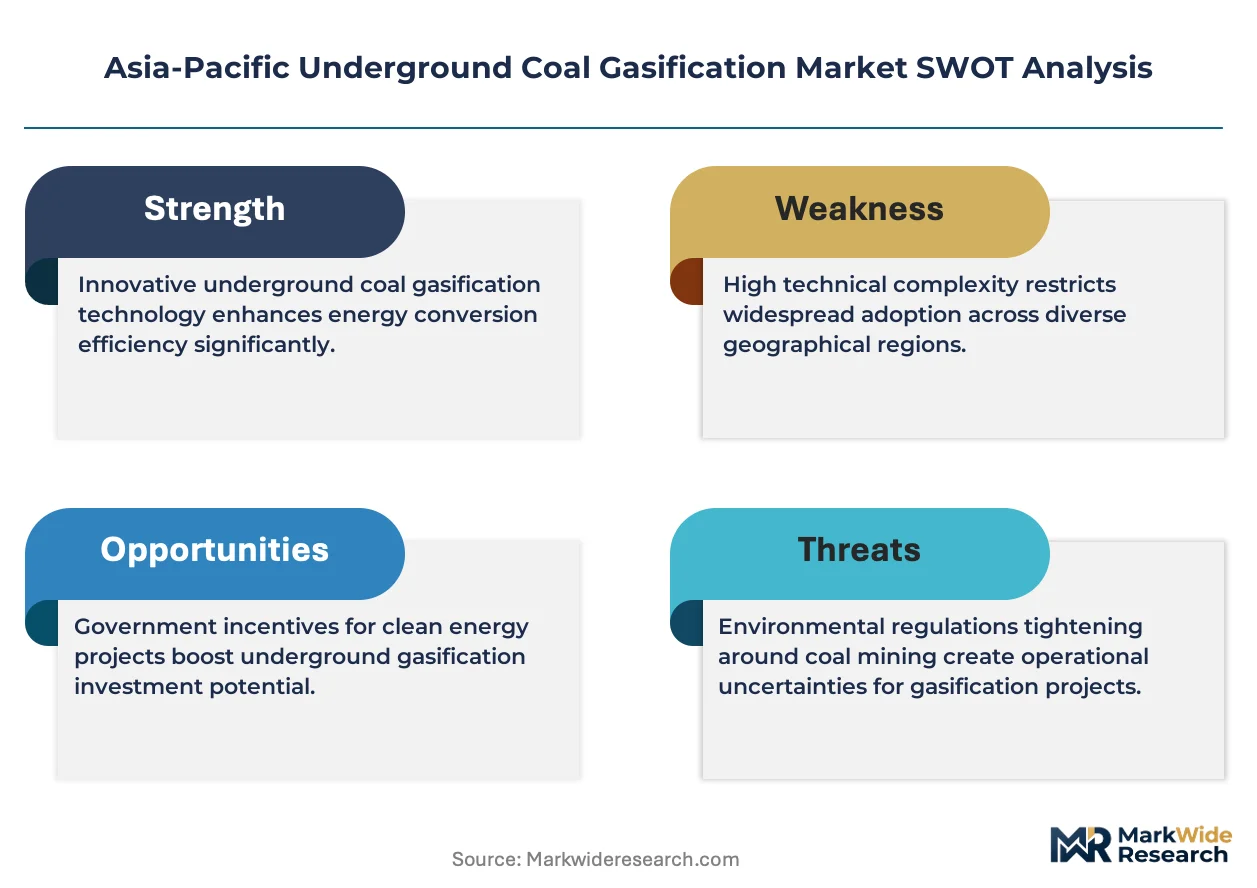
India's Ministry of Coal and China's MIIT shape project approval pathways through domestic resource utilization mandates and clean coal conversion standards, while Australia's state-level environmental regulators impose groundwater protection protocols that determine site eligibility. Compliance with China's GB emissions frameworks and India's CEA technical specifications for syngas quality determines market access for technology providers. Stakeholders must monitor evolving subsurface property rights regimes and carbon accounting methodologies as these will determine which projects advance from pilot to commercial scale.
Market Dynamics
Deep seam thermal extraction economics are reconfiguring project viability thresholds across Asia-Pacific energy corridors. Controlled subsurface combustion protocols developed for 800-1,800°C operating envelopes now enable commercial-scale syngas yields from previously uneconomic coal deposits.
Growth Catalysts
- MIIT Clean Coal Conversion Standards:China's mandatory syngas quality benchmarks accelerate technology provider certification timelines and unlock state-backed project financing for western province developments.
- India's Domestic Resource Utilization Mandates:Ministry of Coal directives prioritize in-situ gasification over imports for power generation feedstocks in Jharkhand and Odisha coal belts.
- Plasma Gasification Thermal Efficiency:Next-generation oxidant injection systems reduce environmental residuals while expanding synthetic fuel production economics for chemical sector offtake.
Market Restraints
- Groundwater Protection Protocols:Australian state environmental regulators impose site eligibility constraints that extend permitting timelines and inflate pre-development capital requirements.
- Deep Drilling Cost Volatility:Specialized directional boring equipment and high-temperature well completion materials concentrate supply risk with limited Asia-Pacific equipment fabricators.
- Surface Solar-Wind Substitution:Declining levelized costs for renewable electricity generation erode syngas-to-power project margins in coastal demand centers.
Strategic Opportunities
- Mongolia's Unmineable Seam Reserves:Vast shallow-depth coal deposits with minimal population overlay offer greenfield project economics superior to established mining jurisdictions.
- Carbon Capture Integration:Syngas processing with subsurface CO2 sequestration creates compliance pathways under emerging emissions trading frameworks.
- Chemical Feedstock Pivot:Ammonia and methanol producers in South Korea and Japan seek long-term syngas supply contracts to decarbonize Haber-Bosch process inputs.
Industry Challenges
- Subsurface Geologist Talent Scarcity:Expertise in coal seam characterization and cavity growth modeling remains concentrated with legacy petroleum reservoir engineers requiring multi-year retraining.
- CEA Technical Specification Compliance:India's Central Electricity Authority syngas quality certification demands extended pilot testing periods before commercial offtake agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Underground Coal Gasification Market |
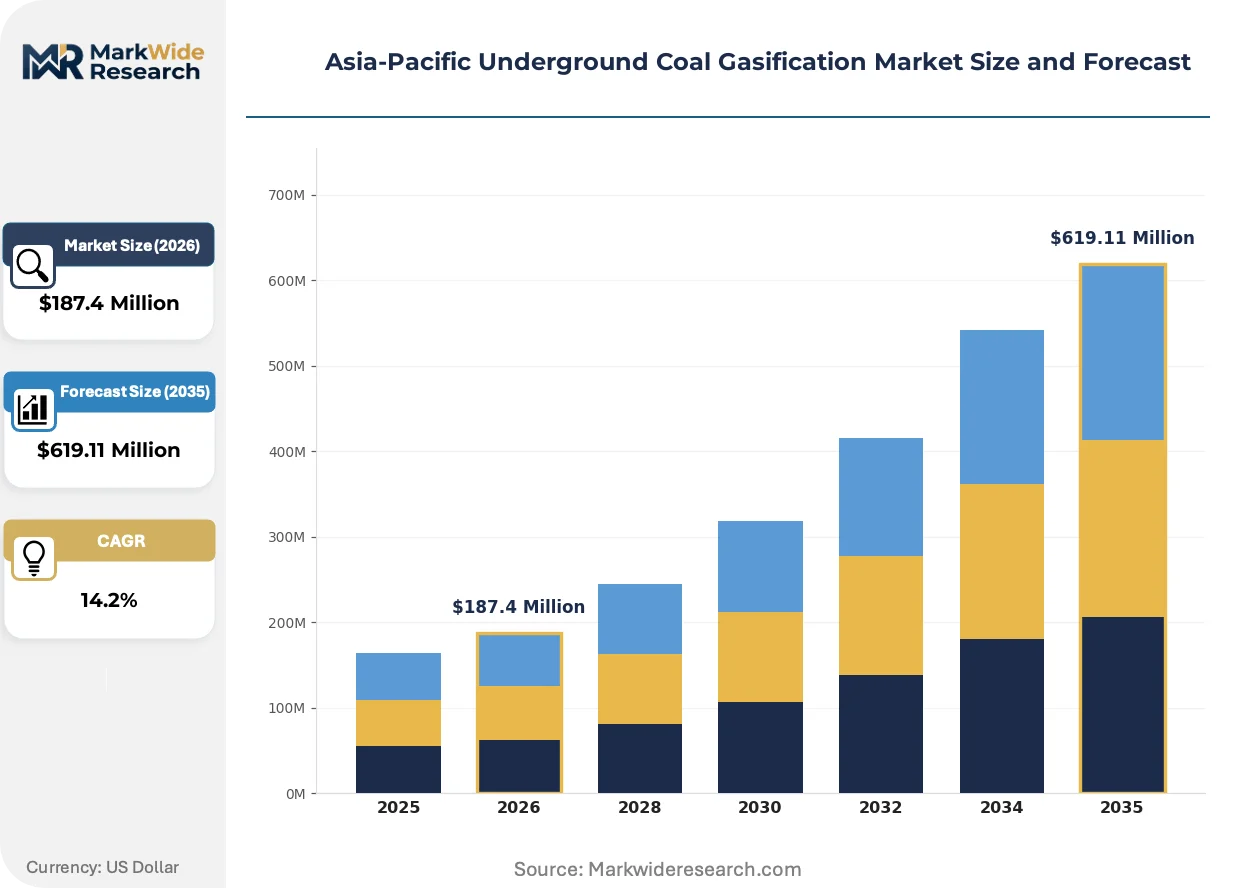
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fixed Bed Gasification, Fluidized Bed Gasification, Plasma Gasification, Hybrid Gasification Application: Power Generation, Chemical Production, Industrial Heating, Synthetic Fuels End User: Utilities, Oil & Gas, Chemical Manufacturers, Power Plants Deployment: Onshore Facilities, Offshore Facilities, Pilot Projects, Large-Scale Operations |
| Companies Covered | Adani Group, Linc Energy Ltd., Carbon Energy Limited, Cougar Energy Limited, SinoCoking Coal, ONGC, Sasol Limited, Sedin Engineering Co. Ltd., ThyssenKrupp AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Underground Coal Gasification Market Strategic Shifts
Process intensification and digital subsurface monitoring are compressing the pilot-to-commercial transition timeline for controlled combustion operations. Technology providers now embed real-time cavity mapping with predictive oxidant flow algorithms.
Plasma gasification is decomposing the thermal efficiency ceiling that constrained fixed-bed system economics. Chemical producers in China's Sichuan and Shaanxi provinces are retrofitting pilot installations with high-temperature plasma torches. This technology is decomposing the historical trade-off between capital intensity and syngas calorific value, enabling smaller-scale commercial units.
China's GB emissions frameworks now mandate continuous groundwater quality monitoring for all subsurface energy extraction permits. Industrial consequence includes mandatory dual-casing well designs with real-time sensor telemetry. Western province operators face the steepest compliance ramps, with Xinjiang and Inner Mongolia projects deploying automated leak detection systems ahead of enforcement deadlines.
Long-term syngas offtake contracting is displacing spot market sales as the dominant procurement model. Chemical sector buyers in Japan and South Korea now demand 15-20 year supply agreements with indexed pricing. This shift concentrates counterparty risk assessment capabilities among integrated energy traders with balance sheet capacity for project finance participation.
Asia-Pacific Underground Coal Gasification Market Segmentation
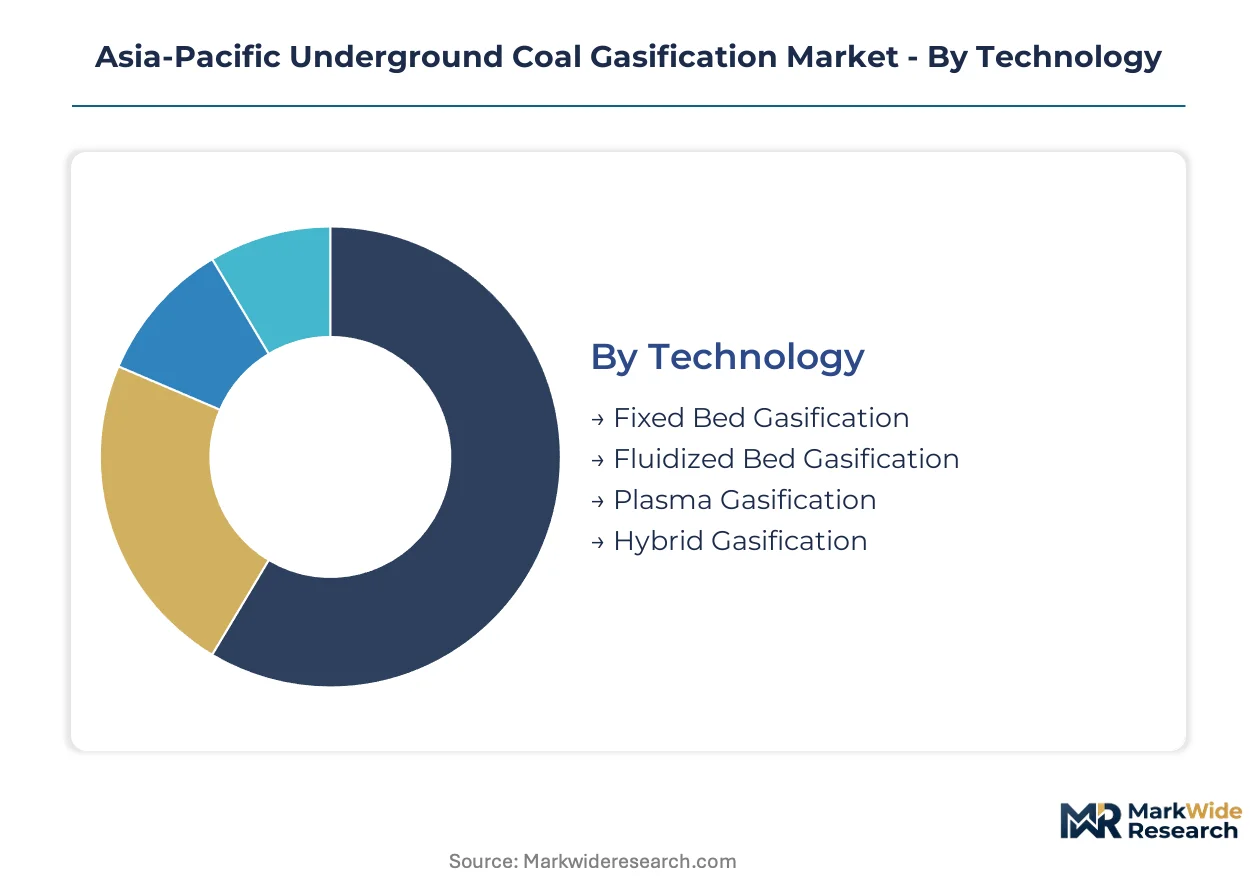
Technology selection determines capital intensity and syngas calorific value for Asia-Pacific project developers. Application mix shapes offtake contracting structures and margin profiles across the value chain.
Technology:
Fixed bed systems flow through established EPC contractors with proven engineering protocols, while plasma and hybrid configurations channel through specialized technology licensors with proprietary equipment packages.
- Fixed Bed Gasification:Operates with stationary coal beds and gravity-fed oxidant distribution at moderate thermal intensities. Demand concentrates in India's Jharkhand and Odisha coal belts where CEA technical specifications favor proven operational track records for grid-connected power projects.
- Plasma Gasification:Deploys high-temperature plasma torches exceeding 3,000°C to achieve complete carbon conversion and minimal tar formation. Chemical producers in China's Sichuan and Shaanxi provinces are retrofitting pilot installations to capture premium methanol and ammonia feedstock margins.
- Fluidized Bed Gasification:Suspends pulverized coal in upward-flowing oxidant streams for uniform temperature distribution. China's MIIT clean coal conversion standards accelerate certification for western province deployments.
- Hybrid Gasification:Combines fixed bed reliability with plasma-stage polishing for variable seam quality. Australian developers evaluate this configuration for groundwater-sensitive sites with extended permitting timelines.
Fixed bed gasification dominates installed base. Plasma gasification is where expansion concentrates.
Application:
Power generation absorbs the largest capital deployment, while chemical production commands superior margin capture through long-term offtake agreements.
- Power Generation:Direct syngas-to-turbine integration supplies baseload electricity to grid operators. India's Ministry of Coal prioritizes this pathway for stranded coal assets in eastern states with transmission infrastructure proximity.
- Chemical Production:Syngas-to-methanol and syngas-to-ammonia value chains serve Haber-Bosch process decarbonization. South Korean and Japanese chemical manufacturers negotiate 15-20 year supply contracts with indexed pricing structures.
- Industrial Heating:Direct syngas combustion replaces coal in cement and steel process heat applications. China's GB emissions frameworks mandate continuous monitoring for these installations.
- Synthetic Fuels:Fischer-Tropsch synthesis converts syngas to diesel and jet fuel substitutes. Mongolia's shallow-depth reserves offer greenfield economics for export-oriented synthetic fuel projects.
Power generation commands volume leadership. Chemical production is climbing the fastest.
End User:
Procurement authority concentrates with integrated energy groups possessing balance sheet capacity for project finance participation.
- Utilities:State-owned power generators in India and China drive pilot-to-commercial transitions through domestic resource utilization mandates.
- Chemical Manufacturers:Ammonia and methanol producers seek captive syngas supply to decarbonize process inputs under emerging emissions trading frameworks.
- Oil & Gas:Integrated energy majors evaluate UCG for synthetic fuel production and carbon capture integration opportunities.
- Power Plants:Independent generators assess syngas co-firing for existing coal turbine retrofits in Australia's National Electricity Market.
Utilities anchor current demand. Chemical manufacturers represent the steepest expansion trajectory.
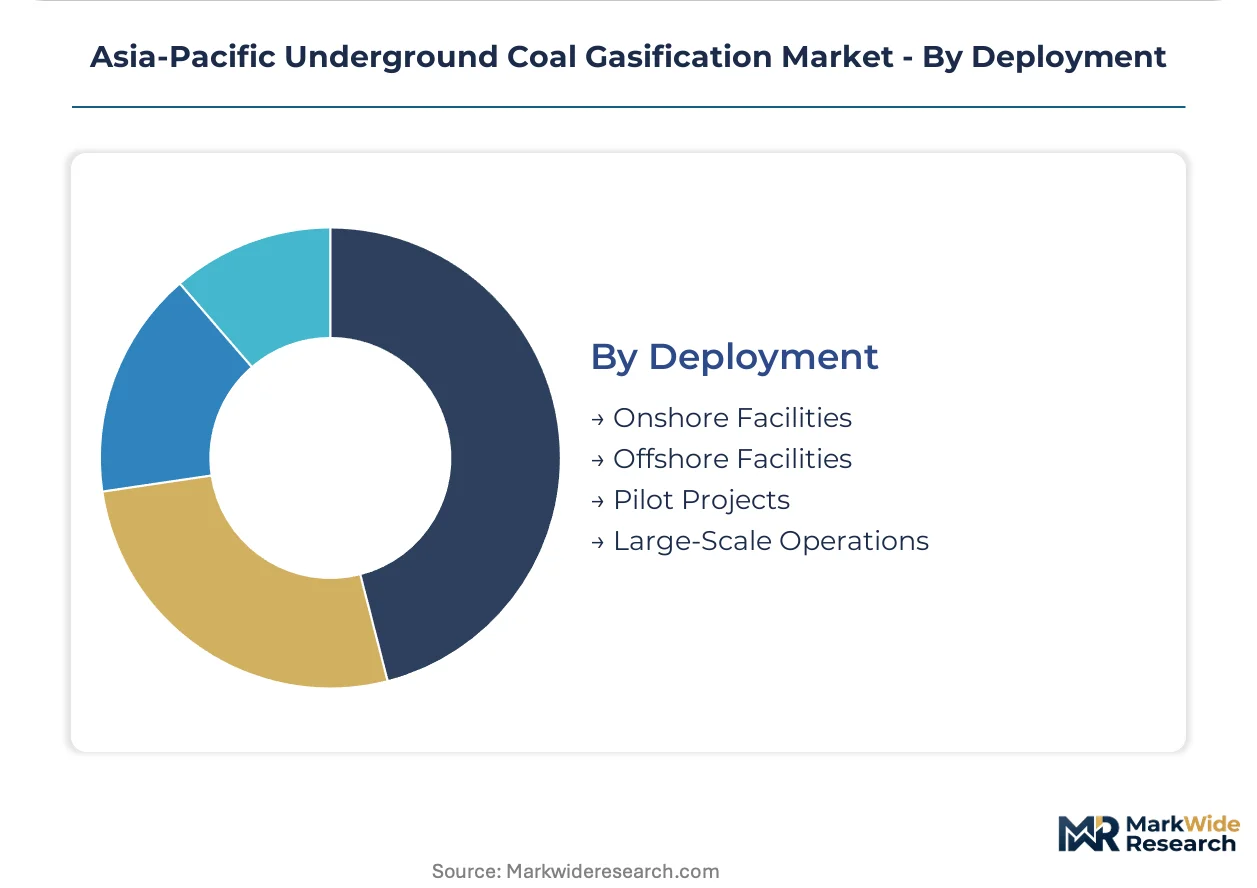
Deployment:
Project scale determines regulatory pathway complexity and capital access conditions across Asia-Pacific jurisdictions.
- Pilot Projects:Sub-commercial installations validate cavity growth models and oxidant flow algorithms. China's western provinces host the densest concentration of MIIT-supervised pilot programs.
- Large-Scale Operations:Commercial syngas production exceeding 100 million standard cubic feet per day requires extended CEA certification periods in India.
- Onshore Facilities:Terrestrial drilling operations access deep unmineable seams in Xinjiang and Inner Mongolia with automated leak detection systems.
- Offshore Facilities:Subsurface gasification of submerged coal deposits remains pre-commercial with Australian regulators evaluating groundwater protection protocols for coastal applications.
Pilot projects dominate current activity. Large-scale operations concentrate expansion investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented syngas-to-chemicals projects in eastern China and South Korea contrast with import-dependent energy security drives in India and Japan. Australia balances domestic synthetic fuel ambitions against LNG export commitments. The region's UCG development clusters around four national jurisdictions with distinct regulatory pathways and resource endowments.
China
Western province coal basins in Xinjiang and Inner Mongolia host the densest concentration of MIIT-supervised pilot-to-commercial transitions. The ministry's clean coal conversion standards mandate continuous groundwater monitoring with automated leak detection systems. Sichuan and Shaanxi chemical producers retrofit installations with high-temperature plasma configurations to capture methanol and ammonia feedstock margins.
India
Jharkhand and Odisha coal belts drive state-owned utility demand for grid-connected power generation from stranded deep seams. Ministry of Coal directives prioritize domestic resource utilization over imported LNG for baseload supply. The Central Electricity Authority's syngas quality certification extends pilot testing timelines before commercial offtake agreements in eastern states.
Australia
Queensland and South Australia evaluate controlled subsurface combustion for synthetic fuel exports to Asian chemical buyers. State environmental regulators impose groundwater protection protocols that inflate pre-development capital requirements. Linc Energy's technology licensing activities concentrate in these jurisdictions despite extended permitting timelines.
South Korea
Ammonia and methanol producers in Ulsan and Yeosu industrial complexes negotiate long-term syngas supply contracts to decarbonize Haber-Bosch process inputs. The country's emissions trading framework creates compliance premiums for low-carbon feedstock sourcing. Korean chemical manufacturers index 15-20 year offtake agreements to regional LNG price benchmarks.
Japan
Metropolitan energy utilities assess UCG syngas for power generation diversification alongside nuclear restart schedules. METI's clean coal technology roadmaps support pilot project feasibility studies in Hokkaido coal fields. Japanese trading houses provide project finance participation for Mongolian greenfield developments with export-oriented synthetic fuel economics.
Asia-Pacific Underground Coal Gasification Market Competitive Environment
Listed energy conglomerates compete with private technology specialists across project development and equipment supply vectors. The vendor base organizes into three tiers: integrated energy groups with balance sheet capacity, specialized drilling and combustion technology licensors, and regional engineering contractors with state-backed project mandates. Strategic moves concentrate on pilot-to-commercial transition partnerships and proprietary well-completion system licensing.
Within the integrated energy tier, Adani Group anchors large-scale project development through captive coal corridor access and downstream power infrastructure. Linc Energy Ltd. and Carbon Energy Limited exemplify specialized technology archetypes, occupying distinct positions in controlled combustion expertise and pilot-to-commercial transition segments respectively. Cougar Energy Limited and SinoCoking Coal represent regional specialists with jurisdiction-specific project mandates.
| Leading Market Players |
|---|
| Adani Group |
| Linc Energy Ltd. |
| Carbon Energy Limited |
| Cougar Energy Limited |
| SinoCoking Coal |
| ONGC |
| Sasol Limited |
| Sedin Engineering Co. Ltd. |
| ThyssenKrupp AG |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with indexed pricing lock in supply access and price visibility for Asia-Pacific UCG developers, binding chemical manufacturers in South Korea and Japan to 15-20 year commitments that shield project financiers from spot market volatility while locking in margins against LNG benchmark fluctuations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Asia-Pacific UCG landscape. Price differentiation rests on syngas calorific value grade and CEA certification tier, with premium contracts commanding higher indices for grid-connected power projects. Cost compression in plasma gasification installations is intensifying because high-temperature torch fabricators face limited regional supply. Chemical manufacturers exhibit the highest price sensitivity due to Haber-Bosch process margin pressures, while state-owned utilities absorb pricing premiums for energy security.
Supply Chain Analysis
Specialized directional boring equipment fabrication concentrates supply risk with limited Asia-Pacific equipment fabricators. Manufacturing gravity centers on China, South Korea, and Germany for high-temperature well completion materials. Raw material dependencies include plasma torch electrodes, dual-casing steel alloys, and real-time sensor telemetry systems. Single-source vulnerability runs through plasma torch licensors with proprietary oxidant injection patents. Distribution feeds from technology licensors through EPC contractors to project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across technology tiers and application segments creates niche entry points, as plasma gasification retrofits displace fixed-bed dominance and chemical feedstock demand splits from power generation procurement patterns.
For Market Incumbents: Secure captive coal corridor access through joint ventures with state-owned mining enterprises in Jharkhand and Xinjiang. Deepen backward integration into plasma torch manufacturing to offset equipment supply bottlenecks. Lock in long-term offtake with Korean and Japanese chemical manufacturers before emerging technology providers achieve CEA certification.
For New Entrants and Emerging Players: Pilot-to-commercial transition services represent an under-served layer where incumbents lack specialized project management bandwidth. Target Australia's extended permitting pipeline with groundwater monitoring and compliance bundling. Enter through hybrid gasification licensing for sites with cavity stability uncertainty.
For Investors and Strategic Acquirers: Proprietary well-completion system developers with MIIT certification pathways offer the strongest acquisition profile. Long-term viability hinges on carbon capture integration economics across the analysis window. Monitor China's GB emissions enforcement deadlines as the inflection signal for commercial scale-up velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Gasification Retrofit | Shaanxi chemical producers capture methanol feedstock premiums through higher thermal efficiency. |
| Long-term Syngas Offtake Agreement | Ulsan ammonia manufacturers lock in 15-year supply to decarbonize Haber-Bosch inputs. |
| Backward Integration into Drilling Equipment | Project developers reduce exposure to limited Asia-Pacific high-temperature well fabricators. |
| Carbon Capture Integration | Xinjiang operators create compliance pathways under China's emerging emissions trading framework. |
| Groundwater Monitoring Technology Licensing | Australian developers accelerate permitting timelines through automated leak detection deployment. |
Study Parameters
The analysis maps fixed bed, plasma, fluidized bed, and hybrid gasification configurations, each validated through utility planning officers, chemical manufacturer procurement leads, EPC contractor project managers, and state regulator environmental compliance officers. Primary fieldwork combined structured interviews with secondary validation against MIIT clean coal conversion guidelines, CEA technical specifications, Australian state environmental protocols, and project development databases. Bottom-up installation capacity estimates triangulated with top-down energy demand projections across the Asia-Pacific region.
Consistency checks validated volume and value outputs against IEA clean coal technology roadmaps, EIA international energy outlooks, and regional emissions trading framework adoption timelines. Segmentation dimensions modeled include gasification technology tier, application pathway, end-user procurement authority, and project deployment scale. CAGRs derived from slope-intercept trajectory fitting across the projection horizon, with inputs from syngas calorific value yield curves and oxidant injection efficiency benchmarks.
Underlying assumptions cover MIIT certification timeline adherence, CEA pilot testing period durations, and groundwater protection protocol stability, with deviation risk concentrated in regulatory enforcement acceleration and renewable electricity substitution rates. Practitioners should keep alternative scenarios live as China's dual carbon goal implementation and India's domestic resource utilization mandate enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
North America Proppants Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Natural Gas Market
Oil & Gas
Peru Oil and Gas Downstream Market
Oil & Gas
Perforating Gun Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Bunker Liners Market