
 Marine Cooling Systems Market | 2026-2036
Marine Cooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Cooling Systems Market Insights
Marine thermodynamics engineering talent is collapsing across European shipyards, forcing OEMs to redesign cooling architectures for simpler commissioning. Alfa Laval leverages its centrifugal separation heritage to dominate compact heat exchanger supply for container vessels. Wärtsilä anchors its position through backward integration into engine-integrated cooling modules that reduce installation complexity. Caterpillar Marine competes by sustaining dense service networks across Latin American and African ports where technical labor scarcity is most acute.
Marine cooling systems regulate propulsion engine, auxiliary machinery, and cargo space temperatures through closed-loop water circuits, plate heat exchangers, and refrigerant-based chillers operating in corrosive seawater environments with typical titanium or cupronickel metallurgy to resist chloride attack. Their primary purpose is preventing thermal overload of diesel and dual-fuel engines while maintaining emissions compliance across variable load profiles. Heat exchangers command the largest installed base due to universal fitment across vessel classes, though hybrid cooling architectures are gaining share fastest as operators balance capital cost against IMO efficiency mandates. Cargo ships represent the deepest retrofit opportunity because aging fleets face escalating EEXI compliance deadlines that demand cooling system upgrades to support engine de-rating or exhaust gas recirculation.
IMO's EEXI and CII frameworks compel vessel operators to prioritize cooling efficiency as a pathway to carbon intensity reduction, while the EU MRV and FuelEU Maritime initiatives tighten operational monitoring requirements that implicate thermal system performance data. The US Coast Guard and classification societies including DNV and Lloyd's Register enforce material certification standards for heat exchanger pressure boundaries that shape supplier qualification timelines. Stakeholders must monitor whether ammonia fuel adoption timelines outpace the development of compatible cooling chemistries and safety-rated refrigeration architectures.
Market Dynamics
IMO's carbon intensity frameworks are forcing a wholesale redesign of thermal architectures as shipowners face hard EEXI compliance deadlines that cannot be met without cooling system upgrades.
Growth Catalysts
- EEXI retrofit mandates:Cargo vessel operators must upgrade heat exchangers and cooling circuits to enable engine de-rating strategies that satisfy IMO carbon intensity reduction requirements.
- South Korean shipbuilding clusters:Ulsan and Geoje production hubs are accelerating procurement of advanced thermal management systems for newbuild LNG carriers and container vessels.
- Dual-fuel engine proliferation:Methanol and ammonia-ready propulsion systems require redesigned cooling architectures with higher thermal rejection capacity and corrosion-resistant metallurgy.
Market Restraints
- Titanium price volatility:Heat exchanger manufacturers face margin compression from fluctuating raw material costs for chloride-resistant titanium tubing and plate stock.
- European engineering talent scarcity:Marine thermodynamics expertise is collapsing across German, Dutch, and Norwegian shipyards, forcing OEMs to simplify system designs.
- Ammonia cooling chemistry immaturity:Compatible thermal fluids and safety-rated refrigeration architectures for ammonia fuel systems remain underdeveloped, delaying adoption timelines.
Strategic Opportunities
- Latin American port service networks:Dense aftermarket infrastructure for cooling system maintenance remains underbuilt across Brazilian and Chilean maritime hubs.
- Hybrid cooling architectures:Converging seawater loops with refrigerant-based chillers offers efficiency gains for cruise operators facing FuelEU Maritime monitoring requirements.
- EU MRV data integration:Thermal system performance monitoring capabilities can be bundled with compliance reporting tools for European-flagged vessel operators.
Industry Challenges
- Commissioning complexity:Simplified cooling system designs must still satisfy Lloyd's Register and DNV material certification standards for pressure boundaries.
- Retrofit integration friction:Legacy engine rooms lack physical space for expanded heat rejection equipment required by exhaust gas recirculation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Cooling Systems Market |
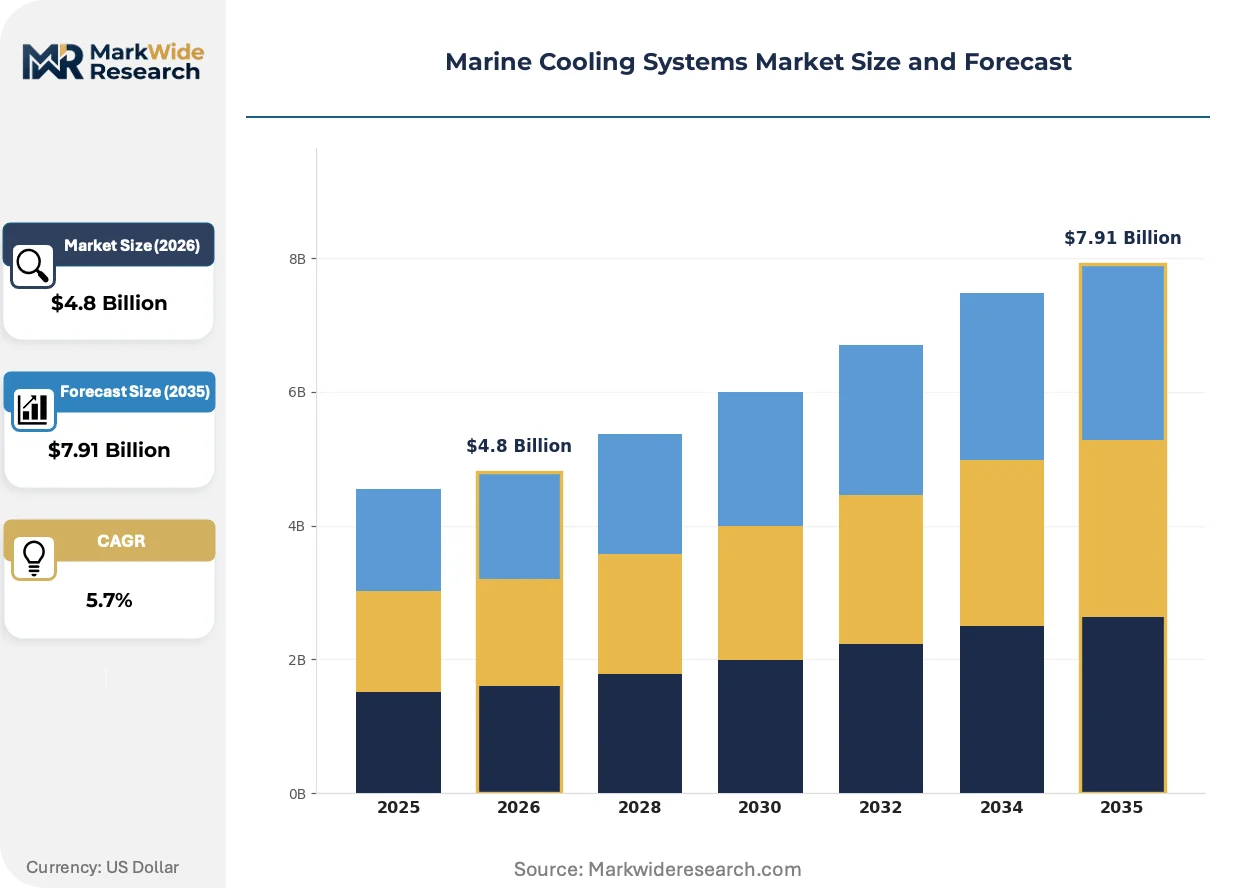
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Exchangers, Chillers, Pumps, Fans Technology: Water Cooling, Air Cooling, Refrigeration, Hybrid Cooling Application: Commercial Vessels, Naval Ships, Yachts, Cargo Ships End User: Shipbuilders, Marine Operators, Maintenance Providers, Research Institutions |
| Companies Covered | MAN Energy Solutions, Caterpillar Marine, Alfa Laval, Orca Marine Cooling Systems, CP Performance, Volvo Penta, Yanmar, EJ Bowman, Wärtsilä, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Cooling Systems Market Trends and Innovations
Compact thermal management solutions are displacing conventional centralized cooling plants as vessel operators prioritize weight reduction and machinery space optimization.
Plate heat exchanger technology is miniaturizing through advanced titanium brazing techniques that maintain thermal duty in 40% smaller footprints. Container vessel operators are adopting these compact units aggressively to reclaim cargo capacity. The technology is miniaturizing cooling plant spatial requirements, enabling distributed thermal architectures that eliminate lengthy piping runs.
EU F-Gas Regulation phase-down schedules are accelerating adoption of CO2-based refrigeration cycles in marine chiller applications. Shipowners face refrigerant availability constraints that threaten existing R-404A and R-134a systems. Cruise operators in Mediterranean and Baltic routes are responding fastest, retrofitting galley and HVAC chillers with transcritical CO2 equipment.
After-sales service unbundling is fragmenting traditional OEM maintenance contracts as independent thermal specialists capture cooling system overhaul work. Third-party service providers in Singapore and Rotterdam are building dedicated heat exchanger reconditioning capabilities. This shift is most visible among mid-sized bulk carrier operators seeking to decouple engine maintenance from auxiliary system support.
Marine Cooling Systems Market Segmentation
Marine cooling system procurement patterns diverge sharply between newbuild shipyards and retrofit operators, with each segment demanding distinct technical specifications and service models. Understanding these divisions reveals where capital expenditure concentrates and which technologies face accelerated replacement cycles.
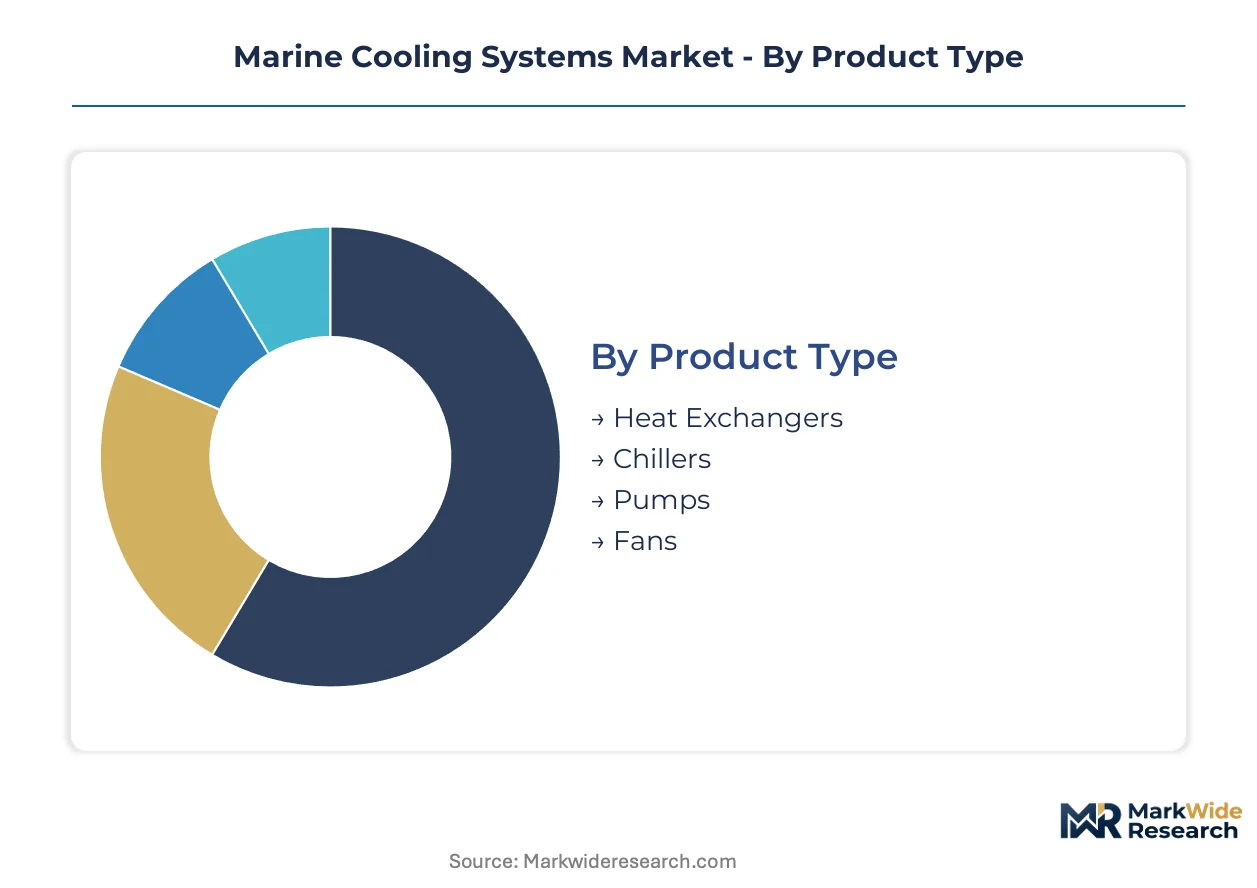
Product Type:
Domestic production dominates heat exchanger and pump supply chains across South Korea and Japan, while European manufacturers export specialized chillers to global retrofit markets.
- Heat Exchangers:Plate and shell-and-tube configurations using titanium or cupronickel metallurgy resist chloride corrosion in seawater loops. Container vessel operators in the Port of Rotterdam cluster are retrofitting compact brazed units to reclaim machinery space for cargo capacity under EEXI compliance pressure.
- Chillers:Refrigerant-based systems regulate HVAC and cargo hold temperatures through vapor compression or emerging CO2 transcritical cycles. Mediterranean cruise operators face EU F-Gas Regulation phase-down deadlines that accelerate R-404A replacement with natural refrigerant architectures.
- Pumps:Centrifugal and positive displacement designs circulate cooling water through engine jackets and heat rejection circuits. Chinese shipyards source these from domestic suppliers to reduce import dependency on European fluid handling equipment.
- Fans:Axial and centrifugal blowers augment air-cooled heat exchanger performance in space-constrained engine rooms. Offshore supply vessel operators in the North Sea specify explosion-rated variants for hazardous zone compliance.
Heat exchangers hold the largest share; momentum sits with chillers as refrigerant regulations force fleet-wide replacement programs.
Technology:
Cost tier stratification separates mature water cooling from premium hybrid architectures that command three to four times the capital outlay but deliver compliance advantages.
- Water Cooling:Closed-loop seawater circuits with plate heat exchangers remain the baseline for propulsion thermal management. German and Dutch shipyards specify these for bulk carrier newbuilds where capital constraints override efficiency optimization.
- Air Cooling:Fin-fan heat rejection eliminates seawater contact, reducing corrosion risk in high-salinity routes. Fishing fleets operating in the Red Sea and Persian Gulf favor these systems to minimize maintenance intervals in extreme chloride environments.
- Refrigeration:Vapor compression chillers support cargo preservation and passenger comfort through mechanical cooling. Reefer container operators on Asia-Europe routes demand these for pharmaceutical and perishable cargo integrity.
- Hybrid Cooling:Converged seawater loops with refrigerant-based chillers optimize thermal rejection across variable load profiles. LNG carriers under construction at Hyundai Heavy Industries in Ulsan integrate these architectures to support dual-fuel engine thermal management.
Water cooling dominates installed base; hybrid configurations are climbing the fastest as dual-fuel propulsion spreads.
Application:
Customer type determines procurement rhythm, with naval programs running decade-long development cycles while cargo operators face compressed retrofit windows.
- Commercial Vessels:Ferries, offshore support vessels, and tugboats require modular cooling plants with rapid maintenance access. Operators in Singapore's port cluster prioritize standardized components to minimize spare parts inventory across mixed fleets.
- Naval Ships:Military specifications demand shock-resistant, redundant thermal systems with electromagnetic compatibility hardening. NATO procurement programs are accelerating adoption of advanced thermal management across frigate and destroyer classes.
- Yachts:Superyacht builders specify whisper-quiet chiller systems with minimal vibration signature for passenger comfort. Mediterranean shipyards in Italy and Turkey compete on aesthetic integration of exposed machinery.
- Cargo Ships:Bulk carriers, tankers, and container vessels present the deepest retrofit opportunity as aging fleets confront EEXI deadlines. Operators in Greece and Germany are upgrading heat exchangers to enable engine de-rating strategies.
Cargo ships command the largest addressable market; naval applications show the steepest expansion trajectory as defense budgets rise.
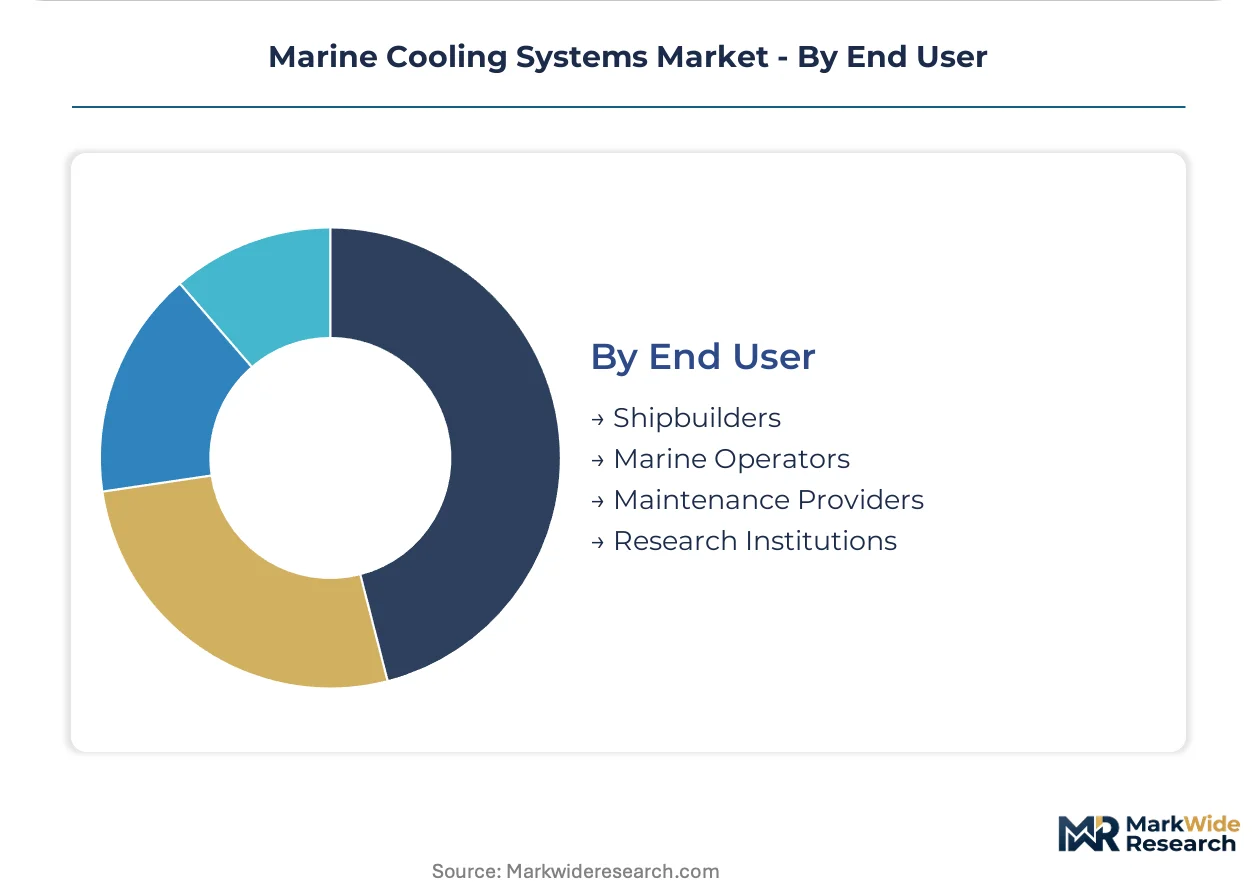
End User:
Margin structure varies dramatically, with shipbuilders capturing equipment markup and maintenance providers securing decade-long service revenue streams.
- Shipbuilders:Hyundai, Samsung, and Daewoo yards in South Korea specify cooling systems during vessel construction, integrating thermal management with propulsion architecture. These customers demand supplier technical support through commissioning and sea trials.
- Marine Operators:Maersk, MSC, and CMA CGM manage fleet-wide cooling system performance across thousands of vessels. Their procurement teams bundle heat exchanger replacements with engine overhaul schedules to minimize off-hire time.
- Maintenance Providers:Independent thermal specialists in Singapore and Rotterdam capture cooling system overhaul work previously bundled with OEM engine contracts. These operators build dedicated plate heat exchanger reconditioning capabilities.
- Research Institutions:Maritime universities and classification society laboratories test novel cooling chemistries and materials for ammonia fuel compatibility. DNV and Lloyd's Register facilities in Norway and the UK validate pressure boundary designs.
Shipbuilders represent the largest equipment revenue pool; maintenance providers are gaining share fastest as service unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean shipyards command premium pricing for advanced thermal management systems, while Chinese manufacturers compete aggressively on standardized cooling equipment for bulk carriers. European yards in Germany and the Netherlands struggle with engineering talent scarcity that compresses margins on complex retrofit projects.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive procurement of hybrid cooling architectures for LNG carriers and container vessels. The Ministry of Trade, Industry and Energy supports shipbuilding competitiveness through targeted R&D subsidies for green propulsion technologies. Ulsan and Geoje production clusters concentrate advanced thermal system integration for dual-fuel engine newbuilds.
China
State-owned shipyards prioritize cost-optimized water cooling systems for bulk carrier and tanker construction. The Ministry of Industry and Information Technology enforces domestic content requirements that favor local pump and heat exchanger suppliers. Shanghai and Jiangsu province manufacturing bases expand plate heat exchanger capacity for export markets.
Germany
Specialized marine engineering firms focus on retrofit consulting for EEXI compliance deadlines facing Greek and German-flagged cargo fleets. The Federal Maritime and Hydrographic Agency enforces stringent material certification standards for pressure equipment on vessels calling at Hamburg and Bremerhaven. Mecklenburg-Vorpommern shipyards concentrate on research vessel and offshore support vessel cooling system integration.
United States
Naval procurement programs accelerate adoption of shock-resistant thermal management systems for frigate and destroyer classes. The US Coast Guard enforces heat exchanger safety standards through its marine safety laboratory certification process. Gulf Coast shipyards in Louisiana and Texas focus on offshore supply vessel cooling system maintenance for deepwater oil operations.
Japan
Engine manufacturers integrate cooling modules with dual-fuel propulsion systems for domestic and export shipyards. The Ministry of Economy, Trade and Industry coordinates ammonia fuel research programs that implicate compatible thermal fluid development. Nagasaki and Kure shipbuilding centers specialize in cruise vessel and ferry cooling plant optimization for passenger comfort requirements.
Marine Cooling Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with Scandinavian and German engineering specialists commanding premium positions while Asian fabricators dominate standardized equipment supply. The market structures around three tiers: integrated propulsion OEMs, dedicated thermal system specialists, and regional component fabricators. Dominant competitive moves include backward integration into engine-integrated cooling modules and geographic expansion of aftermarket service networks into port clusters with technical labor scarcity.
Among Nordic integrated system providers, Wärtsilä and Alfa Laval occupy positions that exemplify the engineering-intensive tier, with the latter representing centrifugal separation heritage applied to compact heat exchanger design. Caterpillar Marine anchors the service-network-driven archetype through dense port presence across Latin American and African maritime hubs.
| Leading Market Players |
|---|
| MAN Energy Solutions |
| Caterpillar Marine |
| Alfa Laval |
| Orca Marine Cooling Systems |
| CP Performance |
| Volvo Penta |
| Yanmar |
| EJ Bowman |
| Wärtsilä |
| Others |
Pricing and Supply Chain Analysis
Ninety-day titanium plate stock inventory cycles at Korean heat exchanger fabricators concentrate pricing power with chloride-resistant metallurgy suppliers while compressing margins for standardized pump assemblers. This inventory-to-pricing linkage intensifies whenever IMO regulatory deadlines accelerate procurement waves.
Pricing Analysis
Configured-to-order pricing for titanium-brazed compact heat exchangers commands a forty-percent premium over standard shell-and-tube units for bulk carrier retrofits. Project-based contracting dominates newbuild procurement at Hyundai Heavy Industries and Samsung Heavy Industries, while transactional spot purchasing prevails for aftermarket pump replacements. Price differentiation hinges on Lloyd's Register certification tier and the inclusion of ten-year spare parts availability guarantees. Cost compression in standard water cooling equipment is intensifying because Chinese shipyards are internalizing pump production under MIIT domestic content mandates. Greek cargo operators exhibit the highest price sensitivity, deferring heat exchanger upgrades until EEXI compliance deadlines force expenditure.
Supply Chain Analysis
Strategic stockpiling of titanium plate and cupronickel tubing distinguishes Korean newbuild yards from European retrofit specialists who run just-in-time inventory on certification documentation. Supply concentration rests on South Korea for advanced hybrid cooling architectures, China for standardized pumps and fans, and Germany for specialized chiller engineering. Raw material dependencies center on titanium sponge from Japanese smelters, refrigerant gases subject to EU F-Gas Regulation phase-down schedules, and precision bearings from Swedish manufacturers. Single-source vulnerability in titanium metallurgy creates exposure to spot price volatility at the London Metal Exchange. Distribution runs through shipbuilder-integrated procurement departments for newbuilds and independent thermal specialists in Singapore and Rotterdam for aftermarket overhaul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine cooling systems sit in early-cycle expansion as dual-fuel engine proliferation forces wholesale thermal architecture redesigns across the installed base. EEXI retrofit mandates provide durable demand visibility independent of newbuild cyclicality.
For Market Incumbents: Compound defensive positioning through backward integration into engine-integrated cooling modules that lock out independent thermal specialists. Secure captive titanium metallurgy supply through long-term offtake agreements with Japanese sponge producers before spot volatility escalates. Invest in Lloyd's Register and DNV certification pre-approval to compress commissioning timelines for talent-scarce European yards. For New Entrants and Emerging Players: Differentiate on ammonia-compatible thermal fluid chemistry development, where incumbent refrigerant expertise creates legacy disadvantage. Target Latin American port service networks in Santos and Valparaíso, where Caterpillar Marine's dense presence has not eliminated independent overhaul opportunity. Pursue white-label heat exchanger reconditioning contracts with Singapore-based maintenance aggregators seeking to decouple from OEM engine service bundles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming marine thermal divisions lacking scale in dual-fuel applications. Five-to-ten-year viability hinges on ammonia fuel adoption timelines outpacing cooling chemistry development gaps. Watch for Lloyd's Register publication of ammonia safety standards as the inflection signal validating premium-priced refrigeration architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Metallurgy | Captive supply of chloride-resistant plate stock insulates Korean fabricators from London Metal Exchange volatility. |
| CO2 Transcritical Chiller Certification | EU F-Gas Regulation compliance positions cruise operators for Baltic and Mediterranean route access. |
| Latin American Service Network Expansion | Dense port presence in Brazilian and Chilean hubs captures overhaul work from technical-labor-scarce regions. |
| Ammonia Thermal Fluid R&D Partnership | Collaboration with DNV and Lloyd's Register accelerates safety-rated refrigeration architecture validation. |
| Hybrid Cooling Architecture Standardization | Modular converged seawater-refrigerant designs reduce commissioning complexity for European shipyards. |
Research Methodology
Desk research of Lloyd's Register certification databases, IMO regulatory filings, and Korean shipyard procurement disclosures preceded structured interviews with thermal system engineering directors, shipyard procurement managers, and independent maintenance provider operations heads. Secondary validation drew from DNV technical papers, EU MRV monitoring system specifications, and customs trade data on titanium plate imports. Bottom-up vessel fleet analysis triangulated against top-down shipbuilding output projections.
Variance decomposition across product type, technology tier, vessel application, and end-user channel shaped the analytical framework over the projection horizon. Modeled segmentation dimensions included heat exchanger metallurgy grade, chiller refrigerant chemistry, propulsion architecture compatibility, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and newbuild orderbook analysis. Industry-specific forecast inputs incorporated EEXI compliance deadline phasing and dual-fuel engine adoption curves at Hyundai Heavy Industries and Samsung Heavy Industries.
The analysis sits within stated boundaries; outcomes outside sustained IMO enforcement of carbon intensity frameworks would require recalibration. Forecasts reflect assumptions on titanium price stability and Korean shipyard capacity utilization. Revision becomes warranted when ammonia fuel adoption timelines accelerate beyond compatible cooling chemistry development capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Portable Chiller Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Solar Fan Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Cryosystem Market
Cooling Systems
Heat Pipe Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Transformer Oil Coolers Market
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Air Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Absorption Chillers Market