
 North America Gas Meter Market | 2026-2036
North America Gas Meter Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gas Meter Market Intelligence
The utility procurement channel is fragmenting across North America as municipal gas distributors and investor-owned utilities diverge on smart grid investment timelines. Itron Inc. sustains technology leadership in AMI-enabled gas metering through embedded communications modules that support remote shutoff and leak detection. Badger Meter differentiates via precision ultrasonic platforms engineered for commercial and industrial custody transfer applications. Landis+Gyr anchors the North American utility landscape with scaled manufacturing capacity serving major metropolitan distribution networks.
North America gas meters are precision volumetric or mass flow measurement instruments, typically constructed with aluminum or composite housings, diaphragm or rotary displacement mechanisms, and temperature-pressure compensation modules, designed to quantify natural gas consumption for billing, safety monitoring, and demand-side management. Smart meters incorporating IoT-enabled wireless communication architectures are displacing analog mechanical units across residential and utility end-user segments, driven by two-way data exchange requirements and real-time leak alerting protocols. Ultrasonic meters command premium positioning in industrial installations where turndown ratios and custody-transfer accuracy standards exceed mechanical device capabilities.
The U.S. Department of Transportation's Pipeline and Hazardous Materials Safety Administration mandates periodic meter accuracy testing and replacement intervals, while the EPA's methane reduction framework incentivizes advanced leak-detection integration in meter hardware. Canada's Measurement Canada enforces stringent accuracy certification under the Electricity and Gas Inspection Act, creating compliance barriers for non-certified equipment suppliers. Stakeholders must monitor evolving state-level building electrification mandates and their downstream effects on new gas connection volumes and meter installation forecasts.
Market Dynamics
The EPA's methane emission reduction mandates are forcing wholesale replacement of mechanical diaphragm meters with ultrasonic and Coriolis systems capable of real-time leak detection and remote shutoff across U.S. and Canadian distribution networks.
Growth Catalysts
- EPA Methane Regulations:Federal emission reduction frameworks mandate advanced leak-detection integration in meter hardware, accelerating procurement of AMI-enabled ultrasonic systems across U.S. utility-scale deployments.
- LNG Export Terminal Expansion:Gulf Coast petrochemical clusters and liquefaction facilities require custody-transfer-grade Coriolis flow measurement with turndown ratios exceeding mechanical device capabilities.
- Canada's Measurement Canada Certification:Stringent accuracy requirements under the Electricity and Gas Inspection Act create compliance-driven replacement cycles for aging residential infrastructure in Ontario and British Columbia.
Market Restraints
- Aluminum and Semiconductor Input Costs:Volatility in commodity housing materials and chip shortages for embedded communications modules compress margins on smart meter production.
- Utility Procurement Fragmentation:Divergent investment timelines between municipal gas distributors and investor-owned utilities in Texas and California create demand unpredictability for manufacturers.
- Building Electrification Mandates:State-level decarbonization targets in New York and Washington threaten new gas connection volumes and long-term meter installation forecasts.
Strategic Opportunities
- Remote Shutoff Integration:AMI platforms with embedded safety modules address liability concerns from U.S. utilities facing wildfire and explosion litigation risks.
- Industrial Ultrasonic Adoption:Underpenetrated commercial segments in the U.S. Midwest present expansion potential for precision mass flow systems replacing rotary displacement meters.
- IoT Convergence with Edge Analytics:Wireless communication architectures combined with on-device processing enable predictive maintenance services as recurring revenue streams.
Industry Challenges
- AMI Integration Complexity:Retrofitting legacy mechanical infrastructure with two-way data exchange protocols requires specialized field engineering capabilities scarce among contractor networks.
- Measurement Canada Certification Timelines:Extended approval cycles for non-domestic equipment suppliers delay market entry and compress product refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gas Meter Market |
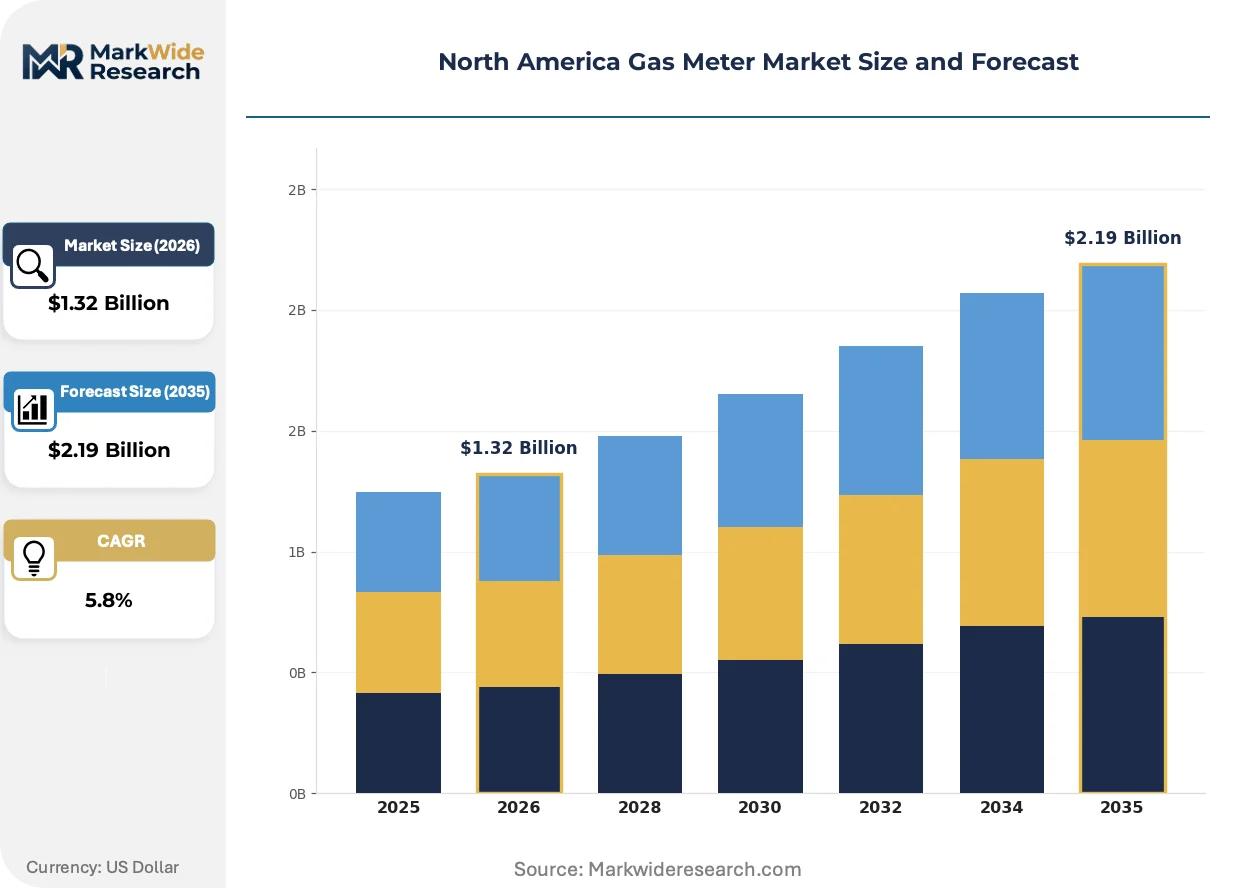
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.19 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Meters, Mechanical Meters, Smart Meters, Ultrasonic Meters Technology: IoT-enabled, Analog, Remote Reading, Wireless Communication End User: Residential, Commercial, Industrial, Utilities Installation: Indoor, Outdoor, Wall-mounted, Portable |
| Companies Covered | Badger Meter, Landis+Gyr, Itron Inc., Sensus Worldwide Holdings Limited, ABB Ltd., Honeywell International Inc., Diehl Stiftung & Co. KG, Schneider Electric, Aclara Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gas Meter Market Strategic Shifts & Innovations
Ultrasonic measurement technology is digitizing gas metering infrastructure while regulatory pressure on methane emissions reshapes procurement specifications and buyer expectations across North American utilities.
Ultrasonic gas metering systems employ transit-time or doppler principles to measure flow without moving parts, eliminating mechanical wear and extending operational lifespans beyond diaphragm alternatives. U.S. investor-owned utilities in California and Texas are deploying these systems at accelerated rates for residential and light commercial applications. The technology is digitizing billing accuracy standards while compressing maintenance intervals and enabling real-time pressure-temperature compensation.
The EPA's methane reduction framework mandates advanced leak-detection capabilities in new meter installations, creating hardware specifications that analog mechanical devices cannot satisfy. This regulatory pressure forces capital allocation toward AMI-enabled platforms with embedded sensors and wireless telemetry. Distribution utilities in the U.S. Northeast and Canadian provinces face the most acute compliance deadlines, driving concentrated procurement of ultrasonic and thermal mass systems.
Buyer concentration among large metropolitan utilities is consolidating procurement power and demanding outcome-based service contracts with guaranteed uptime and accuracy performance. Traditional equipment vendors face disintermediation from systems integrators offering bundled AMI deployment and data analytics. This shift is most visible in Texas and Florida, where municipal utility districts are bypassing legacy distributor relationships for direct manufacturer partnerships with integrated software platforms.
North America Gas Meter Market Segmentation
Gas meter procurement specifications diverge sharply across North American end-use segments, with utility-scale AMI deployments, industrial custody-transfer requirements, and residential safety mandates creating distinct technology-performance tiers. Understanding these segment boundaries clarifies why ultrasonic systems command premium positioning in Gulf Coast petrochemical corridors while mechanical meters persist in cost-constrained municipal distribution networks.
Product Type:
Measurement precision requirements span from residential billing accuracy to industrial mass-flow custody transfer, creating four distinct hardware categories with diverging material specifications and operational lifespans.
- Digital Meters:Electronic pulse-output devices with solid-state registers and temperature-pressure compensation modules. Demand concentrates in California and Texas investor-owned utilities replacing aging mechanical residential infrastructure under EPA methane compliance timelines.
- Mechanical Meters:Diaphragm or rotary displacement mechanisms with aluminum housings and mechanical index registers. Established volume favors this segment across legacy distribution networks in the U.S. Midwest and Canadian prairie provinces where capital constraints delay AMI conversion cycles.
- Smart Meters:AMI-enabled platforms with embedded wireless communications modules supporting remote shutoff, leak detection, and two-way data exchange. Emerging adoption favors this segment in metropolitan utility districts across Florida, New York, and Ontario where wildfire liability and methane reduction mandates accelerate procurement.
- Ultrasonic Meters:Transit-time flow measurement systems with zero moving parts, turndown ratios exceeding mechanical alternatives, and real-time diagnostic capabilities. Specified for LNG export terminal custody transfer and high-precision industrial applications along the U.S. Gulf Coast.
Established volume favors Mechanical Meters; emerging adoption favors Smart Meters.
Technology:
Communications architecture choices determine integration complexity with legacy utility SCADA systems and compliance with evolving federal telemetry mandates.
- IoT-enabled:Cellular or mesh-network-connected platforms with cloud-based data aggregation and edge analytics processing. California utilities prioritize these systems for wildfire-prevention remote shutoff capabilities.
- Analog:Non-communicating mechanical or electromechanical devices requiring manual meter reading. Persist in rural cooperative utilities across the U.S. Mountain West where AMI capital investment lags behind coastal states.
- Remote Reading:Drive-by or fixed-network automated meter reading systems without full two-way command capability. Dominates transitional deployments in Texas municipal utility districts bridging mechanical infrastructure toward AMI endpoints.
- Wireless Communication:RF mesh, cellular, or proprietary spectrum protocols enabling real-time telemetry. Specified for industrial safety monitoring in Canadian oil sands processing facilities and U.S. petrochemical complexes.
Deployment economics favor Remote Reading for mid-cycle replacements; regulatory pressure favors IoT-enabled for new infrastructure.
End User:
Customer scale and liability exposure shape accuracy requirements, maintenance intervals, and integration with downstream energy management systems.
- Residential:Single-family and multi-family dwelling installations with billing-grade accuracy standards and safety shutoff requirements. Ontario and British Columbia utilities drive replacement demand under Measurement Canada certification mandates.
- Commercial:Retail, hospitality, and light manufacturing facilities with intermediate flow rates and demand-response program participation. Adoption concentrates in Texas and Florida where time-of-use rate structures incentivize interval data collection.
- Industrial:Petrochemical processing, refining, and manufacturing operations requiring custody-transfer precision and hazardous area certifications. Gulf Coast LNG liquefaction terminals and Alberta oil sands upgraders specify Coriolis and ultrasonic mass-flow systems.
- Utilities:Distribution system operators managing aggregated metering infrastructure across diverse customer classes. Procurement consolidation among large metropolitan utilities in California, Texas, and Ontario reshapes vendor competitive dynamics.
Volume concentration sits with Utilities; margin expansion concentrates in Industrial.
Installation:
Physical mounting configurations respond to climate exposure, security requirements, and maintenance accessibility constraints across North American operating environments.
- Indoor:Basement or utility room installations protected from weather exposure, typical in older northeastern U.S. and Canadian housing stock. Dominates residential retrofit specifications where existing service entry configurations limit outdoor conversion.
- Outdoor:Pit-set or post-mounted installations with environmental sealing and tamper-evident enclosures. Standard for new construction across Sun Belt states and for utility-scale AMI deployments requiring radio line-of-sight optimization.
- Wall-mounted:Exterior building surface installations common in European-influenced urban planning contexts and multi-family housing configurations. Concentrated in older Canadian metropolitan cores and dense northeastern U.S. cities.
- Portable:Temporary or mobile measurement systems for construction site monitoring, emergency response, and field calibration verification. Demand emerges from utility leak survey operations and pipeline commissioning activities across the Permian Basin and Appalachian shale corridors.
Climate adaptation favors Outdoor; density constraints preserve Wall-mounted in legacy urban cores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal methane reduction mandates and state-level decarbonization targets are reshaping procurement specifications across North American gas distribution networks. Utility-scale smart meter deployments accelerate replacement cycles for aging mechanical infrastructure in the United States and Canada. Mexico's expanding natural gas distribution network creates emerging demand for precision flow measurement systems.
United States
The EPA's methane emission reduction framework mandates advanced leak-detection integration in new meter installations across California and Texas investor-owned utilities. The Department of Transportation's Pipeline and Hazardous Materials Safety Administration enforces periodic accuracy testing and replacement intervals for distribution infrastructure. Gulf Coast petrochemical clusters and LNG export terminals in Louisiana and Texas specify custody-transfer-grade Coriolis and ultrasonic flow measurement systems with elevated turndown ratios.
Canada
Measurement Canada enforces stringent accuracy certification under the Electricity and Gas Inspection Act, creating compliance-driven replacement cycles for aging residential infrastructure in Ontario and British Columbia. Provincial decarbonization targets in British Columbia and Quebec accelerate AMI-enabled smart meter procurement for methane monitoring capabilities. Alberta oil sands upgraders and British Columbia LNG facilities specify industrial-grade ultrasonic mass-flow systems for high-precision custody transfer applications.
Mexico
Expanding natural gas distribution networks in Nuevo León and Jalisco create procurement demand for residential and commercial metering infrastructure as pipeline connectivity extends beyond legacy urban centers. The Comisión Reguladora de Energía oversees technical specifications for measurement accuracy and safety integration in new installations. Industrial clusters in Monterrey and Guadalajara specify precision flow meters for manufacturing and petrochemical processing facilities.
North America Gas Meter Market Key Industry Players
On the supply side, the industry is consolidating around integrated AMI platform providers with embedded communications and safety module capabilities. Tiered competitive positioning separates full-stack solution vendors from component specialists and regional fabricators. Strategic archetypes include utility-scale AMI integrators, precision ultrasonic specialists, and legacy mechanical meter manufacturers transitioning toward electronic platforms. Dominant competitive moves encompass vertical integration into communications module production and strategic partnerships with utility software platforms for bundled deployment contracts.
Within the utility-scale AMI tier, Itron Inc. and Landis+Gyr occupy positions as integrated platform providers serving major metropolitan distribution networks across the United States and Canada. Badger Meter exemplifies the precision measurement specialist archetype, anchoring commercial and industrial custody transfer applications. These three entities represent distinct strategic postures: full-stack AMI deployment, precision flow specialization, and scaled manufacturing capacity for utility infrastructure.
| Leading Market Players |
|---|
| Badger Meter |
| Landis+Gyr |
| Itron Inc. |
| Sensus Worldwide Holdings Limited |
| ABB Ltd. |
| Honeywell International Inc. |
| Diehl Stiftung & Co. KG |
| Schneider Electric |
| Aclara Technologies LLC |
| Others |
Cost & Logistics Intelligence
Alberta's industrial manufacturing corridor anchors North American ultrasonic meter production capacity, where localized precision machining and sensor calibration facilities translate into downstream pricing power for custody-transfer-grade systems. This geographic concentration creates asymmetric leverage: utilities in Ontario and California face premium procurement costs for certified equipment, while Gulf Coast petrochemical buyers negotiate volume-based concessions.
Pricing Analysis
Certification level (Measurement Canada and EPA compliance-grade) creates the primary spread between premium AMI-enabled ultrasonic systems and economy-tier mechanical diaphragm alternatives. Pricing stratifies across three performance tiers: smart meters with embedded leak detection command substantial premiums, standard digital meters with temperature-pressure compensation occupy mid-market positioning, and legacy mechanical units face cost compression from aluminum commodity volatility. Price erosion runs through the mechanical segment as municipal utilities in the U.S. Midwest delay replacement cycles. Industrial buyers in Texas and Louisiana exhibit lowest price sensitivity due to custody-transfer accuracy requirements and liability exposure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for embedded communications modules and semiconductor components. Manufacturing concentration spans Mexico for aluminum housing fabrication, Germany for precision ultrasonic transducers, and Taiwan for RF chipset supply. Raw material dependencies center on aluminum ingots, MEMS pressure sensors, and lithium primary batteries for remote shutoff actuators. Distribution runs through authorized utility distributors in the United States and direct manufacturer relationships in Canadian provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American gas metering is transitioning toward service-attach economics, where predictive maintenance subscriptions and AMI data analytics layers expand faster than hardware replacement cycles. Recurring revenue from leak detection monitoring and pressure anomaly alerting now exceeds unit margin contributions for leading platform vendors.
For Market Incumbents: Entrench platform stickiness by embedding proprietary communications protocols that increase switching costs for utility customers facing AMI integration complexity. Prioritize backward integration into RF module production to insulate margins from semiconductor supply volatility. Defensive consolidation should target specialized ultrasonic calibration facilities in Alberta and Texas to anchor custody-transfer certification authority. For New Entrants and Emerging Players: Establish a beachhead in Mexico's expanding distribution networks, where regulatory frameworks remain less stringent than Measurement Canada or EPA mandates and local manufacturing partnerships can bypass tariff exposure. Target mid-sized municipal utilities in the U.S. Mountain West where AMI penetration lags coastal states. A software-first go-to-market angle—offering leak detection analytics compatible with existing mechanical infrastructure—sidesteps capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because methane emission mandates and safety shutoff requirements create non-discretionary replacement demand insulated from building electrification headwinds. Acquisition targets should prioritize AMI platform vendors with embedded safety module IP and established utility software integrations. The signal to watch is state-level wildfire liability legislation expanding remote shutoff mandates beyond California into Texas and Florida.| Strategic Initiative | Industry Significance |
|---|---|
| AMI Platform Integration | Consolidates vendor relationships for California utilities facing PHMSA compliance deadlines. |
| Ultrasonic Calibration Facility Expansion | Captures Measurement Canada certification premiums in Ontario and British Columbia replacement cycles. |
| Predictive Maintenance Service Launch | Converts hardware sales into recurring revenue from Gulf Coast petrochemical operators. |
| Mexico Distribution Partnership | Positions for CRE-regulated network expansion in Nuevo León and Jalisco industrial corridors. |
| Edge Analytics Module Development | Enables on-device leak detection processing for Texas utilities facing wildfire litigation exposure. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, utility procurement databases, and trade association technical standards. Primary interviews engaged utility planning officers, AMI deployment contractors, and gas distribution engineering leads across California, Texas, Ontario, and Alberta. Secondary validation drew from EPA methane reduction framework documents, Measurement Canada accuracy certification records, FERC infrastructure investment disclosures, and EIA natural gas distribution statistics. Bottom-up unit shipment estimates triangulated against top-down utility capital expenditure projections.
Forecast inputs incorporate technology replacement cycles segmented by product type, end-user scale, and communications architecture complexity. Modeled dimensions span residential, commercial, industrial, and utility customer classes across analog, remote reading, and IoT-enabled technology tiers. CAGRs derived from utility-reported deployment timelines and regulatory compliance deadlines. Industry-specific inputs include state-level building electrification policy trajectories and LNG export terminal commissioning schedules.
Sensitivities concentrate around Measurement Canada certification timeline delays, aluminum commodity price volatility, and semiconductor availability for embedded communications modules. Forecasts reflect assumptions regarding EPA methane mandate enforcement consistency and state-level wildfire liability expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
US Water Meter Market
Smart Meters
Power Metering Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
Europe Water Meter Market
Smart Meters
Smart Gas Metering Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Industrial Power Monitoring System Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
United States (US) Residential Smart Meters Market
Smart Meters
Residential RF Smart Electric Meter Market