
 Southeast Asia Solar Energy Market | 2026-2036
Southeast Asia Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Solar Energy Market Analytics
Commercial and industrial buyers are rotating into the dominant procurement position as utility-scale auction saturation in Thailand and Vietnam redirects developer pipelines. JinkoSolar Holding Co. Ltd anchors its regional position through integrated cell-to-module manufacturing in Southeast Asian hubs. Trina Solar Limited differentiates via high-efficiency bifacial product lines calibrated for tropical humidity cycles. LONGi leverages monocrystalline wafer scale to sustain cost leadership across Indonesian and Philippine project pipelines.
Southeast Asia solar energy encompasses photovoltaic systems that convert sunlight into electricity through silicon-based cells, typically deployed in crystalline modules rated between 400–700 watts peak output for utility and commercial installations. Concentrated solar power remains marginal in this humid tropical climate, while photovoltaic technology dominates installed capacity across all ten ASEAN member states. Solar panels capture the largest value share within product type segments, though energy storage attachment rates are climbing fastest as grid stability requirements tighten. Grid-tied systems lead application penetration in urbanized markets, whereas off-grid systems retain structural importance across Indonesian archipelago provinces and Philippine island chains.
Thailand's Department of Alternative Energy Development and Efficiency enforces national power development plan quotas that mandate utility procurement ceilings, while Vietnam's Ministry of Industry and Trade administers direct power purchase agreement pilot frameworks enabling private offtake. The ASEAN Centre for Energy coordinates regional interconnection standards that shape cross-border project finance structures. Stakeholders must monitor how national renewable portfolio standards evolve against grid absorption constraints and land-use permitting backlogs.
Market Dynamics
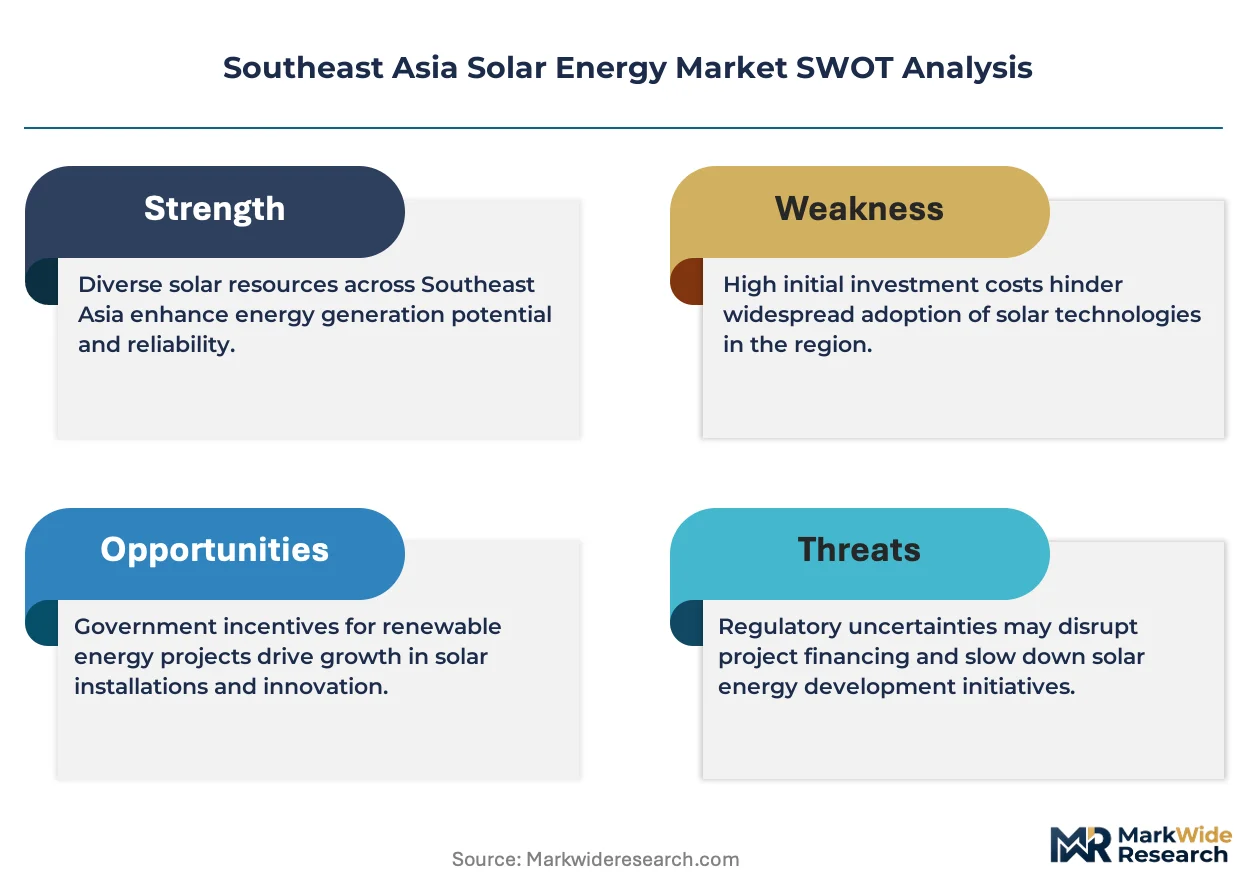
Feed-in tariff phase-outs across Thailand and Vietnam are redirecting developer capital toward direct power purchase agreements with commercial and industrial offtakers, compressing project development timelines and reshaping offtake risk allocation.
Growth Catalysts
- Direct Power Purchase Agreement Frameworks:Vietnam's Ministry of Industry and Trade pilot programs enable private offtake contracts that bypass traditional utility intermediaries, accelerating deployment for manufacturing campuses.
- Indonesia:Archipelago geography and diesel-dependent island grids create structural demand for distributed solar-plus-storage configurations across Sumatran and Sulawesi provinces.
- Bifacial Module Technology:Albedo capture gains in tropical high-humidity environments improve capacity factors for ground-mount installations, particularly in Thai agricultural zones.
Market Restraints
- Polysilicon Input Volatility:Southeast Asian cell and module assemblers remain exposed to Chinese polysilicon price swings, compressing margin visibility for project developers.
- Land-Use Permitting Backlogs:Vietnam's provincial environmental clearance procedures create 18-24 month approval timelines for utility-scale sites, freezing pipeline conversion.
- Grid Absorption Constraints:Weak inter-island transmission infrastructure across the Philippine archipelago limits solar export capacity from Luzon generation clusters.
Strategic Opportunities
- Myanmar and Cambodia:Nascent regulatory frameworks and low electrification rates create first-mover positioning for off-grid commercial solar deployment.
- Floating Photovoltaic Arrays:Reservoir and lagoon installations address land scarcity constraints while reducing evaporative losses for Thai and Vietnamese water utilities.
- Renewable Portfolio Standards:Mandatory procurement quotas under Thailand's Department of Alternative Energy Development and Efficiency create guaranteed demand floors for certified project developers.
Industry Challenges
- Grid Code Harmonization:Divergent interconnection standards across ASEAN member states fragment equipment procurement and engineering design workflows.
- Skilled Technician Scarcity:Shortages of certified inverter commissioning specialists and high-voltage electricians delay commercial rooftop energization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Solar Energy Market |
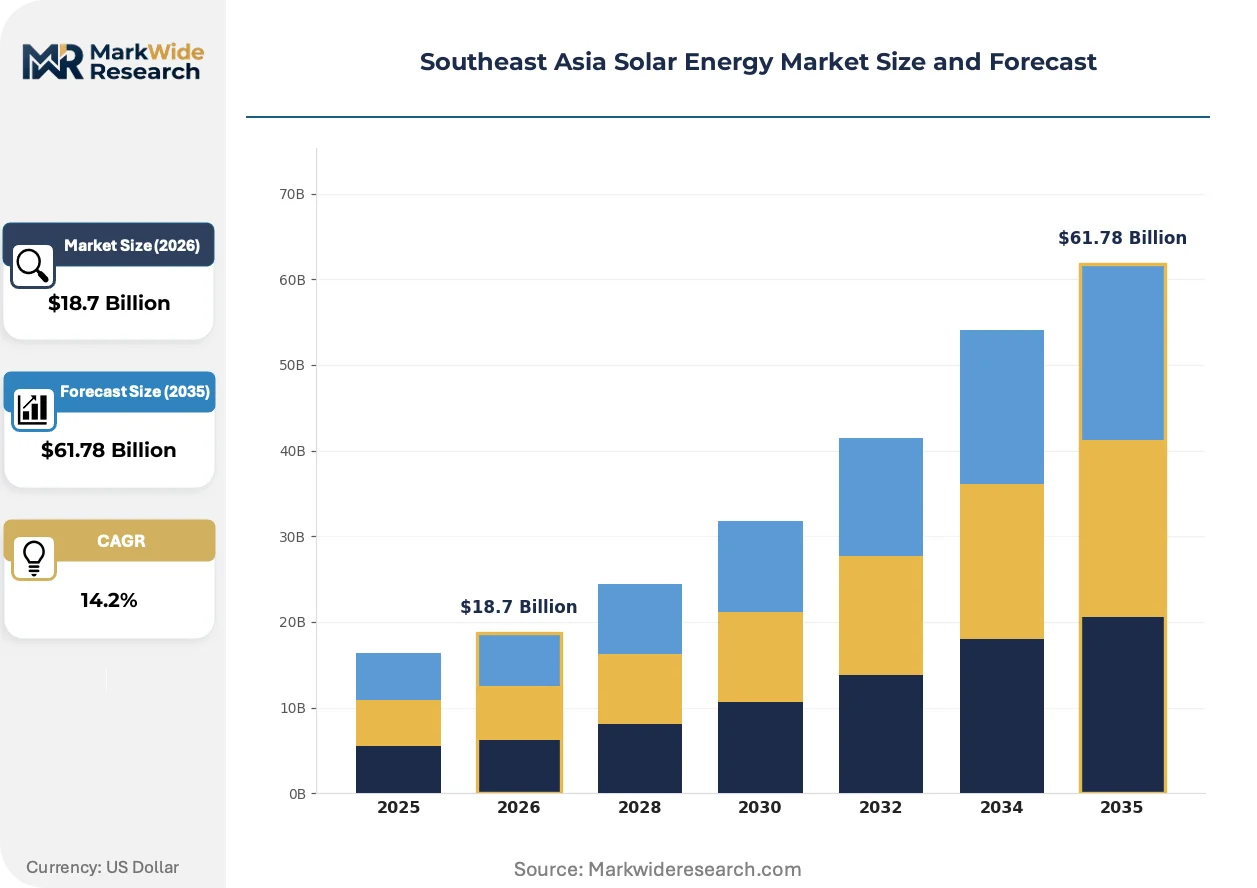
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Inverters, Mounting Systems, Energy Storage End User: Residential, Commercial, Industrial, Utilities Technology: Photovoltaic, Concentrated Solar Power, Bifacial, Thin-Film Application: Off-grid Systems, Grid-tied Systems, Hybrid Systems, Solar Water Pumps |
| Companies Covered | Canadian Solar Inc., Thai Solar Energy Public Company Limited, JinkoSolar Holding Co. Ltd, Scatec ASA, Vena Energy, Trina Solar Limited, Solarvest Group, Solar Philippines New Energy Corporation, LONGi, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Solar Energy Market Evolving Landscape
Module efficiency races and balance-of-system cost compression are converging with evolving offtake structures to redefine project economics across humid tropical deployment environments.
Passivated emitter and rear contact cell architecture is miniaturizing metallization patterns while boosting conversion efficiency above 23 percent in mass production. Thai and Vietnamese commercial installers are specifying these modules for rooftop constraints where surface area is limited. The technology is compressing specific energy yield requirements per square meter, enabling smaller footprints for equivalent output.
Vietnam's direct power purchase agreement pilot framework is mandating standardized contract templates and grid impact studies that reduce transaction costs for bilateral negotiations. Industrial parks in Binh Duong and Dong Nai provinces are leveraging these mechanisms to source captive renewable supply. The policy shift is accelerating private offtake migration away from expired feed-in tariff regimes.
Corporate renewable energy procurement is consolidating buyer power among Thai and Vietnamese manufacturing conglomerates with multi-site portfolios. These offtakers are negotiating master service agreements with developers that bundle construction, operation, and energy management across facility networks. The concentration is visible in Vietnam's textile and electronics export zones where sustainability compliance pressures intensify.
Southeast Asia Solar Energy Market Segmentation
Solar energy deployment across Southeast Asia fragments along technology performance tiers, buyer sophistication levels, and grid integration requirements. Regulatory frameworks in Vietnam, Thailand, and Indonesia create distinct procurement pathways that reshape segment prioritization for equipment suppliers and project developers.
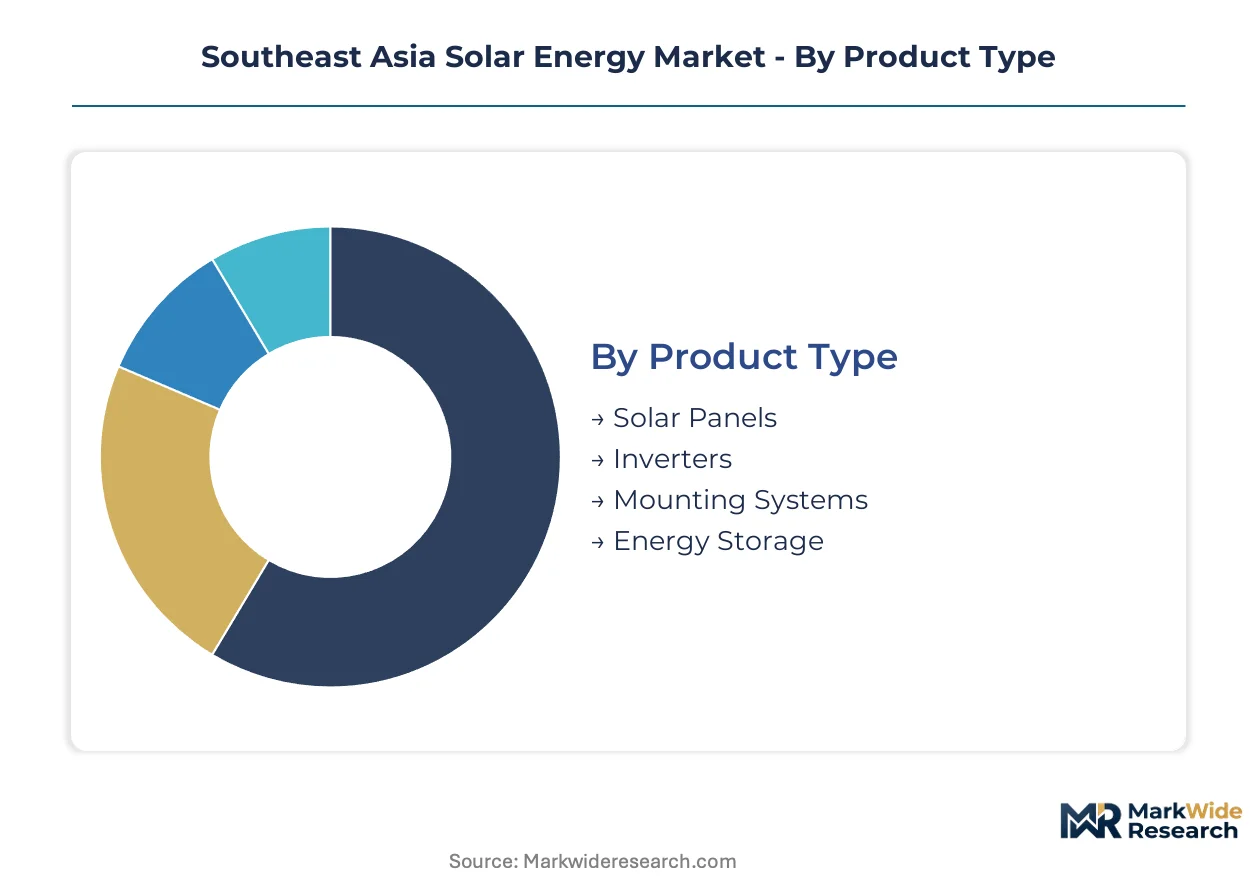
Product Type:
Vietnam's Ministry of Industry and Trade mandates module certification standards that elevate panel specifications above regional baselines, while Thailand's Department of Alternative Energy Development and Efficiency imposes inverter efficiency thresholds for utility-scale eligibility.
- Solar Panels:Crystalline silicon modules rated 400–700 watts peak dominate procurement volumes. Vietnamese rooftop installations and Thai agricultural ground-mount projects concentrate demand as feed-in tariff transitions accelerate replacement cycles.
- Inverters:String and central inverter architectures convert DC generation to grid-compliant AC output. Commercial and industrial buyers in Binh Duong and Dong Nai industrial parks specify three-phase units with remote monitoring capabilities to satisfy power purchase agreement uptime clauses.
- Mounting Systems:Fixed-tilt aluminum and steel structures predominate in Thai utility-scale deployments. Floating mounting configurations gain traction for Vietnamese reservoir installations where land scarcity constrains conventional siting.
- Energy Storage:Lithium-ion battery attachment rates climb as grid stability requirements tighten across the Philippine archipelago and Indonesian island provinces. Diesel displacement economics in Sulawesi and Sumatra drive distributed solar-plus-storage configurations.
Solar Panels handles the majority of throughput; Energy Storage is expanding most quickly on share.
End User:
Buyer type determines financing structures, contract complexity, and equipment specification rigor across the region's divergent regulatory environments.
- Residential:Individual rooftop installations typically deploy sub-10 kilowatt systems with net metering arrangements. Vietnamese households in Ho Chi Minh City and Hanoi municipalities leverage streamlined permitting for behind-the-meter generation.
- Commercial:Manufacturing campuses and retail facilities pursue direct power purchase agreements to lock in electricity costs. Thai conglomerates with multi-site portfolios negotiate master service agreements bundling construction and energy management across facility networks.
- Industrial:Textile and electronics export zones in Vietnam face sustainability compliance pressures from European buyers. High-voltage interconnection requirements and 24/7 load profiles necessitate larger system capacities with sophisticated forecasting integration.
- Utilities:State-owned power authorities procure through auction mechanisms with mandated local content ratios. Thailand's national power development plan quotas cap utility procurement ceilings, redirecting developer pipelines toward private offtake.
Utilities historically anchored procurement volume; Commercial buyers are gaining share fastest as auction saturation redirects capital flows.
Technology:
Module architecture selection hinges on humidity tolerance, bifacial gain coefficients, and manufacturing scale economics in tropical deployment environments.
- Photovoltaic:Silicon-based cell technology captures virtually all installed capacity across ASEAN member states. Passivated emitter and rear contact architectures now exceed 23 percent conversion efficiency in mass production, compressing surface area requirements for constrained rooftops.
- Concentrated Solar Power:Mirror-based thermal generation remains marginal in Southeast Asia's humid tropical climate. High atmospheric moisture and diffuse solar radiation degrade performance economics against photovoltaic alternatives.
- Bifacial:Dual-sided modules capture albedo reflection from ground surfaces and water bodies. Thai agricultural zones and Vietnamese floating installations exploit humidity-stable encapsulants to sustain capacity factor advantages.
- Thin-Film:Cadmium telluride and copper indium gallium selenide technologies occupy niche applications. Lower temperature coefficients suit specific high-heat deployments, though crystalline silicon cost structures limit penetration.
Photovoltaic commands absolute volume leadership; Bifacial modules show the steepest expansion trajectory as albedo capture economics improve.
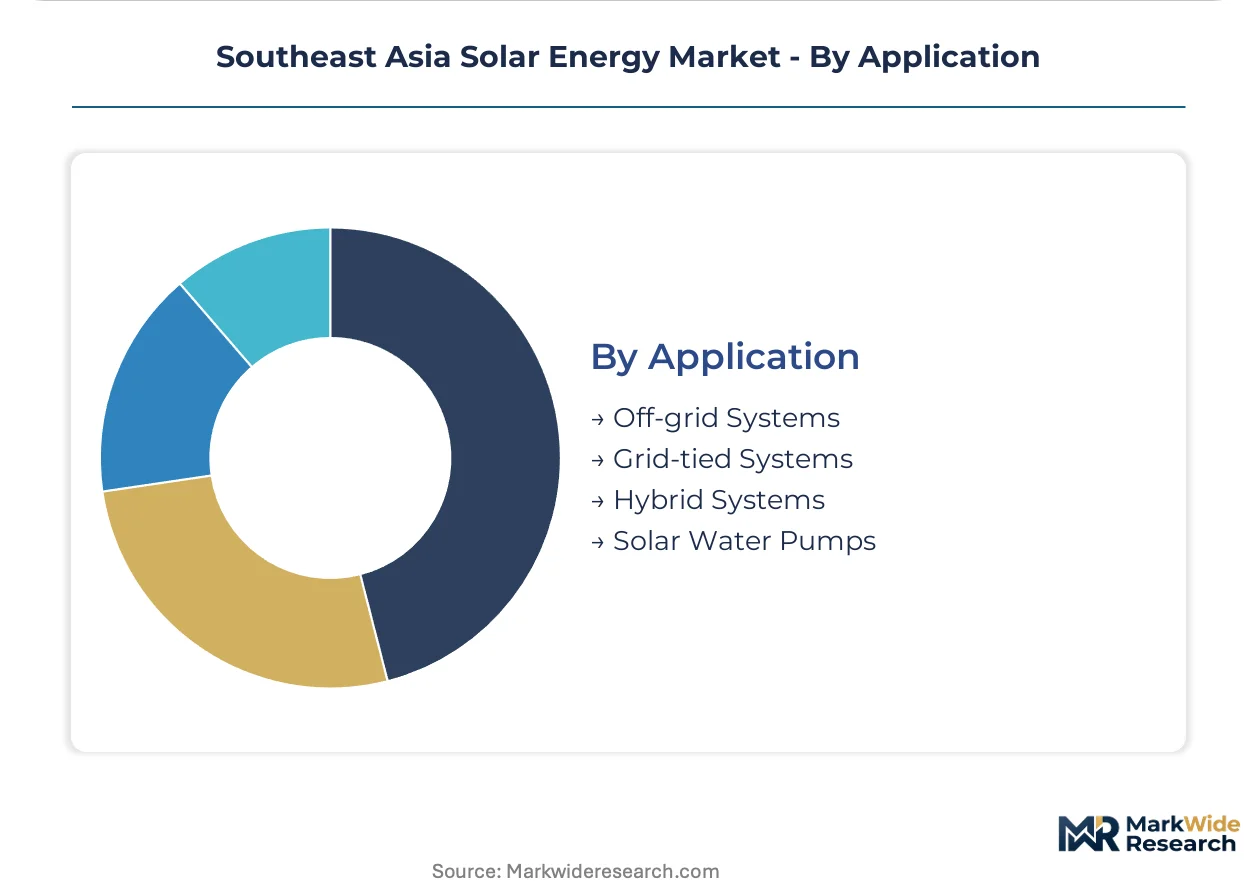
Application:
Grid integration topology shapes equipment procurement, engineering design, and revenue model selection across archipelago and mainland geographies.
- Off-grid Systems:Standalone configurations serve Indonesian provinces and Philippine island chains where inter-island transmission infrastructure remains underdeveloped. Diesel displacement economics in Sulawesi and Mindanao drive solar-plus-storage deployment.
- Grid-tied Systems:Utility-interconnected installations dominate urbanized markets with established distribution infrastructure. Vietnamese net metering frameworks and Thai feed-in tariff successors govern interconnection standards and compensation mechanisms.
- Hybrid Systems:Dual-mode configurations combine solar generation with diesel backup or battery storage for reliability-critical loads. Indonesian mining operations and Philippine commercial facilities specify hybrid architectures to manage grid instability risks.
- Solar Water Pumps:Agricultural irrigation applications deploy submersible and surface pumps powered by dedicated PV arrays. Thai rice-growing regions and Vietnamese Mekong Delta provinces substitute solar pumping for diesel and grid-dependent alternatives.
Grid-tied Systems handle the majority of throughput; Hybrid Systems are climbing the fastest on share as reliability requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ASEAN Power Grid interconnectors and cross-border transmission corridors are underwriting Southeast Asia's solar buildout, with Thailand's 500-kV lines into Laos and Vietnam's 220-kV links to Cambodia enabling regional electricity trade that reshapes project siting economics.
Vietnam
Binh Duong and Dong Nai industrial parks concentrate manufacturing demand for captive renewable supply. The Ministry of Industry and Trade's direct power purchase agreement pilot framework enables private offtake contracts that bypass traditional utility intermediaries. Rooftop solar installations in Ho Chi Minh City and Hanoi municipalities leverage streamlined permitting for behind-the-meter generation.
Thailand
Agricultural ground-mount projects and floating reservoir installations drive utility-scale procurement volumes. The Department of Alternative Energy Development and Efficiency enforces national power development plan quotas that mandate utility procurement ceilings. The Eastern Economic Corridor industrial clusters negotiate master service agreements bundling construction and energy management across facility networks.
Indonesia
Sumatran and Sulawesi provinces exhibit structural demand for distributed solar-plus-storage configurations where diesel-dependent island grids dominate. The archipelago geography and weak inter-island transmission infrastructure create captive markets for off-grid commercial deployment. Mining operations across Kalimantan specify hybrid architectures to manage grid instability risks.
Philippines
Luzon generation clusters face export constraints from weak inter-island transmission infrastructure limiting solar capacity absorption. Solar Philippines New Energy Corporation and utility-scale developers concentrate projects in Batangas and Pangasinan provinces. Mindanao island chains retain structural importance for off-grid systems serving diesel-displacement economics.
Myanmar and Cambodia
Nascent regulatory frameworks and low electrification rates create first-mover positioning for off-grid commercial solar deployment. Yangon and Phnom Penh industrial zones attract early developer entry before auction saturation redirects capital flows. Provincial environmental clearance procedures remain less burdensome than Vietnam's 18-24 month timelines.
Southeast Asia Solar Energy Market Competitive Landscape
Listed leaders compete with private specialists across capital access and project development velocity. The vendor base stratifies into integrated cell-to-module manufacturers, pure-play project developers, and regional engineering specialists. Three archetypes dominate: Chinese-headquartered scale players with captive polysilicon supply, ASEAN-domiciled developers with local permitting expertise, and European-originated IPPs with long-tenor project finance relationships. Competitive moves concentrate on backward integration into wafer manufacturing and strategic partnerships with industrial offtakers for direct power purchase agreement origination.
Among Chinese-headquartered scale manufacturers, JinkoSolar Holding Co. Ltd, Trina Solar Limited, and LONGi occupy positions that exemplify the integrated production archetype. These entities leverage monocrystalline wafer scale and high-efficiency bifacial product lines to sustain cost leadership across Indonesian and Philippine project pipelines. Thai Solar Energy Public Company Limited represents the regional developer archetype with local permitting expertise. Canadian Solar Inc. anchors the North American-originated multinational tier with project finance access across Vietnamese and Thai utility-scale auctions.
| Leading Market Players |
|---|
| Canadian Solar Inc. |
| Thai Solar Energy Public Company Limited |
| JinkoSolar Holding Co. Ltd |
| Scatec ASA |
| Vena Energy |
| Trina Solar Limited |
| Solarvest Group |
| Solar Philippines New Energy Corporation |
| LONGi |
| Others |
Value Network & Pricing Analysis
Wafer-scale manufacturing economics in Chinese polysilicon hubs compress module price floors across Vietnamese and Thai procurement channels, concentrating supply-side pricing power among integrated cell-to-module producers while fragmenting margin capture for regional assemblers.
Pricing Analysis
Volume-discount tiering structures separate premium PERC and TOPCon modules certified for Vietnam's Ministry of Industry and Trade standards from standard-tier string inverters and economy-grade mounting hardware. Price differentiation rests on conversion efficiency thresholds and humidity-stable encapsulant certifications rather than brand premiums alone. Cost compression in central inverters is intensifying because Chinese scale manufacturers are exporting excess capacity into ASEAN markets. Commercial and industrial buyers in Thai industrial parks exhibit the lowest price sensitivity due to sustainability compliance mandates, while residential rooftop segments in Indonesian provinces remain most responsive to per-watt pricing.
Supply Chain Analysis
Inventory lead times for high-efficiency bifacial modules stretch to 12-16 weeks from Chinese wafer facilities through Vietnamese port terminals, compressing project commissioning schedules for EPC contractors. Geographic supply concentration centers on China for polysilicon and cell production, Vietnam for module assembly and regional distribution, and Thailand for inverter integration and balance-of-system fabrication. Raw material dependencies include metallurgical-grade silicon, silver paste for cell metallization, and aluminum frames for module structural integrity. Single-source vulnerability in Chinese polysilicon feedstock exposes margin visibility to commodity price swings. Distribution runs through regional logistics hubs in Ho Chi Minh City and Bangkok before final-mile deployment to project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southeast Asia solar energy sits in early-cycle expansion as direct power purchase agreement frameworks displace expired feed-in tariff regimes and unlock private offtake volumes across manufacturing corridors.
For Market Incumbents: Shield margin positions by securing captive polysilicon supply through backward integration into wafer manufacturing or long-term offtake contracts with Chinese producers. Accelerate certification investment for Vietnam's Ministry of Industry and Trade module standards to maintain eligibility for premium-tier procurement. The threat of auction saturation in Thailand's utility-scale segment demands defensive repositioning toward commercial and industrial buyer segments. For New Entrants and Emerging Players: Anchor in Myanmar and Cambodia's nascent regulatory environments where provincial environmental clearance procedures remain less burdensome than Vietnam's extended timelines. Target off-grid commercial solar deployment across Indonesian Sumatran provinces where diesel displacement economics create immediate payback visibility. Pursue floating photovoltaic arrays for Thai and Vietnamese water utilities as a differentiated siting solution addressing land scarcity constraints. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with established direct power purchase agreement origination capabilities and local permitting expertise across multiple ASEAN jurisdictions. Long-term viability over the next decade hinges on grid interconnection rights and industrial offtake contract tenors rather than equipment manufacturing scale. Acquisition targets should demonstrate bilateral negotiation capacity with Thai and Vietnamese manufacturing conglomerates. Watch floating solar project pipelines as an inflection indicator for technology differentiation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Power Purchase Agreement Origination | Bypasses utility intermediaries in Vietnam's Ministry of Industry and Trade pilot framework, accelerating private offtake conversion. |
| Backward Integration into Wafer Manufacturing | Reduces exposure to Chinese polysilicon price volatility for regional module assemblers. |
| Floating Photovoltaic Array Development | Addresses land scarcity constraints for Thai agricultural zones and Vietnamese reservoir installations. |
| Solar-Plus-Storage Configuration Deployment | Captures diesel displacement economics across Indonesian Sulawesi and Philippine Mindanao island grids. |
| Bifacial Module Technology Certification | Unlocks albedo capture gains in tropical high-humidity environments for ground-mount installations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators across Vietnam, Thailand, and Indonesia; and secondary validation against IEA renewable energy databases, ASEAN Centre for Energy interconnection standards, FERC-style regulatory filings from Thailand's Department of Alternative Energy Development and Efficiency, and project development pipeline trackers. Bottom-up capacity installation estimates were triangulated against top-down policy target trajectories.
Across the projection horizon, the analytical framework modeled segmentation across module technology tier, project scale, buyer type, and regulatory framework cluster. CAGRs were derived from installation run-rate analysis and policy mandate absorption capacity. Forecast inputs incorporated grid interconnection queue depths, land-use permitting velocity, and industrial electricity demand growth in Vietnamese export zones.
Material uncertainties — polysilicon supply disruptions, provincial environmental clearance delays, and grid absorption bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions about policy continuity and financing availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
United States Fixed-Tilt Solar PV Market
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
Solar Bench Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Chile Solar Energy Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Asia-Pacific Bifacial Solar Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Vietnam Solar Energy Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Canada Solar Energy Market