
 Germany Additive Manufacturing Market | 2026-2036
Germany Additive Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Additive Manufacturing Market Insights
Industrial-grade tolerance specifications is collapsing as the baseline for production-part qualification across German additive manufacturing. EOS GmbH leverages its laser sintering heritage to dominate polymer and metal systems for aerospace and medical clients. Trumpf sustains competitive intensity through its photonics-to-systems pipeline, controlling beam source technology that anchors its powder-bed fusion platforms. SLM Solutions Group AG specializes in large-format multi-laser metal systems, occupying the high-value segment for automotive and energy sector tooling.
Additive manufacturing in Germany encompasses layer-by-layer fabrication of three-dimensional objects from digital models, employing directed energy deposition or powder-bed fusion with beam diameters typically ranging from 0.1 to 1.0 millimeters to achieve near-net-shape metal and polymer components. Its primary purpose lies in producing geometrically complex parts with internal lattice structures that subtractive methods cannot machine, while reducing material waste ratios from 90 percent to below 10 percent in aerospace bracket applications. Metal powder systems command the dominant margin pool due to qualification barriers and powder recycling economics, while plastics sustain broader prototyping volumes across mid-tier suppliers. Production parts application is accelerating fastest as automotive OEMs shift from validation prints to certified series components for electric drivetrain housings.
KBA type-approval requirements and the EU Machinery Directive shape product liability frameworks for automotive and aerospace additive components, compelling manufacturers to maintain full process traceability from powder lot to finished part. Germany's Federal Institute for Materials Research and Testing (BAM) develops certification protocols that define tensile property benchmarks for laser powder-bed fusion steels and nickel superalloys. REACH compliance on metal powder composition limits supplier flexibility while creating preference for domestic powder atomization capacity. Stakeholders must monitor how the EU AI Act's quality management obligations apply to machine learning-based process control systems in autonomous build monitoring.
Market Dynamics
Multi-laser powder-bed fusion systems are compressing qualification timelines for production metal parts, forcing mid-tier machine builders to specialize in niche geometries or exit the market entirely.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:Automotive OEMs in Stuttgart and Munich must demonstrate material waste reduction below 10 percent to secure public procurement contracts, accelerating certified additive workflows for electric drivetrain housings.
- Baden-Württemberg aerospace cluster demand:Tier-1 suppliers for engine programs now specify laser powder-bed fusion for turbine brackets previously machined from solid billets, creating captive demand for domestic machine capacity.
- Nickel superalloy powder qualification protocols:BAM certification benchmarks for creep resistance at elevated temperatures unlock flight-critical component approvals that polymer systems cannot address.
Market Restraints
- Argon and helium feedstock cost volatility:Inert gas consumption of 50-200 liters per build hour ties operating margins to commodity price swings that powder suppliers cannot hedge.
- Domestic powder atomization concentration:Three specialized facilities control spherical titanium and nickel alloy supply, creating single-source risk for automotive qualification programs.
- Surface finish limitations without post-processing:As-built roughness values of 5-15 micrometers Ra require CNC machining or chemical polishing for sealing surfaces, eroding the near-net-shape cost advantage.
Strategic Opportunities
- Thuringia and Saxony underpenetrated supplier base:Former precision engineering regions lack additive infrastructure, offering first-mover positioning for contract manufacturers serving medical device clusters.
- EU AI Act quality management obligations:Autonomous build monitoring systems that document layer-wise thermal signatures gain regulatory preference, creating software margin pools beyond hardware sales.
- Directed energy deposition repair applications:Convergence of robotic arm platforms with coaxial wire feeding enables on-site restoration of worn stamping dies and turbine blades, opening service revenue models.
Industry Challenges
- Process engineer talent scarcity:Universities produce fewer than 200 qualified laser powder-bed fusion technicians annually against demand from Bavarian aerospace and automotive programs.
- KBA type-approval traceability documentation:Each production part requires 50-200 process parameters archived for 15 years, forcing IT infrastructure investments that consume 8-12 percent of machine house operating budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Additive Manufacturing Market |
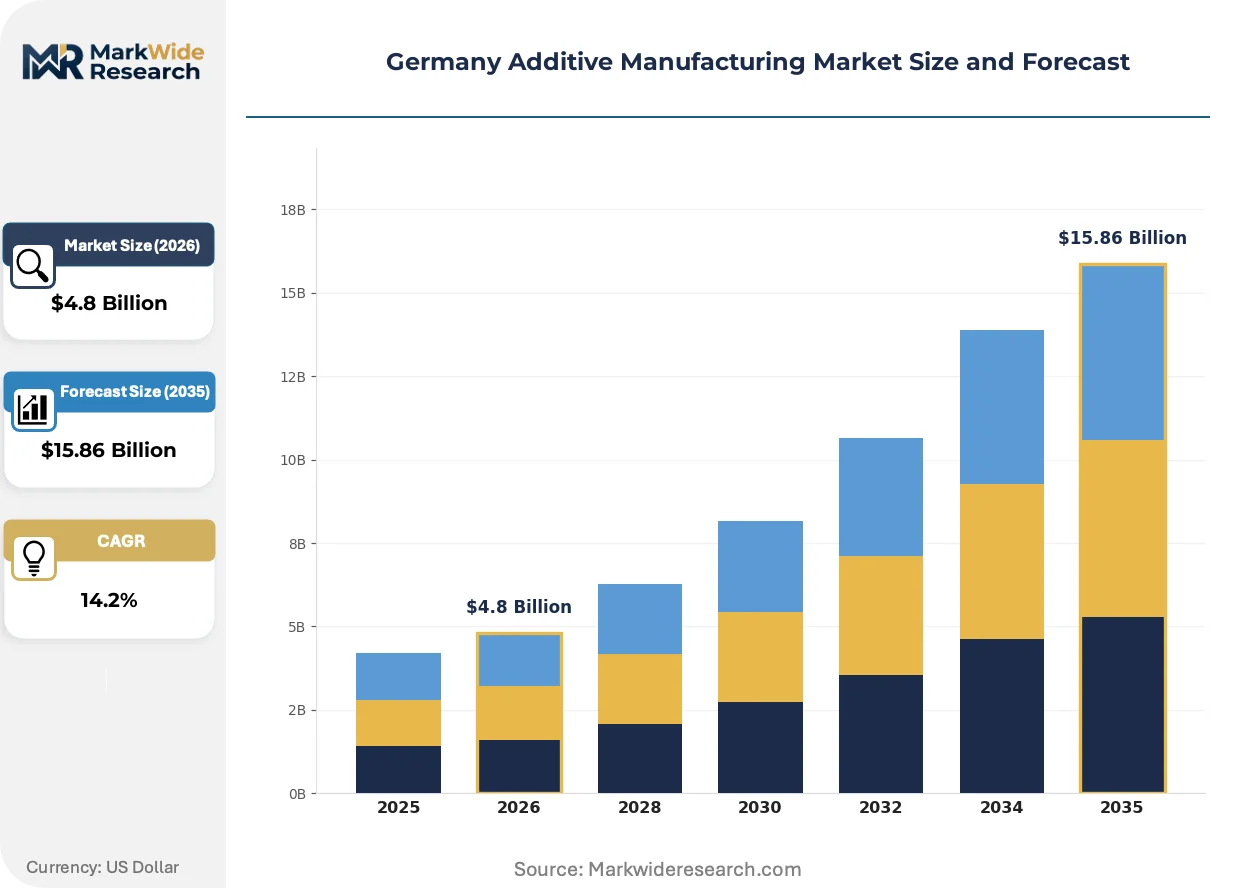
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: SLA, SLS, FDM, DLP Material: Plastic, Metal, Ceramics, Composite End User: Aerospace, Automotive, Healthcare, Consumer Goods Application: Prototyping, Tooling, Production Parts, Customization |
| Companies Covered | EOS GmbH, SLM Solutions Group AG, Trumpf, DMG Mori AG, Voxeljet AG, Stratasys Ltd, 3D Systems Corporation, Markforged Holding Corporation, Desktop Metal Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Additive Manufacturing Market Trends and Innovations
Beam shaping technology and real-time melt pool monitoring are collapsing the defect rate variance that historically separated prototype from production economics.
Dynamic beam modulation using acousto-optical deflectors is displacing fixed Gaussian profiles in multi-laser systems. Aerospace tier-1 suppliers in Augsburg and Hamburg now specify this capability for nickel superalloy turbine components. The technology is displacing secondary hot isostatic pressing cycles by eliminating lack-of-fusion defects at the as-built stage.
REACH compliance on metal powder composition is tightening supplier qualification windows. ECHA substance restrictions on cobalt and chromium particulate exposure force atomization facilities to install closed-loop gas recovery. Medical implant manufacturers in Tuttlingen face 18-24 month requalification timelines when switching powder lots, consolidating procurement around vertically integrated suppliers.
After-sales service contracts are unbundling from machine sales as OEMs seek predictable operating expenditure structures. Contract manufacturers in Bavaria now subscribe to per-build-hour maintenance and powder replenishment rather than capitalizing full system ownership. This shift concentrates most visibly among mid-tier automotive suppliers around Ingolstadt, where balance sheet constraints favor operational leasing over asset ownership.
Germany Additive Manufacturing Market Segmentation
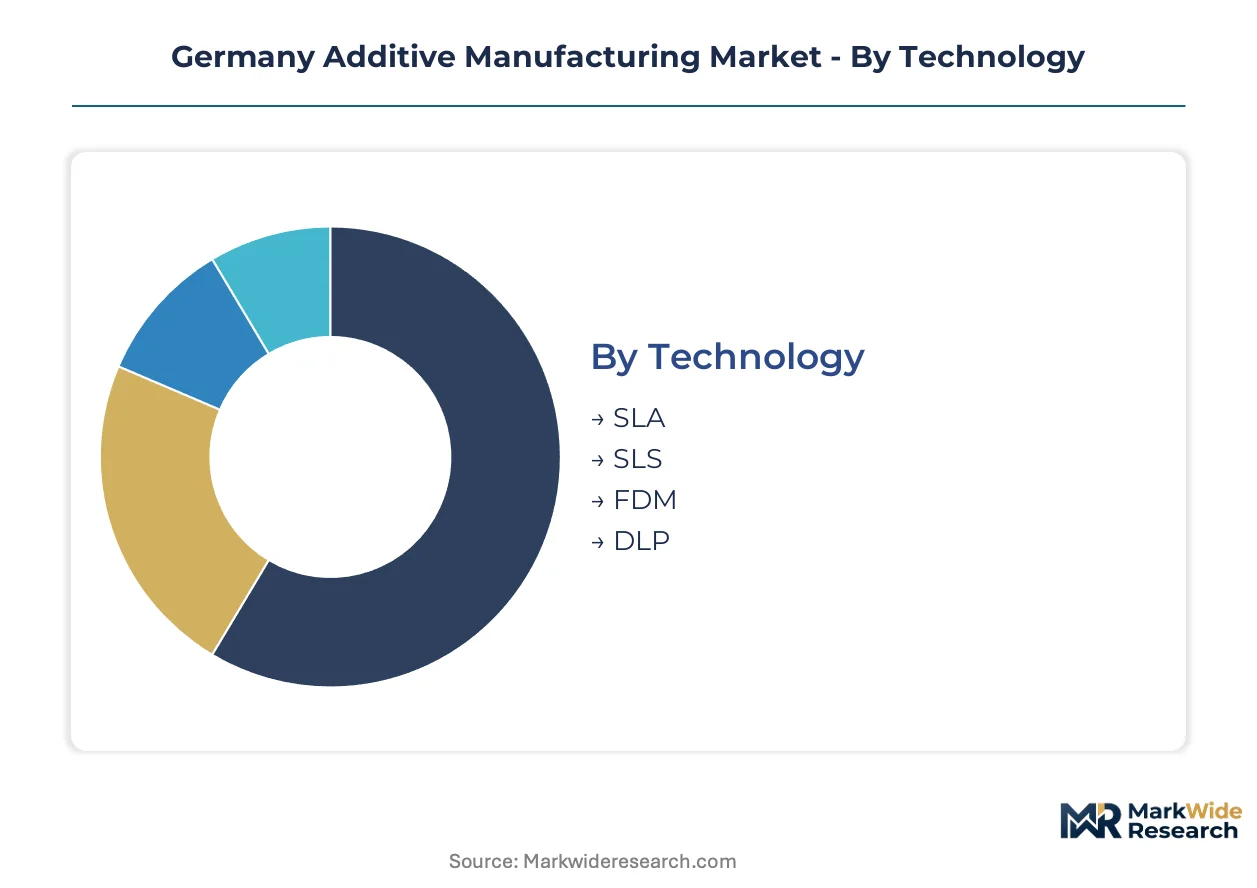
German additive manufacturing segments diverge sharply between export-oriented metal systems serving aerospace and domestic-focused polymer workflows for automotive prototyping. Technology selection determines regulatory pathway complexity, with powder-bed fusion facing BAM certification requirements that thermoplastic extrusion avoids entirely.
Technology:
Domestic demand concentrates in laser-based systems for production metal parts, while stereolithography and filament extrusion serve export markets through machinery sales to European contract manufacturers.
- SLA:Photopolymer vat polymerization achieves surface finishes below 2 micrometers Ra, satisfying Tuttlingen medical implant manufacturers requiring biocompatible resin certification. Demand clusters in dental aligner production and microfluidic device prototyping where layer resolution below 50 micrometers is mandatory.
- SLS:Laser sintering of polyamide powders dominates aerospace bracket manufacturing in Augsburg, with build volumes exceeding 700 millimeters enabling consolidated assembly replacement. EOS GmbH's domestic installed base creates path dependency for spare parts and powder supply logistics.
- FDM:Fused deposition modeling serves automotive jigs and fixtures around Ingolstadt, where ABS and carbon-fiber-reinforced thermoplastics replace machined aluminum in non-critical assembly aids.
- DLP:Digital light projection captures jewelry and dental casting patterns in Pforzheim, leveraging pixel-wise exposure control for investment casting burnout performance.
SLS holds the largest share; momentum sits with SLA as medical device qualification protocols mature.
Material:
Cost tier separation is pronounced: nickel superalloy powder commands 15-20x the per-kilogram price of standard polyamide, concentrating margin in atomization and recycling infrastructure.
- Plastic:Polyamide 12 and PA11 powders sustain prototyping volumes across mid-tier suppliers, with renewable feedstocks gaining preference under EU Green Deal procurement rules. Automotive OEMs in Stuttgart specify recycled-content thresholds for non-structural interior components.
- Metal:Titanium Ti-6Al-4V and Inconel 718 dominate flight-critical applications, with BAM-certified powder lots fetching premiums for aerospace tier-1 contracts. Three domestic atomization facilities control spherical powder supply for KBA-traceable automotive programs.
- Ceramics:Alumina and zirconia feedstocks serve dental crown production in Baden-Württemberg, where biocompatibility certification under EU MDR drives material lock-in.
- Composite:Carbon-fiber-reinforced PEEK addresses orthopedic implant load-bearing requirements, with fiber orientation control determining fatigue performance in spinal fusion cages.
Metal commands the premium tier; composite materials are climbing fastest as orthopedic applications expand.
End User:
Application maturity varies: aerospace demands full process traceability while consumer goods tolerates higher defect rates for cost-sensitive production.
- Aerospace:Turbine bracket and engine mount qualification in Bavaria requires 15-year parameter archiving under KBA type-approval frameworks. MTU Aero Engines specifies laser powder-bed fusion for nickel superalloy components previously machined from solid billets.
- Automotive:Electric drivetrain housings in Munich integrate conformal cooling channels impossible with conventional casting, with BMW and Porsche qualifying additive tooling for series production workflows.
- Healthcare:Patient-specific cranial implants in Tuttlingen exploit DLP and SLS personalization, with EU MDR device classification dictating quality management system investments.
- Consumer Goods:Eyewear and footwear customization in Berlin and Hamburg leverages polymer systems for batch-size-one production, with surface finish limitations restricting premium positioning.
Automotive holds the largest share; healthcare is expanding most quickly as regulatory pathways clarify.
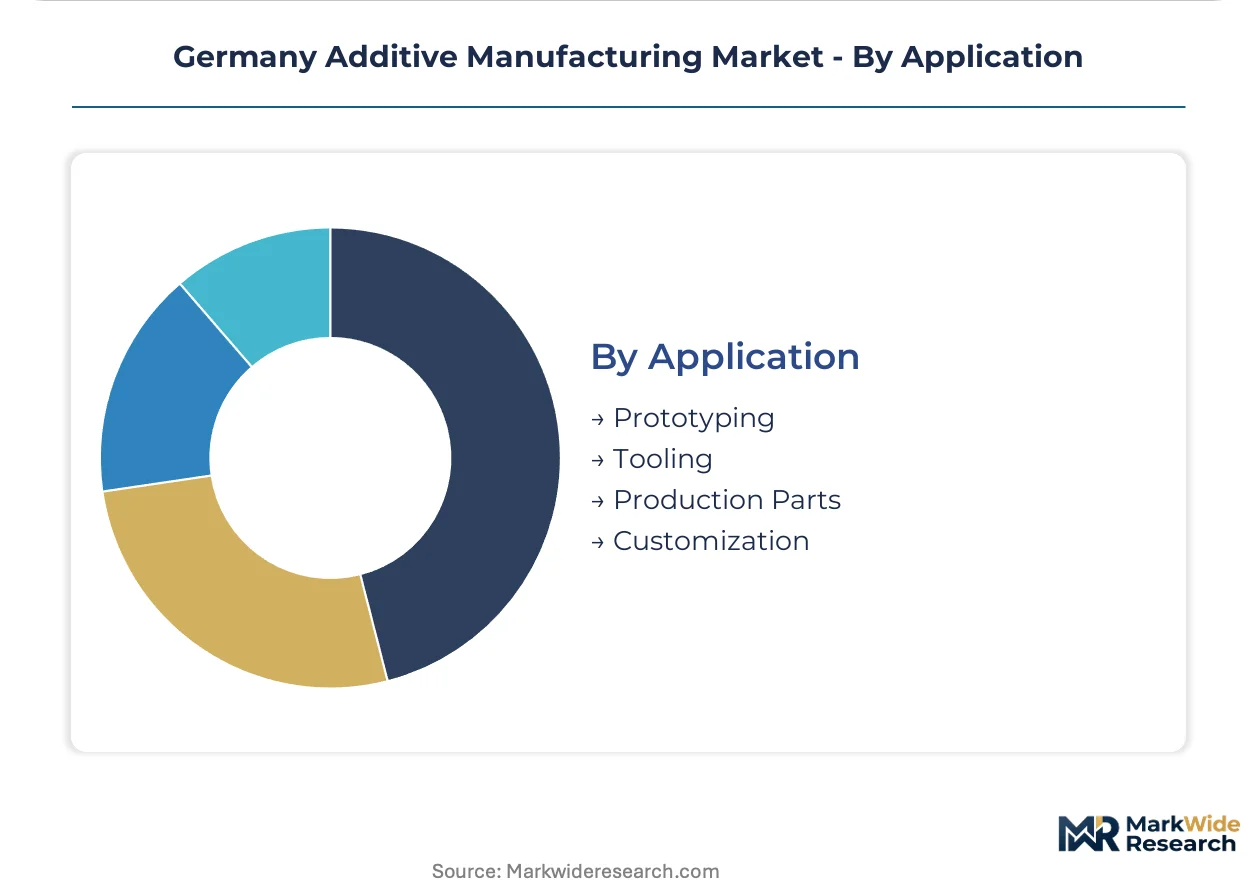
Application:
Volume concentration shifts from validation prints toward certified production as build monitoring reliability improves and qualification timelines compress.
- Prototyping:Form-and-fit validation for automotive design studios in Munich and Stuttgart sustains polymer system utilization, though lead time compression is eroding traditional model-making margins.
- Tooling:Conformal-cooled injection mold inserts around Wolfsburg reduce cycle times 20-40 percent for complex geometries, with Hovmand Tooling and similar specialists capturing mid-tier supplier demand.
- Production Parts:Series manufacturing of electric vehicle motor housings and aerospace brackets now qualifies under BAM protocols, with EOS and Trumpf systems dominating installed capacity for flight-critical approvals.
- Customization:Medical device personalization and luxury goods individualization exploit batch-size-one economics, with software margins from digital workflow tools supplementing hardware revenue.
Tooling holds the largest share; production parts are gaining share fastest as certification barriers fall.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic powder atomization capacity concentrates in three specialized facilities, creating geographic dependency for automotive and aerospace qualification programs. Bavaria and Baden-Württemberg anchor production demand, while eastern states present expansion corridors for contract manufacturing.
Bavaria
MTU Aero Engines and BMW drive laser powder-bed fusion adoption for turbine brackets and electric drivetrain housings. KBA type-approval requirements mandate 15-year parameter archiving for flight-critical components. Munich and Augsburg host the densest concentration of certified production workflows, with aerospace tier-1 suppliers specifying domestic machine capacity.
Baden-Württemberg
Porsche and Daimler Truck integrate conformal-cooled tooling into series production, reducing injection mold cycle times. EU Green Deal procurement rules require material waste documentation below 10 percent for public contracts. Stuttgart anchors automotive prototyping demand, while Tuttlingen medical device manufacturers exploit DLP systems for patient-specific implants.
North Rhine-Westphalia
Industrial machinery OEMs in the Ruhr region adopt directed energy deposition for stamping die repair and large-format tooling. REACH compliance on metal powder composition restricts supplier flexibility for nickel superalloy programs. Dortmund and Essen concentrate robotic arm-based repair services, extending asset life for legacy manufacturing equipment.
Thuringia
Former precision engineering regions lack additive infrastructure despite proximity to medical device clusters. BAM certification protocols for laser powder-bed fusion steels remain underdeveloped compared to western states. Jena and Erfurt offer first-mover positioning for contract manufacturers serving orthopedic implant demand from neighboring Saxony.
Hamburg
Maritime and aerospace suppliers specify dynamic beam modulation for nickel superalloy components. EU AI Act quality management obligations favor autonomous build monitoring systems with layer-wise thermal documentation. The port city's logistics infrastructure supports powder import and finished part export for Scandinavian aerospace programs.
Germany Additive Manufacturing Market Competitive Landscape
Concentration sits with laser-system specialists controlling beam source technology and powder-bed fusion platforms. Three domestic machine builders anchor the premium tier for aerospace and automotive qualification, while international polymer-system vendors compete on prototyping volumes. Strategic moves center on unbundling after-sales service contracts from hardware sales and expanding per-build-hour operational leasing models.
Among Germany-based system manufacturers, EOS GmbH exemplifies the laser-sintering heritage archetype spanning polymer and metal platforms. Trumpf occupies a position anchored by photonics-to-systems vertical control over beam source technology. SLM Solutions Group AG represents the large-format multi-laser specialization segment serving automotive and energy sector tooling demand.
| Leading Market Players |
|---|
| EOS GmbH |
| SLM Solutions Group AG |
| Trumpf |
| DMG Mori AG |
| Voxeljet AG |
| Stratasys Ltd |
| 3D Systems Corporation |
| Markforged Holding Corporation |
| Desktop Metal Inc |
| Others |
Pricing and Supply Chain Analysis
Polyamide powder substitution for machined aluminum in automotive jigs is redrawing supplier maps across Bavaria and Baden-Württemberg while compressing per-part economics for mid-tier contract manufacturers. This material shift simultaneously elevates domestic atomization premiums and erodes traditional tooling margins.
Pricing Analysis
EU Green Deal procurement mandates dictate the pricing tier structure for certified additive workflows, separating BAM-traceable aerospace components from uncertified prototyping services. Three-tier pricing stratifies across flight-critical, automotive-qualified, and non-certified economy levels based on parameter archiving depth and powder lot pedigree. Cost compression in polymer prototyping intensifies as FDM systems commoditize, while nickel superalloy builds retain premium positioning. Tier-1 automotive suppliers exhibit highest price sensitivity due to balance sheet constraints favoring operational leasing.
Supply Chain Analysis
Inventory cycles for spherical titanium and Inconel powder stretch 12-18 weeks against automotive qualification timelines, forcing build-schedule buffers that consume working capital. Domestic supply concentrates in three German atomization facilities, with secondary sourcing from UK and Swedish specialty metal producers. Argon and helium feedstock volatility creates margin exposure that powder suppliers cannot fully hedge. Distribution runs through machine OEM service contracts and direct mill relationships, with per-build-hour replenishment models gaining share among mid-tier Bavarian suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across technology tiers and regional supply gaps creates actionable positioning opportunities as electric drivetrain demand diversifies buyer archetypes beyond traditional aerospace dominance.
For Market Incumbents: Shield certified production margins by deepening backward integration into powder atomization capacity, countering single-source risk from the three domestic spherical alloy facilities. Lock in 15-year parameter archiving infrastructure ahead of KBA type-approval tightening, converting compliance burden into switching-cost moats against emerging Polish and Czech machine builders. For New Entrants and Emerging Players: Anchor in Thuringia and Saxony medical device clusters where BAM certification infrastructure remains underdeveloped against Tuttlingen demand density. Target orthopedic implant contract manufacturing as the most penetrable segment, leveraging proximity to Jena precision engineering heritage without western-state cost structures. Lead with DLP-based patient-specific cranial implant services to bypass laser powder-bed fusion qualification barriers. For Investors and Strategic Acquirers: The market sits at a production-part inflection phase that favors software-enabled service models over pure hardware plays. Long-term viability centers on autonomous build monitoring capabilities that satisfy EU AI Act quality management obligations. Watch for consolidation signals when mid-tier automotive suppliers abandon in-house additive capacity in favor of operational leasing, indicating hardware commoditization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Atomization | Captures margin pool from spherical titanium supply concentrated in three domestic facilities. |
| Autonomous Build Monitoring Platform Launch | Addresses EU AI Act documentation requirements for layer-wise thermal signature archiving. |
| Operational Leasing Model Expansion | Aligns with Ingolstadt automotive supplier preference for per-build-hour expenditure structures. |
| Medical Device Certification Pathway Investment | Unlocks Tuttlingen orthopedic implant demand under EU MDR biocompatibility protocols. |
| Regional Capacity Expansion in Thuringia | Exploits underpenetrated precision engineering base serving Saxony medical device clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laser powder-bed fusion technicians, aerospace tier-1 procurement leads, automotive platform engineers, and medical device quality managers. Secondary validation drew from BAM certification protocols, KBA type-approval documentation, EU Green Deal procurement databases, and ECHA REACH substance restriction filings. Bottom-up build-hour estimates across Bavarian and Baden-Württemberg installed bases were triangulated against top-down machine shipment data from domestic OEMs.
Across the analysis window, the forecast framework modeled technology adoption by material tier, end-use vertical, and regional production cluster density. CAGRs were derived from segment-level build-hour trajectories and powder consumption intensity per qualified application. Industry-specific inputs included BAM certification timeline compression rates and EU AI Act compliance cost curves for autonomous monitoring systems.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal procurement enforcement and stable argon supply; material deviation would warrant model refresh. Specific risks include REACH substance restriction expansion affecting cobalt-containing superalloys and KBA archiving requirement tightening beyond current 15-year mandates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
3D Printing Vacuum Furnaces Market
3D Printing Technology
Global 3D Printing in Medical Applications Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
US Additive Manufacturing Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market
3D Printing Technology
3D Printing Pellet Extruder Market