
 Latin America Industrial 3D Printing Market | 2026-2036
Latin America Industrial 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Industrial 3D Printing Market Intelligence
A divergence in capital investment for large-format metal printing capability is bifurcating the competitive landscape in Latin America. Stratasys leverages its extensive service network and material partnerships across Brazil and Mexico. In contrast, specialists like EOS GmbH differentiate with high-precision laser sintering systems for industrial clients. 3D Systems competes through its broad portfolio of both polymer and metal technologies, targeting a wider range of applications.
Industrial 3D printing is a process of building objects from a digital file, layer by layer, using methods like Fused Deposition Modeling with resolutions often below 100 microns. Its purpose in Latin America is to accelerate product development and enable on-demand production. While prototyping remains a dominant application, the use of metal powders for end-use parts in the automotive sector represents the fastest-growing segment. Demand from medical device manufacturers for custom implants using biocompatible photopolymers is also a significant growth area.
Regulations from bodies like Brazil's ANVISA govern the use of 3D-printed medical devices, mandating specific material and process certifications. Concurrently, national standards organizations in countries such as Mexico and Argentina are developing frameworks for industrial part qualification. Future competitiveness for vendors will depend on navigating these evolving country-specific certification pathways and building local validation capabilities.
Market Dynamics
The market's evolution is defined by the transition from rapid prototyping to qualified end-use part production. This shift is driven by available industrial-grade metal powders and developing country-specific certification pathways for critical applications.
Growth Catalysts
- Biocompatible Material Adoption:Demand for patient-specific medical devices in Brazil and Colombia drives adoption of certified photopolymers for implants and surgical guides.
- Automotive Sector Demand:Mexico’s Tier-1 suppliers use 3D printing for jigs, fixtures, and rapid prototyping, shortening vehicle development cycles.
- National Standards Development:Part qualification frameworks from standards bodies in Argentina and Mexico are clarifying validation pathways for industrial components.
Market Restraints
- High Input Costs:Imported high-performance metal powders and specialized polymers remain a significant cost barrier for small and medium-sized enterprises.
- Infrastructure Instability:Inconsistent power grids disrupt long print jobs, causing material waste and production delays for large-format systems.
- Complex Import Tariffs:Varied customs duties on hardware and materials across Mercosur and Pacific Alliance nations inflate operational costs.
Strategic Opportunities
- Service Bureau Expansion in Chile:Localized service bureaus can supply on-demand spare parts to Chile's critical mining and aquaculture industries.
- Aerospace Component Prototyping:Brazil's aerospace cluster is a key market for high-precision metal printing of lightweight prototype parts for aircraft manufacturers.
- Medical Device Regulation:ANVISA's refined guidelines in Brazil offer a clear certification pathway for vendors of 3D-printed medical devices.
Industry Challenges
- Skilled Workforce Scarcity:A shortage of technicians with expertise in design for additive manufacturing (DfAM) and material science limits the use of advanced systems.
- Part Certification Timelines:The lengthy and costly process of qualifying printed parts for critical sectors like aerospace and medical delays return on investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Industrial 3D Printing Market |
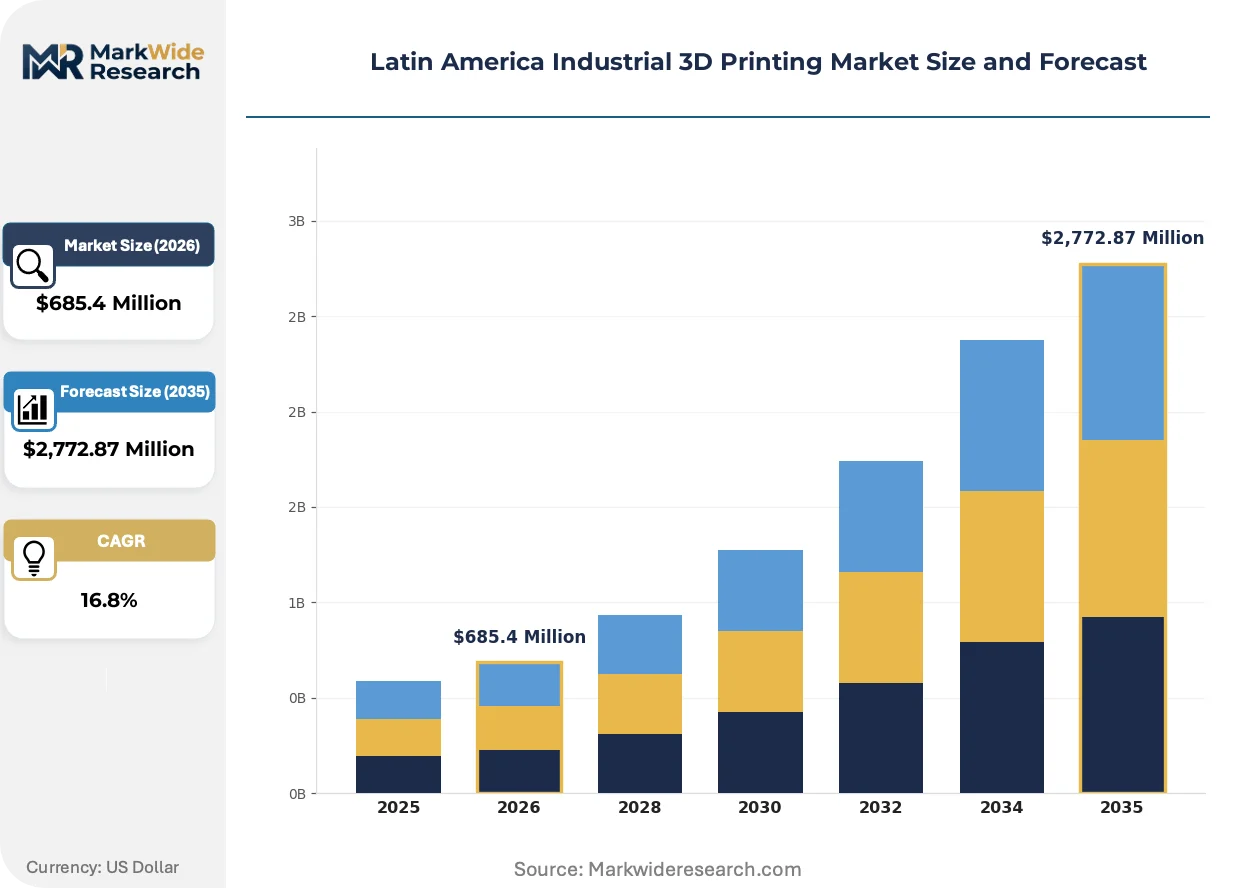
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,772.87 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Selective Laser Sintering, Stereolithography, Digital Light Processing, Binder Jetting Application: Prototyping, Tooling, End-Use Parts, Production, Custom Manufacturing End User: Aerospace, Automotive Tier-1 Suppliers, Consumer Electronics, Medical Device Manufacturers, Industrial Equipment Providers Material Type: Thermoplastics, Photopolymers, Metal Powders, Ceramics, Composite Materials |
| Companies Covered | Renishaw PLC, EnvisionTEC GmbH, Stratasys, Prodways, Sciaky Inc., 3D Systems, Formlabs, BigRep 3D, EOS GmbH, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Industrial 3D Printing Market Strategic Shifts & Innovations
A shift from standalone prototyping to integrated digital manufacturing workflows is defining the market. This involves the convergence of advanced materials with sophisticated software and process validation to produce certified, functional components on demand.
Multi-material polymer jetting allows for the creation of single parts with varied mechanical properties, such as rigid structures with flexible overmolds. Automotive and consumer product design firms in Brazil and Mexico are early adopters for realistic prototyping. This capability is supplanting the need for multi-part assembly processes for functional models, compressing product development cycles significantly.
Brazil's health agency, ANVISA, is formalizing its regulatory framework for the approval of 3D-printed medical implants and surgical guides. This policy mandates stringent process validation and material traceability, increasing the compliance burden for manufacturers. Consequently, medical device companies are investing in quality management systems and partnering with certified material suppliers to meet these new requirements for market entry.
Companies are increasingly opting for an outsourced "printing-as-a-service" model instead of making large capital investments in in-house equipment. This trend bypasses the need for internal expertise and machine maintenance, affecting direct hardware sales channels. The model is gaining significant traction among small and medium-sized manufacturers in industrial hubs like São Paulo and Monterrey for accessing advanced metal printing capabilities.
Latin America Industrial 3D Printing Market Segmentation
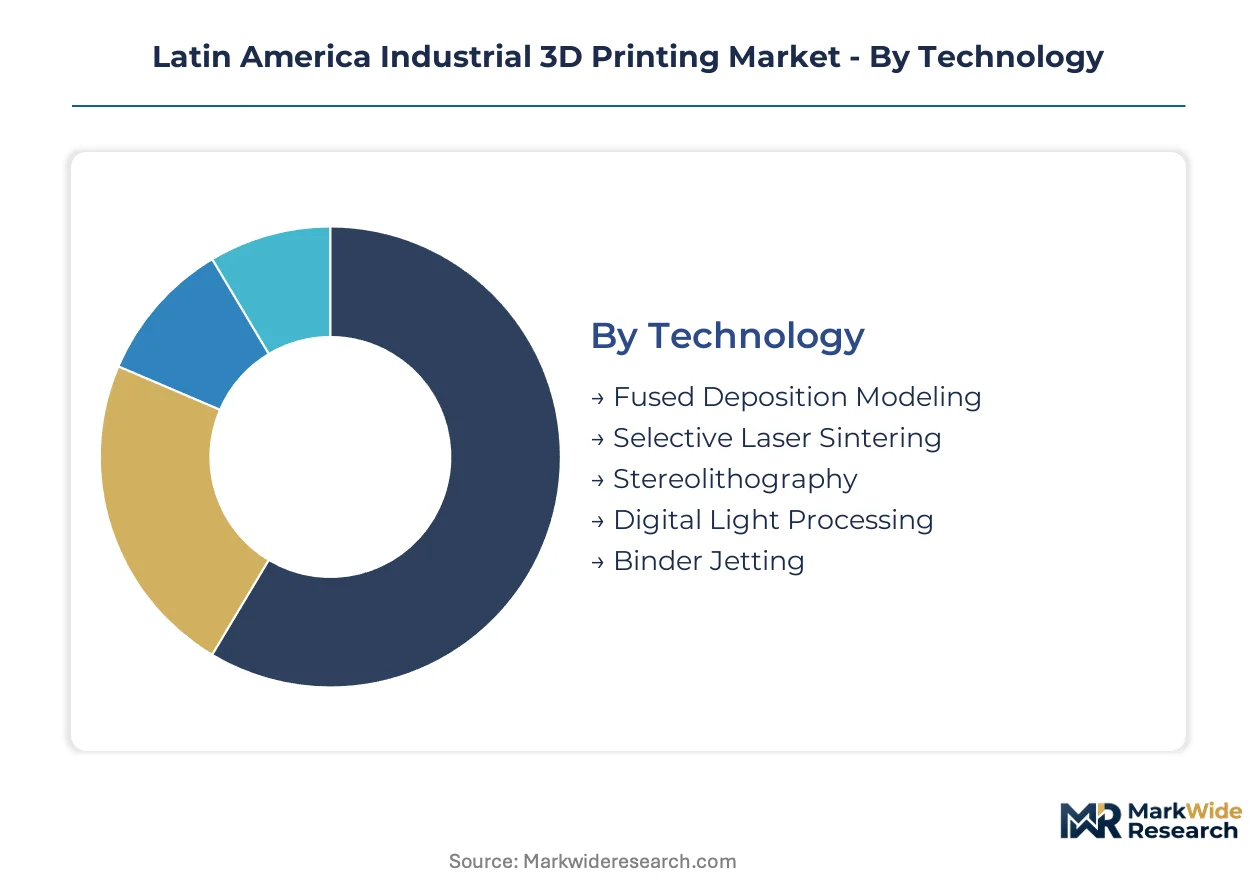
The Latin America Industrial 3D Printing Market is segmented by technology, application, end user, and material type, reflecting the diverse operational needs across the region. Understanding these distinct segments is crucial for identifying specific investment opportunities and tailoring solutions to localized industrial requirements. Each segment addresses unique challenges and leverages additive manufacturing capabilities differently.
Technology:
The market's technology segment reflects the diverse methods by which industrial 3D printing capabilities are delivered to end-users, ranging from in-house systems to specialized service bureau offerings. Each technology offers distinct advantages in material compatibility, part resolution, and production speed. Service bureaus often specialize in high-end systems.
- Fused Deposition Modeling:This extrusion-based process builds objects layer by layer using thermoplastic filaments, offering cost-effective prototyping and functional parts. Its widespread adoption across Brazil's automotive and consumer goods sectors is driven by relative simplicity and accessibility for initial product development stages.
- Selective Laser Sintering:Utilizing a laser to fuse powdered materials, typically polymers, SLS produces complex geometries with excellent mechanical properties and no support structures. Industrial manufacturing hubs in Mexico leverage SLS for durable tooling and jigs due to its precision and material versatility.
- Stereolithography:SLA employs UV lasers to cure liquid photopolymer resins layer by layer, known for its smooth surface finish and high accuracy for detailed prototypes.
- Digital Light Processing:DLP uses a digital light projector to cure an entire layer of liquid resin simultaneously, enabling faster print speeds for high-resolution models.
- Binder Jetting:This technology uses a liquid binding agent to join powdered materials, including metals, layer by layer, enabling large-scale production of complex parts.
Fused Deposition Modeling dominates the installed base. Selective Laser Sintering is where expansion concentrates.
Application:
The application segment delineates how different customer types leverage industrial 3D printing, from early-stage design validation to direct manufacturing of final components. Each application addresses specific customer needs, whether for speed, customization, or material performance. Industrial clients prioritize reliability and repeatability across all uses.
- Prototyping:This involves creating preliminary models to test designs, form, and fit, significantly accelerating product development cycles. Mexico's automotive sector heavily relies on rapid prototyping for new vehicle components, reducing time-to-market.
- End-Use Parts:These are functional components directly integrated into final products, requiring high material performance and stringent quality control. The automotive sector's adoption of metal powders for end-use parts represents the fastest-growing segment in Latin America.
- Tooling:This category includes the production of jigs, fixtures, and molds used in manufacturing processes, improving efficiency and reducing lead times.
- Production:Direct digital manufacturing of finished goods in smaller batches, offering design flexibility and reduced inventory costs for specialized products.
- Custom Manufacturing:Tailored production of unique parts or devices, often patient-specific, as seen in the medical sector for implants and prosthetics.
The shift from Prototyping to End-Use Parts defines the market's trajectory.
End User:
This segment illustrates the maturity of industrial 3D printing adoption across various industries, from sectors with established use cases to those just beginning to integrate additive manufacturing. Each end-user group presents distinct requirements for material properties, part certification, and production scale. Automotive and medical sectors show higher maturity.
- Automotive Tier-1 Suppliers:These suppliers integrate additive manufacturing for rapid prototyping, jigs, and fixtures, reducing development cycles and customizing production tools. Their demand in Mexico's manufacturing hubs is a primary driver for industrial 3D printing adoption.
- Medical Device Manufacturers:This sector utilizes 3D printing for patient-specific implants, surgical guides, and prosthetics, requiring biocompatible materials and strict regulatory compliance. Brazil's ANVISA regulations influence material and process choices for these manufacturers.
- Aerospace:Brazil's aerospace cluster employs 3D printing for lightweight prototype parts, focusing on advanced materials and high-precision metal printing.
- Consumer Electronics:Manufacturers use additive techniques for functional prototypes and custom housings, enabling faster design iterations and personalized product offerings.
- Industrial Equipment Providers:These providers leverage 3D printing for on-demand spare parts and customized components, improving operational efficiency.
Demand from Automotive Tier-1 Suppliers drives immediate market volume. Medical Device Manufacturers represent a significant future revenue stream.
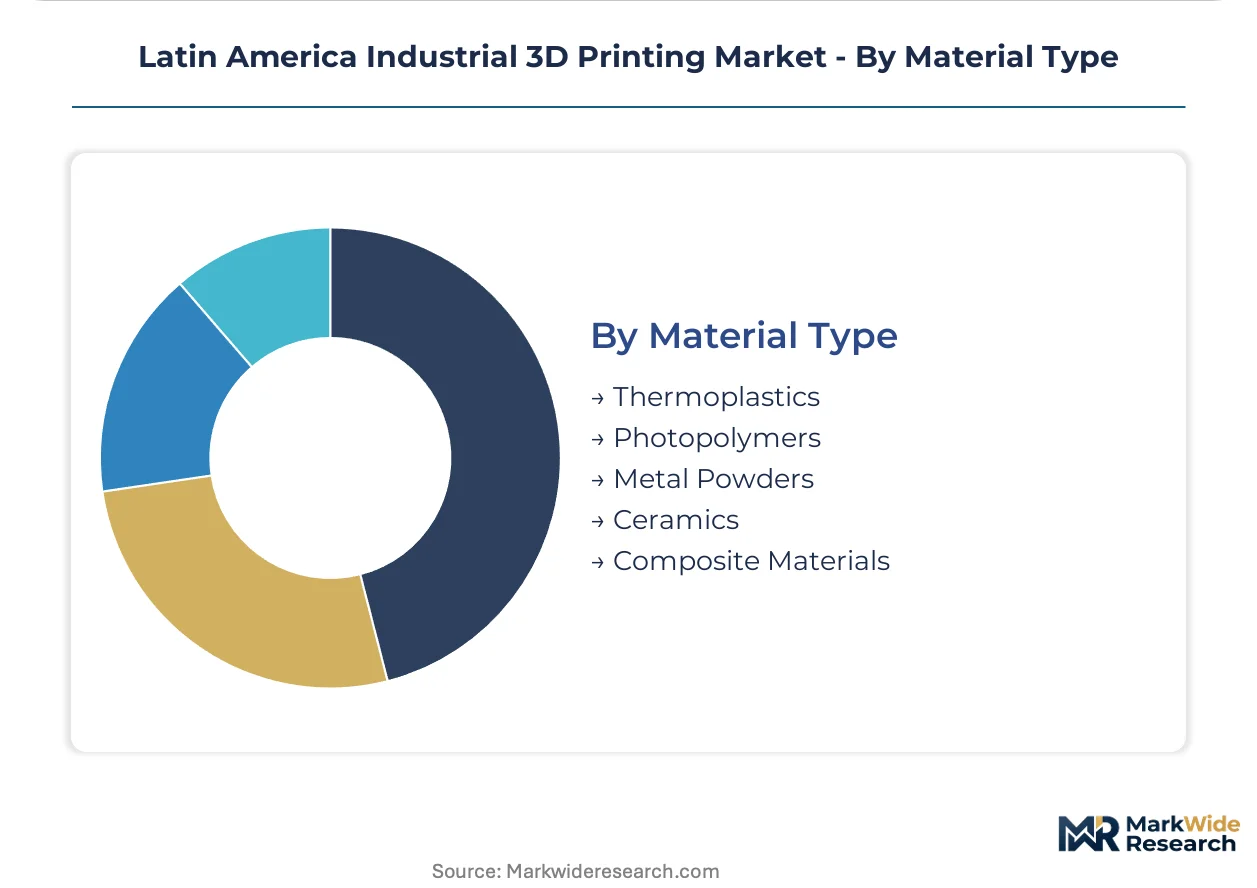
Material Type:
This segment categorizes materials based on their processing requirements and resulting cost tiers, influencing the accessibility and application scope of industrial 3D printing. High-performance materials typically command higher prices but enable more demanding applications. Material selection is critical for meeting specific part performance criteria and regulatory standards.
- Metal Powders:These materials, including stainless steel, titanium, and aluminum alloys, are critical for producing durable, high-strength end-use parts in demanding industrial applications. The increasing availability of advanced metal powders in Brazil's industrial hubs supports this segment's expansion.
- Photopolymers:Liquid resins cured by light, these materials offer excellent surface finish and fine detail, particularly for medical devices and high-resolution prototypes. Biocompatible photopolymers are essential for custom implants in Brazil and Colombia.
- Thermoplastics:Common examples include ABS, PLA, and Nylon, used primarily for cost-effective prototyping, jigs, and fixtures.
- Ceramics:These materials are employed for high-temperature and wear-resistant applications, offering unique properties for specialized industrial components and tooling.
- Composite Materials:Combining polymers with reinforcing fibers, these materials offer enhanced strength-to-weight ratios for lightweight, high-performance parts.
While Thermoplastics materials ensure broad accessibility, Metal Powders materials unlock higher-value applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Latin America's industrial 3D printing market demonstrates a complex interplay of import dependencies for advanced materials and hardware, balanced against a growing domestic capacity for specialized applications. Local manufacturing initiatives aim to reduce reliance on imported components, fostering regional innovation. This dynamic creates both challenges and opportunities for localized production capabilities.
Brazil
Demand for patient-specific medical devices and automotive prototypes drives significant industrial 3D printing activity. ANVISA's refined guidelines offer a clear certification pathway for 3D-printed medical devices, fostering market growth. São Paulo's industrial hubs are actively adopting Fused Deposition Modeling for initial product development stages.
Mexico
Automotive Tier-1 suppliers in Mexico heavily utilize industrial 3D printing for jigs, fixtures, and rapid prototyping. National standards organizations are developing frameworks for industrial part qualification, clarifying validation pathways. Monterrey's industrial manufacturing hubs leverage Selective Laser Sintering for durable tooling applications.
Argentina
National standards organizations in Argentina are developing frameworks for industrial part qualification, supporting local manufacturing. This clarifies validation pathways for components in sectors like machinery and aerospace prototyping. Córdoba's manufacturing sector is exploring additive manufacturing for specialized industrial components.
Chile
Localized service bureaus in Chile are expanding to supply on-demand spare parts for the critical mining and aquaculture industries. Government initiatives support technological adoption across key economic sectors to improve efficiency. Santiago's emerging tech sector is seeing increased interest in advanced metal printing capabilities for industrial repair.
Colombia
Biocompatible material adoption drives demand for patient-specific medical devices, particularly for implants and surgical guides. The country's national pharmaceutical regulator mandates specific material and process certifications for these applications. Bogotá's medical device cluster is a significant growth area for custom 3D-printed solutions.
Latin America Industrial 3D Printing Market Key Industry Players
Concentration sits with established industrial players offering diverse technology portfolios and specialized precision manufacturers, creating a bifurcated competitive landscape. This market separates between broad-spectrum providers and niche specialists focusing on high-performance applications. Companies are pursuing strategic partnerships and portfolio diversification to capture specific market segments. Investment in advanced material development and expanding service networks also represent key competitive moves.
Within the broad-spectrum providers, Stratasys exemplifies a strategy centered on leveraging extensive service networks and material partnerships, particularly across Brazil and Mexico. This approach allows them to address diverse customer needs through localized support. EOS GmbH, a German-based entity, occupies a position as a specialist in high-precision laser sintering systems, targeting industrial clients with demanding technical specifications. Their focus remains on advanced metal printing capabilities. 3D Systems represents another major player with a comprehensive portfolio encompassing both polymer and metal additive manufacturing technologies, aiming to serve a wider range of applications and end-user requirements across the Latin American market.
| Leading Market Players |
|---|
| Renishaw PLC |
| EnvisionTEC GmbH |
| Stratasys |
| Prodways |
| Sciaky Inc. |
| 3D Systems |
| Formlabs |
| BigRep 3D |
| EOS GmbH |
| Others |
Cost & Logistics Intelligence
Large-scale capital investment in industrial 3D printing systems establishes significant scale economies, which in turn shapes supply concentration for advanced hardware and sophisticated materials, influencing price floors for specialized applications.
Pricing Analysis
Industrial OEM buyers anchor value-based pricing for specialized 3D printing services and certified end-use components. Price differentiation stems from material type, part complexity, and required regulatory certifications like ANVISA approval for medical devices. Pricing softness influences prototyping services due to increased accessibility of FDM technology. Medical device manufacturers exhibit the lowest price sensitivity, prioritizing compliance and patient safety over cost.
Supply Chain Analysis
Just-in-time inventory strategies are difficult to implement for specialized 3D printing inputs, leading some users to maintain strategic stockpiles of critical materials. Geographic supply concentration for advanced metal powders and specialized photopolymers primarily rests in Europe and the United States. Raw material dependencies include high-performance metal alloys, biocompatible resins, and complex polymers. Complex import tariffs across Mercosur nations present a structural supply chain risk, inflating operational costs. Distribution runs through direct sales channels for hardware and localized material distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America industrial 3D printing market is experiencing a buyer-power shift, fueled by the fragmentation of service providers offering "printing-as-a-service" models, which gives end-users greater flexibility.
For Market Incumbents:Compound existing service networks by deepening material partnerships across Brazil and Mexico. Invest in local validation capabilities to navigate evolving country-specific certification pathways for critical parts. Offer hybrid hardware and service models to counter the "printing-as-a-service" trend. This strategy addresses the threat from new entrants leveraging localized service bureaus.
For New Entrants and Emerging Players:Anchor in specific underpenetrated niche applications, such as supplying on-demand spare parts to Chile's mining and aquaculture industries. Target medical device manufacturing in Colombia for patient-specific implants, leveraging biocompatible materials. A focused "printing-as-a-service" go-to-market angle can bypass high capital investment barriers for end-users.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized service bureaus with strong localized validation expertise. Long-term viability is strong in certified end-use parts for automotive and medical sectors. Acquisition targets should possess robust material science capabilities or established regulatory compliance frameworks. The signal to watch is the consistent approval of 3D-printed medical devices by ANVISA, indicating market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Service Network | Enhances localized support and accessibility for industrial clients across key manufacturing hubs. |
| Material Certification Investment | Ensures compliance with stringent regulatory requirements for medical and aerospace applications. |
| Advanced Metal Powder Development | Unlocks new high-value end-use applications requiring superior material performance. |
| "Printing-as-a-Service" Model Rollout | Lowers entry barriers for small and medium-sized enterprises to access advanced capabilities. |
| Localized Validation Capabilities | Streamlines the part qualification process, reducing time-to-market for critical components. |
Research Approach
A standing panel of automotive Tier-1 executives, medical device engineers, DfAM specialists, and material scientists provided ongoing calibration for market assumptions. This analysis combined insights from primary interviews with industry stakeholders and secondary validation through ANVISA guidelines, national standards documents, industrial manufacturing output data, and trade association reports. Bottom-up and top-down triangulation ensured data consistency.
Outputs were validated against external benchmarks to ensure the analytical framework's consistency across the analysis window. Segmentation dimensions included technology, application, end user, material type, and regional industrial clusters. CAGRs were derived from historical trends and projected adoption curves, integrating specific forecast inputs such as capital investment trends in automotive and medical device regulatory approvals.
Underlying assumptions cover stable import tariffs, consistent power grids, and skilled workforce availability, with deviation risk concentrated in infrastructure instability and material cost fluctuations. Revision becomes warranted when major economic shifts impact industrial investment across Latin America.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
3D Printer Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
Online 3D Printing Service Market
3D Printing Technology
Metal 3D Printing Service Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Digital 3D Printing Market
3D Printing Technology
Food 3D Printing Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
3D Printing Software Market