
 3D Concrete Printers Market | 2026-2036
3D Concrete Printers Market Size, Share, and Industry Trends Forecast 2026-2036
3D Concrete Printers Market Analytics
Direct equipment sales to large contractors is narrowing as rental and print-service models gain ground. COBOD International A/S leverages its open-source gantry architecture to sustain technology leadership across European demonstration projects. ICON Technology Inc. anchors the North American market through vertically integrated project delivery spanning design, printing, and finish work. Sika AG competes via its captive supply of printable admixtures and binder chemistries.
3D concrete printers are gantry or robotic-arm systems that extrude cementitious paste through a digitally controlled nozzle, typically achieving layer heights of 10-50 mm and compressive strengths matching conventional cast concrete after 28-day curing. These systems automate vertical construction to reduce labor input, material waste, and formwork requirements. Infrastructure Projects represent the most mature application segment, with standardized bridge components and retaining walls already passing structural certification in multiple jurisdictions. Residential Structures constitute the fastest-expanding category, driven by single-family housing shortages and the need for rapid disaster relief shelter deployment. Fiber-Reinforced material formulations command premium positioning due to their enhanced tensile performance and reduced steel reinforcement needs.
OSHA governs site safety protocols for automated construction equipment in the United States, while the EU Green Deal and CE marking requirements shape material compliance and carbon accounting across European deployments. Dubai's 3D Printing Strategy, administered by the country's national construction regulator, mandates specific adoption thresholds for printed public buildings and influences procurement specifications throughout the Gulf Cooperation Council. Stakeholders must monitor how evolving structural codes for layer-bonded concrete interact with insurance underwriting and project financing terms.
Market Dynamics
The 3D Concrete Printers Market is being fundamentally restructured by the EU Green Deal's embodied carbon limits, which are forcing equipment manufacturers and material suppliers to reengineer printable binder chemistries and automated construction workflows to meet tightening environmental compliance thresholds.
Growth Catalysts
- Regulatory Mandates:Dubai's 3D Printing Strategy mandates printed building targets for new public projects, creating procurement pull throughout the Gulf Cooperation Council.
- Material Innovation:Fiber-Reinforced concrete formulations are reducing steel reinforcement needs while enhancing tensile performance in load-bearing printed structures.
- Housing Shortages:Single-family housing deficits and disaster relief shelter requirements are accelerating adoption of rapid-build residential printing systems.
Market Restraints
- Input Cost Volatility:Specialized printable admixtures and high-performance binders face price instability due to concentrated chemical supply chains.
- Technical Limitations:Layer-bonded concrete exhibits anisotropic strength properties that complicate structural certification for high-rise applications.
- Regulatory Friction:OSHA site safety protocols for automated construction equipment create compliance complexity and deployment delays in the United States.
Strategic Opportunities
- Underpenetrated Geographies:Germany's residential construction sector shows accelerating adoption of printed wall assemblies as builders scale demonstration projects.
- Technology Convergence:Integration of gantry systems with robotic finishing arms is compressing total project timelines from print to occupancy.
- Channel Innovation:Equipment-as-a-service and print-service rental models are displacing direct capital sales to mid-sized contractors.
Industry Challenges
- Skill Gap:Shortage of technicians trained in digital construction workflows and nozzle calibration limits deployment velocity.
- Certification Timelines:Structural codes for layer-bonded concrete remain under development, creating insurance underwriting uncertainty.
- Capex Intensity:Gantry infrastructure and material testing facilities require substantial upfront investment before revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Concrete Printers Market |
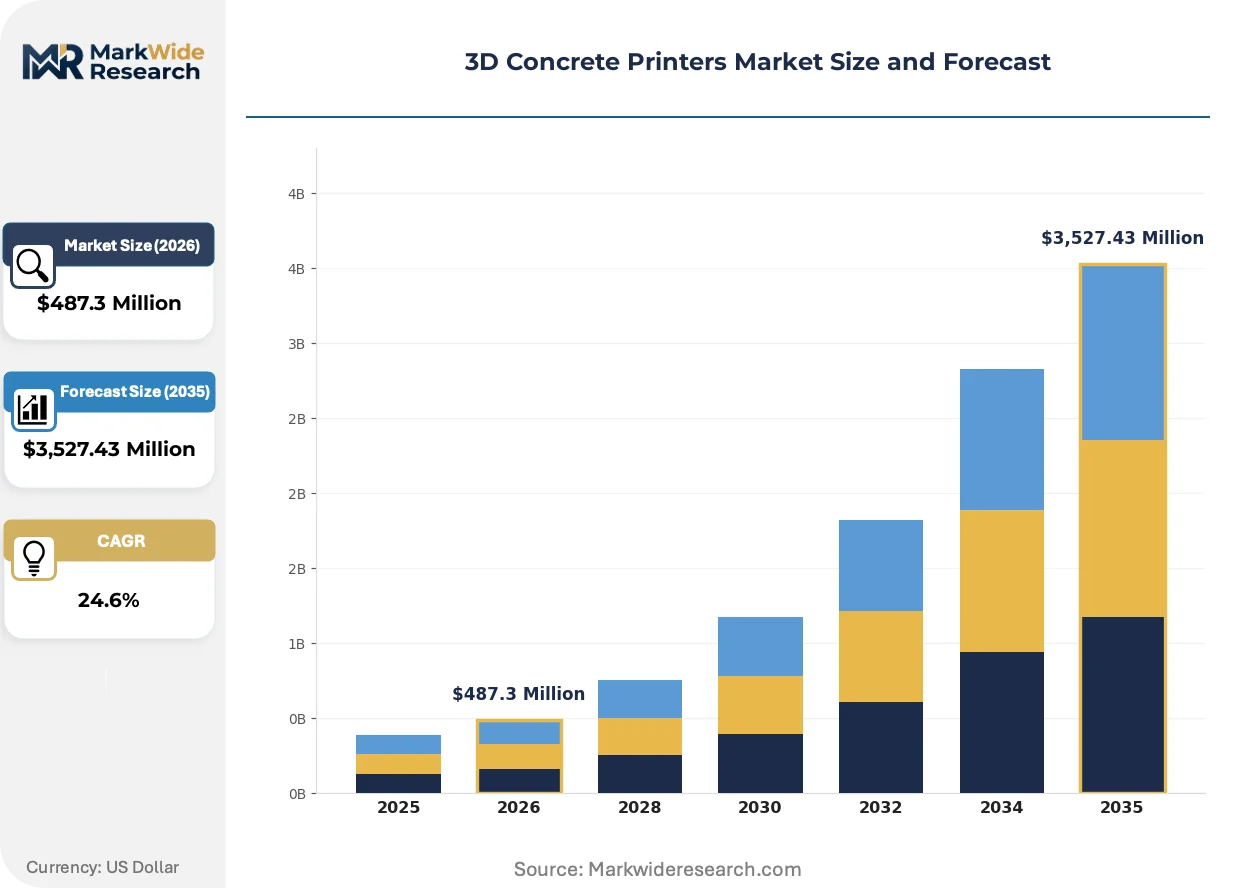
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $3,527.43 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Powder Bonding, Binder Jetting, Stereolithography End User: Construction Companies, Architectural Firms, Engineering Services, Urban Developers Material Type: Concrete Mix, Polymers, Recycled Aggregates, Fiber-Reinforced Application: Residential Structures, Commercial Buildings, Infrastructure Projects, Artistic Installations |
| Companies Covered | ICON Technology Inc., COBOD International A/S, Apis Cor Inc., Yingchuang Building Technique (Shanghai) Co., Ltd., XtreeE, CyBe Construction, Sika AG, Heidelberg Materials AG, WASP S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Concrete Printers Market Evolving Landscape
Equipment architectures and material platforms are converging around open-source gantry designs and captive admixture supply chains, compressing the traditional separation between hardware vendors and chemical suppliers.
Multi-material extrusion systems are hybridizing conventional Portland cement pastes with geopolymers and recycled aggregates. Infrastructure contractors in bridge and retaining wall segments are piloting these formulations at scale. The technology is hybridizing structural and non-structural applications previously served by distinct manufacturing methods.
The EU Green Deal's carbon accounting frameworks are reshaping material specifications across automated construction deployments. CE marking requirements now extend to layer-bonded concrete durability testing. European demonstration projects are responding by integrating life-cycle assessment tools directly into print-path planning software.
Contractor procurement patterns are gravitating toward vertically integrated project delivery spanning design, printing, and finish work. Equipment vendors are unbundling hardware sales from material supply agreements. This shift is most visible in North American residential developments where single-source accountability reduces interface risk between design and construction phases.
3D Concrete Printers Market Segmentation
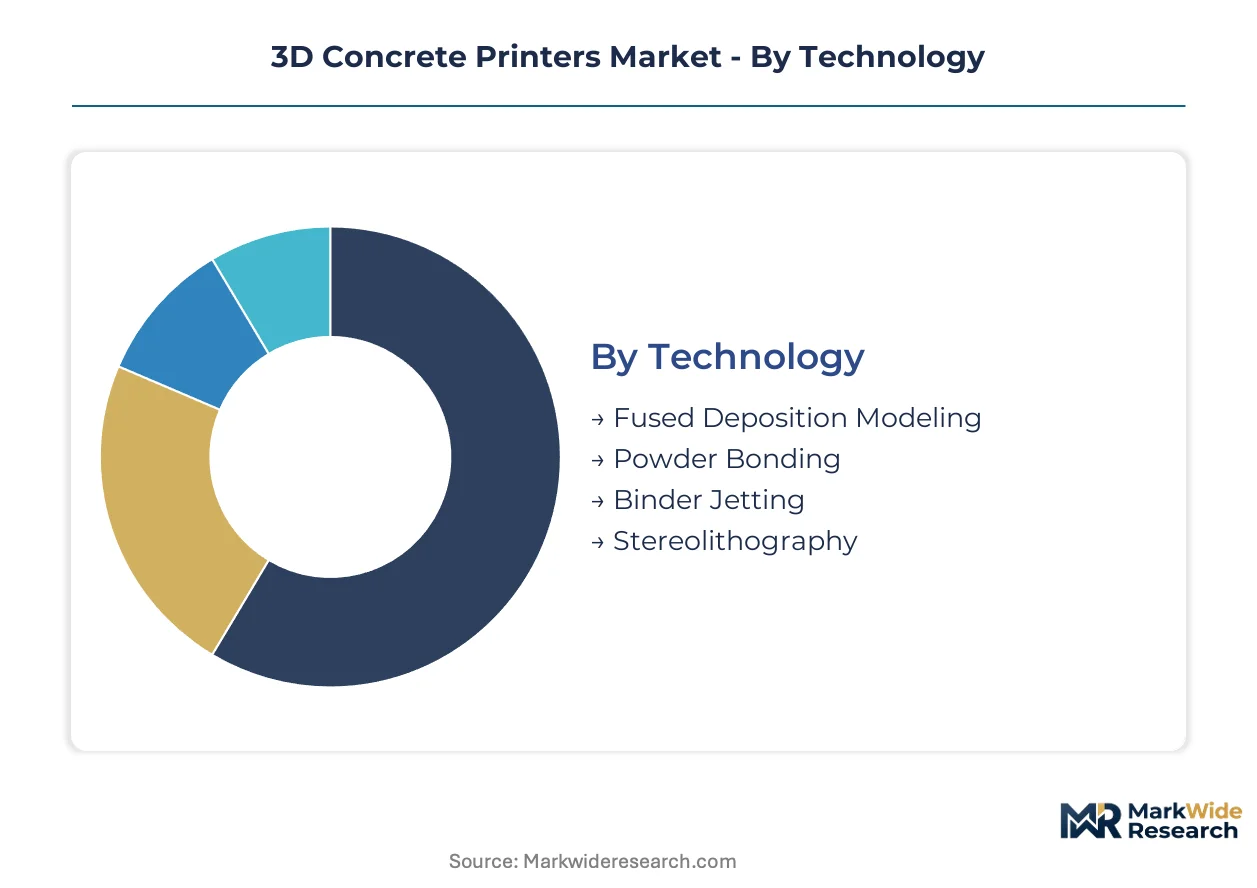
Technology selection determines equipment capex, material compatibility, and structural certification pathways for automated construction deployments. End-user sophistication and application risk tolerance further stratify procurement patterns across the value chain.
Technology:
Use-case spectrum spans high-throughput infrastructure work to precision architectural detailing, with each technology matching specific project scale and finish requirements.
- Fused Deposition Modeling:Extrudes cementitious paste through a digitally controlled nozzle in continuous bead deposition, achieving layer heights of 10-50 mm. Demand concentrates among German residential construction firms scaling printed wall assemblies, driven by EU Green Deal embodied carbon limits tightening material specifications. The dominant share belongs to Fused Deposition Modeling, while Powder Bonding is closing the gap fastest.
- Powder Bonding:Selectively deposits binding agent onto powder bed layers to build structures without formwork or support structures. UAE urban developers favor this approach for Dubai's mandated public building targets under the national 3D Printing Strategy.
- Binder Jetting:Jetting liquid binding agent across powder layers enables complex geometries with reduced material waste.
- Stereolithography:Photopolymer curing delivers highest surface finish precision for detailed architectural mockups and artistic components.
Equipment vendors are converging around open-source gantry architectures that accommodate multiple deposition technologies within modular platforms.
End User:
Customer sophistication tiers separate capital-intensive owner-operators from service-dependent project developers.
- Construction Companies:Direct equipment purchasers integrating printing into vertical project delivery from design through occupancy. North American contractors are adopting rental and print-service models to avoid upfront gantry infrastructure investment. Construction Companies hold the dominant share, though Architectural Firms are expanding their equipment footprint most aggressively.
- Architectural Firms:Design-centric adopters leveraging printing for rapid prototyping and bespoke structural elements.
- Engineering Services:Technical consultants specifying equipment for client projects and certifying layer-bonded concrete performance.
- Urban Developers:Project sponsors procuring printed structures through turnkey contracts without direct equipment ownership.
Procurement patterns are gravitating toward vertically integrated delivery spanning design, printing, and finish work.
Material Type:
Formulation chemistry dictates structural performance, carbon intensity, and regulatory compliance across deployment geographies.
- Concrete Mix:Standard Portland cement formulations with printable rheology modifiers matching conventional cast compressive strength after 28-day curing. Infrastructure contractors in bridge and retaining wall segments pilot these at scale under developing structural codes. Concrete Mix commands the dominant share, while Fiber-Reinforced formulations are climbing the fastest.
- Fiber-Reinforced:Polymeric or steel fiber additions reduce steel reinforcement needs while enhancing tensile performance in load-bearing printed structures.
- Polymers:Acrylic and epoxy-based printable systems for non-structural architectural elements and protective coatings.
- Recycled Aggregates:Construction demolition waste and industrial byproducts blended into printable mixes to meet EU Green Deal carbon accounting frameworks.
Material suppliers are capturing value through captive admixture supply chains that unbundle from hardware sales agreements.
Application:
Project type determines regulatory scrutiny intensity, insurance underwriting requirements, and acceptable technology risk profiles.
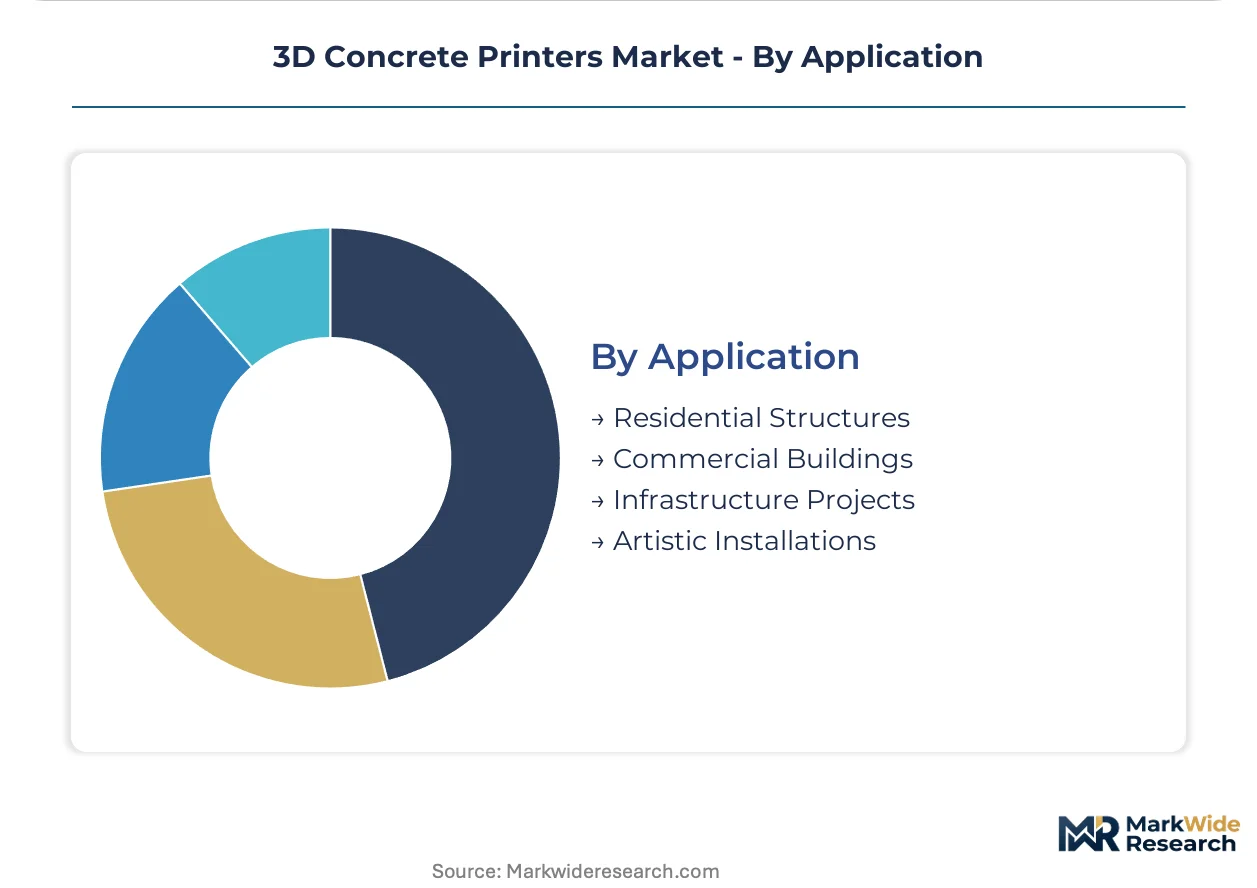
- Infrastructure Projects:Standardized bridge components and retaining walls passing structural certification in multiple jurisdictions represent the most mature deployment category. Fiber-reinforced formulations are gaining traction here for enhanced durability. Infrastructure Projects retain the dominant share, though Residential Structures are expanding most quickly.
- Residential Structures:Single-family housing and disaster relief shelter applications driving fastest equipment adoption, constrained by anisotropic strength properties complicating high-rise certification.
- Commercial Buildings:Mid-rise office and retail structures requiring extended fire rating certifications and occupancy code compliance.
- Artistic Installations:Non-structural sculptures and facade elements with reduced regulatory burden and shorter project timelines.
Application boundaries are blurring as multi-material extrusion systems hybridize structural and non-structural capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's 3D Printing Strategy mandates printed building targets for new public projects, creating procurement pull that extends across the Gulf Cooperation Council and influences demonstration projects in Germany and the United States.
United Arab Emirates
Dubai's 3D Printing Strategy, administered by MOHAP, mandates specific adoption thresholds for printed public buildings. Abu Dhabi's urban developers favor Powder Bonding technology for complex geometries in mandated public infrastructure. The Dubai-Al Ain corridor hosts concentrated demonstration projects for bridge components and retaining walls.
Germany
Residential construction firms are scaling adoption of printed wall assemblies as builders expand demonstration projects. The EU Green Deal's embodied carbon limits and CE marking requirements shape material compliance across automated construction workflows. Bavaria and North Rhine-Westphalia cluster equipment testing facilities and printable admixture development centers.
United States
Single-family housing shortages and disaster relief shelter requirements accelerate adoption of rapid-build residential printing systems. OSHA governs site safety protocols for automated construction equipment, creating compliance complexity in deployment timelines. Texas and California anchor vertically integrated project delivery spanning design, printing, and finish work.
China
Urban developers procure printed structures through turnkey contracts without direct equipment ownership, concentrating demand among construction companies. GB standards and MIIT regulations shape equipment certification and material testing protocols. The Yangtze River Delta and Pearl River Delta cluster multi-material extrusion pilot projects for bridge and retaining wall segments.
Saudi Arabia
NEOM Northwest and Riyadh anchor public project procurement influenced by Dubai's mandate spillover effects across the Gulf Cooperation Council. The national construction regulator adapts procurement specifications for layer-bonded concrete in public buildings. The Eastern Province concentrates material testing facilities for fiber-reinforced formulations in load-bearing applications.
3D Concrete Printers Market Competitive Landscape
On the supply side, the industry is consolidating around equipment vendors with captive material supply chains and open-source gantry architectures. The vendor base separates into three strategic archetypes: gantry system specialists, vertically integrated project deliverers, and captive admixture suppliers. Competitive moves center on technology licensing agreements and backward integration into printable binder chemistries.
Within the equipment architecture tier, COBOD International A/S and ICON Technology Inc. exemplify divergent approaches to market positioning, while Sika AG occupies a position as a captive admixture supplier unbundling hardware from material agreements. Among Asia-Pacific fabricators, Yingchuang Building Technique (Shanghai) Co., Ltd. represents the regional equipment manufacturing archetype.
| Leading Market Players |
|---|
| ICON Technology Inc. |
| COBOD International A/S |
| Apis Cor Inc. |
| Yingchuang Building Technique (Shanghai) Co., Ltd. |
| XtreeE |
| CyBe Construction |
| Sika AG |
| Heidelberg Materials AG |
| WASP S.r.l. |
| Others |
Value Network & Pricing Analysis
Admixture chemistry concentration in Germany and Switzerland feeds margin capture downstream among equipment vendors bundling printable binders with gantry hardware sales. Buyers face tiered cost structures where fiber-reinforced formulations command premiums over standard Portland cement mixes, compressing contractor margins on fixed-price public tenders.
Pricing Analysis
Volume-discount tiering structures dominate equipment procurement, with gantry system vendors offering scaled rebates for multi-unit fleet purchases exceeding five installations. Price differentiation separates CE-certified European configurations from economy-tier Asian fabricators lacking structural code equivalency. Cost compression in standard concrete mixes is intensifying because recycled aggregate suppliers are expanding capacity faster than certification protocols can validate performance. Urban developers in the UAE show lowest price sensitivity due to mandated adoption thresholds, while mid-sized North American contractors face acute budget constraints under rental-model fee structures.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized gantry fabricators in China and precision nozzle suppliers in Germany, with final assembly increasingly regionalizing to reduce shipping costs for oversized equipment. Raw material dependencies center on printable rheology modifiers sourced from Sika AG and Heidelberg Materials AG captive supply chains, plus high-performance steel fiber reinforcement from Japanese metallurgical specialists. Single-source vulnerability persists in digitally controlled extrusion nozzles, where two European suppliers hold effective duopoly. Distribution runs through equipment-as-a-service platforms displacing traditional capital sales channels, with material supply agreements unbundled from hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendor fragmentation creates acquisition opportunities as the shift from direct sales to rental and print-service models splinters incumbent revenue pools into specialized niches.
For Market Incumbents: Entrench technology leadership by deepening captive supply of printable admixtures and binder chemistries, insulating margin pools from commodity cement price volatility. Acquire regional service capabilities in Germany and Texas to control deployment velocity as rental models displace capital sales. Certification investment in CE marking for layer-bonded concrete durability testing represents the critical defensive lever against emerging Asian fabricators. For New Entrants and Emerging Players: Pursue white-space positioning in robotic finishing arm integration, where gantry-to-occupancy timeline compression commands premium pricing. Target Saudi Arabia's NEOM corridor and Riyadh public project procurement, where Dubai mandate spillover effects concentrate demand without incumbent equipment saturation. A print-service-only go-to-market model bypasses capital intensity barriers while capturing recurring revenue from mid-sized contractors. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated project deliverers spanning design, printing, and finish work, as single-source accountability reduces interface risk and extends contract duration. Long-term viability across the projection horizon hinges on structural code maturation for layer-bonded concrete and insurance underwriting acceptance. Monitor CE marking timeline acceleration and OSHA protocol finalization as inflection indicators for North American deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Printable Admixtures | Captive supply of fiber-reinforced binders locks in margin pools against chemical price volatility. |
| Equipment-as-a-Service Platform Launch | Rental models displace direct sales to mid-sized contractors unable to absorb gantry capex intensity. |
| Robotic Finishing Arm Integration | Compression of print-to-occupancy timelines commands premium positioning in residential segments. |
| CE Marking Pathway Investment | EU Green Deal carbon accounting frameworks require validated layer-bonded concrete durability testing. |
| Joint Venture with Regional Contractors | Turnkey project delivery in Saudi Arabia and UAE leverages mandated public building procurement thresholds. |
Research Methodology
Operator-level perspectives from construction company procurement directors, gantry system maintenance technicians, printable admixture R&D leads, and urban developer project sponsors anchored the qualitative base. Primary interview findings triangulated against secondary validation from SEC filings of Heidelberg Materials AG, EU Green Deal regulatory documentation, Dubai 3D Printing Strategy procurement specifications, and OSHA automated construction equipment safety protocols. Bottom-up equipment deployment counts and top-down cementitious material demand estimates converged through iterative reconciliation.
Scenario-bracketing framed volume and value outputs across the projection horizon, with technology adoption curves segmented by gantry versus robotic arm architectures, material type stratification across fiber-reinforced and standard formulations, and application risk tolerance spanning infrastructure certification maturity versus residential structural code development. CAGRs derived from logistic diffusion modeling of regulatory mandate compliance timelines and contractor capital expenditure cycle analysis. Forecast inputs incorporated EU embodied carbon limit phase-in schedules and UAE public project procurement thresholds.
Sensitivities concentrate around OSHA protocol finalization delays, CE marking timeline acceleration for layer-bonded concrete, and fiber-reinforced formulation price volatility from concentrated chemical supply chains. Quarterly review of structural code committee publications, insurance underwriting guideline releases, and national construction regulator procurement specification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
Global 3D Printed Electronics Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
3D Printing Service Bureaus Market
3D Printing Technology
Selective Laser Sintering Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
3D Printing Vacuum Furnaces Market
3D Printing Technology
North America 3D Printing Market