
 Digital Light Processing (DLP) Printer Market | 2026-2036
Digital Light Processing (DLP) Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Light Processing (DLP) Printer Market Insights
Dental prosthetics is repositioning from niche adoption to a primary demand anchor for DLP hardware. Formlabs leverages its vertical integration into resin chemistry to sustain pricing power across clinical workflows. Stratasys Ltd anchors its position through manufacturing scale in production-grade systems, while 3D Systems Corporation differentiates via deep specialization in biocompatible materials for patient-specific devices.
Digital Light Processing printers project ultraviolet light through a digital micromirror device to selectively cure photopolymer resin layers with resolutions reaching 25 microns, serving precision manufacturing needs from jewelry casting patterns to surgical guides. Industrial printers command the dominant share of installed value as manufacturers replace CNC workflows for complex geometries, though personal printers represent the fastest-expanding volume tier among hobbyist jewelers and tabletop gaming enthusiasts. LED-based systems are displacing legacy lamp architectures across all tiers, concentrating margin pools with semiconductor light source suppliers.
FDA 510(k) requirements govern biocompatible resin clearance in the United States, while the EU Medical Device Regulation (MDR) imposes post-market surveillance obligations on European clinical deployments. China's SAMR enforces GB standards for electromagnetic compatibility and workplace chemical exposure, shaping import certification timelines for foreign equipment vendors. Stakeholders must monitor evolving resin toxicity classifications and regional conformity assessment pathways to avoid supply chain disruption.
Market Dynamics
LED-based projection systems are automating layer exposure workflows, compressing print cycle times from minutes to seconds while concentrating supplier power among semiconductor foundries in Taiwan and South Korea.
Growth Catalysts
- EU MDR post-market surveillance:Streamlined conformity assessment for biocompatible resins accelerates clinical deployment of patient-specific surgical guides across German and French dental networks.
- Jewelry casting patterns:Investment casting houses in India and Turkey adopt desktop DLP systems to eliminate wax pattern labor, reducing prototype turnaround from days to hours.
- Photopolymer resin chemistry:Ceramic-filled and rubber-toughened formulations expand addressable applications from rigid prototypes to functional end-use parts in hearing aid shells.
Market Restraints
- Digital micromirror device supply:Texas Instruments maintains effective monopoly on high-resolution DMD chips, creating single-source vulnerability for printer OEMs above 4K pixel arrays.
- Acrylate monomer price volatility:Petrochemical feedstock fluctuations drive 15-30% quarterly swings in standard resin material costs, squeezing consumables margin pools.
- Build volume limitations:Z-axis constraints below 300mm restrict DLP adoption in aerospace tooling and automotive fascia prototyping favoring fused deposition alternatives.
Strategic Opportunities
- India's medical device PLI scheme:Domestic manufacturing incentives attract contract printer assembly for export to Middle East and African clinical markets.
- Silicone molding convergence:Hybrid workflows combining DLP printed masters with platinum-cure tooling open industrial soft-goods prototyping previously served by CNC aluminum.
- Same-day crown production:Chairside integration in US and German dental practices creates demand for compact autoclave-compatible systems with validated resin cartridges.
Industry Challenges
- ISO 13485 quality system implementation:Medical device printer manufacturers face 18-24 month certification timelines blocking revenue recognition from hospital capital budgets.
- Post-processing automation:Manual resin washing and UV curing steps create bottleneck capacity constraints limiting effective machine utilization below 40% in service bureau environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Light Processing (DLP) Printer Market |
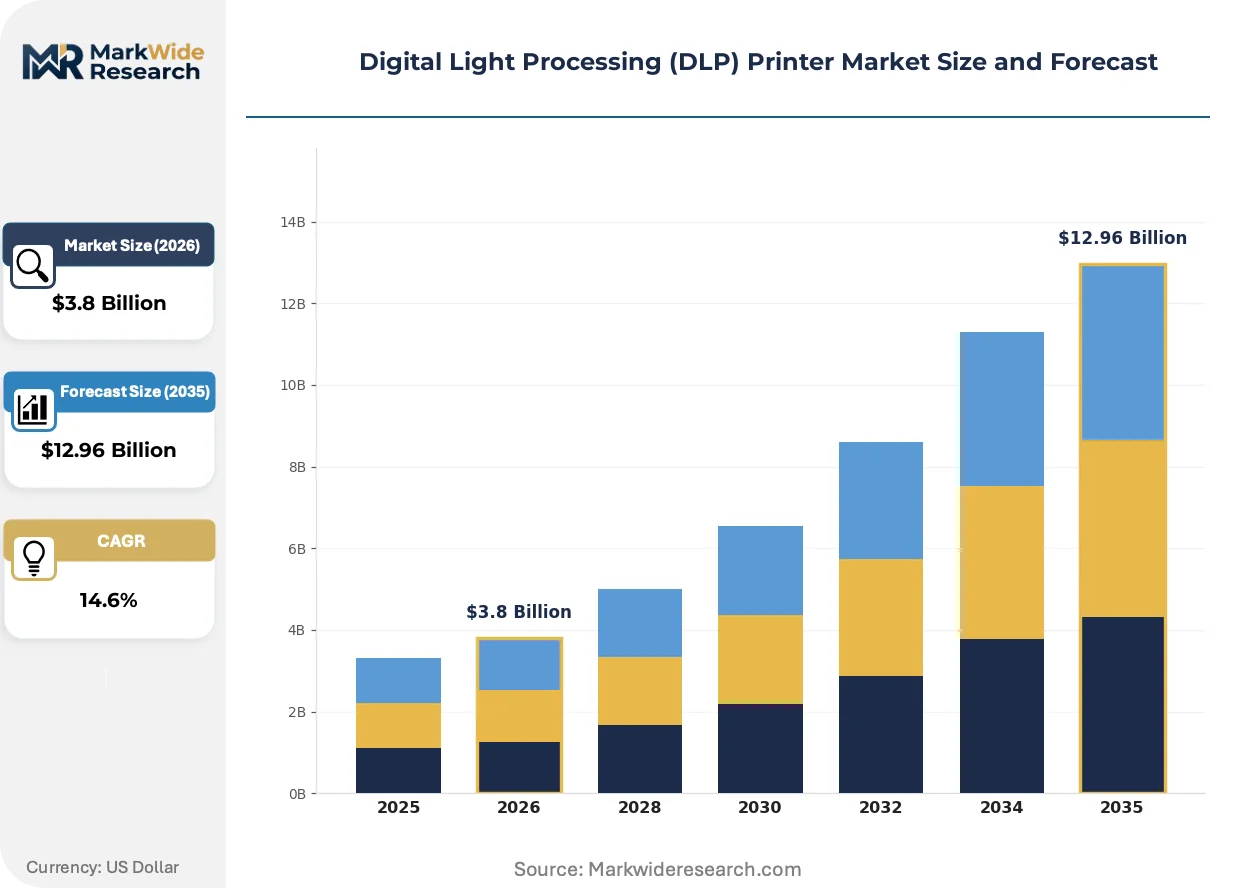
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Printers, Personal Printers, Educational Printers, Commercial Printers Technology: LED, Laser, Inkjet, Electrostatic End User: Manufacturers, Designers, Educators, Hobbyists Application: Prototyping, Production, Art, Education |
| Companies Covered | EnvisionTec, EOS GmbH, ETEC, Optomec, XYZprinting, Formlabs, Stratasys Ltd, Voxeljet AG, 3D Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Light Processing (DLP) Printer Market Trends and Innovations
Computational exposure algorithms and multi-material vat switching are redefining throughput benchmarks, while regulatory data requirements reshape competitive moats around clinical-grade hardware.
Pixel-shifting optical engines are automating sub-25 micron feature resolution without DMD hardware upgrades. Dental laboratories in the United States deploy these retrofitted systems for margin-free crown fits. The technology compresses equipment refresh cycles from five years to eighteen months.
China's SAMR enforcement of GB electromagnetic compatibility standards for networked manufacturing equipment extends import certification timelines for foreign printer vendors. Domestic champions leverage pre-approved component libraries to accelerate product registration. Industrial users in the Pearl River Delta increasingly specify locally certified systems to avoid deployment delays.
Service contracts unbundle from hardware purchases as buyer sophistication matures. German dental technicians now procure resin subscriptions tied to validated print parameters rather than capitalizing standalone equipment. This consumption-model pivot concentrates recurring revenue with vendors possessing captive material chemistry capabilities.
Digital Light Processing (DLP) Printer Market Segmentation
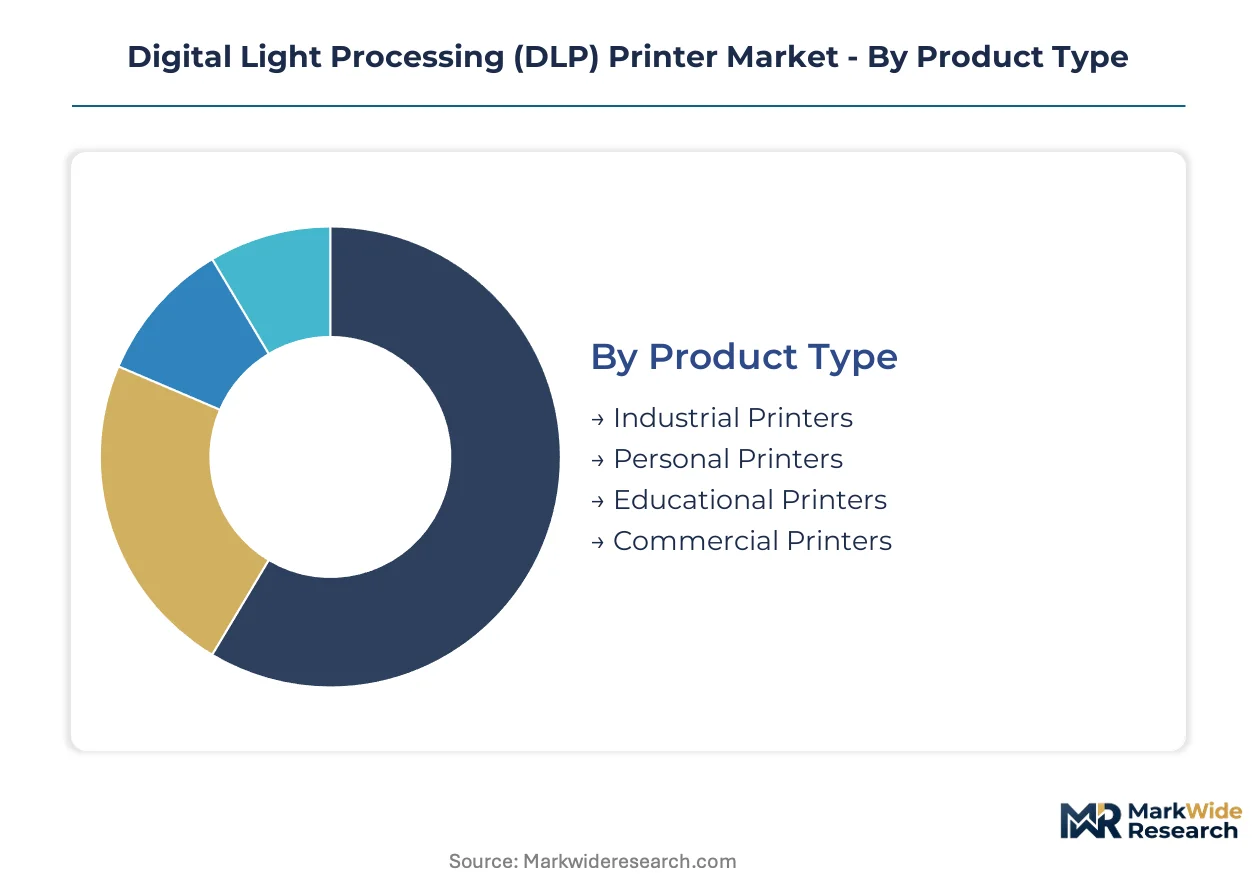
DLP printer segmentation reveals divergent margin structures across hardware tiers. LED-based systems command premium pricing in clinical workflows while personal units expand through hobbyist channels with compressed economics.
Product Type:
Industrial systems anchor installed value through production-grade throughput, while personal printers drive volume expansion among jewelry makers and tabletop gaming enthusiasts.
- Industrial Printers:These systems deploy high-power LED arrays and precision linear motion stages to cure photopolymer layers at sub-50 micron resolution. German dental laboratories and contract manufacturers in China's Pearl River Delta concentrate procurement here, drawn by validated workflows for same-day crown production and consumer electronics prototyping that compress turnaround from days to hours.
- Personal Printers:Compact desktop units with 2K-4K monochrome LCD panels dominate hobbyist adoption for jewelry casting patterns and miniature figurines. Indian and Turkish investment casting houses deploy these systems to eliminate wax pattern labor, though build volume constraints below 200mm restrict functional end-use applications.
- Educational Printers:Ruggedized enclosures and simplified resin handling target university maker spaces and technical training programs.
- Commercial Printers:Mid-tier systems bridge personal flexibility with industrial reliability for service bureaus and design studios.
Today's leader: Industrial Printers. Tomorrow's challenger: Personal Printers.
Technology:
Light source architecture determines resolution limits, maintenance intervals, and semiconductor supply chain exposure across all hardware tiers.
- LED:Solid-state emission at 405nm wavelength dominates new installations, eliminating lamp replacement cycles and enabling sub-second layer exposure times. Taiwan and South Korean foundries concentrate supplier power for high-brightness chip arrays, creating procurement leverage for OEMs scaling production.
- Laser:Galvanometer-steered UV sources persist in high-resolution dental applications requiring edge acuity below 25 microns.
- Inkjet:Material jetting hybrids combine DLP curing with multi-material deposition for gradient mechanical properties.
- Electrostatic:Niche powder-bed approaches for ceramic-filled resins in investment casting applications.
LED systems capture the steepest expansion trajectory as semiconductor foundries scale 405nm chip capacity.
End User:
Buyer sophistication determines procurement model, with consumption-based resin subscriptions displacing capital purchases among clinical technicians.
- Manufacturers:Production engineers in hearing aid and dental device fabrication specify validated systems with ISO 13485 quality documentation. FDA 510(k) clearance pathways for biocompatible resins streamline hospital capital budget approval, though EU MDR post-market surveillance obligations extend European deployment timelines.
- Designers:Industrial design studios and architectural model shops prioritize build volume and surface finish over throughput metrics.
- Educators:Technical institutes and research laboratories drive training-equipment procurement with emphasis on safety enclosures and curriculum integration.
- Hobbyists:Tabletop gaming miniature painters and jewelry makers expand fastest by unit volume, purchasing through direct-to-consumer channels with minimal service attachment.
Manufacturers extract premium pricing through regulatory compliance; hobbyists expand addressable market breadth.
Application:
Workflow positioning determines hardware specification, with production applications demanding validated repeatability absent in exploratory prototyping.
- Prototyping:Design iteration and form-validation workflows dominate commercial printer utilization, with silicone molding convergence creating hybrid soft-goods prototyping demand.
- Production:End-use manufacturing of dental crowns, hearing aid shells, and jewelry casting patterns requires biocompatible resin chemistry and autoclave-compatible hardware. German dental technicians now procure resin subscriptions tied to validated print parameters rather than capitalizing standalone equipment.
- Art:Sculptural and jewelry artists exploit DLP resolution for lost-wax casting masters with surface detail unattainable through hand carving.
- Education:Curriculum deployment emphasizes safe handling protocols and design-for-manufacturability principles rather than production economics.
Production applications concentrate margin pools; art and education expand installed base for future upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting DLP printer assembly toward jurisdictions with streamlined medical device certification, as manufacturers seek to bypass extended FDA and EU MDR timelines while maintaining access to major clinical markets.
United States
FDA 510(k) clearance pathways for biocompatible resins are accelerating hospital procurement of chairside crown production systems. Dental laboratories in California and Texas are expanding validated workflows for same-day prosthetics. Boston-area medical device clusters concentrate demand for patient-specific surgical guides with ISO 13485 documentation.
Germany
EU MDR post-market surveillance obligations extend deployment timelines for clinical-grade hardware, though streamlined conformity assessment accelerates adoption in Bavarian and North Rhine-Westphalian dental networks. Frankfurt and Stuttgart industrial zones anchor precision manufacturing demand for jewelry casting patterns. German dental technicians increasingly procure resin subscriptions rather than capitalizing standalone equipment.
China
SAMR enforcement of GB electromagnetic compatibility standards extends import certification timelines for foreign vendors. Domestic champions leverage pre-approved component libraries to accelerate product registration. The Pearl River Delta concentrates contract manufacturing for consumer electronics prototyping, with Shenzhen and Dongguan facilities specifying locally certified systems to avoid deployment delays.
India
The medical device PLI scheme attracts contract printer assembly for export to Middle Eastern and African clinical markets. Mumbai and Ahmedabad investment casting houses adopt desktop DLP systems to eliminate wax pattern labor. Tamil Nadu technical institutes drive educational printer procurement with emphasis on safety enclosures and curriculum integration.
South Korea
Semiconductor foundries in Seoul and Busan concentrate supplier power for high-brightness 405nm LED arrays, creating procurement leverage for OEMs scaling production. MFDS medical device regulations govern clinical resin clearance, though streamlined pathways support hearing aid shell manufacturing in Gyeonggi-do medical device clusters. Domestic printer vendors leverage captive LED supply relationships.
Digital Light Processing (DLP) Printer Market Competitive Landscape
Capacity expansion dominates the current landscape as vendors scale LED-based system production to capture dental and jewelry casting demand. The vendor base stratifies across three tiers: integrated resin-chemistry specialists, manufacturing-scale production-system builders, and regional assembly operations serving price-sensitive markets. Strategic archetypes include backward-integrated material formulators, semiconductor-light-source partners, and certified clinical-workflow validators. M&A activity and geographic licensing agreements represent the dominant competitive moves.
Among North American-anchored specialists, Formlabs and 3D Systems Corporation exemplify contrasting approaches to clinical-market penetration, with the former representing captive resin-chemistry integration and the latter anchoring biocompatible-material specialization. Stratasys Ltd occupies a position within the manufacturing-scale tier. German-origin EOS GmbH and Voxeljet AG sit within the precision-industrial segment, while EnvisionTec and ETEC represent dental-vertical focus. Taiwan- and South Korea-based LED suppliers concentrate upstream component leverage.
| Leading Market Players |
|---|
| EnvisionTec |
| EOS GmbH |
| ETEC |
| Optomec |
| XYZprinting |
| Formlabs |
| Stratasys Ltd |
| Voxeljet AG |
| 3D Systems Corporation |
| Others |
Pricing and Supply Chain Analysis
German dental laboratories and contract manufacturers in China's Pearl River Delta dominate procurement volume, anchoring a subscription-based pricing model where resin subscriptions displace capital purchases. This buyer concentration enables vendors with captive chemistry capabilities to extract recurring revenue while compressing hardware margins.
Pricing Analysis
Distributor margins in the clinical tier run 15-25 points above hobbyist channels due to ISO 13485 validation requirements. Pricing stratifies across premium certified systems, standard professional units, and economy desktop tiers. Cost compression in the personal printer segment intensifies as Chinese OEMs scale LED-based architectures. Hobbyists exhibit extreme price sensitivity, while manufacturers absorb premium pricing for FDA-cleared workflows.
Supply Chain Analysis
Regional distribution centers in Taiwan, South Korea, and Germany feed assembly operations with semiconductor light sources and precision motion components. The chain draws from Texas Instruments for DMD chips, Taiwanese foundries for 405nm LED arrays, and German linear stage suppliers. Single-source vulnerability at the DMD layer creates structural risk. Distribution runs through direct OEM relationships for industrial tiers and e-commerce platforms for personal units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on LED cost-down curves and the shift toward consumables-anchored revenue models that extend customer lifetime value beyond hardware depreciation cycles.
For Market Incumbents: Hedge against DMD supply concentration by qualifying alternative optical engine architectures from emerging MEMS suppliers. Deepen backward integration into resin chemistry to defend subscription revenue against Formlabs' captive formulation advantage. Prioritize certification investment in India's PLI scheme to capture Middle East and African export demand before domestic champions consolidate assembly share. For New Entrants and Emerging Players: Capture the silicone molding convergence opportunity in industrial soft-goods prototyping, where hybrid DLP-CNC workflows remain underpenetrated. Target Turkish and Indian investment casting houses with desktop systems priced below German incumbents. Lead with resin subscription trials to bypass capital budget friction in service bureau environments. For Investors and Strategic Acquirers: Dental technology conglomerates are the most active acquirers in this space, seeking chairside workflow integration. Long-term viability favors vendors with simultaneous control over light source procurement, resin chemistry, and regulatory clearance pathways. Watch for MFDS streamlined clearance announcements in South Korea as an inflection signal for Asian clinical market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Chemistry Acquisition | Captive formulation control secures subscription revenue against Formlabs' vertical integration. |
| LED Foundry Partnership | Taiwanese semiconductor supply agreements compress exposure times and maintenance intervals. |
| India PLI Assembly | Domestic manufacturing incentives unlock Middle Eastern and African clinical export channels. |
| FDA 510(k) Dual Submission | Parallel hardware-resin clearance accelerates hospital capital budget approval timelines. |
| Pixel-Shifting Retrofit Program | Optical engine upgrades extend equipment lifecycles and delay replacement purchase decisions. |
Research Methodology
Direct dialogue with dental laboratory technicians, biomedical engineers at hearing aid manufacturers, semiconductor procurement leads, and resin formulation chemists grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EU MDR conformity assessment databases, SAMR product registration records, and customs trade data for photopolymer resin imports. Bottom-up and top-down triangulation reconciled equipment shipment estimates with resin consumption patterns.
Top-down macroeconomic drivers informed the analytical lens, while bottom-up vendor interviews calibrated segment-level penetration rates across the projection horizon. Segmentation modeling spanned hardware tier, light source architecture, end-use vertical, and application workflow. CAGRs derived from equipment replacement cycle compression and consumables attach rate expansion. Industry-specific inputs included dental clinic same-day crown adoption curves and jewelry casting house labor substitution elasticities.
Underlying measurement precision varies by segment; industrial printer installed base estimates carry tighter precision than hobbyist channel volumes given distributor reporting gaps. Forecasts reflect documented assumptions around LED cost trajectories and regulatory clearance timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
3D Printing Service Bureaus Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
3D Printing Vacuum Furnaces Market