
 3D Printing in Aerospace and Defense Market | 2026-2036
3D Printing in Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing in Aerospace and Defense Market Analysis
Aftermarket service revenue is reshaping margin capture across the 3D printing aerospace and defense value chain as flight-hour contracts expand printed spare part mandates. EOS GmbH leverages its direct metal laser sintering portfolio to dominate European defense qualification programs. GE Additive anchors industrial-scale electron beam melting for jet engine turbine blades. Stratasys Ltd. specializes in polymer flight-certified cabin components for commercial aviation retrofit programs.
3D printing in aerospace and defense encompasses layer-by-layer fabrication of structural and functional components from metals, polymers, and composites, typically achieving tolerances of ±0.1 mm and densities exceeding 99.5% in laser-based metal systems, primarily serving weight reduction, lead-time compression, and supply chain resilience objectives. Selective laser sintering of titanium and nickel superalloys leads military engine programs where thermal performance dictates material selection. End-use parts now outpaces prototyping as the fastest-growing application segment as FAA and EASA qualification frameworks mature. Polymers retain the largest volume share in non-structural cabin and avionics housings where flame-retardant certification requirements shape material formulation.
FAA airworthiness directives and EASA certification memoranda establish the primary regulatory boundaries for flight-critical additive components, while ITAR and EAR export controls govern cross-border transfer of defense-relevant printing parameters and machine specifications. The EU AI Act introduces emerging compliance obligations for autonomous quality inspection systems integrated into production lines. Stakeholders must monitor evolving qualification reciprocity between FAA and EASA to anticipate which printed part categories will achieve bilateral acceptance first.
Market Dynamics
FAA and EASA qualification frameworks for flight-critical additive components are compressing certification timelines from years to months, restructuring competitive entry barriers for structural metal parts.
Growth Catalysts
- Pentagon sustainment directives:US defense procurement mandates now require qualified additive suppliers for legacy aircraft spare part contracts, creating captive demand pools for titanium and nickel superalloy components.
- Electron beam melting maturation:Industrial-scale EBM systems achieve 99.5%+ density in turbine blade production, enabling single-crystal-equivalent performance without traditional casting supply chains.
- REACH compliance acceleration:EU chemical registration deadlines are forcing OEMs to redesign legacy supply chains around domestically printed parts with full material traceability.
Market Restraints
- Titanium powder supply concentration:Spherical Ti-6Al-4V feedstock production clusters in three countries, exposing aerospace programs to export control volatility and price spikes.
- FAA part-specific airworthiness rigidity:Each printed component requires individual qualification even when material-process combinations are pre-approved, extending lead times for new designs.
- CNC machining cost parity:Traditional five-axis milling retains cost advantages below 500-unit production runs for aluminum airframe brackets, limiting additive penetration in medium-volume programs.
Strategic Opportunities
- India defense indigenization:PLI scheme incentives for domestic aerospace manufacturing create first-mover advantages for additive suppliers establishing local qualification labs.
- Autonomous quality inspection:EU AI Act compliance pathways for machine-learning defect detection systems open regulatory-cleared automation in European production lines.
- Flight-hour contract unbundling:Power-by-the-hour service models separate hardware ownership from operational availability, creating distributed printing networks for on-demand spare deployment.
Industry Challenges
- Non-destructive testing technician scarcity:X-ray computed tomography interpretation for internal porosity detection requires specialized certification that outpaces training pipeline output.
- Legacy MES integration friction:Additive work cells lack native connectivity to SAP and Oracle shop-floor systems, forcing expensive custom middleware development for traceability compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing in Aerospace and Defense Market |
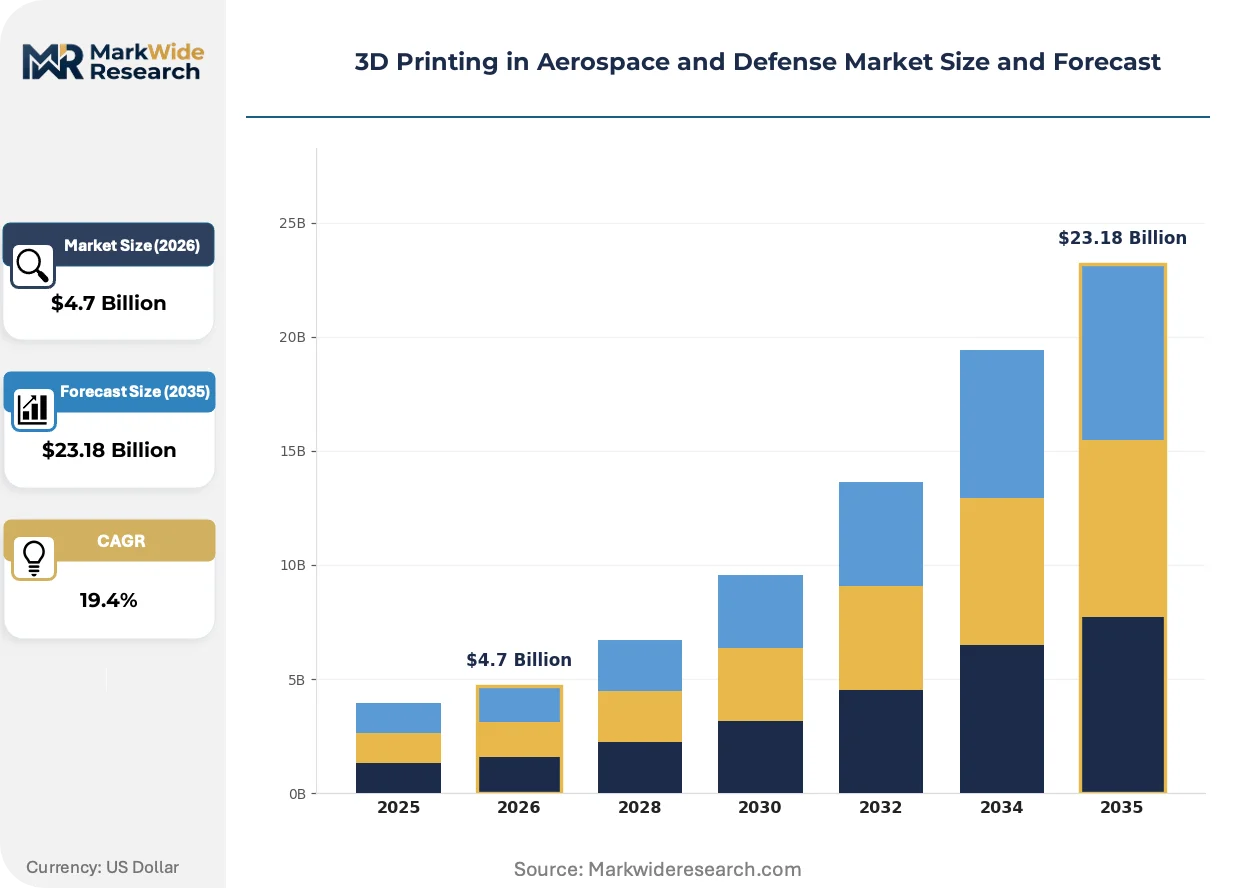
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing Material Type: Metals, Polymers, Composites, Ceramics Application: Prototyping, Tooling, End-Use Parts, Repair Components End User: Military, Commercial Aviation, Space Exploration, Defense Contractors |
| Companies Covered | Stratasys Ltd., 3D Systems Corporation, EOS GmbH, Norsk Titanium AS, Materialise NV, GE Additive, Aerojet Rocketdyne Holdings, Lockheed Martin, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing in Aerospace and Defense Market Emerging Trajectories
Digital thread architectures are collapsing the boundary between design, production, and certification, enabling real-time parameter adjustment based on in-situ sensor feedback during builds.
Multi-laser powder bed fusion is virtualizing traditional casting and forging workflows for large structural titanium brackets. Boeing and Airbus tier-one suppliers now deploy twelve-laser systems for wing rib production, compressing lead times from eighteen months to six weeks while eliminating tooling capital expenditure.
EASA certification memoranda on additive manufacturing are harmonizing qualification requirements across EU member states, reducing redundant testing for suppliers serving multiple national aerospace programs. German and French regulators now mutually recognize powder bed fusion process qualifications, streamlining cross-border supply chains for engine OEMs.
Aftermarket service unbundling is fragmenting traditional OEM spare part monopolies. Airlines now contract directly with qualified additive bureaus for cabin component replacement, bypassing manufacturer distribution networks. Lufthansa Technik and ST Engineering have established captive printing capabilities for non-structural polymer parts, capturing margin previously held by original equipment suppliers.
3D Printing in Aerospace and Defense Market Segmentation
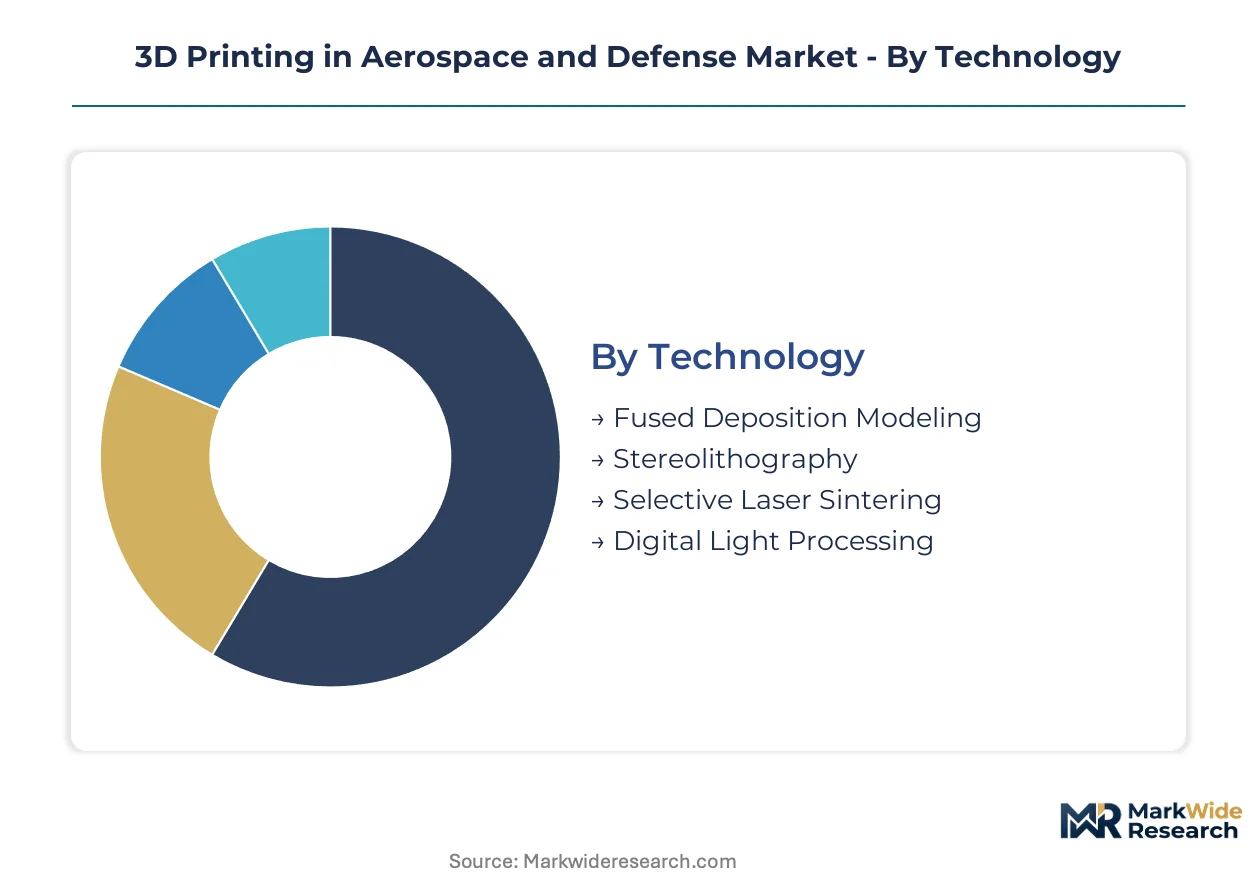
Segmentation in aerospace and defense additive manufacturing reveals how distinct qualification requirements, material performance thresholds, and contract structures create divergent profit pools across technology platforms and end-use categories.
Technology:
After-sales service intensity varies sharply across technology platforms, with metal systems demanding specialized technician certification and polymer platforms enabling remote technical support.
- Selective Laser Sintering:Powder bed fusion using CO2 or fiber lasers to sinter polymer or metal powders layer-by-layer, achieving ±0.1 mm tolerances in flight-critical applications. Demand concentrates in United States defense contractor facilities where Pentagon sustainment contracts mandate qualified SLS suppliers for titanium and nickel superalloy engine brackets. FAA qualification pathways for SLS-produced structural parts are compressing certification timelines from years to months.
- Fused Deposition Modeling:Thermoplastic extrusion through heated nozzles depositing ABS, ULTEM, or PEEK filaments in successive layers, typically for non-structural cabin components and avionics housings. Commercial aviation retrofit programs in Germany and France drive volume, where EASA flame-retardant certification requirements shape material formulation specifications. Lufthansa Technik deploys FDM for on-demand galley component replacement, bypassing traditional OEM distribution networks.
- Stereolithography:UV laser curing of liquid photopolymer resins, producing high-resolution prototypes and investment casting patterns for turbine blade foundries.
- Digital Light Processing:Projector-based photopolymer curing enabling faster build speeds than SLA for large-format aerospace tooling and sacrificial patterns.
By volume, Fused Deposition Modeling leads. By growth pace, Selective Laser Sintering is ahead.
Material Type:
Cost tier differentiation separates commodity feedstocks from qualified aerospace-grade materials with full lot traceability and export-controlled specifications.
- Metals:Titanium Ti-6Al-4V, Inconel 718, and aluminum AlSi10Mg powders processed through laser or electron beam systems, achieving densities exceeding 99.5% in flight-critical applications. United States defense industrial base procurement concentrates demand, where ITAR-controlled spherical powder specifications restrict supplier qualification to domestic sources. Spherical Ti-6Al-4V feedstock production clusters in three countries, exposing programs to export control volatility.
- Polymers:Flame-retardant ULTEM 9085, PEEK, and PA12 formulations serving non-structural cabin components, avionics housings, and ducting where FAR 25.853 fire-smoke-toxicity compliance is mandatory. Commercial aviation retrofit demand in France and Germany drives volume, with EASA certification memoranda harmonizing qualification requirements across EU member states.
- Composites:Continuous fiber-reinforced thermoplastics combining carbon fiber with nylon or PEEK matrices for structural brackets with directional strength properties.
- Ceramics:Oxide and non-oxide ceramic matrices for thermal protection systems, rocket nozzles, and high-temperature sensor housings in space exploration applications.
Polymers retain the largest volume share. Metals command the steepest expansion trajectory.
Application:
Customer type maturity separates legacy prototyping contracts from emerging flight-hour service models that unbundle hardware ownership from operational availability.
- End-Use Parts:Flight-certified structural and functional components replacing cast, forged, or machined equivalents in production aircraft and defense platforms. United States military sustainment directives now require qualified additive suppliers for legacy aircraft spare part contracts, creating captive demand pools. FAA and EASA qualification frameworks for flight-critical additive components are restructuring competitive entry barriers.
- Prototyping:Design validation and form-fit-function testing for new aircraft programs, traditionally the entry point for additive adoption but now yielding to production applications. Commercial aviation OEMs in Germany and France still deploy prototyping for iterative wing rib and bracket development before committing to hard tooling.
- Tooling:Drill guides, assembly fixtures, and composite layup molds produced through polymer or metal additive methods, compressing lead times from months to days.
- Repair Components:Cold spray deposition, directed energy repair, and hybrid additive-subtractive restoration of worn turbine blades and landing gear components.
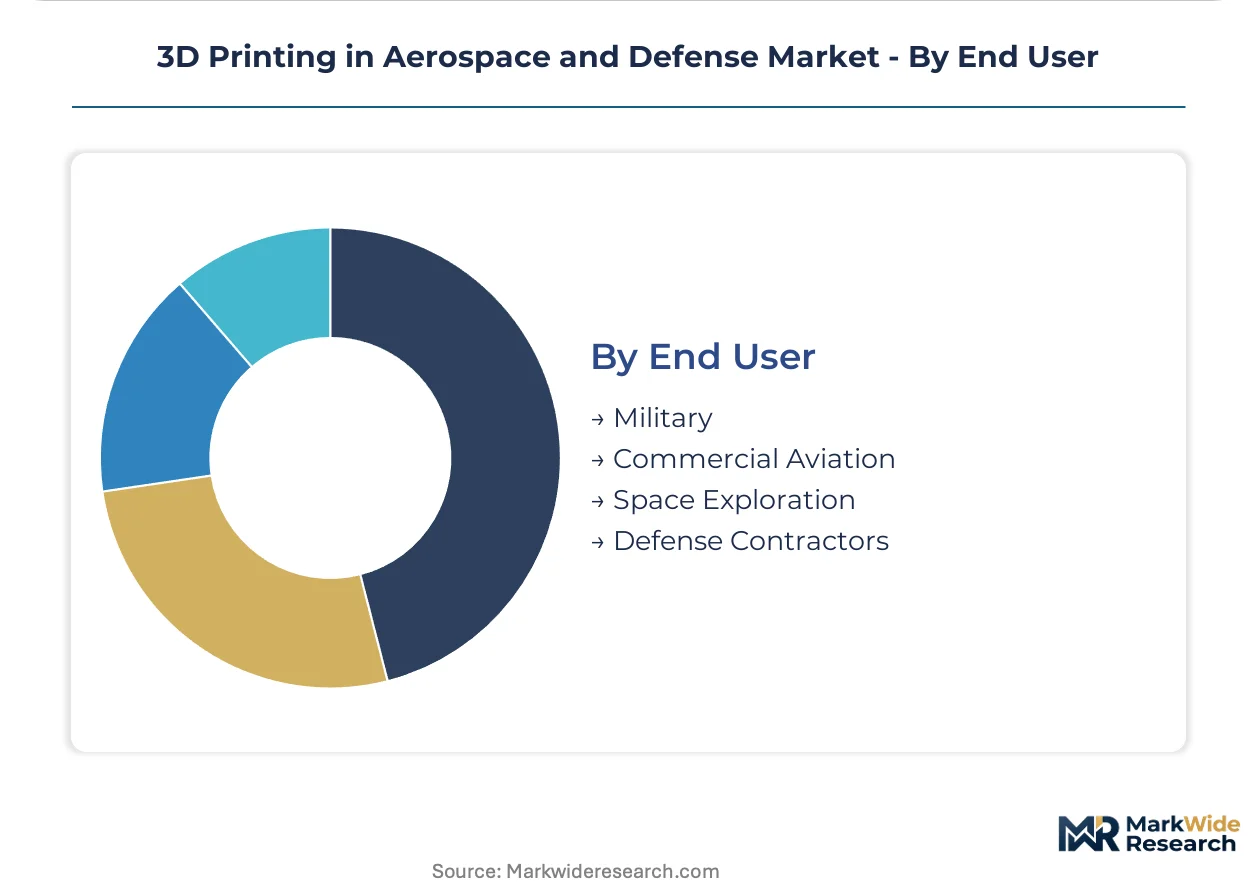
Prototyping holds historical volume leadership. End-Use Parts is climbing the fastest.
End User:
Supply concentration shapes procurement patterns, with defense contractors integrating captive additive cells while commercial aviation relies on qualified supplier networks.
- Defense Contractors:Tier-one suppliers to Pentagon programs operating ITAR-compliant facilities with qualified metal powder bed fusion systems for titanium and nickel superalloy components. United States procurement mandates prioritize qualified additive suppliers for sustainment contracts, creating structural demand concentration. Boeing and Lockheed Martin tier-one suppliers now deploy twelve-laser systems for wing rib production.
- Military:Direct armed forces ownership of additive capabilities for expeditionary sustainment, including containerized printing cells for forward-deployed spare part fabrication. United States Marine Corps and Army programs evaluate mobile additive manufacturing for reduced logistics tail in contested environments.
- Commercial Aviation:Airlines and MRO providers establishing captive polymer printing capabilities for cabin component replacement, bypassing OEM distribution networks. Lufthansa Technik and ST Engineering have established captive printing capabilities for non-structural polymer parts.
- Space Exploration:Satellite manufacturers and launch vehicle providers adopting additive for weight-optimized propulsion components and thermal management systems.
Defense Contractors dominate current procurement value. Space Exploration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spherical titanium powder production clusters in three countries, exposing aerospace supply chains to export control volatility and concentrating additive manufacturing investment in defense-industrial hubs with qualified feedstock access.
United States
Pentagon sustainment directives mandate qualified additive suppliers for legacy aircraft spare contracts, creating structural demand concentration in the defense industrial base. FAA certification pathways for printed airframe parts accelerate qualification timelines for structural metal components. Boeing and Lockheed Martin tier-one suppliers in the Pacific Northwest and Southwest now deploy twelve-laser systems for wing rib production.
Germany
EASA certification memoranda harmonize qualification requirements across EU member states, streamlining cross-border supply chains for engine OEMs. The EU AI Act introduces compliance obligations for autonomous quality inspection systems integrated into production lines. EOS GmbH anchors direct metal laser sintering capabilities in Munich and Krailling, dominating European defense qualification programs.
France
Commercial aviation retrofit programs drive polymer flight-certified cabin component demand, where EASA flame-retardant certification shapes material formulation. REACH compliance deadlines force OEMs to redesign legacy supply chains around domestically printed parts with full traceability. Safran and Airbus tier-one suppliers in Toulouse and Saint-Étienne concentrate electron beam melting for turbine blade production.
United Kingdom
BAE Systems and Rolls-Royce defense programs prioritize additive suppliers with ITAR-equivalent export control compliance for titanium and nickel superalloy components. The Civil Aviation Authority aligns with EASA additive manufacturing guidance, reducing redundant testing for suppliers serving European aerospace programs. Sheffield and Bristol host concentrated metal powder bed fusion qualification labs serving engine OEM supply chains.
India
PLI scheme incentives for domestic aerospace manufacturing create first-mover advantages for additive suppliers establishing local qualification infrastructure. The Directorate General of Foreign Trade monitors spherical powder import dependencies for defense-relevant printing feedstock. Bengaluru and Hyderabad concentrate emerging metal additive capabilities for indigenized fighter engine and structural programs.
3D Printing in Aerospace and Defense Market Vendor Landscape
Industrial-scale systems specialists and polymer flight-certification leaders split the market between defense-critical metal production and commercial aviation retrofit applications. The vendor base stratifies across three archetypes: captive aerospace primes operating internal additive cells, qualified independent bureaus serving MRO networks, and equipment OEMs capturing aftermarket powder and service revenue. Dominant competitive moves include backward integration into spherical powder production and strategic partnerships with national qualification bodies to accelerate regulatory clearance timelines.
Within the equipment OEM tier, EOS GmbH and Stratasys Ltd. exemplify divergent specialization paths—German metal systems versus Israeli polymer platforms—while GE Additive occupies a position spanning industrial-scale electron beam melting and captive aerospace supply. These three anchors represent the strategic choice facing market participants: pure-play equipment scale, integrated materials-to-parts verticality, or focused polymer certification dominance.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| 3D Systems Corporation |
| EOS GmbH |
| Norsk Titanium AS |
| Materialise NV |
| GE Additive |
| Aerojet Rocketdyne Holdings |
| Lockheed Martin |
| Northrop Grumman |
| Others |
Supply Flow & Price Mechanics
Spherical Ti-6Al-4V powder production concentrates in the United States, Germany, and China, anchoring margin capture in qualified aerospace feedstock tiers and ITAR-controlled domestic sourcing mandates for defense contractors.
Pricing Analysis
FAA part-specific airworthiness directives dictate the pricing tier structure across flight-critical additive components, separating FAA-qualified structural metal parts from non-certified prototyping bureaus. Three-tier pricing structure across premium flight-certified, standard industrial-grade, and economy prototyping levels reflects certification investment recovery and powder traceability costs. Cost compression in polymer cabin components is intensifying because commercial aviation MROs are bypassing OEM distribution networks for qualified bureau sourcing. Defense contractors exhibit the lowest price sensitivity due to Pentagon sustainment contract mandates, while commercial retrofit programs drive the hardest volume negotiations.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for ITAR-controlled spherical powder specifications. Spherical titanium feedstock draws from domestic atomization facilities in the United States, plasma rotating electrode production in Germany, and electrode induction melting capacity in China. Nickel superalloy powder and flame-retardant ULTEM polymer filament represent secondary dependencies with concentrated qualified suppliers. Single-source vulnerability in electron beam melting system hardware constrains capacity expansion timelines. Distribution runs through qualified additive bureaus serving defense prime contractors, with captive printing cells capturing an expanding share of commercial aviation retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D printing in aerospace and defense market is accelerating through a regulatory inflection as FAA and EASA qualification frameworks compress certification timelines from years to months for flight-critical metal components.
For Market Incumbents: Build regulatory moats through accelerated FAA qualification pathway investments for titanium and nickel superalloy process combinations. Deepen backward integration into spherical powder atomization to secure ITAR-compliant feedstock supply against export control volatility. Expand twelve-laser system capacity in the Pacific Northwest and Southwest to capture Boeing and Lockheed Martin wing rib production contracts.
For New Entrants and Emerging Players: Build out captive polymer printing capabilities for commercial aviation cabin component replacement, targeting Lufthansa Technik and ST Engineering service unbundling models. Establish local qualification labs in Bengaluru and Hyderabad to capture PLI scheme incentives for India's defense indigenization programs. Pursue EASA flame-retardant certification for ULTEM 9085 formulations as the fastest regulatory entry point.
For Investors and Strategic Acquirers: Capital is best deployed toward qualified independent bureaus with existing FAA structural part approvals and established defense contractor relationships. The five-to-ten year viability window favors additive suppliers with integrated powder-to-parts traceability and multi-laser production scale. Monitor Pentagon procurement directive expansion beyond legacy aircraft sustainment into next-generation platform development as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FAA Qualification Pathway Investment | Compresses certification timelines for titanium structural brackets at Boeing tier-one suppliers. |
| Backward Integration into Spherical Powder | Secures ITAR-compliant Ti-6Al-4V feedstock against export control volatility in defense programs. |
| Multi-Laser System Deployment | Twelve-laser powder bed fusion reduces wing rib lead times from eighteen months to six weeks. |
| EASA Certification Memoranda Alignment | Harmonizes qualification requirements across German and French engine OEM supply chains. |
| Flight-Hour Contract Unbundling | Power-by-the-hour models separate hardware ownership from operational availability for on-demand spare deployment. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with additive manufacturing program directors, defense procurement officers, FAA certification engineers, and commercial aviation MRO executives; and secondary validation through FAA airworthiness directives, EASA certification memoranda, Pentagon sustainment contract disclosures, and SEC filings from listed additive equipment OEMs. Bottom-up and top-down triangulation cross-checked installed base estimates against powder consumption volumes and qualified supplier facility counts.
Forecast inputs considered technology platform adoption curves, material qualification pipeline depth, and defense procurement directive expansion trajectories across the analysis window. Segmentation dimensions modeled include technology platform, material type, application category, and end-user archetype. CAGRs were derived from fitted adoption curves calibrated to historical qualification timeline compression and Pentagon contract award patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese spherical powder producers or expedited FAA certification reforms would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
Digital 3D Printing Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
Additive Manufacturing Software Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
4D Printing Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Metal 3D Printing Service Market
3D Printing Technology
US Additive Manufacturing Market