
 Latin America Data Center Cooling Market | 2026-2036
Latin America Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Data Center Cooling Market Foresight
The performance gap between precision liquid cooling and conventional air handling is expanding across Latin American facilities. Vertiv leverages its regional service footprint to anchor large-scale deployments in Brazil and Mexico. Schneider Electric differentiates through integrated microgrid-to-cooling architectures that sustain uptime in grid-unstable zones. Stulz competes on specialized humidity control systems calibrated for tropical latitudes.
Latin America data center cooling encompasses thermal management infrastructure engineered to maintain server inlet temperatures between 18°C and 27°C per ASHRAE guidelines, utilizing refrigerant loops, chilled water distribution, or dielectric fluid immersion to reject heat generated by IT loads exceeding 15 kW per rack. Liquid cooling and hybrid systems now capture the strongest momentum as AI training clusters proliferate, while air cooling retains volume dominance in legacy enterprise facilities. Among end users, cloud providers and telecommunications operators represent the most active procurement segments, with BFSI institutions trailing due to longer capital refresh cycles.
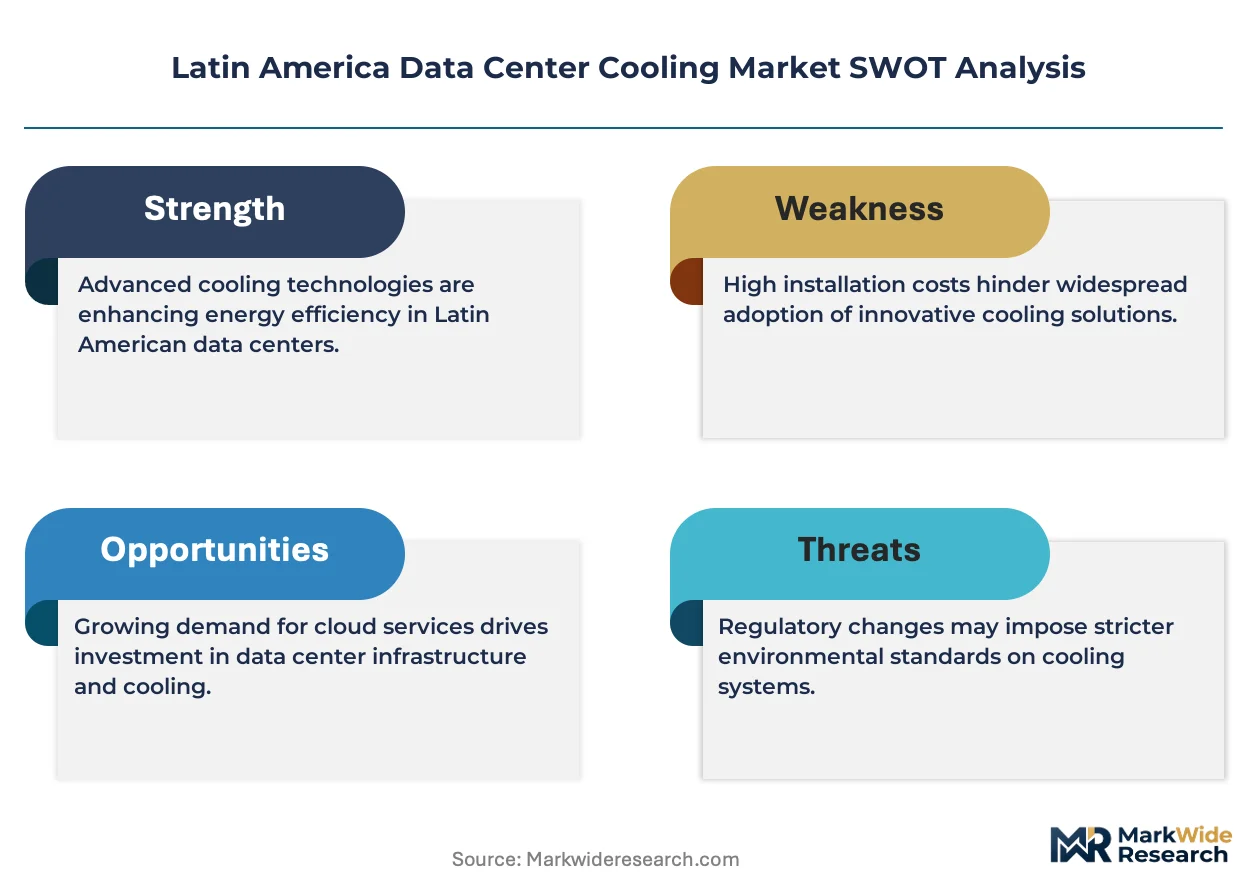
Brazil's INMETRO certification and Mexico's CONUEE energy efficiency standards shape equipment eligibility and import compliance across the region. Chile's environmental ministry enforces progressively stricter limits on refrigerant Global Warming Potential, directing specification choices toward low-GWP alternatives. Stakeholders must weigh sovereign data residency laws against cooling technology refresh timelines when committing to multi-year infrastructure contracts.
Market Dynamics
The collision between AI-driven power density requirements and legacy air-cooled infrastructure is forcing wholesale architectural recalculation across Latin American facilities. Cloud operators now specify liquid-ready designs for new builds while retrofitting existing halls.
Growth Catalysts
- INMETRO certification mandates:Brazil's efficiency labeling program disqualifies legacy cooling equipment from government-procured data center projects, redirecting capital toward certified precision air handlers and chilled water systems.
- Hyperscale cloud expansion:São Paulo's corridor attracts AWS, Microsoft, and Google facility investments exceeding 100 MW each, with direct liquid cooling specified for AI training clusters surpassing 50 kW per rack.
- Immersion cooling maturation:Single-phase dielectric fluid systems from 3M and Novec formulations achieve price parity with chilled water architectures at densities above 30 kW, unlocking adoption in Chilean cryptocurrency mining facilities.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger and piping costs swing 15-25% quarterly, compressing margins for equipment vendors locked into fixed-price EPC contracts.
- Refrigerant supply concentration:Low-GWP HFO blends rely on Chemours and Honeywell production facilities in the United States, exposing Latin American integrators to import tariff uncertainty and extended lead times.
- Grid instability in secondary markets:Northern Mexico and Colombia experience voltage fluctuation rates incompatible with precision cooling compressor startup sequences, requiring redundant UPS investment that inflates total cost of ownership.
Strategic Opportunities
- Colombia's underpenetrated Bogotá-Andean corridor:Submarine cable landings at Barranquilla and Medellín's emerging fiber backbone position the capital for captive cooling demand from content delivery networks seeking Andean latency arbitrage.
- CONUEE efficiency rebates:Mexico's national energy commission subsidizes free cooling economizer retrofits in high-altitude facilities, creating immediate specification pull for adiabatic and evaporative hybrid systems.
- Edge computing convergence with telecom infrastructure:Tower operators like American Tower and Phoenix Tower International deploy micro data centers at 5G base stations, requiring compact liquid-cooled enclosures previously developed for defense applications.
Industry Challenges
- Thermal hydraulic engineering talent scarcity:Single-phase and two-phase liquid cooling design expertise concentrates in São Paulo and Monterrey, leaving secondary markets dependent on flown-in commissioning teams.
- ASHRAE 90.4 compliance timeline compression:Certification bodies in Brazil and Mexico lack accredited testing capacity for integrated mechanical systems, extending project schedules by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Data Center Cooling Market |
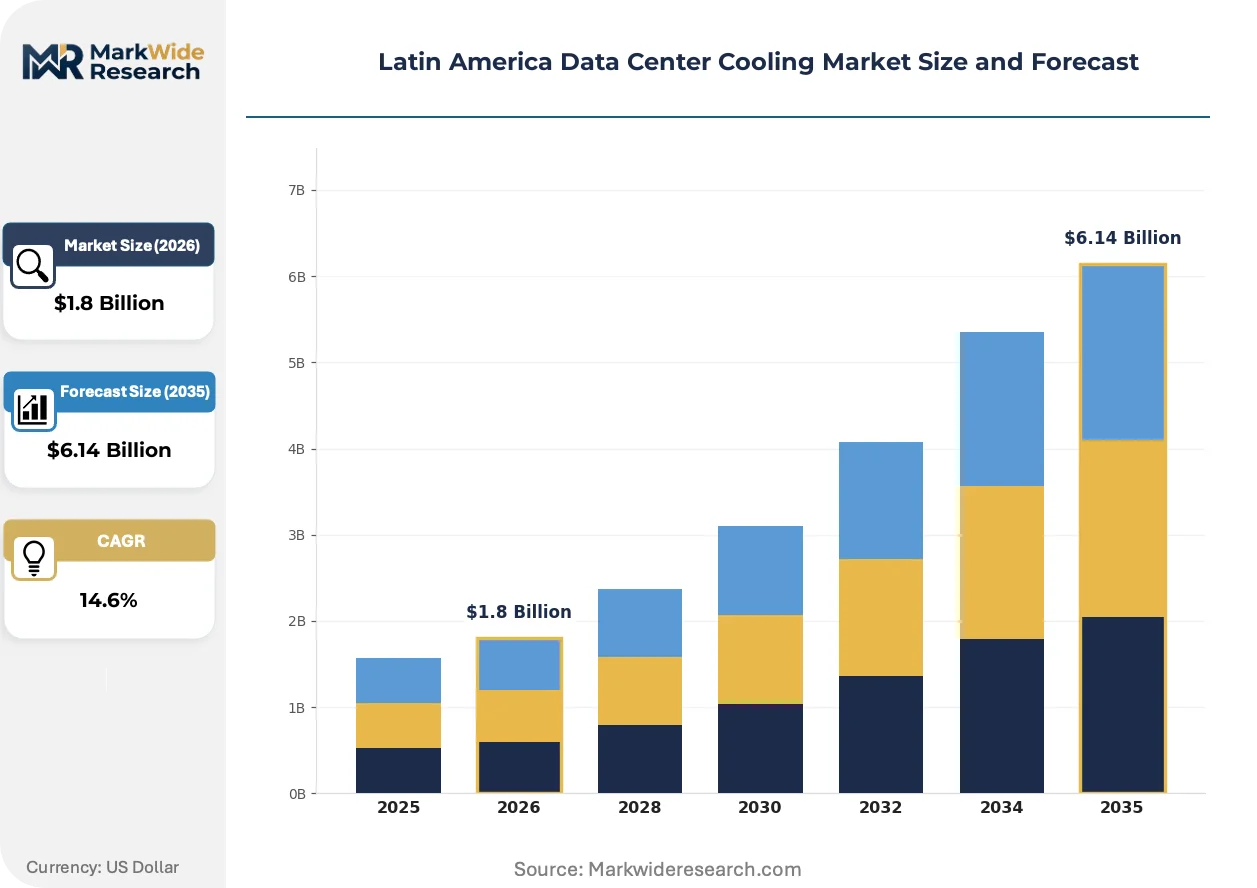
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Cooling, Liquid Cooling, Refrigeration, Hybrid Systems End User: Telecommunications, BFSI, Cloud Providers, Research Institutions Service Type: Maintenance, Installation, Consultation, Remote Monitoring Technology: Dynamic Cooling, Passive Cooling, Immersion Cooling, Evaporative Cooling |
| Companies Covered | Stulz, Vertiv, Schneider Electric, Rittal, Mitsubishi Electric, Johnson Controls, Daikin, Emerson Electric, Alfa Laval, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Data Center Cooling Market Shifts & Advancements
Latin American data center cooling is pivoting from capacity-led specification to efficiency-led architectural selection. Operators now prioritize heat rejection technologies that synchronize with renewable generation profiles and carbon accounting requirements.
Direct-to-chip liquid cooling is electrifying competitive positioning among hyperscale builders. Cold plates from CoolIT and Asetek attach to CPU and GPU packages, capturing 80% of server heat at the source. Cloud providers in São Paulo and Querétaro deploy these systems at 100 kW rack densities. The technology is electrifying procurement patterns by collapsing the distinction between facility infrastructure and IT hardware specification.
Chile's Ministry of Environment enforces progressively stricter limits on refrigerant Global Warming Potential through its national ozone protection program. Equipment imports above 750 GWP face phased restrictions through 2030. This policy is redirecting specification choices toward R-513A and R-1234ze alternatives in Santiago and Valparaíso facilities, with distributors building regional buffer stocks to hedge supply uncertainty.
Power purchase agreement structures now dictate cooling technology selection rather than vice versa. Operators with contracted solar generation in Mexico's Bajío region specify thermal storage and chilled water systems that arbitrage daytime cooling load against nighttime IT demand. This pattern is most visible among financial services colocation providers in León and Aguascalientes seeking Scope 2 emissions reductions for ESG reporting.
Latin America Data Center Cooling Market Segmentation
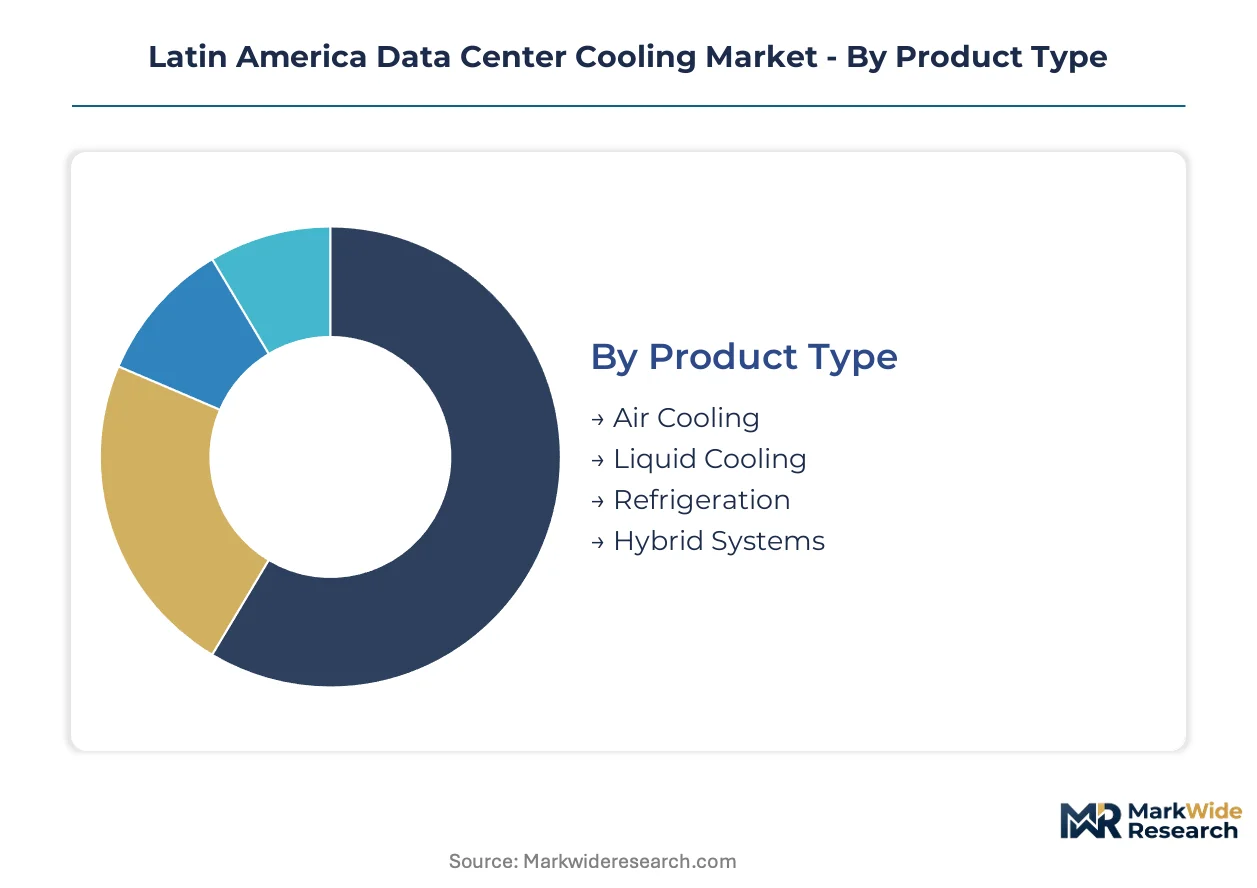
Cooling architecture selection in Latin America hinges on power density thresholds, ambient climate conditions, and regulatory compliance timelines. Segmentation reveals where legacy infrastructure persists versus where liquid and hybrid systems displace conventional approaches.
Product Type:
Standalone cooling plants dominate hyperscale deployments, while embedded thermal modules integrate into prefabricated edge enclosures.
- Liquid Cooling:Direct-to-chip and immersion configurations handle rack densities exceeding 50 kW. São Paulo's AI training clusters specify these systems to manage GPU thermal loads that air handlers cannot address.
- Hybrid Systems:Chilled water economizers paired with adiabatic pads optimize for Mexico's high-altitude facilities where free cooling hours extend operational efficiency. CONUEE rebate eligibility accelerates procurement in Querétaro and León.
- Air Cooling:Precision air handlers retain volume in legacy enterprise facilities across Brazil's secondary cities where rack densities remain below 15 kW.
- Refrigeration:Compressor-based DX systems serve small colocation sites in grid-unstable northern Mexico where chilled water distribution proves unreliable.
Volume placements concentrate in Air Cooling; the faster expansion belongs to Liquid Cooling.
End User:
Capital deployment cycles and thermal density requirements create divergent procurement patterns across customer categories.
- Cloud Providers:Hyperscale operators specify liquid-ready designs for new builds exceeding 100 MW. AWS, Microsoft, and Google facilities in São Paulo's corridor drive specification authority toward direct-to-chip architectures.
- Telecommunications:Tower operators deploy compact liquid-cooled enclosures at 5G base stations. American Tower and Phoenix Tower International require defense-derived thermal solutions for edge micro data centers.
- BFSI:Financial institutions in Mexico City and Santiago maintain longer refresh cycles, delaying liquid cooling adoption despite rising rack densities in trading floor environments.
- Research Institutions:Universities and national labs in Chile and Brazil procure immersion systems for high-performance computing clusters with intermittent utilization patterns.
Cloud Providers command the steepest expansion trajectory; BFSI institutions lag in upgrade velocity.
Service Type:
Recurring revenue attachment rates vary by cooling complexity and local technical labor availability.
- Maintenance:Preventive service contracts for liquid cooling systems require specialized thermal hydraulic expertise concentrated in São Paulo and Monterrey.
- Installation:Chilled water system commissioning demands flown-in engineering teams for secondary markets, extending project timelines.
- Remote Monitoring:AI-driven predictive analytics platforms optimize cooling energy consumption for hyperscale operators seeking Scope 2 emissions reductions.
- Consultation:Engineering advisory services guide CONUEE and INMETRO compliance for facilities navigating efficiency certification requirements.
Maintenance contracts generate the highest recurring attachment; Remote Monitoring is gaining share fastest among cloud operators.
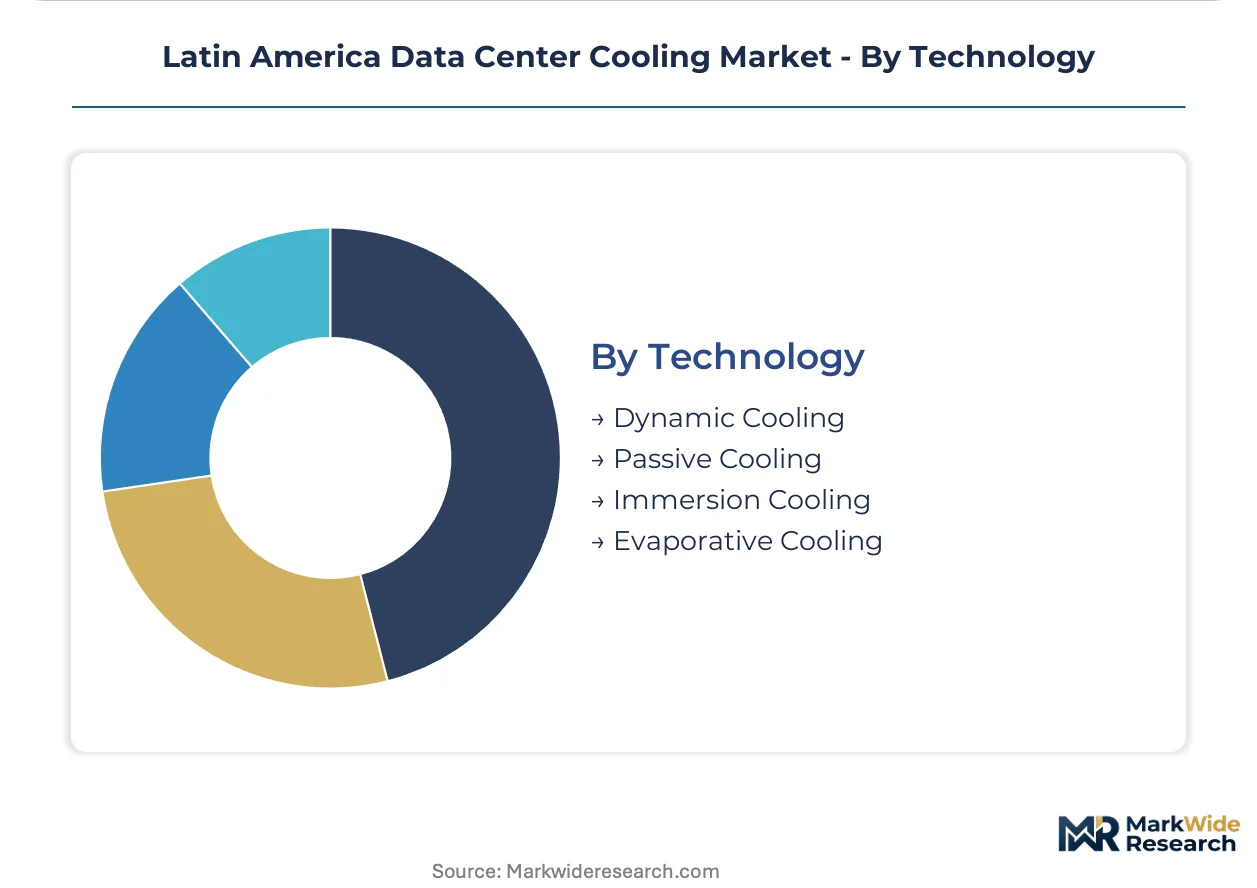
Technology:
Thermal management approaches align with ambient climate zones and IT load predictability.
- Immersion Cooling:Single-phase dielectric fluid systems from 3M achieve price parity with chilled water above 30 kW density. Chilean cryptocurrency mining facilities deploy these configurations for thermal stability.
- Dynamic Cooling:Variable-speed compressor and fan arrays match cooling output to real-time IT load in São Paulo hyperscale halls with fluctuating AI training schedules.
- Evaporative Cooling:Adiabatic pads supplement mechanical cooling in Mexico's Bajío region where low humidity extends free cooling hours.
- Passive Cooling:Heat sink and natural convection designs serve low-density edge nodes in Colombia's Andean corridor where ambient temperatures moderate thermal loads.
Dynamic Cooling holds the largest installed base; Immersion Cooling exhibits the steepest adoption curve among density-constrained operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's hyperscale corridor concentrates the region's most intensive cooling demand, with cloud providers specifying liquid-ready architectures for facilities exceeding 100 MW. This metropolitan anchor shapes procurement patterns across the Southern Cone and drives specification authority toward direct-to-chip systems.
Brazil
INMETRO certification mandates disqualify legacy cooling equipment from government-procured data center projects, redirecting capital toward certified precision air handlers. São Paulo anchors hyperscale expansion where AWS, Microsoft, and Google facilities now specify direct liquid cooling for AI training clusters surpassing 50 kW per rack.
Mexico
CONUEE efficiency rebates subsidize free cooling economizer retrofits in high-altitude facilities, creating immediate specification pull for adiabatic and evaporative hybrid systems. The Bajío region around Querétaro and León attracts financial services colocation providers seeking Scope 2 emissions reductions through thermal storage arbitrage.
Chile
The Ministry of Environment enforces progressively stricter limits on refrigerant Global Warming Potential through its national ozone protection program. Santiago and Valparaíso facilities redirect specification choices toward R-513A and R-1234ze alternatives, with distributors building regional buffer stocks to hedge supply uncertainty.
Colombia
Submarine cable landings at Barranquilla and Medellín's emerging fiber backbone position Bogotá for captive cooling demand from content delivery networks. The Andean corridor's moderate ambient temperatures enable passive cooling designs for low-density edge nodes seeking latency arbitrage.
Argentina
Grid instability in secondary markets complicates precision cooling compressor startup sequences, requiring redundant UPS investment that inflates total cost of ownership. Buenos Aires concentrates limited procurement activity among enterprise facilities maintaining legacy air-cooled architectures below 15 kW per rack.
Latin America Data Center Cooling Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Latin America's data center cooling market, with integrated infrastructure vendors holding advantage in large-scale deployments. The structure tilts toward consolidated specification authority at the hyperscale tier, while fragmented local integrators serve secondary markets. Three archetypes dominate: full-stack thermal infrastructure providers, specialized humidity control specialists, and regional service-heavy integrators. Competitive moves center on geographic service footprint expansion and certification compliance partnerships with national energy regulators.
Among European-headquartered conglomerates, Schneider Electric and Stulz occupy positions reflecting divergent specialization vectors. Vertiv represents the service-anchored integrator archetype with pronounced regional deployment capabilities. These three entities exemplify how competitive positioning in Latin American data center cooling correlates with the ability to navigate INMETRO and CONUEE compliance timelines while maintaining commissioning capacity across São Paulo, Querétaro, and Santiago corridors.
| Leading Market Players |
|---|
| Stulz |
| Vertiv |
| Schneider Electric |
| Rittal |
| Mitsubishi Electric |
| Johnson Controls |
| Daikin |
| Emerson Electric |
| Alfa Laval |
| Others |
Supply & Pricing Matrix
Hyperscale cloud providers in São Paulo's corridor concentrate procurement authority for liquid-ready cooling systems, anchoring a value-based pricing model where uptime guarantees and energy efficiency outcomes determine contract value rather than equipment cost alone. This buyer concentration shifts pricing power toward vendors with proven CONUEE and INMETRO certification pathways, compressing margins for uncertified competitors.
Pricing Analysis
Value-based pricing anchored to thermal outcome guarantees dominates hyperscale contracts, with cloud providers paying premiums for direct-to-chip systems delivering sustained rack densities above 50 kW. Price differentiation rests on INMETRO certification tier and regional service response capability, with certified precision air handlers commanding 15-20% uplifts over uncertified equivalents. Pricing pressure stems from copper and aluminum input volatility swinging heat exchanger costs quarterly, forcing EPC vendors into margin-absorbing fixed-price commitments. Colocation providers in Mexico's Bajío region exhibit highest price sensitivity due to CONUEE rebate dependency, while AI training cluster operators prioritize thermal performance over capital cost.
Supply Chain Analysis
Freight costs from United States-based refrigerant production facilities to Latin American integration hubs consume 8-12% of landed equipment value, with low-GWP HFO blends from Chemours and Honeywell facing extended lead times through Gulf of Mexico ports. Manufacturing concentration in China, Germany, and the United States for precision compressors and cold plate assemblies creates single-source vulnerability for direct-to-chip components. Raw material dependencies on Chilean copper, Brazilian aluminum, and imported dielectric fluids from 3M tether production schedules to commodity exchange volatility. Distribution runs through São Paulo and Monterrey-based system integrators serving hyperscale corridors, with secondary markets dependent on flown-in commissioning teams from these hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's data center cooling market functions as a cost-of-compliance arena where Brazil's INMETRO certification mandates erect barrier-to-entry moats favoring vendors with established regulatory navigation capabilities and regional service footprints.
For Market Incumbents: Deepen vertical integration into refrigerant buffer stock management and regional commissioning team capacity to defend against supply disruption threats from United States import tariff uncertainty. Anchor market position by expanding certified service nodes in Querétaro and Santiago corridors, leveraging existing INMETRO compliance pathways to capture CONUEE rebate-driven retrofits before uncertified competitors achieve accreditation. For New Entrants and Emerging Players: Enter via Colombia's Bogotá-Andean corridor where submarine cable landings and moderate ambient temperatures create underserved demand for passive and hybrid cooling designs absent entrenched incumbent presence. Target content delivery network edge deployments seeking latency arbitrage, positioning compact liquid-cooled enclosures derived from defense application heritage as the go-to-market wedge against air-cooled legacy specifications. For Investors and Strategic Acquirers: The window for entry favors regional service-heavy integrators with established thermal hydraulic engineering talent pools in São Paulo and Monterrey, as capability scarcity in single-phase liquid cooling design constrains market expansion. Watch refrigerant Global Warming Potential regulatory tightening in Chile and Mexico as the inflection signal accelerating specification shifts toward low-GWP alternatives and rewarding distributors with pre-positioned inventory.| Strategic Initiative | Industry Significance |
|---|---|
| CONUEE Certification Investment | Unlocks rebate eligibility for adiabatic economizer retrofits in Mexico's high-altitude Bajío facilities. |
| Refrigerant Buffer Stock Build | Hedges supply uncertainty from Chemours and Honeywell production concentration in the United States. |
| Thermal Hydraulic Talent Acquisition | Addresses commissioning bottleneck constraining liquid cooling deployment in secondary markets. |
| Direct-to-Chip Partnership | Collapses facility infrastructure and IT hardware specification for AWS and Microsoft São Paulo clusters. |
| Edge Micro Data Center Deployment | Captures 5G base station convergence demand from American Tower and Phoenix Tower International. |
Research Methodology
Multi-period observation of hyperscale facility capex commitments, INMETRO certification timelines, and CONUEE rebate disbursement patterns anchored the trend analysis, supplemented by interviews with data center engineering directors, thermal infrastructure procurement leads, EPC contractors, national energy regulator officials, and refrigerant distribution specialists. Secondary validation drew from SEC filings of publicly traded cloud providers, Brazilian customs import records for cooling equipment, Chilean Ministry of Environment refrigerant restriction announcements, and ASHRAE technical standards documentation. Bottom-up facility-level capacity tracking and top-down national energy efficiency program analysis enabled triangulation across independent data streams.
Input-output matrices modeled cooling architecture adoption across product type, end user vertical, service attachment rate, and technology category dimensions over the projection horizon. CAGRs derived from facility pipeline tracking, cloud provider announced investments, and regulatory compliance deadline impacts. Forecast inputs incorporated AI training cluster power density trajectories, grid instability indices for secondary markets, and refrigerant supply lead time volatility assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt refrigerant import restriction scenarios or accelerated INMETRO efficiency tier escalations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Switzerland Data Center Cooling Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
Sweden Data Center Cooling Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
AI Datacenter Liquid Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
Australia Data Center Cooling Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market