
 Conventional and Rapid Prototyping Market | 2026-2036
Conventional and Rapid Prototyping Market Size, Share, and Industry Trends Forecast 2026-2036
Conventional and Rapid Prototyping Market Analysis
Modular service bundling is broadening buyer choice as platform providers combine design verification, functional testing, and low-volume production into unified procurement workflows. Xometry leverages its distributed manufacturing network to sustain rapid turnaround capabilities across North American and European markets. Stratasys anchors polymer-based prototyping through deep expertise in FDM and SLA hardware systems. Proto Labs competes on speed by operating automated quoting engines that compress order-to-delivery cycles for injection-molded and CNC-machined parts.
Conventional and rapid prototyping encompasses subtractive methods such as CNC milling and turning alongside additive techniques including stereolithography (SLA) with layer resolutions down to 25 microns, serving industrial needs from concept validation through pre-production bridge manufacturing. FDM technology dominates unit volume in educational and consumer electronics sectors due to low equipment cost and material accessibility. Metal SLS applications represent the fastest-expanding margin pool as aerospace and healthcare end users pursue flight-worthy and biocompatible components without tooling investment. Plastic resin formulations across SLA and DLP platforms occupy mature, price-competitive territory where material suppliers differentiate through specialized optical and thermal properties.
ISO 9001 quality management and ASTM F42 additive manufacturing standards shape product certification requirements for medical and aerospace buyers, while FDA 510(k) pathways govern clinical adoption of patient-specific prototypes. China's GB standards and MIIT regulations on dual carbon compliance are redirecting material selection toward recycled and bio-based feedstocks. Stakeholders must monitor evolving ECHA REACH restrictions on photopolymer resin chemistry, as regulatory tightening in Europe and Asia-Pacific threatens existing supply formulations and forces reformulation investment.
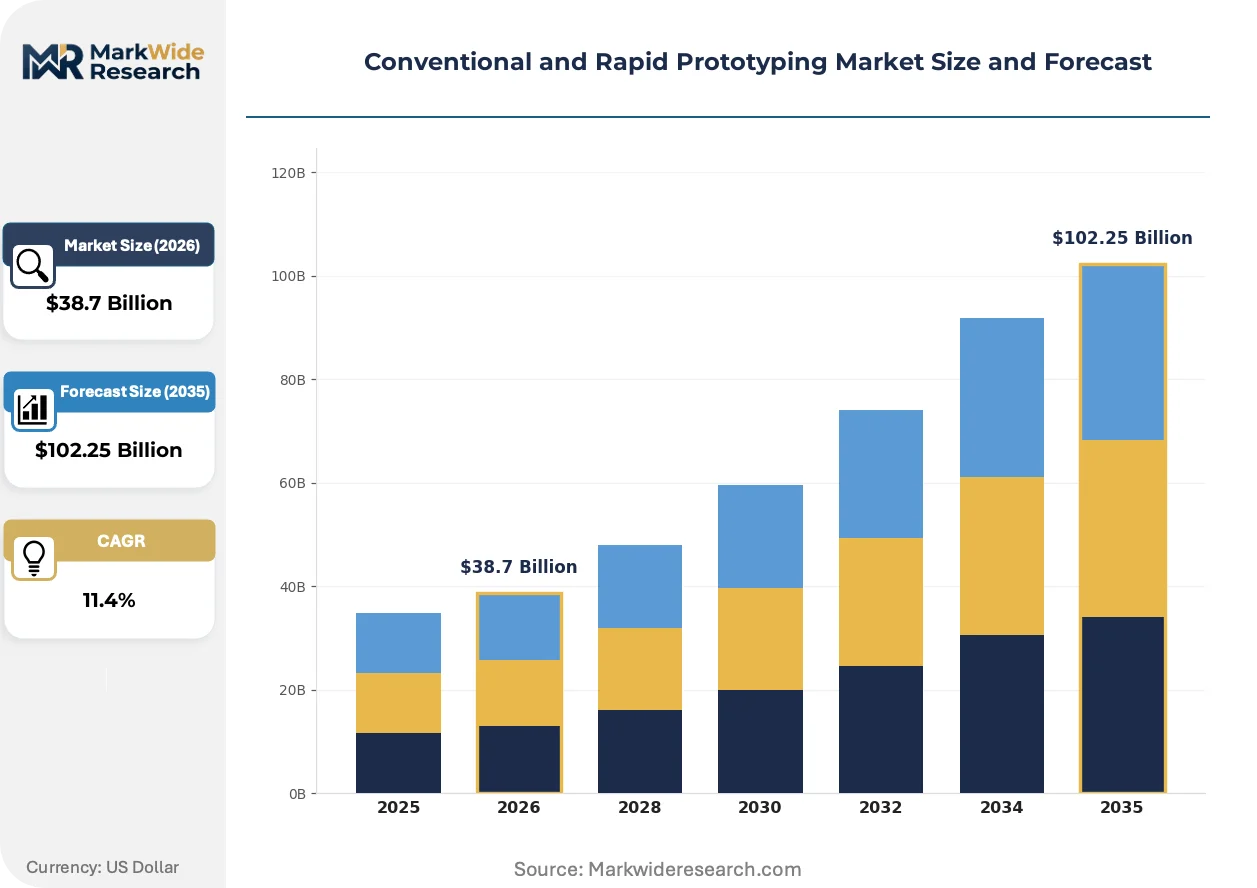
Market Dynamics
Metal selective laser sintering is compressing tooling lead times from months to days across aerospace and medical device supply chains, forcing conventional manufacturers to reposition around bridge production and functional validation rather than purely geometric mock-ups.
Growth Catalysts
- China's MIIT dual carbon mandate:Accelerating substitution of aluminum and carbon fiber composites for steel in automotive prototypes, creating demand for SLS and binder jetting workflows that minimize material waste.
- ISO 9001 and ASTM F42 harmonization:Medical device OEMs in Germany and Switzerland now accept additive manufacturing for patient-specific surgical guides, expanding addressable applications beyond concept models.
- Functional testing applications:Automotive manufacturers in Stuttgart and Munich clusters require crash-worthy prototypes, pulling high-temperature polymer and metal powder demand from validation labs.
Market Restraints
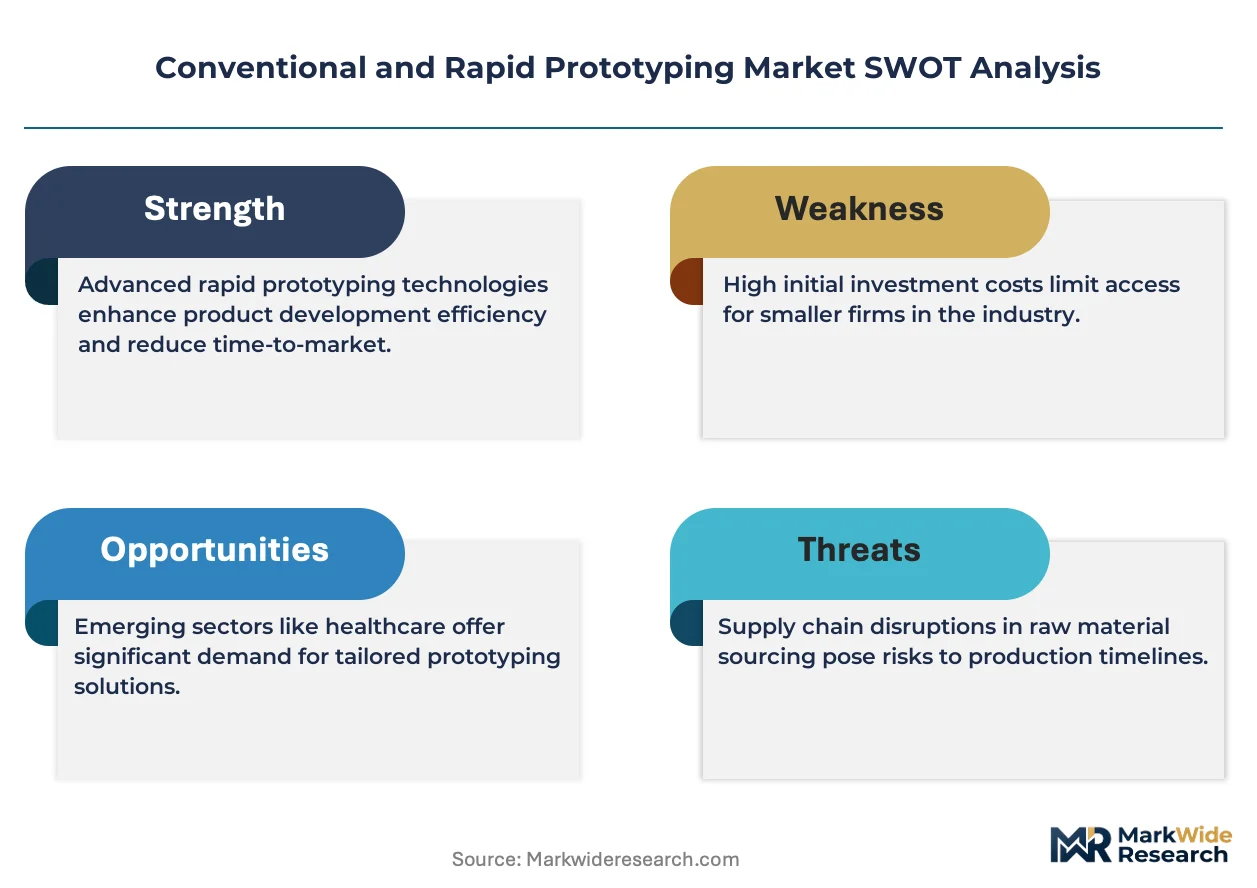
- Titanium and nickel powder supply concentration:Over 70% of aerospace-grade metal feedstock originates from Chinese and Russian refiners, exposing Western prototype shops to export restriction risk and price volatility.
- ECHA REACH photopolymer restrictions:Tightening limits on acrylate and epoxy resin chemistry force European SLA operators into costly reformulation cycles without guaranteed performance parity.
- Surface finish limitations of FDM:Layer lines and anisotropic strength prevent adoption for optical and fluid dynamics testing, ceding share to CNC machining in precision segments.
Strategic Opportunities
- Brazil's ANVISA fast-track pathway:Emerging regulatory clarity for 3D-printed dental and orthopedic devices creates first-mover advantage for prototype-to-production integrators serving Latin American markets.
- Multi-material jetting convergence:Combining rigid and elastomeric photopolymers in single builds enables soft robotics and wearable medical device prototyping previously requiring assembly of discrete components.
- Distributed manufacturing platforms:On-demand quoting engines compress procurement cycles from weeks to hours, capturing share from traditional job shops in North American and European industrial corridors.
Industry Challenges
- DFAM skill scarcity:Design for additive manufacturing expertise remains concentrated among senior engineers at tier-one aerospace suppliers, limiting adoption at mid-tier automotive and consumer electronics firms.
- FDA 510(k) validation timelines:Patient-specific implant prototypes require 18-24 month certification cycles, compressing margins and deterring smaller service bureaus from clinical market entry.
- Legacy ERP integration friction:Prototype shops struggle to connect automated quoting systems with customer MRP platforms, delaying order confirmation and payment reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conventional and Rapid Prototyping Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: SLA, FDM, SLS, DLP End User: Aerospace, Automotive, Healthcare, Consumer Electronics Application: Design Verification, Functional Testing, Visual Prototyping, Low-Volume Production Material: Plastic, Metal, Resin, Composite |
| Companies Covered | Stratasys, Fathom, Proto Labs, Envative, Fictiv, Xometry, WAYKEN, Maruti Techlabs, 3ERP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conventional and Rapid Prototyping Market Emerging Trajectories
Continuous fiber reinforcement is blurring the boundary between prototype and structural part, compelling equipment manufacturers to bundle simulation software with hardware subscriptions to capture recurring revenue.
Continuous fiber 3D printing embeds carbon, glass, or aramid strands within thermoplastic matrices during deposition, producing anisotropic strength comparable to aluminum in specific orientations. Aerospace tier-one suppliers in Toulouse and Hamburg are qualifying these parts for non-critical cabin brackets and ducting, bypassing forging lead times entirely. This capability is electrifying competition between polymer and light metal solutions in the 10-100 unit production band.
Europe's ECHA REACH restrictions on monomer volatility are forcing resin suppliers to eliminate traditional photoinitiators from SLA formulations, redirecting R&D investment toward cationic and thiol-ene chemistries with lower occupational exposure risk. Medical device manufacturers in Ireland and the Netherlands face reformulation validation costs exceeding €500,000 per product line, consolidating supply relationships toward integrated material-hardware vendors capable of absorbing compliance burden.
Automotive OEM procurement teams now bundle design verification, functional testing, and low-volume bridge manufacturing into single-source contracts with penalty clauses for missed validation milestones. Tier-one suppliers in Detroit and Wolfsburg are displacing fragmented job shop networks with preferred platform partnerships that guarantee 48-hour turnaround on engineering change orders. This concentration is most visible in electric vehicle battery enclosure development, where thermal runaway testing demands iterative prototype cycles compressed from months to weeks.
Conventional and Rapid Prototyping Market Segmentation
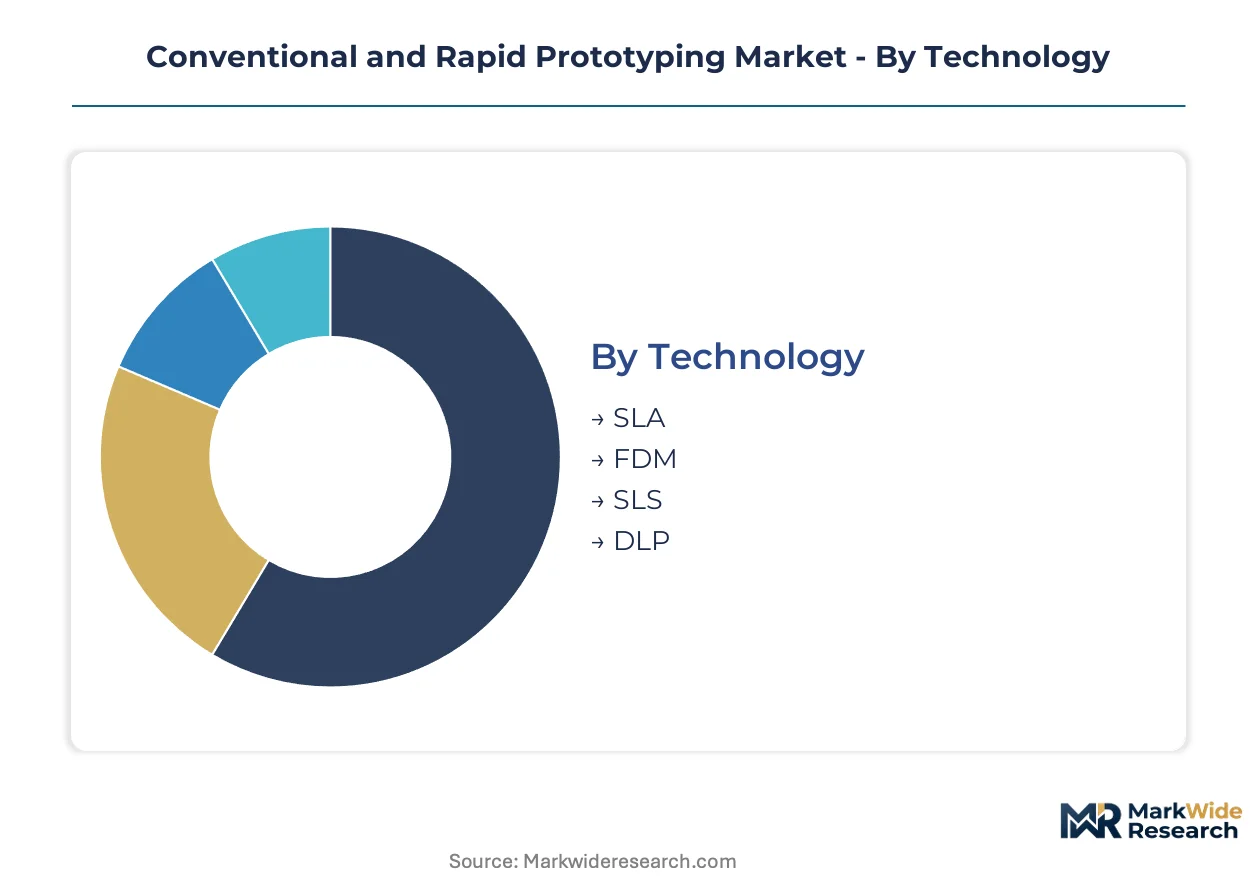
Prototyping market segmentation reveals stark capital-intensity gradients across technologies, with metal powder systems demanding infrastructure investments that polymer workflows avoid entirely. Material selection and end-use certification requirements further stratify operational economics, creating distinct competitive arenas that resist cross-segment migration.
Technology:
Capital intensity peaks with metal powder bed fusion systems requiring controlled atmosphere chambers and thermal management infrastructure, while vat photopolymerization operates at significantly lower equipment thresholds.
- SLA:Vat photopolymerization achieves layer resolutions down to 25 microns through ultraviolet laser curing of liquid resins. Demand concentrates in Germany's precision engineering clusters around Stuttgart and Munich, where medical device manufacturers require optical-grade surface finishes for surgical guide validation. FDA 510(k) pathways for patient-specific prototypes pull high-resolution SLA capacity toward healthcare applications.
- SLS:Selective laser sintering fuses nylon and thermoplastic powders without support structures, enabling complex geometries impossible through conventional machining. Aerospace tier-one suppliers in Toulouse and Hamburg qualify SLS parts for non-critical cabin brackets, bypassing forging lead times entirely while awaiting full structural certification pathways.
- FDM:Fused deposition modeling dominates educational and consumer electronics sectors through accessible equipment costs and open material standards.
- DLP:Digital light processing projects entire layer patterns simultaneously, accelerating throughput for dental and jewelry applications where batch consistency outweighs absolute resolution.
FDM absorbs the bulk of installed capacity; SLS is expanding most quickly.
End User:
Customer type determines certification burden and margin structure, with regulated industries accepting premium pricing for traceability while consumer-facing sectors prioritize unit economics.
- Automotive:OEM procurement teams bundle design verification, functional testing, and low-volume bridge manufacturing into single-source contracts with penalty clauses for missed validation milestones. Stuttgart and Munich engineering clusters require crash-worthy prototypes, pulling high-temperature polymer and metal powder demand from validation labs serving electric vehicle battery enclosure development.
- Aerospace:Flight-worthy component qualification demands material traceability and process documentation that exclude all but the most capitalized service bureaus. China's MIIT dual carbon goals are accelerating aluminum and carbon fiber composite substitutions, creating demand for SLS and binder jetting workflows that minimize material waste in structural prototype iterations.
- Healthcare:Patient-specific implant prototypes require 18-24 month FDA 510(k) certification cycles, compressing margins and deterring smaller service bureaus from clinical market entry.
- Consumer Electronics:Rapid design iteration cycles favor low-cost FDM and SLA workflows where cosmetic appearance outweighs mechanical performance.
Automotive commands the largest contract values; aerospace is gaining share fastest.
Application:
Workflow positioning along the product development cycle determines pricing power, with upstream concept validation commoditizing while downstream production bridging sustains premiums.
- Functional Testing:Crash simulation and thermal runaway validation require engineering-grade materials that replicate end-use performance. Tier-one suppliers in Detroit and Wolfsburg are displacing fragmented job shop networks with preferred platform partnerships that guarantee 48-hour turnaround on engineering change orders.
- Low-Volume Production:Bridge manufacturing fills the gap between prototype approval and tooling completion, capturing margin pools that conventional manufacturers forfeit to lead time pressure. Multi-material jetting convergence enables soft robotics and wearable medical device prototyping previously requiring assembly of discrete components.
- Design Verification:Form and fit checking tolerates lower material specifications, concentrating demand at price-sensitive service tiers.
- Visual Prototyping:Marketing and stakeholder presentation models prioritize surface finish over mechanical properties, sustaining SLA and resin-based workflows.
Design verification holds the largest volume base; functional testing is climbing the fastest.
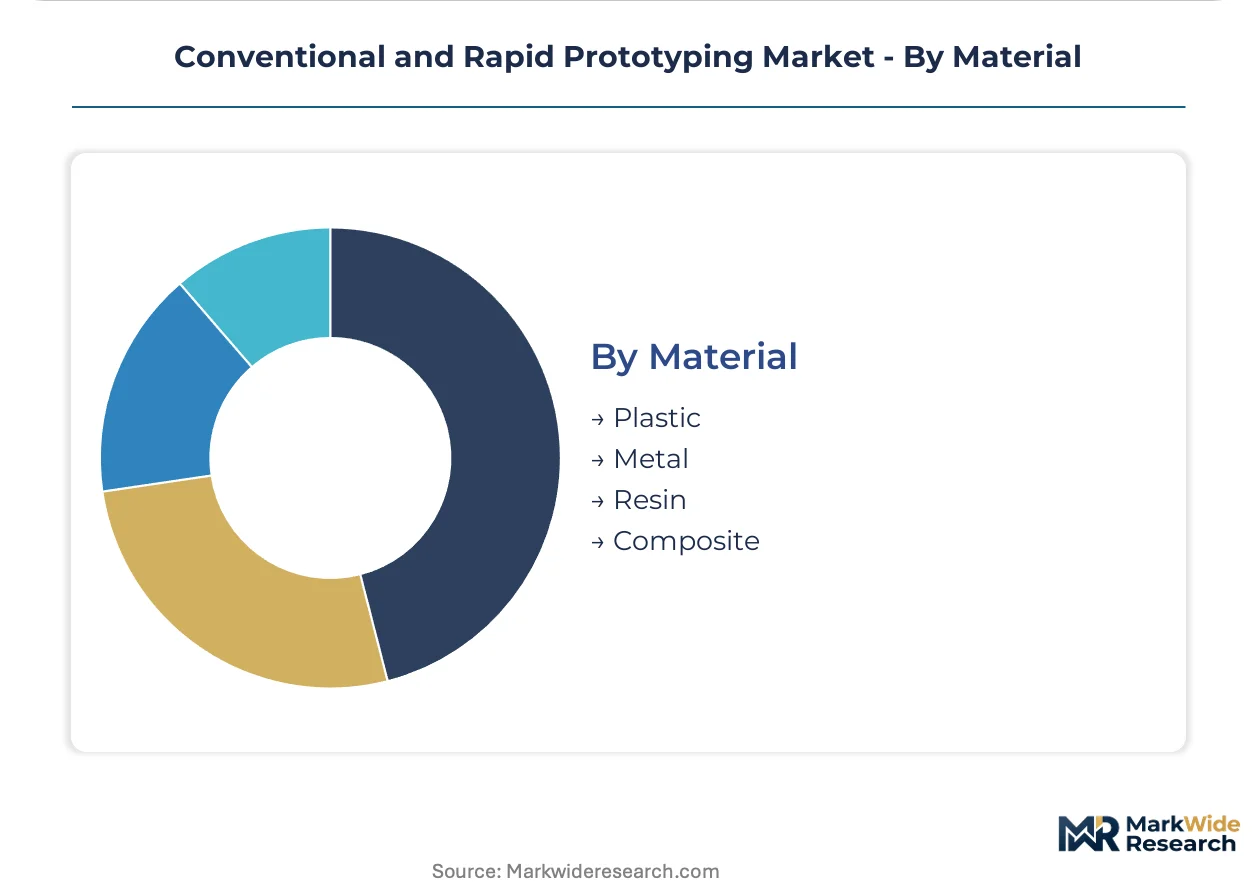
Material:
Feedstock chemistry dictates equipment compatibility, regulatory exposure, and supply chain vulnerability across geographic markets.
- Metal:Titanium and nickel powder supply concentration exposes Western prototype shops to export restriction risk, with over 70% of aerospace-grade feedstock originating from Chinese and Russian refiners. ECHA REACH restrictions on powder handling and occupational exposure force European operators into costly ventilation and containment upgrades.
- Resin:Photopolymer formulations face tightening ECHA REACH limits on acrylate and epoxy chemistry, forcing European SLA operators into reformulation cycles without guaranteed performance parity. Medical device manufacturers in Ireland and the Netherlands face reformulation validation costs exceeding €500,000 per product line.
- Plastic:Nylon and ABS filaments operate in mature, price-competitive territory where material suppliers differentiate through specialized optical and thermal properties.
- Composite:Continuous fiber reinforcement embeds carbon, glass, or aramid strands within thermoplastic matrices, producing anisotropic strength comparable to aluminum in specific orientations.
Plastic resins anchor current throughput volumes; metal powders are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT dual carbon goals concentrate prototyping demand in special economic zones offering tax incentives for sustainable manufacturing infrastructure. Germany's precision engineering clusters and the United States' aerospace corridors anchor high-value functional testing applications.
China
Automotive OEMs in the Yangtze River Delta demand aluminum and carbon fiber composite prototypes to meet MIIT dual carbon mandates. GB standards on recycled feedstocks redirect material selection toward bio-based resins. Shenzhen and Dongguan manufacturing hubs host SLS and binder jetting facilities serving electric vehicle battery enclosure development.
Germany
Stuttgart and Munich engineering clusters require crash-worthy prototypes for functional validation of electric powertrains. KBA regulations on automotive safety certification pull high-temperature polymer demand toward ISO 9001-accredited labs. Baden-Württemberg's precision tooling ecosystem integrates additive workflows into traditional supply chains.
United States
FDA 510(k) pathways for patient-specific implants concentrate healthcare prototyping demand in FDA-registered facilities. FAA certification requirements for flight-worthy components sustain premium pricing in aerospace corridors. Detroit automotive procurement teams bundle design verification and bridge manufacturing into single-source platform contracts.
Japan
METI subsidies for advanced manufacturing equipment accelerate adoption of metal powder bed fusion systems. JIS standards on material traceability govern aerospace tier-one supplier qualification processes. Nagoya's industrial corridor hosts validation labs serving Toyota and Honda engineering change orders.
United Kingdom
EMA and MHRA convergence on medical device regulations creates demand for ISO 13485-certified prototyping services. CSRD reporting requirements push material suppliers toward recycled feedstock formulations. Midlands automotive suppliers integrate SLA workflows for interior component validation ahead of tooling commitment.
Conventional and Rapid Prototyping Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology and service tiers. Market structure concentrates around three strategic archetypes: distributed manufacturing platforms, integrated hardware-material vendors, and automated job shop networks. Consolidation pressures favor players with captive material supply or proprietary quoting engines. Dominant competitive moves include geographic expansion through distributed networks and backward integration into specialty resin formulations.
Among North American platform operators, Xometry and Fictiv exemplify the distributed manufacturing archetype, connecting buyers to validated supplier networks without fixed asset ownership. Stratasys anchors the integrated hardware-material tier, representing equipment vendors bundling simulation software with hardware subscriptions to capture recurring revenue. Proto Labs occupies the automated production position, compressing order-to-delivery cycles through proprietary quoting engines for injection-molded and CNC-machined components.
| Leading Market Players |
|---|
| Stratasys |
| Fathom |
| Proto Labs |
| Envative |
| Fictiv |
| Xometry |
| WAYKEN |
| Maruti Techlabs |
| 3ERP |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up service bureau networks now control significant prototyping capacity across North American and European markets, concentrating pricing discipline through standardized quoting engines while compressing margins for independent job shops competing on turnaround speed. This ownership pattern aligns supply consolidation with tiered service bundling, as platform operators leverage captive supplier relationships to enforce volume discounts on metal powder and photopolymer resin feedstocks.
Pricing Analysis
Price erosion across economy-tier FDM services traces to open-source hardware commoditization and filament oversupply from Chinese extrusion plants. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical prototyping from uncertified concept modeling, with aerospace functional testing commanding the highest premiums due to material traceability requirements. Cost compression in standard-tier polymer SLS accelerates because automated nesting software maximizes build chamber utilization, squeezing per-part margins for manual operators. Automotive OEM procurement teams exhibit lowest price sensitivity, prioritizing 48-hour engineering change turnaround over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns for metal powder and resin feedstock delivery, with Stuttgart, Shenzhen, and Detroit serving as primary consolidation nodes. Titanium and nickel powder supply draws from Chinese and Russian refiner concentration, while photopolymer resin formulation rests on German and Japanese chemical specialist expertise. Single-source vulnerability in aerospace-grade metal feedstock exposes Western prototype shops to export restriction risk. Distribution runs through platform-managed supplier networks that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards players securing captive control over specialty resin formulations and metal powder qualification pipelines, as backward integration into feedstock chemistry separates margin leaders from quoting-engine intermediaries.
For Market Incumbents: Extend platform density through preferred supplier network expansion in Germany's Stuttgart and Munich engineering clusters, defending against emerging distributed manufacturing entrants by embedding automated quoting engines directly into customer MRP systems. ISO 9001 and ASTM F42 certification investment creates switching costs for automotive and medical device accounts. For New Entrants and Emerging Players: Brazil's ANVISA fast-track pathway for 3D-printed dental and orthopedic devices opens a window for prototype-to-production integrators targeting Latin American markets with regulatory-first positioning. Soft robotics and wearable medical device applications represent the most penetrable white-space segment, with multi-material jetting convergence enabling single-build rigid-elastomer combinations previously requiring assembly. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated job shop networks with proprietary quoting engines in North American industrial corridors, where private-equity rollup fatigue may release assets at compressed multiples. Watch FDA 510(k) validation timeline compression as the inflection signal distinguishing clinical-market viable platforms from concept-modeling commodity players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resin Formulations | ECHA REACH compliance burden consolidation favors integrated material-hardware vendors absorbing reformulation costs. |
| Distributed Manufacturing Platform Expansion | Xometry and Fictiv validate supplier networks compress procurement cycles from weeks to hours across North America and Europe. |
| Continuous Fiber Reinforcement Hardware Bundling | Equipment vendors embedding simulation software capture recurring revenue while blurring prototype-structural part boundaries. |
| ISO 13485 Certification Investment | Medical device manufacturers in Ireland and Netherlands consolidate supply relationships toward compliant prototyping partners. |
| Multi-Material Jetting Capability Deployment | Single-build rigid-elastomer combinations enable soft robotics prototyping previously requiring discrete component assembly. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with additive manufacturing service bureau operators, automotive Tier 1 procurement managers, medical device regulatory affairs leads, and aerospace tier-one supplier quality engineers. Bottom-up capacity modeling across technology segments triangulated against top-down demand projections from end-use industry production forecasts. ASTM F42 committee documentation, FDA 510(k) submission databases, and ECHA REACH restriction notices provided standardization and compliance trajectory inputs.
Data-stream reconciliation across shipment volumes, equipment install bases, and material consumption patterns informed the analytical framework across the analysis window. Segmentation dimensions modeled include technology type, end-use industry, application workflow position, and material chemistry family, with metal powder bed fusion and vat photopolymerization treated as distinct capital-intensity strata. CAGRs derived from fitted growth curves incorporating technology substitution elasticities and regulatory adoption thresholds.
The model assumes a particular technology adoption path; alternative pathways for metal binder jetting would alter the outlook if aerospace qualification timelines compress faster than projected. Forecasts reflect documented assumptions on ECHA REACH enforcement intensity and MIIT dual carbon mandate implementation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
Metal 3D Printing Service Market
3D Printing Technology
Global 3D Printed Electronics Market
3D Printing Technology
US Additive Manufacturing Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
3D Printing Vacuum Furnaces Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
3D Printing Market