
 Middle East and Africa Additive Manufacturing Market | 2026-2036
Middle East and Africa Additive Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Additive Manufacturing Market Foresight
Skilled metal powder technicians is rotating from a bottleneck into a deliberate competitive moat across Gulf additive operations. Immensa Technology Labs leverages its Dubai-based engineering workforce to dominate on-demand spare part production for energy sector clients. Aeroswift anchors South African capability in large-format titanium printing for aerospace structural components. Sinterex specializes in medical device-grade polymer printing, navigating stringent biocompatibility requirements that filter out generalist competitors.
Additive manufacturing encompasses layer-by-layer fabrication processes that fuse metals, polymers, or ceramics using directed energy or binding agents to achieve near-net-shape geometries with typical tolerances of 0.1–0.3 mm. The technology eliminates conventional tooling for low-volume production, enabling distributed manufacture of complex internal channels and topology-optimized structures that subtractive methods cannot machine. Aerospace applications lead value generation across the region, with OEM demand for lightweight bracketry and engine repair components commanding premium pricing. Selective Laser Sintering in metals captures the fastest expansion trajectory, driven by Gulf defense and aviation maintenance programs requiring Inconel and Ti-6Al-4V part certification. Research Institutions as an end user category sustains above-average growth, with Saudi and Emirati universities operating government-funded centers of excellence in directed energy deposition.
South Africa's BIS-aligned national standards framework and the UAE's Emirates Authority for Standardization and Metrology regulate material traceability and mechanical testing protocols for load-bearing printed parts. EMA-equivalent pathways through Saudi FDA and South African Health Products Regulatory Authority shape medical implant qualification timelines, creating compliance barriers that favor established certificate holders. Stakeholders must monitor how Gulf sovereign wealth deployment into domestic manufacturing capability alters procurement preferences away from European service bureaus toward local production partnerships.
Market Dynamics
Gulf sovereign wealth deployment into domestic manufacturing capability is redirecting procurement preferences away from European service bureaus toward local production partnerships, reshaping competitive positioning across the value chain.
Growth Catalysts
- Emirates Authority for Standardization and Metrology protocols:The UAE's national standards framework accelerates part qualification timelines for energy sector clients, reducing certification delays that previously bottlenecked adoption.
- Selective Laser Sintering in metals:Gulf defense and aviation maintenance programs drive fastest expansion trajectory, with Inconel and Ti-6Al-4V certification requirements pulling investment into qualified production capacity.
- South African local content mandates:Department of Trade, Industry and Competition requirements redirect tooling spend toward domestic additive producers, insulating regional suppliers from import competition.
Market Restraints
- Specialized metal powder supply concentration:Spherical titanium and nickel superalloy feedstock concentrates among limited qualified suppliers, exposing Gulf operations to input cost volatility and geopolitical supply disruption.
- Biocompatibility certification friction:EMA-equivalent pathways through Saudi FDA and South African Health Products Regulatory Authority create multi-year qualification timelines for medical implants, filtering out generalist competitors.
- Subtractive machining substitution:Conventional CNC retains cost advantage for simple geometries above medium volumes, compressing addressable market for metal additive in standardized bracketry.
Strategic Opportunities
- Saudi university research centers:Government-funded directed energy deposition facilities at King Saud University and KAUST create technology transfer pipelines for industrial commercialization.
- Oil and gas spare part digitization:Immensa Technology Labs and Emirates Centre for Industrial Technology anchor distributed manufacturing networks for obsolete component reproduction without original tooling.
- Topology-optimized aerospace bracketry:Lightweighting demand from Gulf carriers and defense procurement creates premium pricing environment for flight-certified printed structures.
Industry Challenges
- Skilled metal powder technician scarcity:Gulf operations compete for qualified personnel capable of parameter optimization and build plate management, with training pipelines lagging installed machine base expansion.
- Mechanical testing protocol complexity:BIS-aligned South African standards and UAE material traceability requirements demand destructive testing regimes that extend delivery timelines and inflate qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Additive Manufacturing Market |
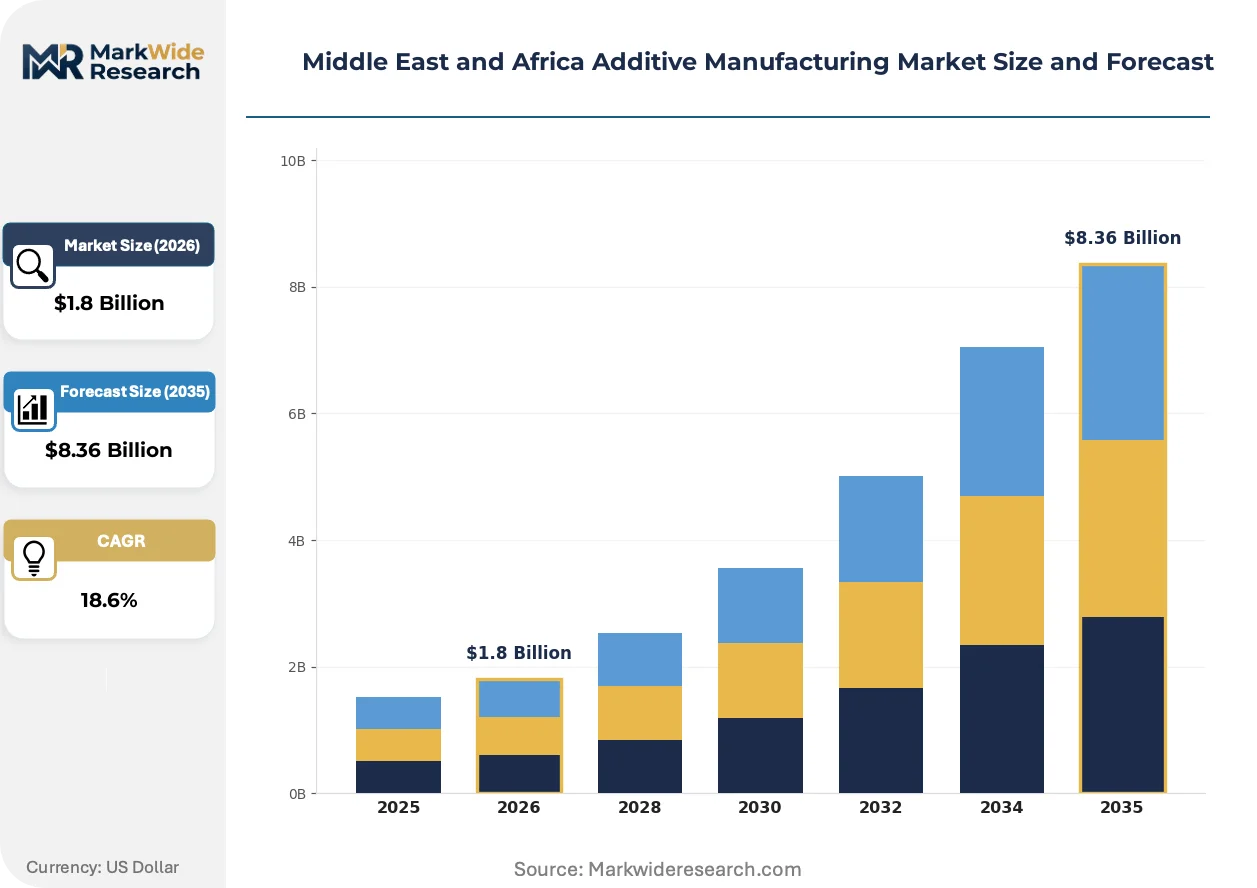
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerospace, Automotive, Healthcare, Consumer Goods Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing End User: OEMs, Research Institutions, Prototyping Firms, Tooling Companies Material: Plastics, Metals, Ceramics, Composites |
| Companies Covered | Immensa Technology Labs, Sinterex, D2M Solutions, Team Visual Solutions, Printie 3D, Amtech 3D, IRIS 3D Solutions, KSA 3D, Aeroswift, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Additive Manufacturing Market Shifts & Advancements
Directed energy deposition systems are fragmenting application boundaries between repair and original manufacture, while regulatory convergence around medical device qualification reshapes competitive entry barriers.
Multi-laser powder bed fusion is fragmenting throughput economics for titanium aerospace components. Saudi defense maintenance divisions and Emirates airline engineering units adopt these systems for turbine blade repair and structural bracket production. The technology is fragmenting the traditional separation between OEM supply chains and MRO operations, enabling same-facility transition from repair to replacement part manufacture.
South Africa's BIS-aligned national standards framework and UAE's Emirates Authority for Standardization and Metrology are converging on ISO/ASTM additive manufacturing standards for load-bearing part certification. This regulatory convergence reduces duplicative testing burdens for suppliers operating across both jurisdictions. Medical implant manufacturers face compressed qualification timelines as Saudi FDA and South African Health Products Regulatory Authority align biocompatibility protocols with EMA-equivalent pathways.
Energy sector buyers are consolidating spare part procurement around digitized inventory programs. Oil and gas operators in the UAE and Saudi Arabia are displacing traditional warehousing with on-demand production contracts tied to digital part libraries. This pattern concentrates most visibly in offshore platform maintenance, where logistics costs previously dominated obsolete component sourcing economics.
Middle East and Africa Additive Manufacturing Market Segmentation
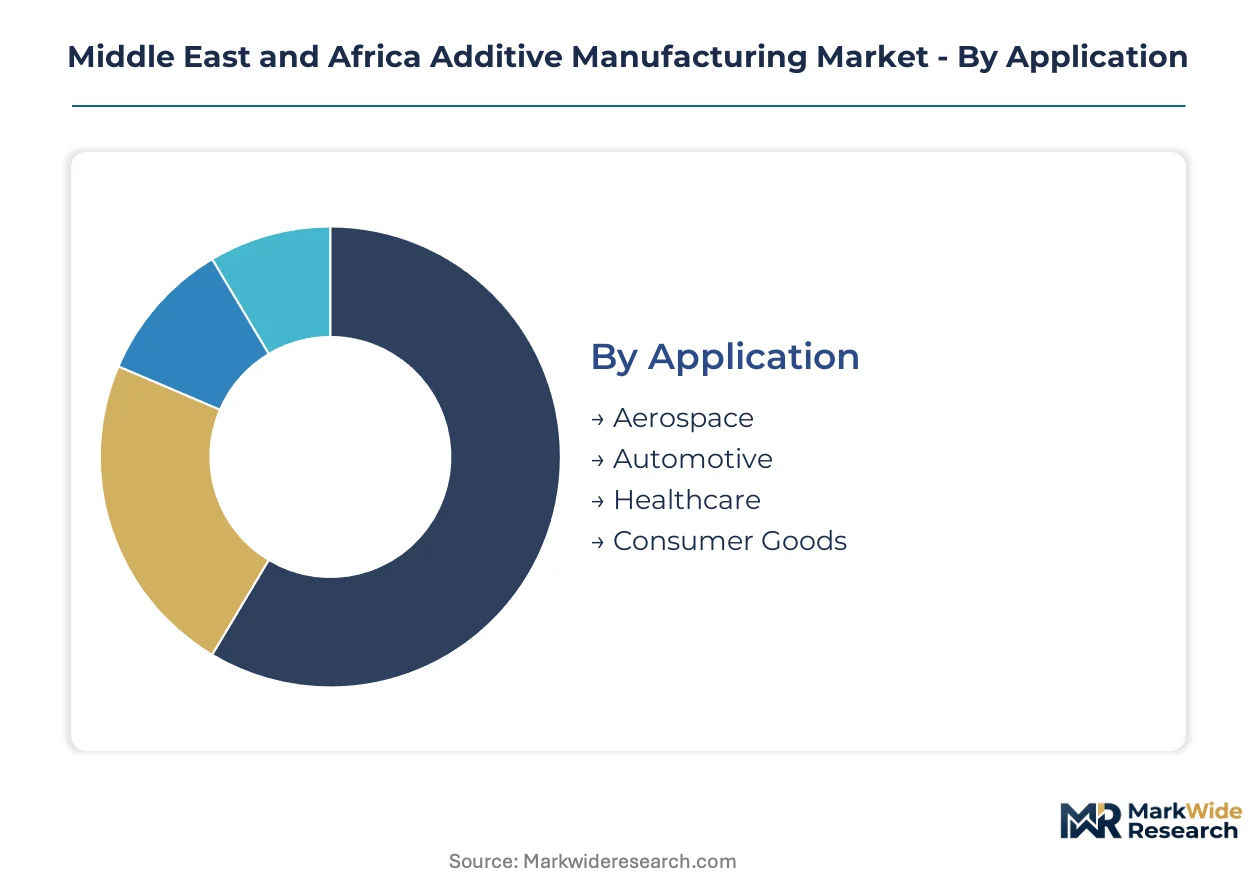
Additive manufacturing demand across the Middle East and Africa fragments sharply by application maturity and technology readiness. Procurement patterns in Gulf aerospace diverge fundamentally from South African medical device workflows, creating distinct segment performance profiles.
Application:
Aerospace and healthcare applications concentrate in UAE and Saudi Arabia, while automotive and consumer goods serve broader regional export markets.
- Aerospace:Turbine blade repair and structural bracketry dominate Gulf procurement budgets. Emirates airline engineering and Saudi defense maintenance divisions command premium pricing for Inconel and Ti-6Al-4V flight-certified components.
- Healthcare:Patient-specific implants and surgical guides navigate SFDA and South African Health Products Regulatory Authority biocompatibility pathways. Sinterex and similar specialists isolate revenue from generalist competitors through multi-year qualification investments.
- Automotive:Tooling and jigs absorb South African local content mandates under Department of Trade, Industry and Competition directives.
- Consumer Goods:Customized product runs and replacement parts serve distributed African markets with limited logistics infrastructure.
Aerospace holds the largest share; momentum sits with healthcare as regulatory convergence compresses implant qualification timelines.
Technology:
Metal-capable systems command cost premiums above polymer-focused equipment, fragmenting vendor strategies between margin and volume plays.
- Selective Laser Sintering:Multi-laser powder bed fusion systems process titanium and nickel superalloys for defense and aviation maintenance programs. Gulf sovereign wealth deployment accelerates qualified production capacity installation.
- Fused Deposition Modeling:Entry-level polymer extrusion dominates prototyping firm installed bases across Nigeria and Kenya. Equipment costs below metal systems enable rapid geographic penetration.
- Stereolithography:High-resolution resin curing serves dental and jewelry applications in UAE and South African urban centers.
- Digital Light Processing:Mask-based polymer curing bridges resolution and speed requirements for mid-volume consumer goods production.
Selective Laser Sintering generates highest revenue per machine; Fused Deposition Modeling expands most quickly through African distributor networks.
End User:
OEM captive operations and independent service bureaus compete for overlapping contract boundaries, particularly in energy sector spare part digitization.
- OEMs:Emirates airline engineering and Saudi Aramco maintain in-house metal printing for proprietary component repair. Captive capacity insulates critical supply chains from external qualification delays.
- Research Institutions:King Saud University and KAUST directed energy deposition facilities transfer technology to industrial commercialization pipelines. Government funding sustains above-average growth in this category.
- Prototyping Firms:Quick-turn polymer printing serves product development cycles for consumer goods and automotive suppliers.
- Tooling Companies:South African domestic producers redirect spend from imported dies toward locally printed conformal cooling inserts.
OEMs retain largest share; Research Institutions gain share fastest through Saudi and Emirati government-funded center expansion.
Material:
Feedstock qualification requirements separate aerospace and medical revenue pools from commodity polymer applications.
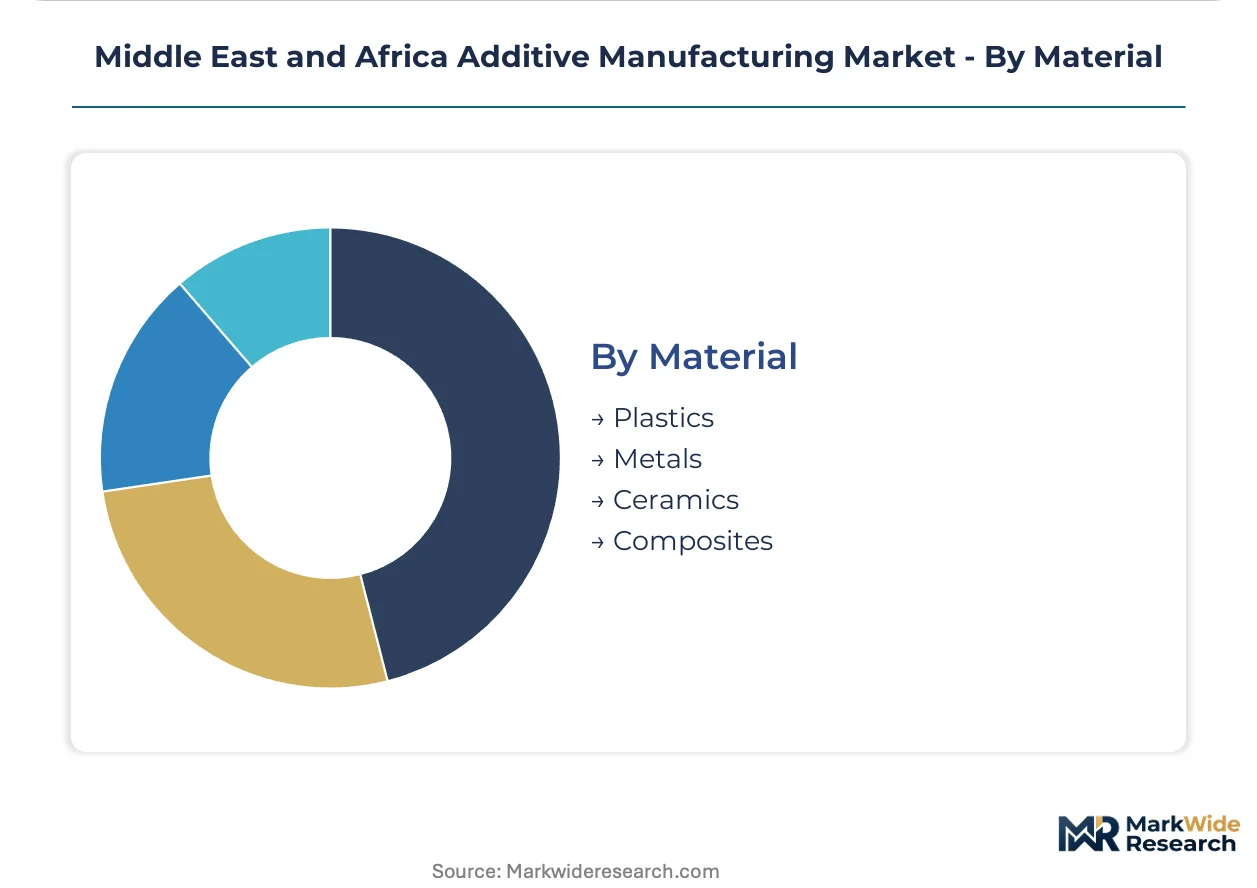
- Metals:Spherical titanium and Inconel powder supply concentrates among limited qualified vendors, exposing Gulf operations to input cost volatility. Emirates Authority for Standardization and Metrology traceability protocols govern batch documentation.
- Plastics:ABS and nylon filaments serve prototyping firm volume demand across price-sensitive African markets. Material costs per kilogram run substantially below metal powders.
- Ceramics:Alumina and zirconia printing navigates emerging qualification frameworks for dental and industrial wear applications.
- Composites:Carbon fiber-reinforced polymers target aerospace bracketry and automotive structural components with specific strength requirements.
Metals command highest value share; composites climb fastest as fiber-reinforced polymer qualification matures for flight-critical structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf states consume additive manufacturing primarily for energy sector spare parts and aerospace maintenance, while South Africa deploys the technology for medical devices and automotive tooling under local content mandates.
United Arab Emirates
Dubai's Emirates Centre for Industrial Technology anchors oil and gas digitization programs, converting obsolete component libraries into on-demand production contracts. MOHAP regulates medical device biocompatibility through alignment with international standards. Immensa Technology Labs dominates energy sector spare part production from its Dubai engineering base.
Saudi Arabia
King Saud University and KAUST operate government-funded directed energy deposition centers that transfer technology to industrial pipelines. SFDA governs medical implant qualification timelines through EMA-equivalent pathways. Riyadh and the Eastern Province concentrate defense maintenance divisions adopting multi-laser powder bed fusion for turbine blade repair.
South Africa
Aeroswift anchors large-format titanium printing capability for aerospace structural components under BIS-aligned national standards. The Department of Trade, Industry and Competition redirects tooling spend toward domestic additive producers through local content requirements. Johannesburg and Pretoria host medical device specialists like Sinterex navigating multi-year biocompatibility certifications.
Israel
Defense procurement programs drive metal additive adoption for lightweight bracketry and topology-optimized structures. The country's national standards framework converges on ISO/ASTM protocols for load-bearing part certification. Tel Aviv and Haifa concentrate research institutions sustaining above-average growth in directed energy deposition commercialization.
Egypt
Prototyping firms serving consumer goods and automotive suppliers absorb entry-level polymer extrusion systems. The country's national industrial development programs channel investment toward distributed manufacturing networks. Cairo anchors quick-turn printing operations for product development cycles across North African export markets.
Middle East and Africa Additive Manufacturing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Gulf sovereign wealth deployment favoring domestic production partnerships over European service bureau relationships. The vendor base separates into technology-agnostic service bureaus, material-integrated fabricators, and research-commercialization hybrids. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players race to qualify production lines for Inconel and Ti-6Al-4V aerospace certification.
Among UAE-based technology-agnostic service bureaus, Immensa Technology Labs and Team Visual Solutions exemplify the energy sector spare part digitization archetype. South African fabricators Aeroswift occupy a position within the large-format metal printing tier, anchoring capability for aerospace structural components under stringent BIS-aligned testing protocols. These three entities represent contrasting geographic and specialization strategies within a market where qualification investments create durable competitive moats.
| Leading Market Players |
|---|
| Immensa Technology Labs |
| Sinterex |
| D2M Solutions |
| Team Visual Solutions |
| Printie 3D |
| Amtech 3D |
| IRIS 3D Solutions |
| KSA 3D |
| Aeroswift |
| Others |
Supply & Pricing Matrix
Emirates Authority for Standardization and Metrology certification protocols gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified imports while enabling premium capture by accredited domestic producers. Contract structures stratify across long-term offtake agreements for aerospace-qualified titanium builds, project-based pricing for energy sector spare part digitization, and spot transactions for polymer prototyping services. Price differentiation hinges on material traceability grade and flight-certification tier, with Inconel and Ti-6Al-4V builds commanding substantial premiums over uncertified aluminum or polymer equivalents. Cost compression in entry-level polymer extrusion intensifies as Nigerian and Kenyan distributor networks expand equipment penetration. Prototyping firms exhibit highest price sensitivity; defense maintenance divisions show least sensitivity due to qualification-driven procurement rigidity.
Pricing Analysis
Contract structures stratify across long-term offtake agreements for aerospace-qualified titanium builds, project-based pricing for energy sector spare part digitization, and spot transactions for polymer prototyping services. Price differentiation hinges on material traceability grade and flight-certification tier, with Inconel and Ti-6Al-4V builds commanding substantial premiums over uncertified aluminum or polymer equivalents. Cost compression in entry-level polymer extrusion intensifies as Nigerian and Kenyan distributor networks expand equipment penetration. Prototyping firms exhibit highest price sensitivity; defense maintenance divisions show least sensitivity due to qualification-driven procurement rigidity.
Supply Chain Analysis
Inventory strategy favors just-in-time digitized part libraries over physical warehousing, particularly in UAE and Saudi offshore platform maintenance operations. Spherical titanium and nickel superalloy feedstock concentrates among qualified suppliers in Germany, the United States, and China, exposing Gulf operations to input cost volatility. Supply chain risk centers on single-source vulnerability for aerospace-grade metal powders. Distribution runs through authorized service bureaus and OEM captive facilities rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as sovereign wealth deployment redirects procurement toward domestic partnerships, splintering previously consolidated European service bureau relationships. Energy sector digitization programs and medical implant qualification pipelines offer distinct white-space targets for differentiated positioning.
For Market Incumbents: Secure qualification moats through Emirates Authority for Standardization and Metrology accreditation expansion and backward integration into spherical powder supply. Threats from emerging UAE-based service bureaus intensify as Immensa Technology Labs and similar entities capture energy sector contracts. Capacity addition in Riyadh and Dubai anchors geographic defense against European import competition. For New Entrants and Emerging Players: Lead with medical device-grade polymer specialization in South African urban centers, where Sinterex has validated biocompatibility pathway economics but capacity constraints create service gaps. Egyptian prototyping firms serving North African consumer goods exporters represent the most penetrable segment. Go-to-market angle should emphasize quick-turn surgical guide production with SAHPRA-aligned documentation support. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-laser powder bed fusion capacity installation, favoring scaled players with sovereign wealth backing. Long-term viability over the next decade rests on aerospace certification depth rather than equipment count alone. Acquisition targets should display existing Inconel or Ti-6Al-4V qualification pipelines. Signal to monitor: SFDA and SAHPRA convergence timelines on EMA-equivalent biocompatibility protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Laser Powder Bed Fusion Capacity Buildout | Emirates airline engineering and Saudi defense maintenance divisions demand qualified titanium throughput for turbine blade repair. |
| Backward Integration into Spherical Metal Powder Supply | Concentrated qualified feedstock vendors in Germany and China expose Gulf operations to geopolitical disruption risk. |
| Medical Device Biocompatibility Certification Investment | SAHPRA and SFDA pathway alignment with EMA standards compresses multi-year qualification timelines for implant specialists. |
| Digital Part Library Platform Development | Immensa Technology Labs anchors oil and gas spare part digitization through on-demand production contracts. |
| Research Institution Technology Licensing | King Saud University and KAUST directed energy deposition facilities create industrial commercialization pipelines. |
Research Methodology
Initial hypotheses were tested against primary input from additive manufacturing operations managers, aerospace procurement leads, medical device regulatory affairs specialists, and energy sector maintenance planners, then refined against secondary validation. Primary fieldwork combined structured interviews with service bureau engineering directors and OEM captive facility heads. Secondary sources encompassed Emirates Authority for Standardization and Metrology technical bulletins, SAHPRA medical device registration databases, South African Department of Trade, Industry and Competition local content directives, and ISO/ASTM additive manufacturing standards documentation. Bottom-up capacity and utilization estimates were triangulated against top-down procurement spend analysis.
Variance decomposition across the projection horizon isolates technology adoption rates, regulatory pathway convergence timing, and sovereign wealth deployment intensity as primary forecast drivers. Segmentation dimensions modeled include application maturity tier, material qualification grade, end-user captive versus outsourced procurement preference, and geographic regulatory cluster. CAGRs were derived from installed base expansion trajectories qualified by utilization rate assumptions and average revenue per machine benchmarks. Industry-specific inputs incorporated aerospace OEM part certification timelines and energy sector digitized inventory adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained Gulf sovereign wealth manufacturing commitment or accelerated EMA-equivalent regulatory convergence would require recalibration. Forecasts reflect documented assumptions regarding qualified technician pipeline development and metal powder supply diversification. Revision becomes warranted when spherical titanium feedstock concentration crosses critical dependency thresholds or when SFDA-SAHPRA protocol alignment stalls.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
Military 3D and 4D Printing Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
4D Printing Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
3D Printer Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
3D Printing Market
3D Printing Technology
Desktop 3D Printing Market