
 Europe Industrial 3D Printing Market | 2026-2036
Europe Industrial 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial 3D Printing Market Insights
Production-grade metal powder specifications are reorganizing competitive priorities across European industrial additive manufacturing. EOS GmbH leverages its laser powder-bed fusion portfolio to dominate high-tolerance aerospace contracts across Germany and France. SLM Solutions Group AG anchors its position through selective laser melting systems purpose-built for nickel superalloy turbine blades. Materialise NV differentiates via software-controlled build preparation and distributed manufacturing networks spanning Benelux medical device clusters.
Europe Industrial 3D Printing encompasses layer-by-layer fabrication of functional components from digital models, typically achieving tolerances of 50-200 micrometers through directed energy deposition or powder-bed fusion processes. Its primary industrial purpose is producing geometrically complex parts—internal lattice structures, conformal cooling channels, topology-optimized brackets—that subtractive machining cannot economically realize. Selective Laser Sintering leads in polymer tooling and medical guides where surface finish requirements are moderate but batch flexibility is paramount. Metal powder systems, particularly in titanium and aluminum alloys, represent the fastest-expanding margin pool as aerospace and orthopedic OEMs qualify flight- and implant-grade builds. Fused Deposition Modeling occupies a mature cost-position in jigs, fixtures, and prototyping workflows where engineering thermoplastics suffice.
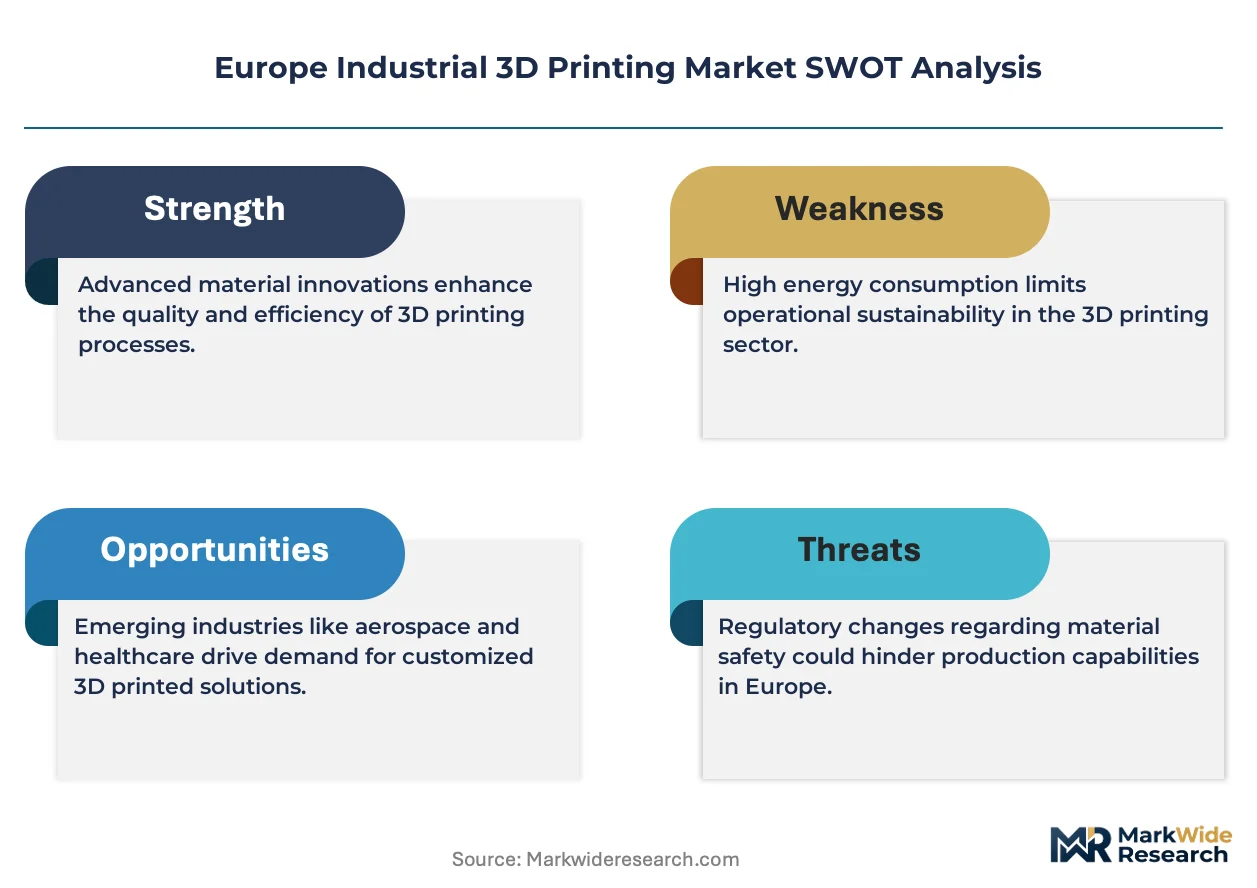
EMA medical device regulations and the EU AI Act's quality-system requirements are tightening documentation standards for patient-specific implant production across member states. REACH chemical restrictions and the F-Gas Regulation constrain solvent-based post-processing and certain inert atmosphere gases, redirecting R&D toward water-soluble support systems and closed-loop powder recovery. Stakeholders must monitor how CSRD sustainability disclosure rules reshape supplier qualification criteria for automotive and aerospace tier-one contracts.
Market Dynamics
Metal powder-bed fusion systems are compressing production timelines for aerospace and orthopedic OEMs across Germany, France, and Italy, forcing incumbent suppliers to requalify legacy supply chains around additive-certified specifications.
Growth Catalysts
- REACH chemical compliance:Manufacturers are accelerating adoption of recyclable thermoplastic feedstocks to meet ECHA-mandated sustainability disclosure requirements for automotive tier-one contracts.
- Conformal cooling channels:Injection molders in Germany's industrial belt are integrating lattice-structured tooling to reduce cycle times and eliminate secondary machining operations.
- France:ANSM's streamlined qualification pathway for patient-specific cranial implants is expanding hospital-based point-of-care manufacturing networks across the Paris and Lyon medical clusters.
Market Restraints
- Argon and nitrogen supply concentration:Inert gas dependencies on Eastern European suppliers create input cost volatility for laser powder-bed fusion operations requiring controlled atmosphere builds.
- Surface finish limitations:As-printed metal components require secondary CNC machining or chemical polishing to achieve aerospace Ra specifications, eroding additive cost advantages for precision surfaces.
- F-Gas Regulation constraints:Solvent-based vapor smoothing systems face phase-out timelines, forcing polymer processors toward aqueous support removal with longer post-processing cycles.
Strategic Opportunities
- Italy's underpenetrated automotive belt:Turin and Modena manufacturing clusters show low additive adoption relative to German counterparts, presenting first-mover positioning for production-grade polymer systems.
- EU Green Deal procurement mandates:Public sector buyers must weight embodied carbon in supplier selection, advantaging near-net-shape additive methods over subtractive waste streams.
- AI-driven build optimization:Machine learning convergence with real-time melt pool monitoring is decomposing traditional parameter development cycles from months to days.
Industry Challenges
- Certified technician scarcity:Aerospace-qualified additive manufacturing engineers command premium wages across Munich, Hamburg, and Toulouse industrial zones, constraining production scaling.
- EMA MDR documentation burdens:Patient-specific implant producers face 18-24 month technical file compilation timelines, compressing commercialization windows for novel device geometries.
- Legacy ERP integration:Shop-floor data from additive systems lacks standardized connectivity with SAP and Oracle manufacturing execution modules, forcing custom middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial 3D Printing Market |
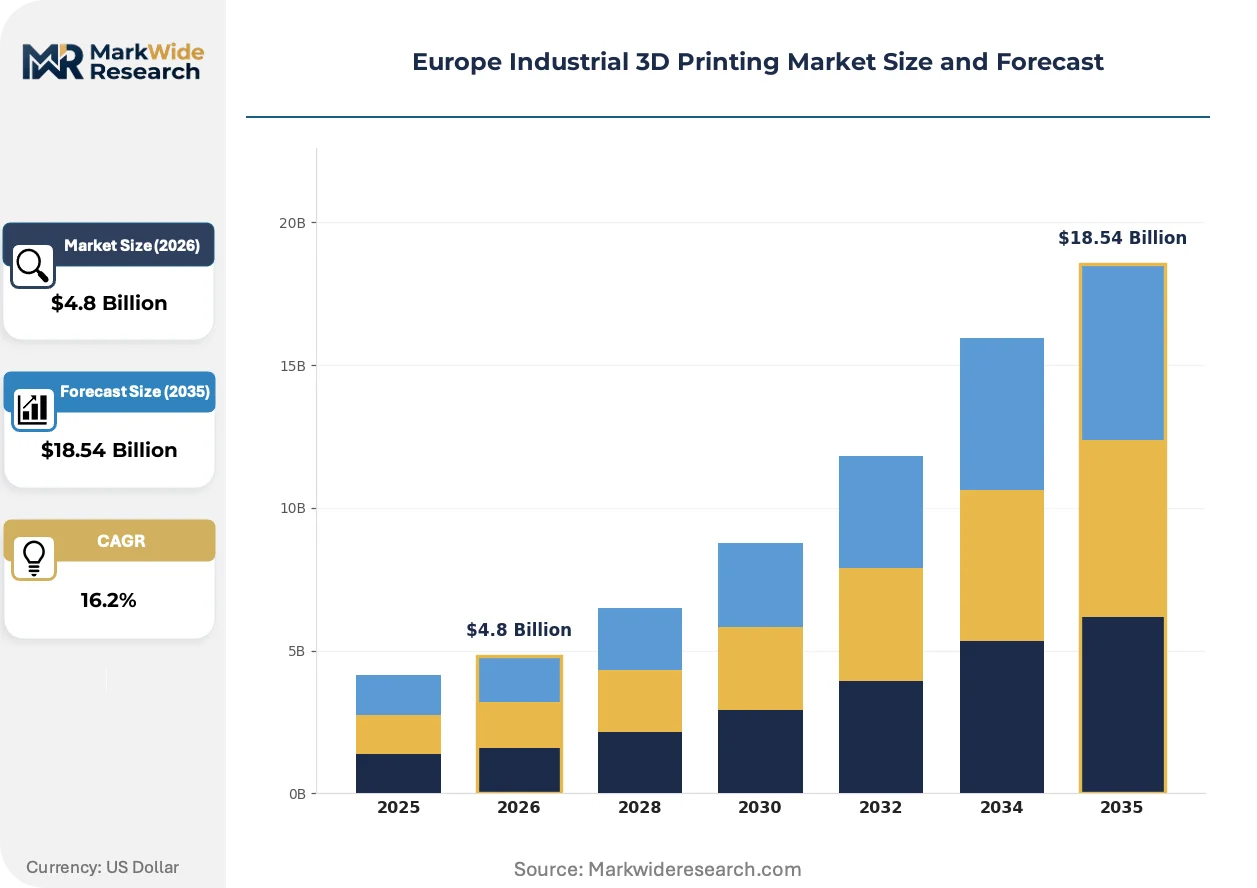
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.54 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing Material: Thermoplastics, Metals, Ceramics, Composites End User: Aerospace, Automotive, Healthcare, Consumer Goods Application: Prototyping, Tooling, Production, Customized Manufacturing |
| Companies Covered | Materialise NV, SLM Solutions Group AG, EOS GmbH, Stratasys Ltd., 3D Systems Corporation, Renishaw plc, Trumpf GmbH + Co., Ultimaker, Arcam AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial 3D Printing Market Trends and Innovations
Multi-laser metal systems and closed-loop powder recovery are reorganizing cost structures and environmental footprints simultaneously, while regulatory documentation requirements harden around traceability and sustainability verification.
Directed energy deposition with wire feedstock is decomposing the traditional forge-and-machine workflow for large titanium aerospace structures. Airbus and Safran suppliers in Hamburg and Nantes are qualifying wire-arc builds for wing rib and pylon components previously requiring 90% material removal. The technology is decomposing capital intensity barriers that confined additive to small, complex parts.
CSRD sustainability disclosure rules are mandating Scope 3 emissions reporting across automotive and aerospace supply chains. Tier-one suppliers must now document embodied carbon from raw powder through finished component, redirecting procurement toward closed-loop recycling systems and renewable-energy-powered build floors. German OEMs are imposing these requirements earliest, with French and Italian majors following within 18-24 months.
Point-of-care manufacturing is consolidating hospital demand for patient-specific surgical guides and implants around regional print hubs. Belgium's Materialise-driven distributed production model is displacing centralized manufacturing for craniomaxillofacial and orthopedic cases, with Netherlands and Swiss hospital networks adopting similar hub-and-spoke configurations. This shift is most visible in Benelux and Alpine medical corridors where regulatory harmonization supports cross-border device distribution.
Europe Industrial 3D Printing Market Segmentation
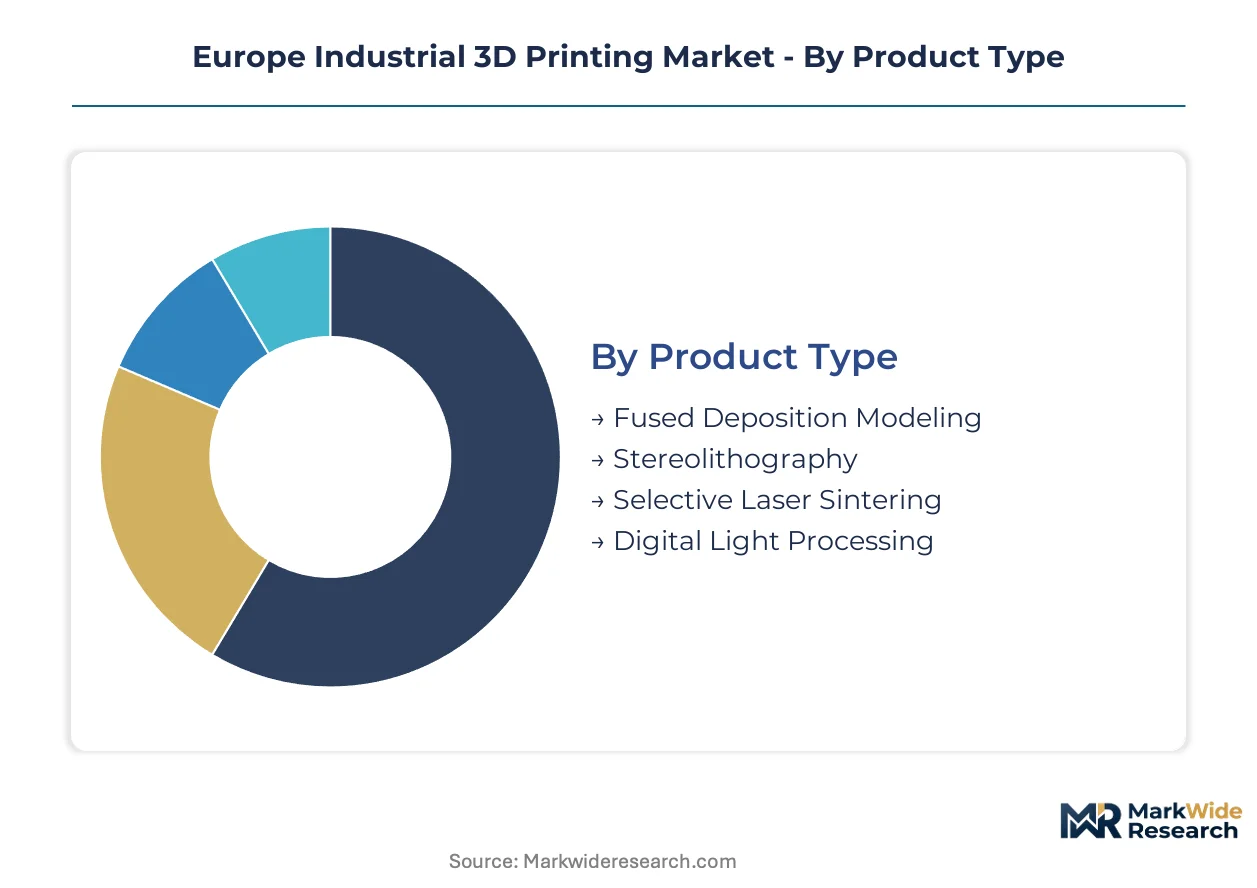
Industrial additive manufacturing in Europe fragments across four distinct dimensions that determine procurement priorities, margin profiles, and regulatory exposure. Each category reflects divergent supply chain configurations and end-use qualification requirements that shape competitive positioning across Germany, France, and Italy.
Product Type:
Geographic concentration varies sharply: German automotive and aerospace clusters drive powder-bed system demand, while Benelux medical device hubs favor vat-polymerization platforms for surgical guide production.
- Selective Laser Sintering:Powder-bed fusion of nylon and TPU polymers achieves 100-micron layer resolution for functional prototypes and end-use brackets. Munich and Stuttgart toolrooms deploy SLS for conformal cooling inserts in injection molds, though argon atmosphere costs constrain smaller job shops.
- Fused Deposition Modeling:Extrusion-based deposition of ABS and polycarbonate filaments dominates jigs, fixtures, and low-volume production across Turin and Modena automotive suppliers. Italian adoption lags German counterparts by 40% in production-grade applications, presenting first-mover positioning for tier-one contract manufacturers.
- Stereolithography:UV-cured resin systems from Dutch and Belgian vendors serve dental and hearing aid markets with 25-micron precision.
- Digital Light Processing:Projector-based vat polymerization accelerates orthodontic aligner mold production in Paris medical clusters.
Selective Laser Sintering commands the established base. The steepest expansion runs through Fused Deposition Modeling as Italian automotive suppliers close the adoption gap.
Material:
Cost tiers separate commodity thermoplastics from qualified metal powders, with aerospace and orthopedic OEMs imposing 3-5x price premiums for traceable titanium and nickel superalloy feedstocks.
- Metals:Titanium Ti-6Al-4V and aluminum AlSi10Mg powders dominate laser powder-bed fusion for flight-critical brackets and hip implants. Hamburg and Toulouse aerospace suppliers require lot-level chemical certification, compressing qualified supplier lists to German and French powder atomizers with EASA-recognized quality systems.
- Thermoplastics:PA12 and TPU pellets feed selective laser sintering workflows across automotive tooling and medical device housings. REACH-compliant recycled powder streams from German chemical suppliers are displacing virgin feedstocks as CSRD disclosure rules harden.
- Ceramics:Alumina and zirconia pastes serve dental crown production in Swiss and Austrian precision manufacturing clusters.
- Composites:Carbon-fiber-reinforced filaments strengthen robotic end-effectors and drone frames for industrial automation OEMs.
Thermoplastics anchor volume shipments across prototyping and tooling workflows. Metals gain share fastest as orthopedic and aerospace qualification timelines compress.
End User:
Application maturity diverges: aerospace and healthcare operate under EASA and EMA qualification regimes, while automotive and consumer goods face lighter regulatory burdens but sharper cost competition.
- Aerospace:Airbus and Safran suppliers in Hamburg, Nantes, and Turin qualify titanium pylon brackets and engine components for serial production. EASA Part 21G production organization approvals require 18-36 month certification cycles, locking incumbent additive suppliers into long-term contracts.
- Healthcare:Patient-specific cranial implants and surgical guides drive demand across Materialise-managed hospital networks in Belgium, Netherlands, and Switzerland. ANSM's streamlined qualification pathway accelerates Paris and Lyon point-of-care manufacturing adoption.
- Automotive:BMW and Mercedes-Benz toolrooms in Munich and Stuttgart deploy metal powder-bed fusion for press brake tooling and assembly fixtures.
- Consumer Goods:Eyewear and hearing aid manufacturers leverage vat-polymerization for mass customization across Italian and French design clusters.
Aerospace captures the highest per-kilogram margins. Healthcare expands most quickly as regulatory harmonization enables cross-border device distribution.
Application:
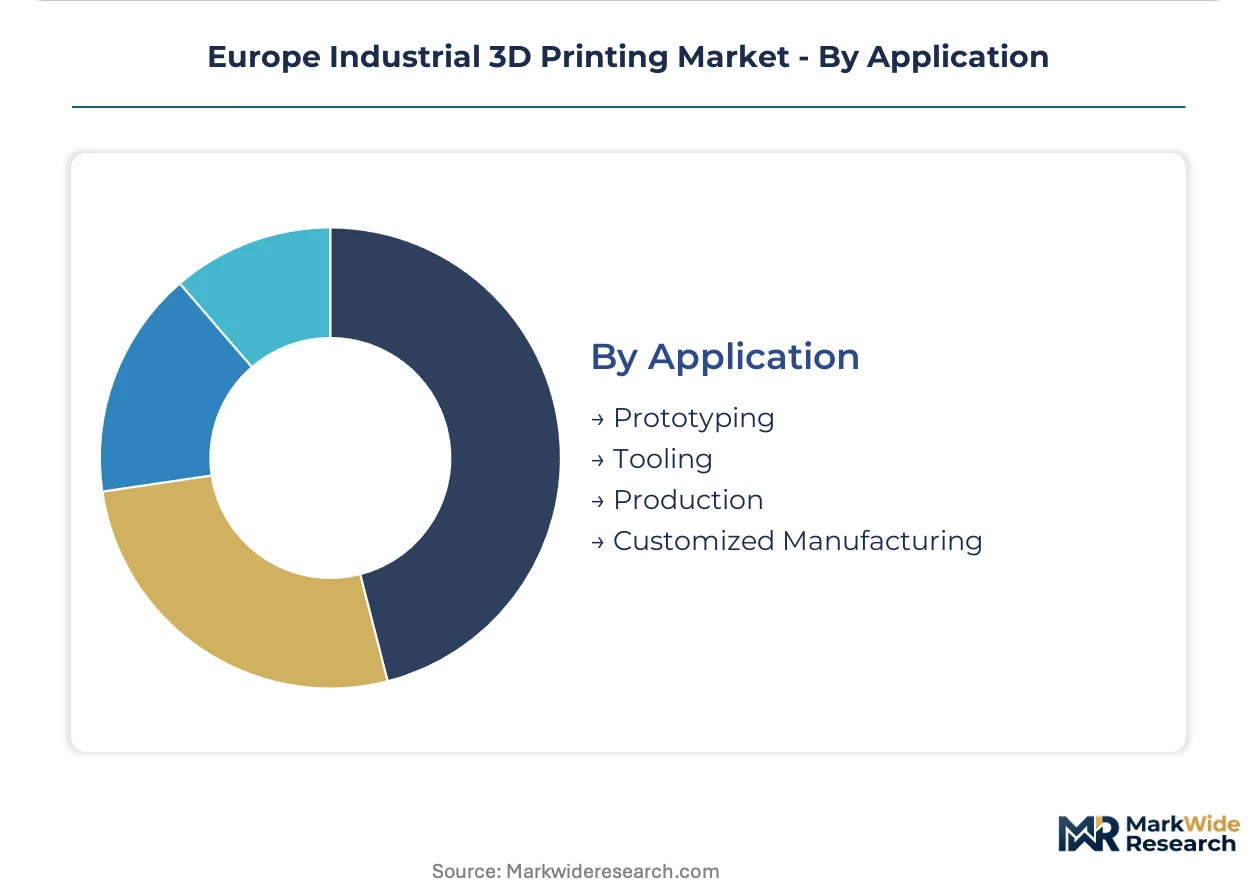
Volume concentration shifts from prototyping—still dominant in job-shop revenue—toward production workflows as automotive and aerospace OEMs integrate additive into serial manufacturing.
- Production:Serial manufacturing of end-use components—titanium brackets, conformal-cooled molds, patient-matched implants—now represents the priority investment category. German automotive OEMs impose 10,000-unit annual volume thresholds for qualified additive suppliers.
- Tooling:Conformal-cooled injection molds and press brake dies reduce cycle times 15-40% versus conventional drilled cooling channels. Stuttgart and Milan moldmakers lead adoption, though surface finish requirements limit polymer systems to prototype tooling.
- Prototyping:Design verification and fit-check models remain the entry-point application across European engineering services firms.
- Customized Manufacturing:Lot-size-one production of patient-matched devices and luxury goods leverages additive's geometric freedom without tooling amortization.
Tooling commands the established revenue base. Production applications climb the fastest as qualification timelines compress and per-part economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's industrial additive manufacturing trade flows reflect a net exporter position in high-value metal powder systems, with Germany and France shipping precision equipment to aerospace clusters in North America and Asia while importing specialized polymer feedstocks from Benelux chemical suppliers.
Germany
BMW and Mercedes-Benz toolrooms in Munich and Stuttgart anchor demand for conformal-cooled injection molds and titanium assembly fixtures. REACH compliance mandates from ECHA are accelerating shifts toward recyclable PA12 powder streams in automotive tier-one contracts. The Baden-Württemberg industrial belt concentrates the continent's densest additive manufacturing supplier ecosystem.
France
Airbus suppliers in Toulouse and Nantes qualify wire-arc directed energy deposition for titanium wing ribs and engine pylons. ANSM's streamlined qualification pathway for patient-specific cranial implants is expanding hospital-based point-of-care manufacturing across Paris and Lyon medical clusters. Safran engine component suppliers are locking in 18-36 month EASA Part 21G certification cycles.
Italy
Turin and Modena automotive suppliers show additive adoption rates 40% below German counterparts, presenting first-mover positioning for production-grade polymer systems in press brake tooling. The EU Green Deal's embodied carbon procurement mandates are redirecting Ferrari and Lamborghini suppliers toward near-net-shape methods. Milan moldmakers lead conformal cooling adoption for luxury automotive trim production.
United Kingdom
Renishaw's Gloucestershire operations anchor precision metrology integration with metal powder-bed systems for aerospace and orthopedic OEMs. The Medicines and Healthcare products Regulatory Agency's post-Brexit device registration requirements are extending technical file timelines for patient-matched implants. Bristol and Oxford engineering clusters concentrate medical device additive development.
Belgium and Netherlands
Materialise-driven distributed production networks span hospital print hubs for craniomaxillofacial and orthopedic cases across Benelux and into Swiss Alpine corridors. Cross-border regulatory harmonization under EMA MDR enables seamless device distribution between Leuven, Eindhoven, and Zurich medical centers. Dutch chemical suppliers are scaling REACH-compliant recycled powder streams for German automotive procurement.
Europe Industrial 3D Printing Market Competitive Landscape
Concentration sits with German laser system specialists and Belgian software-driven production networks, creating a bifurcated structure where hardware margins pool with powder-bed fabricators and service revenues concentrate with distributed manufacturing platforms. Strategic archetypes include precision metal system builders, polymer platform generalists, and hospital-integrated point-of-care operators. Competitive moves center on EASA qualification lock-in for aerospace contracts and CSRD-compliant supply chain certification for automotive tier-one relationships.
Among German precision fabricators, EOS GmbH and SLM Solutions Group AG exemplify the laser powder-bed fusion archetype, with the former representing high-tolerance aerospace system supply and the latter anchoring nickel superalloy turbine blade specialization. Materialise NV occupies a distinct position as a Belgium-based software-controlled production network, demonstrating the hospital-integrated service model across Benelux medical device clusters. These three entities illustrate how competitive positioning splits between capital equipment dominance and distributed manufacturing scale.
| Leading Market Players |
|---|
| Materialise NV |
| SLM Solutions Group AG |
| EOS GmbH |
| Stratasys Ltd. |
| 3D Systems Corporation |
| Renishaw plc |
| Trumpf GmbH + Co. |
| Ultimaker |
| Arcam AB |
| Others |
Pricing and Supply Chain Analysis
EASA Part 21G production organization approvals gate both supplier qualification and price differentiation simultaneously, compressing qualified vendor lists to German and French powder atomizers while allowing certified suppliers to command 3-5x premiums over uncertified competitors for flight-critical titanium builds.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to EASA-recognized quality systems and lot-level chemical certification for aerospace Ti-6Al-4V, while standard tiers serve automotive tooling with traceable but non-flight-grade specifications. Cost compression in economy polymer feedstocks intensifies as REACH-compliant recycled PA12 streams displace virgin powder. Tier-one automotive procurement teams show highest price sensitivity, whereas orthopedic OEMs accept premium positioning for implant-grade nickel superalloys.
Supply Chain Analysis
Strategic stockpiling of argon and nitrogen dominates inventory strategy given Eastern European supply concentration and input cost volatility. Metal powder production draws from Germany, France, and Belgium, with titanium sponge feedstock anchored in Ukrainian and Russian extraction prior to processing. Single-source vulnerability runs through inert gas dependencies for laser powder-bed fusion builds. Distribution runs through direct OEM contracts for aerospace qualification and Materialise-managed hospital networks for medical device clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as CSRD sustainability disclosure rules force automotive tier-one suppliers to requalify around closed-loop powder recovery and renewable-energy-powered build floors.
For Market Incumbents: Compound EASA qualification lock-in through selective laser melting system upgrades for nickel superalloy turbine blades, while deepening backward integration into closed-loop titanium powder recycling to defend margin position against emerging wire-arc directed energy deposition challengers in large-structure aerospace segments. For New Entrants and Emerging Players: Differentiate on point-of-care manufacturing software integration for hospital print hubs in Italy's underpenetrated automotive belt, targeting Turin and Modena press brake tooling applications with production-grade FDM systems and CSRD-compliant carbon accounting bundles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision metrology integrators holding Renishaw-class hardware-software bundles. Five-to-ten year viability hinges on consolidation of hospital-integrated production networks and AI-driven build optimization platforms. Watch for inflection when AI-enabled real-time melt pool monitoring crosses 50% adoption in German aerospace supplier qualifications.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD-Compliant Supply Chain Certification | Automotive tier-one contracts now require documented Scope 3 emissions from powder through finished component. |
| Closed-Loop Powder Recovery Investment | German chemical suppliers scale REACH-compliant recycled PA12 streams for BMW and Mercedes-Benz procurement. |
| EASA Part 21G Production Organization Approval | Airbus and Safran suppliers in Hamburg and Nantes lock in 18-36 month certification barriers for competitors. |
| AI-Driven Build Optimization Platform | Machine learning convergence with melt pool monitoring decomposes parameter development from months to days. |
| Point-of-Care Manufacturing Network Expansion | Materialise-driven hub-and-spoke configurations displace centralized production across Benelux medical corridors. |
Research Methodology
Operator-level perspectives from additive manufacturing engineers, aerospace procurement managers, hospital biomedical engineers, and EASA certification specialists anchored the qualitative base. Primary interviews combined with secondary validation from EMA MDR filings, EASA production organization approvals, customs trade data for metal powder flows, and SEC disclosures from listed equipment vendors. Bottom-up segment sizing triangulated against top-down industrial production indices.
Sensitivity analysis tested forecast robustness across argon price volatility scenarios, EASA certification timeline compression, and CSRD compliance cost pass-through assumptions. Segmentation dimensions modeled include product type, material grade tier, end-use industry, and regional regulatory cluster. CAGRs derived from installed base growth rates, utilization intensity curves, and per-system revenue productivity across the projection horizon. Industry-specific inputs incorporated powder-bed fusion system shipment data and hospital print hub expansion trajectories.
The analysis sits within stated boundaries; outcomes outside sustained aerospace qualification timelines and REACH chemical compliance trajectories would require recalibration. Forecasts reflect documented assumptions regarding EASA certification backlog resolution and automotive tier-one additive adoption thresholds. Revision becomes warranted when wire-arc directed energy deposition adoption in large titanium structures crosses 30% share in Airbus supplier networks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
Global 4D Printing in Healthcare Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
Global 3D Printing in Medical Applications Market