
 United States 3D Printing Market | 2026-2036
United States 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
United States 3D Printing Market Intelligence
A capital-intensity divergence between polymer-focused hardware makers and metal-systems specialists is rotating competitive investment toward industrial-grade platforms. Stratasys leverages its fused deposition installed base to sustain service revenue across education and healthcare channels. General Electric Company anchors metal additive production for aviation turbine components through in-house powder supply control. Carbon differentiates with its digital light processing resin platform, competing for high-throughput dental and consumer applications.
3D printing encompasses additive manufacturing processes that build objects through sequential material deposition or fusion, typically achieving layer resolutions between 25 and 100 microns depending on the specific technology. The primary industrial purpose is to convert digital CAD files directly into physical geometries, eliminating traditional tooling for prototypes, end-use components, and customized medical devices. Fused deposition modeling occupies the largest installed base across education and prototyping environments, while selective laser sintering commands premium positioning in aerospace and automotive functional testing. Medical implants represent the fastest-growing application segment as FDA 510(k) pathways mature for patient-specific titanium and cobalt-chrome constructs.
FDA device regulations, NIST additive manufacturing standards, and ITAR export controls shape product qualification requirements and market access for defense-relevant systems. OSHA powder handling guidelines and EPA volatile organic compound emissions frameworks further constrain facility design and material choices for resin-based operations. Stakeholders must monitor evolving FAA airworthiness certification timelines for flight-critical printed components.
Market Dynamics
Metal additive systems are compressing production timelines for aerospace and defense contractors while FDA 510(k) pathway maturation accelerates patient-specific implant commercialization across orthopedic and dental verticals.
Growth Catalysts
- IRA clean manufacturing incentives:Domestic production tax credits for energy-efficient additive systems are lowering effective equipment costs for Midwest automotive suppliers retooling for electric vehicle platforms.
- Titanium powder supply localization:Nevada and Pennsylvania powder production facilities are reducing lead times for Great Lakes medical device manufacturers qualifying implant-grade materials.
- Selective laser melting:Layer-resolution improvements below 50 microns are expanding flight-critical component applications beyond prototyping into serial production for Southwest defense primes.
Market Restraints
- Nickel and cobalt price volatility:Superalloy feedstock cost swings above 30% annually are destabilizing quoted pricing for aerospace turbine blade contracts.
- Equipment supplier concentration:German and Japanese machine tool dominance creates single-source vulnerability for US metal-system procurement teams.
- Post-processing bottleneck:Required hot isostatic pressing and CNC finishing steps extend total cycle times, limiting throughput scaling for high-volume automotive applications.
Strategic Opportunities
- Texas Gulf Coast petrochemical corridor:Underutilized industrial infrastructure offers brownfield conversion potential for large-format polymer additive facilities serving energy sector tooling demand.
- FAA airworthiness certification streamlining:Emerging delegated authority frameworks for printed non-critical brackets and ducts are compressing qualification timelines from 18 months to sub-6-month cycles.
- AI-driven topology optimization convergence:Generative design software integration with direct metal laser sintering is enabling lattice structures impossible through conventional machining.
Industry Challenges
- Certified welding engineer scarcity:Metal additive operations require specialized metallurgical expertise absent from standard manufacturing training pipelines, constraining facility expansion in Arizona and New Mexico defense clusters.
- Legacy ERP integration friction:Shop-floor data from polymer and metal systems lacks standardized protocols, forcing custom middleware development for production planning synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States 3D Printing Market |
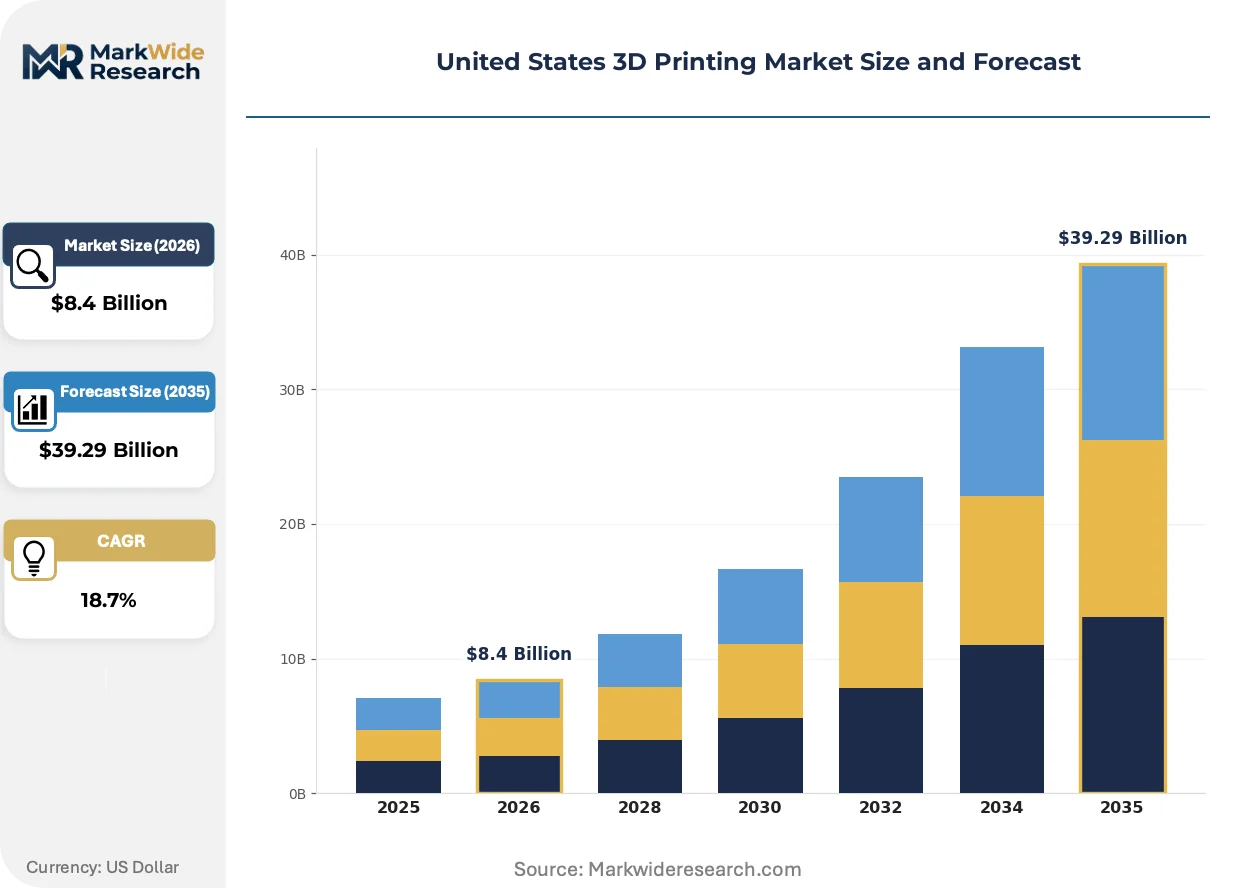
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing Application: Aerospace Components, Medical Implants, Automotive Prototyping, Consumer Goods Material: PLA, ABS, Nylon, Resin End User: Aerospace, Healthcare, Automotive, Education |
| Companies Covered | Stratasys, 3D Systems, HP, General Electric Company, Carbon, Protolabs, Markforged, EnvisionTEC, Nano Dimension, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States 3D Printing Market Strategic Shifts & Innovations
Process monitoring systems and real-time quality assurance tools are embedding predictive capabilities directly into production workflows, shifting competitive advantage from equipment ownership to operational intelligence.
Continuous liquid interface production is decomposing traditional batch-based resin manufacturing by enabling metered polymerization without layer-wise interruption. Dental aligner manufacturers in California are adopting these systems at 40% annual capacity expansion rates. The technology is decomposing inventory holding requirements for customized orthodontic devices from weeks to same-day production cycles.
FDA's evolving guidance on patient-matched device submissions is compressing premarket notification preparation timelines for titanium cranial implants. The agency's 2023 additive manufacturing working group recommendations are standardizing mechanical testing protocols. Medical device innovators in Massachusetts and Minnesota are restructuring regulatory affairs functions to align with the new predicate device pathways.
Consolidated procurement consortia among Midwest hospital systems are aggregating orthopedic implant demand into multi-year additive manufacturing supply agreements. Traditional distributor markups are compressing as direct manufacturer relationships displace intermediary inventory holding. The shift is most visible in Michigan and Ohio, where integrated delivery networks now specify printed implant sourcing in capital equipment RFPs.
United States 3D Printing Market Segmentation
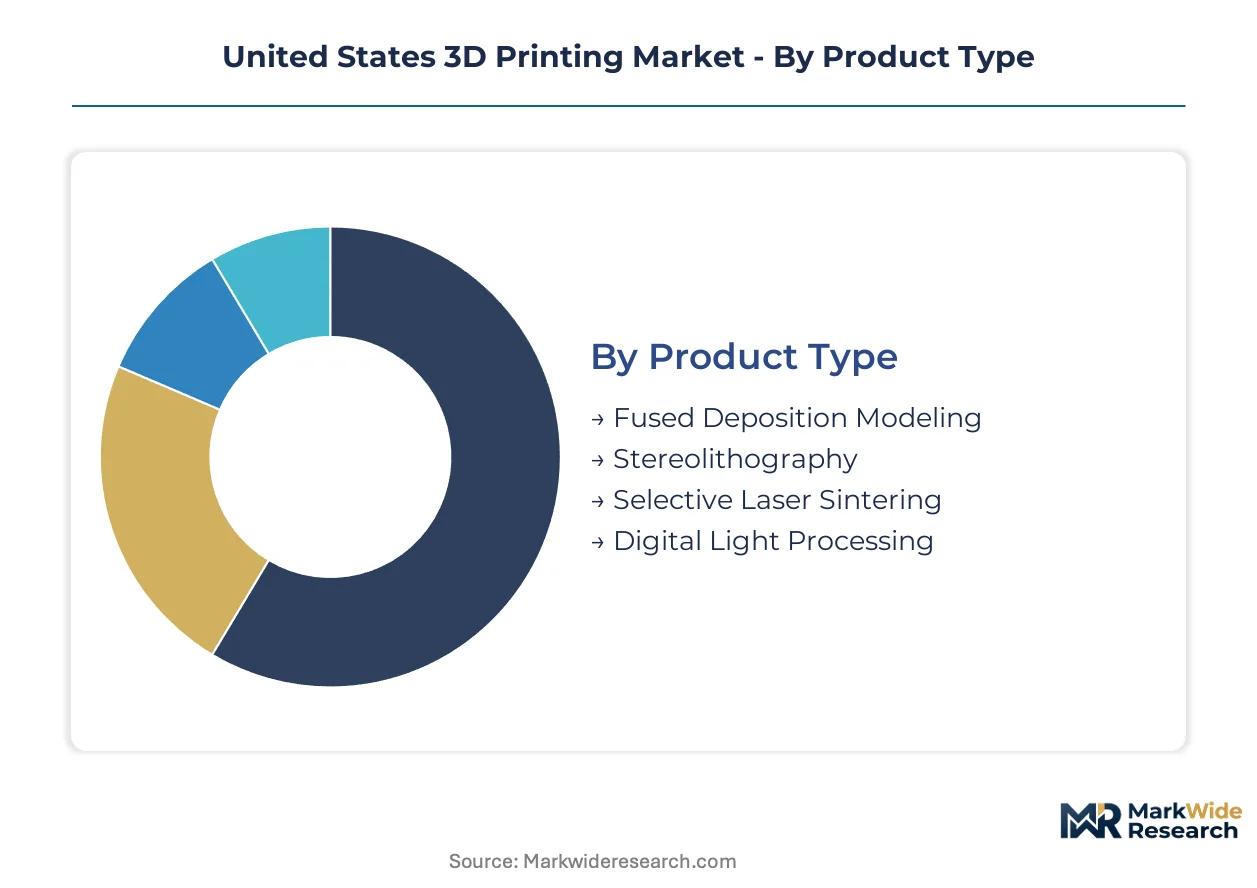
Technology-platform choices in additive manufacturing lock end-users into distinct capital cycles, material supply chains, and post-processing requirements. Segment boundaries increasingly blur as hybrid systems emerge, yet procurement decisions still cluster around historical technology-class preferences shaped by installed base inertia.
Product Type:
Domestic demand concentrates in polymer-based systems for prototyping and education, while export-competitive aerospace and defense contracts drive metal-system procurement from German and Japanese suppliers.
- Fused Deposition Modeling:Thermoplastic filament extrusion through heated nozzles builds parts layer-by-layer with equipment costs accessible to secondary education budgets. Demand clusters in Texas and California school districts modernizing vocational training labs, constrained by ABS warping challenges in uncontrolled environments. The installed base commands the established foundation. The steepest expansion trajectory runs through Selective Laser Sintering.
- Selective Laser Sintering:CO2 laser fusion of polymer or metal powders achieves isotropic mechanical properties unattainable through filament deposition. Great Lakes automotive suppliers and Southwest defense primes are qualifying flight-critical brackets and ducting through FAA delegated authority frameworks, compressing airworthiness timelines from 18 months toward 6-month cycles.
- Stereolithography:UV laser polymerization of liquid resin delivers surface finishes suitable for investment casting patterns and dental mold masters.
- Digital Light Processing:Projected light engines cure entire layers simultaneously, enabling California dental aligner manufacturers to expand capacity at 40% annual rates.
Fused Deposition Modeling retains the broadest installed footprint. The most rapid capability advancement is concentrating in Selective Laser Sintering.
Application:
Cost-tier stratification separates prototype validation from serial production, with regulatory qualification requirements creating steep margin cliffs between segments.
- Aerospace Components:Titanium and nickel superalloy turbine blades, structural brackets, and fuel nozzles demand hot isostatic pressing and CNC finishing that extends total cycle times. Southwest defense manufacturing clusters in Arizona and New Mexico face certified welding engineer scarcity, constraining facility expansion despite IRA clean manufacturing incentives lowering effective equipment costs.
- Medical Implants:Patient-specific titanium cranial plates and cobalt-chrome orthopedic constructs qualify through FDA 510(k) pathways maturing under 2023 additive manufacturing working group recommendations. Massachusetts and Minnesota device innovators are restructuring regulatory affairs functions to align with standardized mechanical testing protocols, compressing premarket notification preparation timelines.
- Automotive Prototyping:Functional testing of interior trim and under-hood components dominates Great Lakes corridor demand from Detroit-area OEM design centers.
- Consumer Goods:Customized eyewear frames and jewelry applications remain fragmented across boutique production networks with limited scale economics.
Automotive Prototyping holds the deepest historical penetration. The most rapid demand acceleration is occurring in Medical Implants.
Material:
Supply concentration in petrochemical feedstocks versus powder metallurgy creates divergent procurement risk profiles across user segments.
- PLA:Corn-starch-derived biopolymer dominates education and consumer desktop printing with low-temperature processing requirements and minimal fume extraction needs. Midwest school districts specify PLA-only systems to comply with OSHA powder handling guidelines that constrain resin-based operations.
- ABS:Petroleum-based terpolymer delivers higher temperature resistance for functional prototyping, though warping sensitivity demands heated build chambers that elevate equipment costs.
- Nylon:Polyamide powders for Selective Laser Sintering achieve wear resistance for hinge mechanisms and snap-fit assemblies in automotive functional testing.
- Resin:Photopolymer formulations span standard prototyping grades through FDA-cleared biocompatible clear aligner materials, with EPA volatile organic compound emissions frameworks constraining facility ventilation design.
PLA sustains the highest shipment volumes. The most rapid formulation innovation is advancing in Resin.
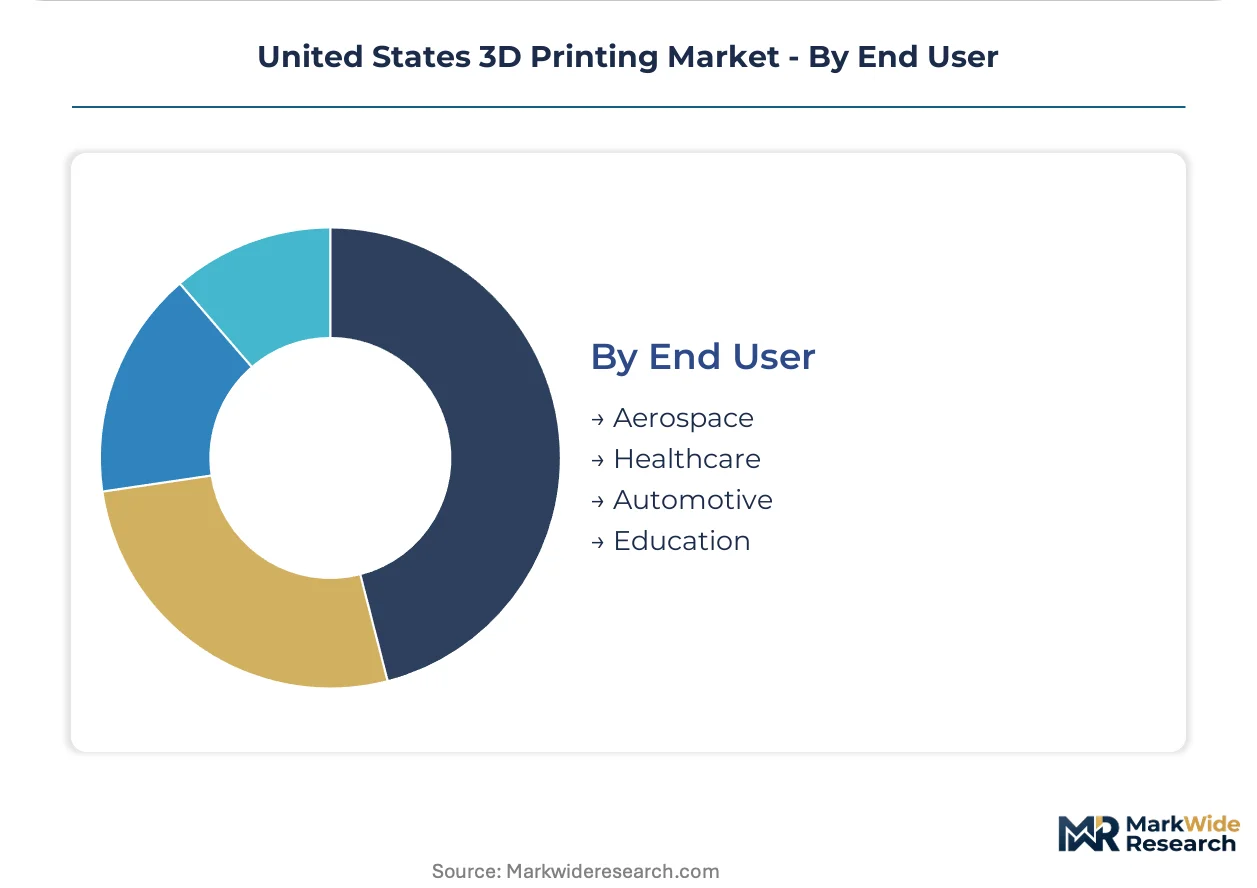
End User:
Customer-type maturity separates specification-driven industrial procurement from budget-constrained institutional purchasing with divergent vendor relationship models.
- Aerospace:Prime contractors and tier-one suppliers operate captive additive centers with in-house powder supply control, as General Electric Company anchors metal additive production for aviation turbine components. ITAR export controls shape product qualification requirements and market access for defense-relevant systems.
- Healthcare:Hospital systems and device manufacturers are consolidating procurement through integrated delivery networks that specify printed implant sourcing in capital equipment RFPs, displacing traditional distributor markups in Michigan and Ohio.
- Automotive:OEM design centers and tier suppliers balance polymer prototyping against metal additive for electric vehicle platform retooling.
- Education:Secondary and post-secondary institutions prioritize equipment reliability and curriculum alignment over production throughput metrics.
Education represents the most dispersed customer base. The tightest supply integration is developing in Aerospace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California commands premium pricing for metal additive aerospace contracts while Texas polymer prototyping clusters compete on throughput volume. This regional asymmetry concentrates high-margin defense work on the West Coast and commoditized service bureau capacity in the Southwest.
Texas
Gulf Coast petrochemical infrastructure and underutilized brownfield industrial sites attract large-format polymer additive facilities targeting energy sector tooling demand. IRA clean manufacturing incentives lower effective equipment costs for suppliers retooling for electric vehicle platforms. Houston-area service bureaus expand filament deposition capacity to capture automotive prototyping contracts from Austin and Dallas-Fort Worth design centers.
California
Dental aligner manufacturers in the Bay Area and Los Angeles basin adopt continuous liquid interface production systems at accelerated capacity expansion rates. EPA volatile organic compound emissions frameworks constrain resin-based facility ventilation design in coastal counties. San Diego defense primes qualify flight-critical titanium brackets through FAA delegated authority frameworks, compressing airworthiness timelines toward six-month cycles.
Michigan
Detroit-area OEM design centers drive Great Lakes demand for nylon powder selective laser sintering in functional automotive testing. OSHA powder handling guidelines shape facility compliance costs for medical device manufacturers qualifying implant-grade materials. Grand Rapids orthopedic implant suppliers consolidate procurement through integrated delivery networks that specify printed sourcing in capital equipment RFPs.
Arizona
Southwest defense manufacturing clusters face certified welding engineer scarcity that constrains metal additive facility expansion despite strong contract flow. ITAR export controls shape product qualification requirements and market access for defense-relevant systems. Tucson and Phoenix-area primes anchor captive additive centers with in-house titanium powder supply control for aviation turbine components.
Massachusetts
Medical device innovators restructure regulatory affairs functions to align with FDA 510(k) pathway maturation for patient-specific implants. The agency's additive manufacturing working group recommendations standardize mechanical testing protocols for titanium cranial plates. Boston-area firms compress premarket notification preparation timelines while Minnesota counterparts pursue parallel predicate device strategies.
United States 3D Printing Market Key Industry Players
Concentration sits with diversified industrial conglomerates and specialized additive pure-plays competing across distinct technology-platform silos. The vendor landscape segments into three strategic archetypes: polymer-system incumbents with education-channel installed bases, metal-additive specialists with aerospace certification depth, and resin-platform innovators targeting high-throughput dental applications. Competitive moves cluster around strategic partnerships for powder supply security and portfolio diversification into adjacent post-processing capabilities.
Among established additive specialists, Stratasys and 3D Systems represent the polymer-system incumbent archetype with broad installed bases across institutional channels. General Electric Company anchors the metal-additive tier through aviation-focused production integration. Carbon occupies a distinct position within resin-platform innovation for dental and consumer applications. These three exemplify how technology-platform choices lock competitive positioning into divergent capital cycles and customer relationship models.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| HP |
| General Electric Company |
| Carbon |
| Protolabs |
| Markforged |
| EnvisionTEC |
| Nano Dimension |
| Others |
Cost & Logistics Intelligence
FAA airworthiness certification requirements gate both supplier qualification and price differentiation in aerospace additive manufacturing, compressing procurement timelines for flight-critical components while elevating configured-to-order premiums for patient-specific medical implants. This regulatory architecture simultaneously constrains supply base expansion and stratifies pricing power across certification tiers.
Pricing Analysis
Configured-to-order pricing for patient-specific titanium cranial implants commands substantial premiums over standard orthopedic constructs, with FDA 510(k) pathway maturation compressing premarket timelines and intensifying competition at the premium tier. Price differentiation hinges on certification grade and volume scale, with hospital system procurement consortia in Michigan and Ohio extracting volume discounts that displace traditional distributor markups. Cost compression in polymer prototyping runs through Texas service bureau capacity expansion, while aerospace metal additive retains pricing resilience due to welding engineer scarcity constraining qualified supplier expansion.
Supply Chain Analysis
Titanium powder supply localization through Nevada and Pennsylvania production facilities anchors feedstock security for Great Lakes medical device manufacturers, though German and Japanese machine tool dominance creates single-source vulnerability for metal-system procurement teams. Raw material dependencies span nickel superalloys, cobalt-chrome powders, and photopolymer resins, with nickel and cobalt price volatility above thirty percent annually destabilizing aerospace turbine blade contract pricing. Tariff exposure on imported machine tools amplifies equipment procurement risk, while distribution runs through direct manufacturer relationships with integrated delivery networks displacing traditional inventory-holding intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates substantial switching costs for qualified suppliers, with FDA certification depth and FAA delegated authority frameworks locking end-users into established vendor relationships.
For Market Incumbents: Fortify powder supply security through captive production or long-term offtake agreements with Nevada and Pennsylvania facilities, while deepening post-processing capabilities to capture value from hot isostatic pressing and CNC finishing bottlenecks. Emerging resin-platform specialists threaten polymer prototyping margins in Texas and California education channels, making channel control through curriculum-integrated training programs a critical defensive lever. For New Entrants and Emerging Players: Post-processing service gaps where incumbents under-serve present immediate white-space targets, particularly hot isostatic pressing capacity constrained in Southwest defense clusters. Arizona and New Mexico metal additive operations face certified welding engineer scarcity that constrains facility expansion, creating penetrable geography for specialized metallurgical workforce providers. A direct go-to-market angle through FDA regulatory consulting bundled with equipment procurement addresses Massachusetts and Minnesota device innovators restructuring compliance functions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across metal additive platforms as powder supply localization and post-processing integration demands escalate, favoring scaled incumbents over capital-constrained specialists. Acquisition targets should display captive powder supply relationships or FAA delegated authority certification depth that compresses airworthiness timelines. The signal to watch is IRA clean manufacturing incentive utilization rates, which indicate effective equipment cost positioning for Midwest automotive supplier retooling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Production | Nevada and Pennsylvania titanium facilities reduce lead times for implant-grade material qualification. |
| FAA Delegated Authority Certification | San Diego defense primes compress airworthiness timelines from eighteen months toward six-month cycles. |
| Post-Processing Capability Expansion | Hot isostatic pressing and CNC finishing integration captures value from cycle time bottlenecks. |
| Hospital System Procurement Consortium | Michigan and Ohio integrated delivery networks displace distributor markups through direct sourcing. |
| Continuous Liquid Interface Production Deployment | California dental aligner manufacturers expand capacity at accelerated rates without layer-wise interruption. |
Research Approach
Operator-level perspectives from additive manufacturing plant managers, biomedical engineers at hospital purchasing committees, aerospace procurement leads, and FDA regulatory affairs specialists anchored the qualitative base. Primary interview insights combined with secondary validation from FAA airworthiness certification databases, FDA 510(k) submission records, SEC equipment manufacturer filings, and OSHA powder handling guideline documentation. Bottom-up demand modeling across technology platforms, applications, and end-user segments triangulated against top-down market sizing from capital equipment shipment data and service bureau capacity expansion rates.
Sensitivity analysis framing informed the analytical approach across the projection horizon, with segmentation dimensions spanning technology platform, material grade tier, application vertical, and regional manufacturing cluster. CAGRs derived from equipment replacement cycles, regulatory pathway maturation timelines, and end-user adoption curve positioning. Industry-specific forecast inputs incorporated IRA clean manufacturing incentive utilization patterns and titanium powder supply localization trajectories.
Underlying assumptions cover stable FAA delegated authority expansion and continued FDA additive manufacturing working group protocol standardization, with deviation risk concentrated in nickel and cobalt superalloy feedstock price volatility and certified welding engineer pipeline constraints. Practitioners should keep alternative scenarios live as ITAR export control enforcement intensity and EPA volatile organic compound emissions framework evolution reshape facility compliance costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
Global 3D Printed Electronics Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
3D Printing Pellet Extruder Market