
 Military 3D Printing Market | 2026-2036
Military 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Military 3D Printing Market Outlook
Spare parts fabrication on demand is rewriting profit distribution across the military aftermarket. EOS GmbH anchors European defense supply chains through certified metal powder-bed systems for flight-critical aerospace brackets. Stratasys Ltd. dominates polymer-based field repair stations with ruggedized FDM platforms deployed at forward operating bases. Materialise NV specializes in software-controlled build preparation that sustains repeatability across distributed manufacturing networks.
Military 3D printing encompasses additive manufacturing processes producing metallic and polymer structures layer-by-layer from digital models, typically achieving tolerances of ±0.1 mm in direct metal laser sintering for titanium and Inconel alloys used in weapons systems and airframe brackets. Its primary purpose centers on eliminating traditional tooling lead times while enabling geometrically complex components impossible through subtractive machining. Electron beam melting leads in high-strength titanium aerospace applications where porosity control determines fatigue life certification. Fused deposition modeling occupies the broadest installed base across expeditionary maintenance units due to minimal facility requirements and polymer feedstock versatility. Selective laser sintering captures expanding share in precision naval tooling where nylon 12 composites replace aluminum fixtures.
US DoD acquisition directives and NATO STANAG standards shape certification pathways for flight-worthy printed components, while the US FAA and military airworthiness boards enforce material traceability requirements that filter supplier eligibility. The EU's Cyber Resilience Act and emerging defense procurement frameworks are tightening digital thread security for battlefield file transmission. Stakeholders must weigh in-house qualification investment against qualified supplier partnerships as regulatory divergence between US MIL-STD and European defense agency protocols complicates cross-border platform deployment.
Market Dynamics
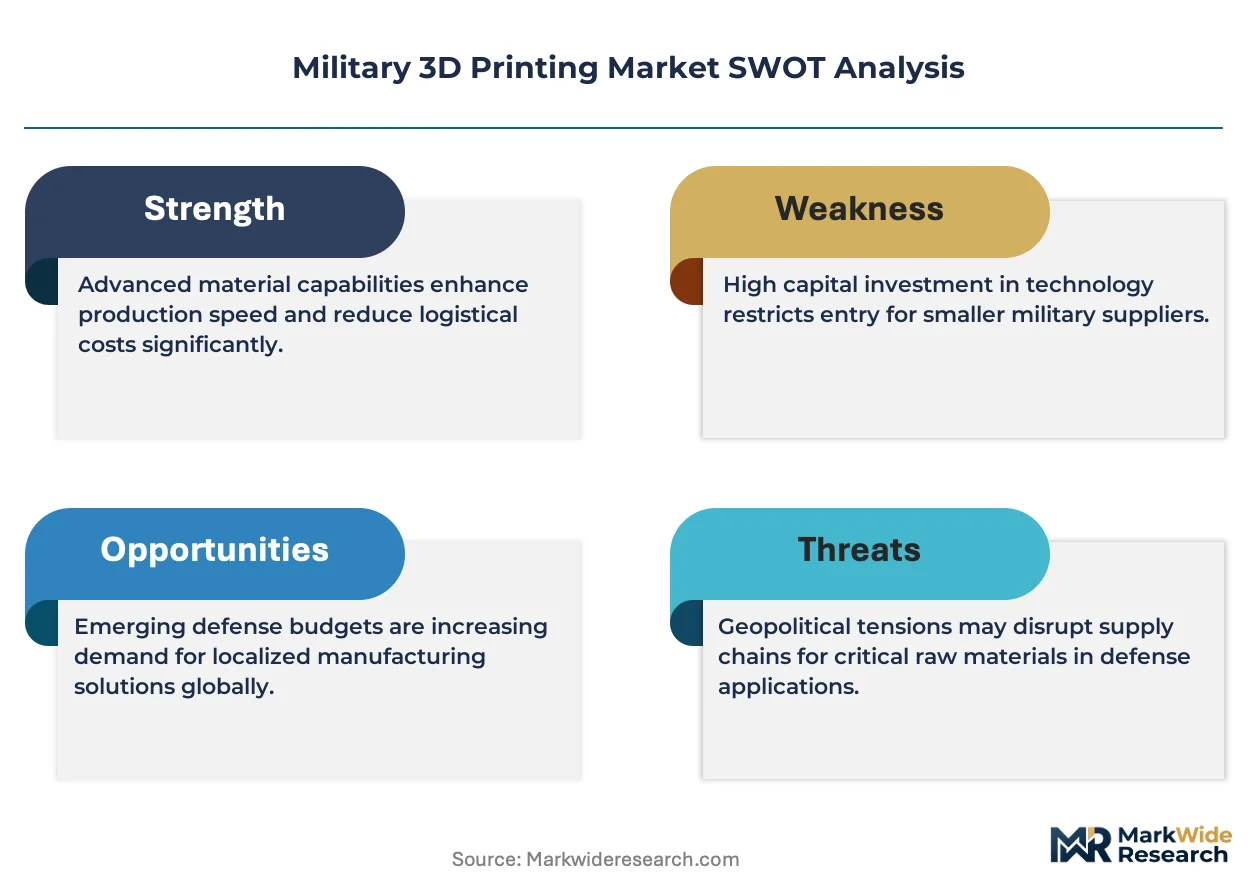
Supply chain resilience mandates from the US DoD are compressing qualification timelines for metal additive manufacturing, forcing defense contractors to choose between in-house certification investment and qualified supplier partnerships.
Growth Catalysts
- Executive Directive 14017:US federal supply chain resilience orders compel military maintenance depots to qualify on-demand spare part production, accelerating certified metal printing protocol adoption across army and naval facilities.
- Expeditionary Logistics:Forward operating bases deploy ruggedized polymer deposition systems for same-day component repair, eliminating airlift dependency for non-critical brackets and housings.
- NATO STANAG Harmonization:Standardization agreements for additive manufacturing quality assurance enable cross-border platform support, allowing German powder-bed systems to supply Dutch and Belgian airframe maintenance networks.
Market Restraints
- Titanium Powder Supply Concentration:Plasma atomization capacity for aerospace-grade Ti-6Al-4V feedstock clusters with three specialty chemical suppliers, exposing defense programs to price volatility and allocation risk.
- MIL-STD Qualification Burden:US military material traceability requirements for flight-critical components impose 18-24 month certification timelines that freeze supplier entry and favor incumbent qualified vendors.
- Porosity Control Limitations:Electron beam melting struggles with consistent void elimination in thick-section Inconel turbine brackets, restricting application to non-rotating hardware despite superior mechanical properties.
Strategic Opportunities
- Underpenetrated Naval Shipyards:US Pacific Fleet maintenance facilities lack qualified metal printing capacity for submarine hull fittings, creating first-mover advantage for contractors establishing localized deposition centers.
- Cyber-Physical Convergence:Blockchain-secured digital thread integration with battlefield file transmission protocols addresses EU Cyber Resilience Act requirements while enabling distributed manufacturing network integrity.
- Selective Laser Sintering Tooling:Nylon 12 composite fixtures replace machined aluminum equivalents in precision naval assembly jigs, cutting lead times from weeks to hours for one-off configurations.
Industry Challenges
- Non-Destructive Evaluation Talent Scarcity:Qualified ultrasonic and computed tomography technicians capable of certifying printed aerospace brackets remain concentrated with prime contractors, constraining depot capacity expansion.
- Legacy ERP Integration Friction:Defense maintenance software systems built for subtractive manufacturing part numbering struggle to accommodate variable-geometry additive files, requiring expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military 3D Printing Market |
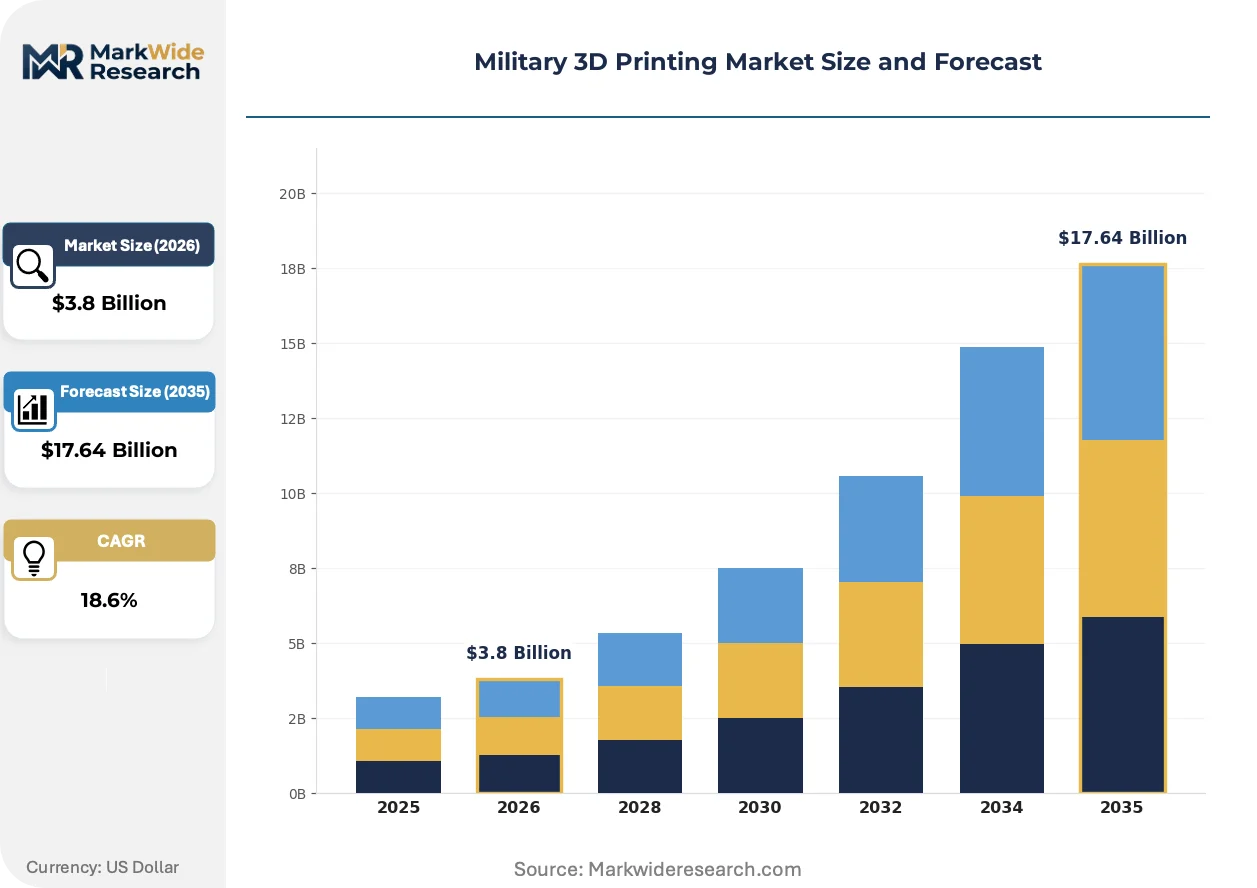
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prototyping, Spare Parts, Tools, Components Technology: Fused Deposition Modeling, Selective Laser Sintering, Stereolithography, Electron Beam Melting End User: Army, Navy, Air Force, Defense Contractors Application: Equipment Maintenance, Field Deployments, Training Simulations, Rapid Prototyping |
| Companies Covered | Stratasys Ltd., 3D Systems Corporation, EOS GmbH, GE Additive, Markforged Inc., Renishaw plc, Materialise NV, Desktop Metal Inc., SPEE3D, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military 3D Printing Market Strategic Shifts
Digital thread architecture is collapsing the boundary between design authority and production execution, enabling real-time design modifications to propagate directly to battlefield manufacturing nodes without traditional engineering release cycles.
Multi-laser powder-bed fusion is digitizing titanium aerospace bracket production by enabling parallel processing of large-format components. Naval aviation maintenance units adopt these systems to compress depot repair cycles from months to days. The technology is digitizing inventory economics by eliminating minimum order quantities and tooling amortization from spare part cost structures.
EU Cyber Resilience Act implementation is mandating encrypted file transmission protocols for defense additive manufacturing networks. Equipment suppliers must embed hardware security modules into build preparation software to maintain European defense procurement eligibility. German and French aerospace agencies are accelerating certification of compliant systems ahead of enforcement deadlines.
Maintenance contracts are unbundling hardware ownership from manufacturing capability, with defense agencies purchasing print licenses rather than physical spares. Third-party service providers operate deposition equipment at military facilities under performance-based arrangements. This shift concentrates most visibly in US Army ground vehicle programs, where regional fab-labs assume component production responsibility from traditional supply depots.
Military 3D Printing Market Segmentation
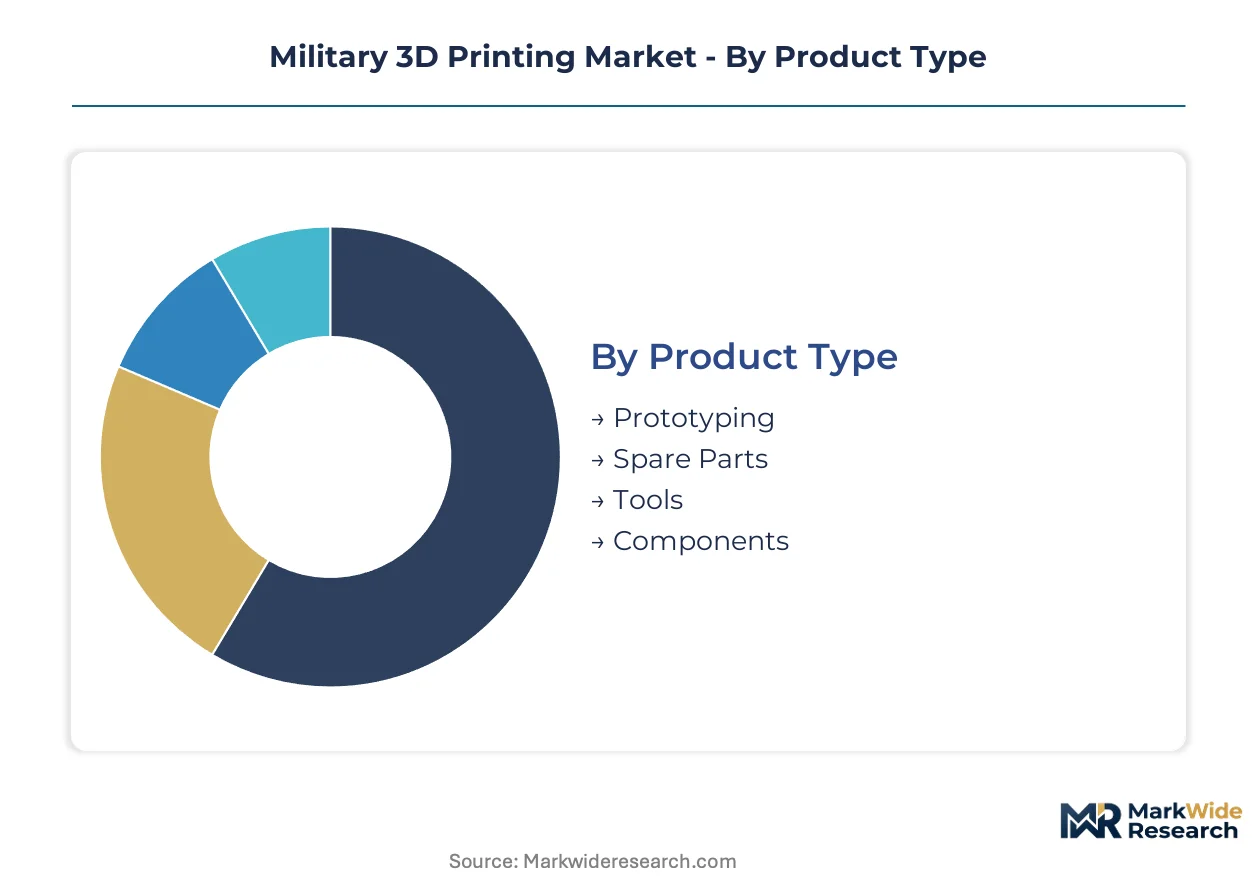
Military 3D printing segments diverge sharply between depot-level precision manufacturing and expeditionary field repair. Each dimension carries distinct certification burdens, facility requirements, and supply chain architectures that determine vendor eligibility and contract profitability.
Product Type:
Use cases span concept validation through operational deployment, with qualification thresholds escalating from non-critical tooling to flight-ready hardware.
- Spare Parts:Digitally stored component files enable on-demand fabrication of brackets, housings, and structural elements without minimum order constraints. US Army maintenance depots and naval shipyards concentrate demand here as supply chain resilience directives compress traditional procurement cycles.
- Prototyping:Rapid iteration of weapon system mock-ups and fit-check models accelerates design validation before cutting production tooling. Air Force research laboratories and defense contractor engineering centers drive consumption where geometric complexity exceeds conventional machining feasibility.
- Tools:Custom jigs, fixtures, and assembly aids replace machined aluminum equivalents in precision naval construction.
- Components:Flight-critical airframe brackets and weapons system hardware require full material traceability and fatigue life certification.
The dominant share belongs to Spare Parts, while Components is closing the gap fastest as certification protocols mature for titanium and Inconel deposition.
Technology:
Process selection hinges on material requirements, geometric complexity, and facility constraints across fixed depots versus forward operating environments.
- Fused Deposition Modeling:Polymer extrusion systems operate with minimal infrastructure, consuming ABS and nylon filaments for non-structural brackets and housings. Expeditionary maintenance units across NATO forward operating bases deploy ruggedized FDM platforms where airlift resupply proves unreliable.
- Electron Beam Melting:Vacuum-based titanium processing achieves superior mechanical properties for aerospace applications demanding fatigue resistance. Naval aviation depots concentrate investment here despite higher capital requirements and powder handling complexity.
- Selective Laser Sintering:Nylon 12 composite processing supports precision tooling and functional prototypes with isotropic mechanical properties.
- Stereolithography:Photopolymer curing delivers finest feature resolution for medical training models and optical component prototypes.
Depot infrastructure favors Electron Beam Melting for structural metalwork, though Fused Deposition Modeling maintains the broadest installed base through expeditionary logistics mandates.
End User:
Service branch procurement patterns reflect platform complexity, maintenance depth, and operational tempo across fixed installations versus deployed forces.
- Army:Ground vehicle maintenance depots and expeditionary fab-labs drive polymer-based field repair adoption. Regional manufacturing networks assume component production responsibility from traditional supply chains under performance-based arrangements.
- Navy:Submarine hull fitting production and carrier air wing maintenance require certified metal deposition capacity. Pacific Fleet facilities show particular supply concentration for localized titanium bracket fabrication.
- Air Force:Flight-critical component certification and aerospace-grade material traceability dominate procurement criteria.
- Defense Contractors:Prime manufacturers integrate additive manufacturing into original equipment production and aftermarket support ecosystems.
Army procurement volumes lead service branch consumption, with Navy investment expanding most quickly through underpenetrated shipyard infrastructure.
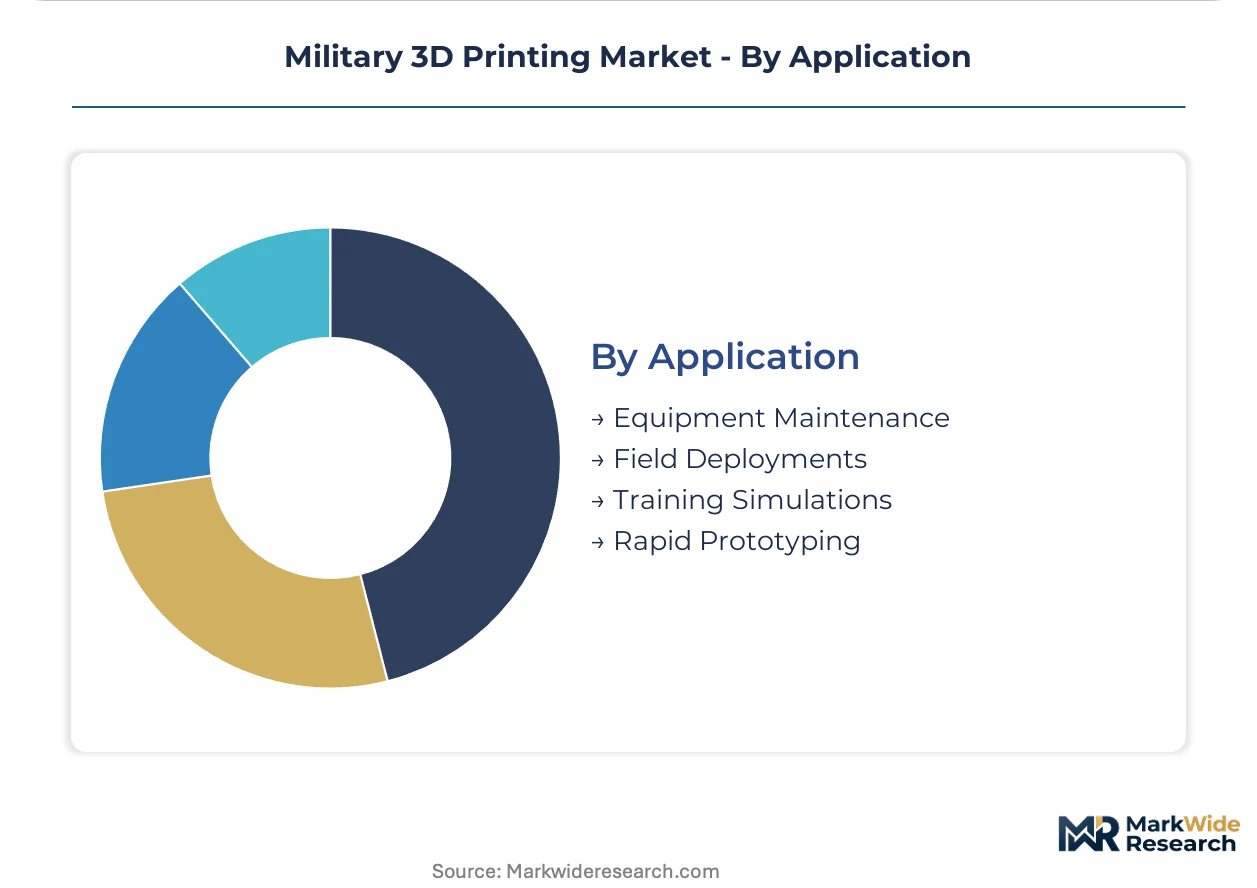
Application:
Operational context determines equipment specification, from climate-controlled depots to austere field conditions with limited power and material resupply.
- Equipment Maintenance:Scheduled and unscheduled repair of weapons platforms, vehicles, and aircraft drives recurring demand for qualified spare production. Organic manufacturing capability eliminates airlift dependency for non-critical components across distributed maintenance networks.
- Field Deployments:Same-day fabrication at forward operating bases addresses supply chain disruption and extended logistics tails. Ruggedized polymer systems operate from containerized facilities with minimal technical support infrastructure.
- Rapid Prototyping:Accelerated design iteration supports concept validation before committing to production tooling investment.
- Training Simulations:Anatomical models and equipment replicas support medical and technical instruction without consuming operational assets.
Equipment Maintenance commands the largest application share, while Field Deployments gains share fastest as expeditionary logistics doctrine embeds additive manufacturing into unit equipment tables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma atomization capacity for aerospace-grade titanium powder clusters with three specialty chemical suppliers, exposing defense programs to price volatility and allocation risk. The United States dominates procurement volumes through Pentagon maintenance depots and naval shipyards. European NATO members are harmonizing certification protocols through STANAG agreements to enable cross-border platform support.
United States
Army maintenance depots and Pacific Fleet naval shipyards drive demand for certified metal deposition systems. Executive Directive 14017 compels military facilities to qualify on-demand spare part production, accelerating adoption of powder-bed fusion protocols. Huntsville's Redstone Arsenal anchors ground vehicle component fabrication networks.
Germany
EOS GmbH anchors European defense supply chains through certified metal powder-bed systems for flight-critical aerospace brackets. The EU Cyber Resilience Act mandates encrypted file transmission protocols, forcing equipment suppliers to embed hardware security modules. Bavaria's aerospace cluster concentrates qualification expertise for NATO platform interoperability.
United Kingdom
Royal Air Force maintenance units and BAE Systems integration facilities consume precision naval tooling and aerospace-grade titanium brackets. Military airworthiness boards enforce material traceability requirements that filter supplier eligibility. The Midlands defense manufacturing corridor hosts electron beam melting capacity for fatigue-critical components.
Japan
Ministry of Defense procurement emphasizes supply chain resilience for maritime patrol aircraft and submarine hull fittings. METI standards guide additive manufacturing quality assurance for dual-use aerospace applications. Nagoya's aerospace cluster integrates multi-laser powder-bed systems for parallel processing of large-format brackets.
Israel
Israel Defense Forces expeditionary units deploy ruggedized polymer deposition systems for field repair of unmanned aerial vehicle components. The national defense procurement framework prioritizes distributed manufacturing network integrity for contested logistics environments. Tel Aviv's defense technology corridor specializes in software-controlled build preparation for rapid deployment scenarios.
Military 3D Printing Market Competitive Environment
Metal powder-bed specialists and polymer deposition platform providers split the market between depot-level precision manufacturing and expeditionary field repair. The vendor base concentrates around certified defense suppliers with established MIL-STD qualification histories. Three archetypes dominate: European precision metal systems houses, US-based ruggedized field equipment fabricators, and software-centric build preparation specialists. Competitive moves center on strategic partnerships with prime defense contractors and geographic expansion into underpenetrated naval shipyard infrastructure.
Within the certified metal systems tier, EOS GmbH and Renishaw plc occupy positions anchored to European aerospace agency qualification protocols. Stratasys Ltd. exemplifies the expeditionary logistics archetype through polymer platform deployment at forward operating bases. These three companies represent the strategic spectrum from precision depot manufacturing to austere field capability.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| 3D Systems Corporation |
| EOS GmbH |
| GE Additive |
| Markforged Inc. |
| Renishaw plc |
| Materialise NV |
| Desktop Metal Inc. |
| SPEE3D |
| Others |
Value Chain & Pricing Dynamics
Plasma atomization capacity for aerospace-grade Ti-6Al-4V titanium powder clusters with three specialty chemical suppliers in the United States, Germany, and Japan, anchoring margin capture at the feedstock tier while defense contractors downstream absorb qualification cost burdens. This upstream concentration forces equipment vendors and depot operators to accept pass-through volatility or pursue multi-year offtake commitments that lock in working capital.
Pricing Analysis
MIL-STD qualification requirements dictate the pricing tier structure across defense additive manufacturing, separating flight-certified metal deposition systems from expeditionary polymer platforms. Three-tier pricing structure across certified-flight, depot-grade, and field-deployable levels reflects material traceability investment and airworthiness board scrutiny. Cost compression in field-deployable tiers is intensifying because ruggedized FDM platforms face commodity polymer filament competition. Army ground vehicle maintenance units exhibit highest price sensitivity due to performance-based contracting, while naval aviation depots accept premium positioning for fatigue-critical titanium brackets.
Supply Chain Analysis
Extended payment terms from prime defense contractors now stretch to 90-120 days, forcing equipment suppliers to draw from supply-chain finance facilities or accept liquidity constraints. Raw material dependencies center on plasma-atomized titanium powder, nylon 12 polymer pellets, and specialty Inconel feedstock sourced from the United States, Germany, and China. Single-source vulnerability concentrates in aerospace-grade powder certification, where alternative atomization routes require 18-month requalification. Distribution runs through prime contractor integration facilities and direct military depot procurement channels, with regional fab-labs emerging as localized demand nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery driven by Pentagon maintenance depot modernization cycles and NATO STANAG harmonization timelines. Defense procurement budgets are rotating toward supply chain resilience after years of consolidation-focused austerity.
For Market Incumbents: Build certification moats around MIL-STD and NATO STANAG flight-critical component pathways before harmonization deadlines compress qualification timelines. Deepen backward integration into plasma atomization capacity to secure titanium powder supply against allocation risk from specialty chemical suppliers. Anchor position through multi-year performance-based maintenance contracts with Army regional fab-labs, displacing traditional supply depot networks. For New Entrants and Emerging Players: Underpenetrated Pacific Fleet naval shipyards represent the most penetrable entry point, lacking qualified metal printing capacity for submarine hull fittings and carrier air wing titanium brackets. Cyber-physical convergence offerings—blockchain-secured digital thread integration—address EU Cyber Resilience Act compliance gaps among European equipment vendors. Partner with software-centric build preparation specialists to bypass capital-intensive hardware manufacturing and capture recurring license revenue from distributed manufacturing networks. For Investors and Strategic Acquirers: Capital is best deployed toward qualified metal powder-bed specialists with established European aerospace agency certifications and incumbent prime contractor relationships. Long-term viability hinges on regulatory divergence between US MIL-STD and European defense agency protocols persisting through the projection horizon, preserving certification barriers. Watch for NATO STANAG enforcement acceleration as the inflection indicator signaling qualification timeline compression and vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment Acceleration | MIL-STD and NATO STANAG qualification timelines compress supplier eligibility to incumbent vendors with established airworthiness board relationships. |
| Backward Integration into Feedstock | Plasma atomization capacity acquisition secures titanium powder supply against price volatility from three dominant specialty chemical suppliers. |
| Digital Thread Security Integration | Hardware security module embedding addresses EU Cyber Resilience Act mandates for encrypted battlefield file transmission protocols. |
| Regional Fab-Lab Network Expansion | Performance-based arrangements with Army maintenance depots displace traditional supply chains and capture recurring print license revenue. |
| Multi-Laser Powder-Bed Deployment | Parallel processing capability compresses naval aviation depot repair cycles from months to days for large-format titanium brackets. |
Study Parameters
Operator-level perspectives from depot maintenance directors, powder-bed system operators, defense procurement officers, and airworthiness certification engineers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through US DoD acquisition directives, NATO STANAG documentation, FAA material traceability guidelines, and EU Cyber Resilience Act implementation drafts. SEC filings from listed additive manufacturing vendors and customs records for titanium powder trade flows supplemented demand-side calibration. Bottom-up equipment shipment tallies and top-down defense maintenance budget allocations were triangulated to establish market sizing boundaries.
Scenario-bracketing around supply chain disruption severity and qualification timeline compression shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, deposition technology, service branch end user, and operational application context, with material certification grade as an additive manufacturing-specific overlay. CAGRs were derived from equipment deployment trajectories and maintenance contract value migration patterns, cross-referenced against Pentagon budget justification documents and NATO capability target disclosures.
Stress conditions across titanium powder allocation rationing, MIL-STD qualification timeline extension, and EU Cyber Resilience Act enforcement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about defense procurement continuity and regulatory harmonization progress. Macroeconomic contraction affecting defense budgets, unilateral regulatory divergence, or breakthrough non-laser deposition technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
Hybrid Additive Manufacturing Machine Market
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
Additive Manufacturing Platform Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
Selective Laser Sintering Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
Global 3D Pens Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
3D Printing Vacuum Furnaces Market
3D Printing Technology
Germany Additive Manufacturing Market