
 Asia-Pacific Industrial 3D Printing Market | 2026-2036
Asia-Pacific Industrial 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Industrial 3D Printing Market Insights
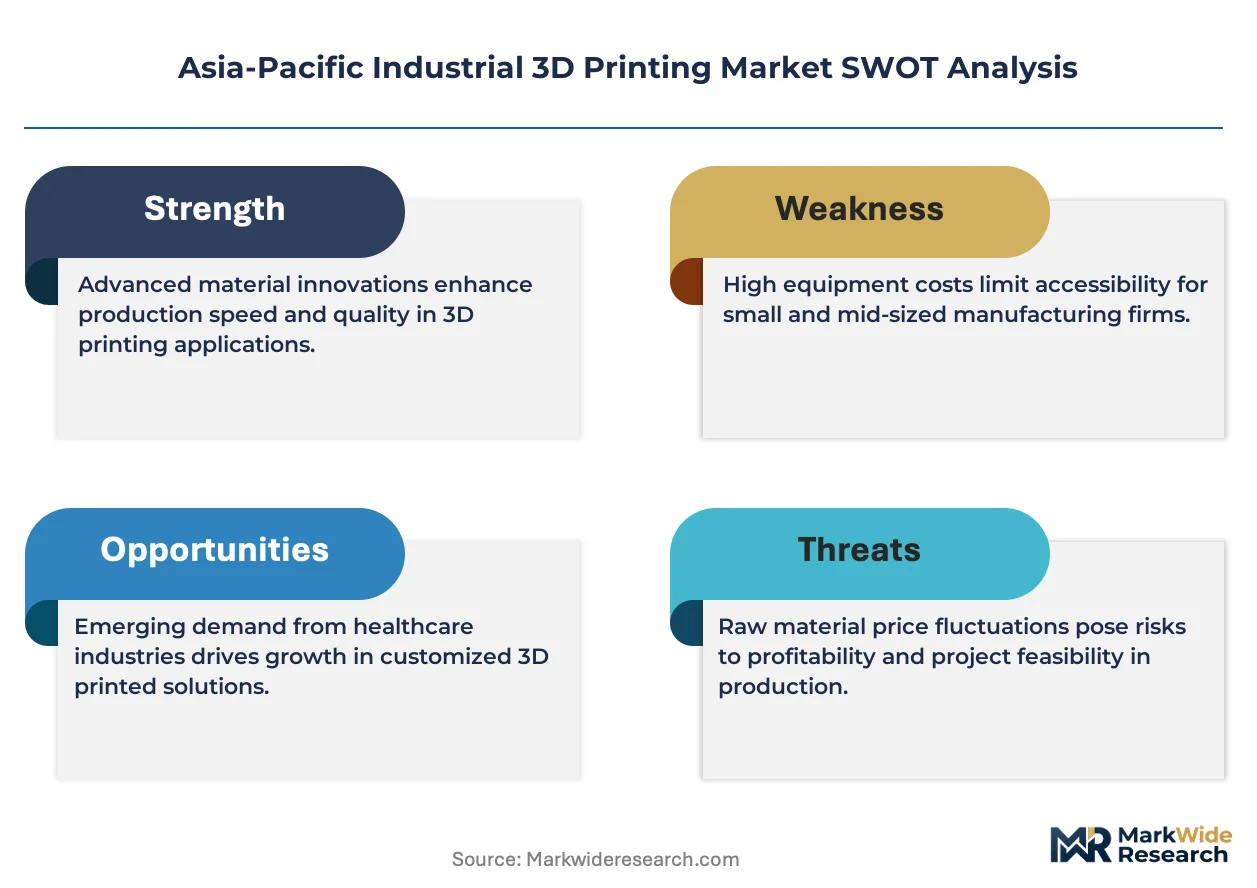
High-temperature alloy-grade printing is unwinding legacy limitations in aerospace component fabrication. EOS GmbH leverages its selective laser melting platform to anchor European-origin technology leadership across Chinese and Japanese production lines. Stratasys Ltd. competes through polymer-based systems that dominate prototyping workflows in Australian and South Korean industrial parks. HP Inc extends its multi-jet fusion architecture into high-volume tooling contracts with Southeast Asian contract manufacturers.
Asia-Pacific industrial 3D printing encompasses additive manufacturing systems producing functional metal, polymer, and composite parts through directed energy deposition, powder bed fusion, and material extrusion processes operating at layer resolutions below 50 microns and build temperatures exceeding 1,000 degrees Celsius for nickel superalloys. These systems generate complex geometries for weight-critical structural components, patient-specific orthopedic implants, and conformal cooling mold inserts that subtractive methods cannot fabricate. Metal powder bed fusion leads installed capacity across the region due to aerospace and medical certification pathways, while binder jetting emerges as the fastest-expanding technology category as Chinese and Indian automotive suppliers adopt it for stainless steel tooling at throughput rates competitive with conventional casting. Thermoplastic filament systems retain the broadest installed base in consumer goods prototyping, though margin pools concentrate in titanium and cobalt-chrome powder supply chains serving orthopedic device manufacturers.
China's SAMR enforces GB standards for industrial equipment safety and environmental controls on metal powder handling facilities, while Japan's METI coordinates JIS certification pathways that determine market access for foreign printer OEMs. India's BIS is developing localized conformity assessment protocols for imported additive systems deployed under national manufacturing incentive programs. Stakeholders must monitor divergent certification timelines across these three regimes to avoid stranded capital in production-scale installations.
Market Dynamics
China's MIIT certification mandates for industrial metal powder handling facilities are forcing simultaneous equipment upgrades across Yangtze River Delta manufacturing clusters, compressing supplier lead times and reshaping procurement authority toward compliance-first vendor selection.
Growth Catalysts
- Smart Factory Integration:Japan's METI pushes additive systems into connected production lines, mandating data interoperability standards that accelerate digital twin adoption for turbine blade manufacturers.
- GB Standards Enforcement:China's SAMR implements environmental controls on metal powder facilities, creating certified supplier tiers that filter out uncertified competitors and consolidate demand toward compliant OEMs.
- Orthopedic Implant Customization:Patient-specific cobalt-chrome and titanium geometries for hip and knee replacements drive powder bed fusion capacity expansion in medical device clusters across eastern China.
Market Restraints
- Nickel Superalloy Powder Volatility:Aerospace-grade powder supply concentrates among limited qualified suppliers, exposing turbine blade producers to input cost swings and allocation constraints.
- Dual Certification Burden:Foreign printer OEMs face parallel JIS pathway requirements in Japan and GB compliance in China, extending market entry timelines and stranding pre-certified equipment.
- Subtractive Machining Persistence:Conventional five-axis CNC retains cost advantage for simple geometries below certain complexity thresholds, limiting additive penetration in high-volume automotive brackets.
Strategic Opportunities
- Indian Automotive Tooling:Binder jetting adoption for stainless steel mold inserts remains underpenetrated among Pune and Chennai supplier parks, offering first-mover positioning as BIS protocols finalize.
- Conformal Cooling Convergence:Integration of topology optimization software with multi-jet fusion hardware enables mold inserts with complex internal channels that slash injection cycle times.
- Australian Defense Procurement:Sovereign industrial capability mandates in aerospace maintenance create localized demand for metal additive repair cells serving regional fighter and transport fleets.
Industry Challenges
- Process Engineer Scarcity:Qualified technicians for parameter optimization in high-temperature alloy printing remain concentrated in European and North American training pipelines, constraining Asia-Pacific facility ramp rates.
- Legacy MES Integration:Shop-floor data architectures at established automotive plants require custom middleware to accommodate additive machine telemetry, extending deployment timelines and inflating project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Industrial 3D Printing Market |
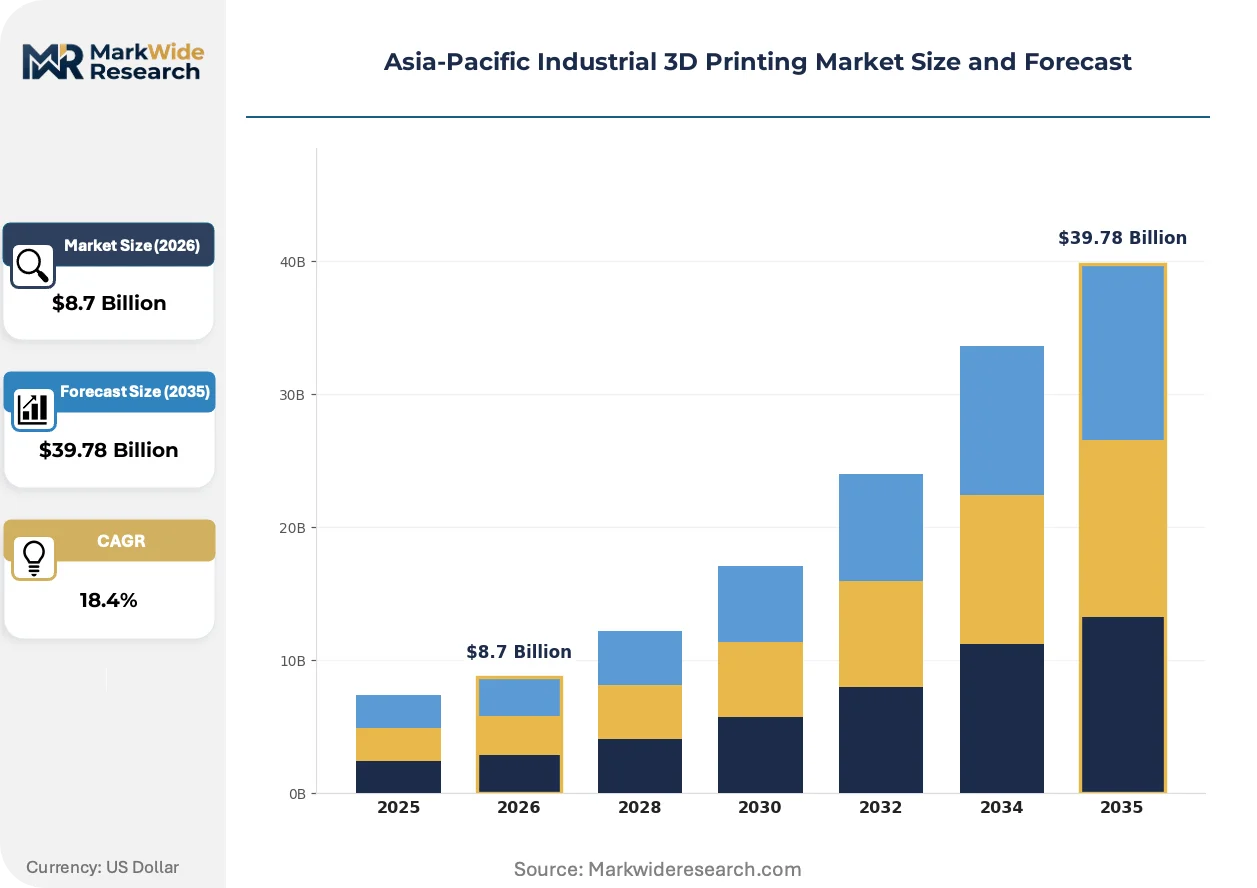
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Prototyping, Tooling, End-Use Production, Customization Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Binder Jetting Material: Thermoplastics, Metals, Composites, Ceramics End User: Aerospace, Automotive, Healthcare, Consumer Goods |
| Companies Covered | 3D Systems Corporation, Stratasys Ltd., EOS GmbH, Materialise NV, HP Inc, Autodesk Inc, ExOne Company, Voxeljet AG, SLM Solutions Group AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Industrial 3D Printing Market Trends and Innovations
Material extrusion systems for high-temperature thermoplastics are compressing prototyping timelines while powder bed fusion architectures evolve toward multi-laser configurations that challenge conventional casting economics.
Directed energy deposition for nickel superalloy repair is fragmenting the aftermarket maintenance landscape. MRO providers across Japan and Australia adopt wire-fed systems to restore worn turbine components without full replacement. This capability compresses turnaround times from weeks to days while displacing traditional weld-overlay shops from high-value aerospace contracts.
China's GB standards for industrial equipment safety and environmental controls on metal powder handling are tightening facility licensing requirements. Manufacturers must install exhaust filtration and inert gas monitoring systems to maintain operating permits. Medical device producers in Suzhou and Shenzhen face the steepest compliance curves as patient-specific implant certification requires documented powder traceability.
Contract manufacturers in Southeast Asia are unbundling equipment ownership from production service, offering print-on-demand capacity without capital commitment. Automotive and consumer electronics buyers in Vietnam and Thailand access titanium and aluminum geometries through service bureaus rather than in-house installation, shifting risk to suppliers while preserving design flexibility for low-volume product generations.
Asia-Pacific Industrial 3D Printing Market Segmentation
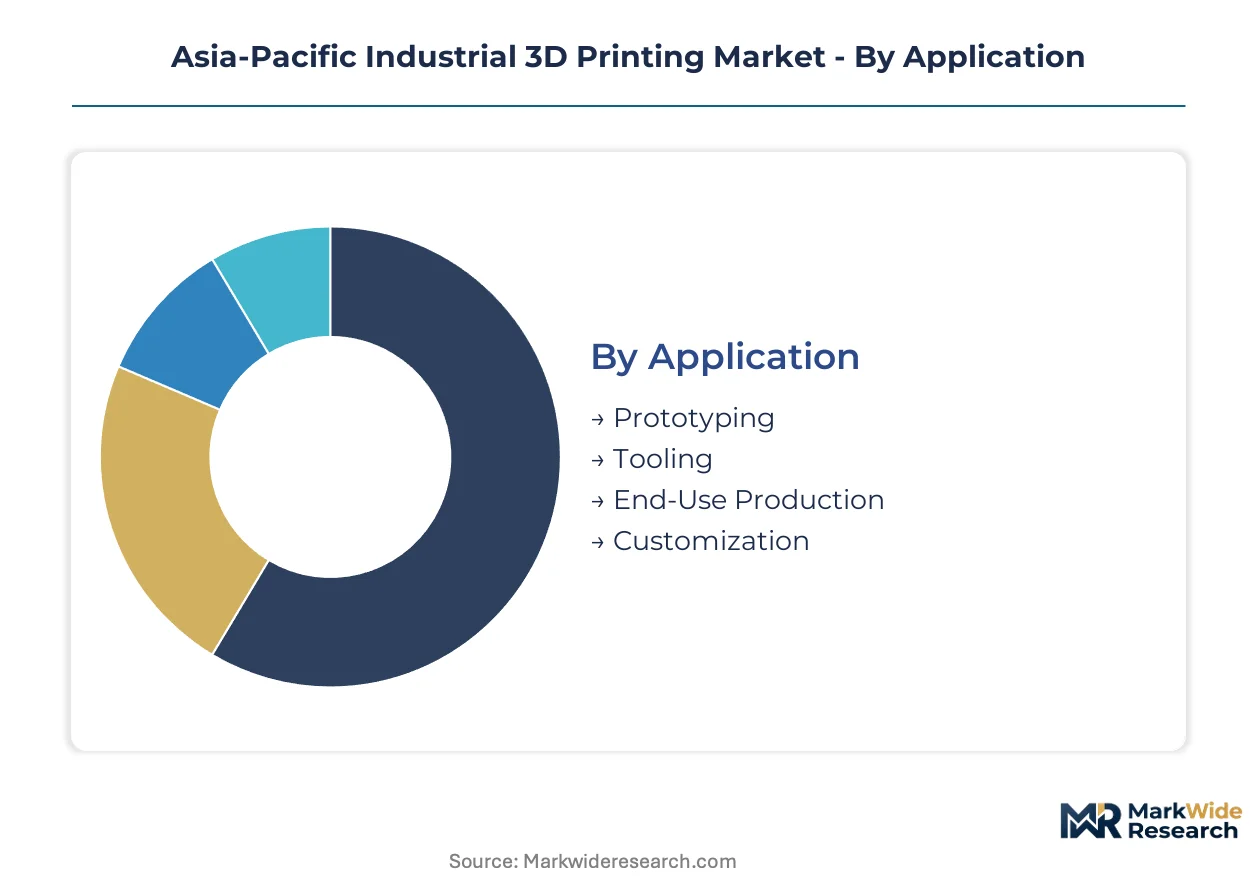
Segmentation in Asia-Pacific industrial 3D printing reveals where additive systems displace conventional fabrication and where legacy methods retain cost advantage. Understanding these boundaries guides capital allocation across technology tiers and end-use verticals.
Application:
Substitution pressure varies sharply by production stage, with late-stage manufacturing facing the highest barriers from entrenched tooling economics.
- Prototyping:Thermoplastic filament and resin systems dominate design validation cycles, compressing iteration timelines from weeks to days for consumer electronics developers in Shenzhen and Seoul. Japanese automotive studios deploy polymer powder bed fusion for functional prototype dashboards, though build volume constraints limit full-scale component testing.
- Tooling:Stainless steel mold inserts with conformal cooling channels now challenge conventional machined tooling in injection molding cycles across Yangtze River Delta automotive supplier parks. Binder jetting throughput gains are displacing cast aluminum tooling for medium-volume production runs.
- End-Use Production:Aerospace bracketry and orthopedic implants command certified production workflows, though qualification timelines stretch 18-24 months for powder lot traceability.
- Customization:Patient-specific dental aligners and hearing aid shells drive photopolymer system utilization, with distributed manufacturing models reducing shipping distances to Australian and Southeast Asian clinics.
Prototyping anchors the volume base while tooling gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive metal systems from accessible polymer platforms, determining customer entry points.
- Fused Deposition Modeling:Entry-level thermoplastic extrusion systems saturate educational and hobbyist channels, though industrial-grade variants with heated build chambers penetrate jigs and fixtures production for Australian defense maintenance depots.
- Stereolithography:Resin-based systems deliver surface finishes required for investment casting patterns in Indian jewelry clusters and dental mold fabrication across Bangkok medical device districts.
- Selective Laser Sintering:Polymer powder bed fusion enables functional prototyping and low-volume end-use parts in nylon and TPU, serving footwear midsole production for Vietnamese athletic brands.
- Binder Jetting:Metal and sand printing systems expand fastest among automotive tooling suppliers, with Chinese equipment vendors driving 40% cost reductions against imported powder bed fusion alternatives.
Fused deposition modeling retains the broadest installed base while binder jetting climbs the fastest.
Material:
Application requirements dictate material selection, with thermal and mechanical performance thresholds filtering options.
- Thermoplastics:ABS, nylon, and high-temperature PEI formulations dominate prototyping and industrial jigs, though flame-retardant grades face GB standard certification delays for Chinese railway interior components.
- Metals:Titanium and cobalt-chrome powder supply chains concentrate around orthopedic implant manufacturers in Suzhou and Singapore, with nickel superalloy grades reserved for aerospace turbine repairs in Nagoya and Melbourne.
- Composites:Carbon fiber-reinforced filaments and continuous fiber deposition systems penetrate drone airframe and motorsport applications, though fiber alignment control limits structural certification.
- Ceramics:Alumina and zirconia printing remains nascent, confined to dental crowns and specialized electrical insulators for Tokyo semiconductor equipment suppliers.
Thermoplastics sustain the highest shipment volumes while metal powders generate the steepest margin expansion.
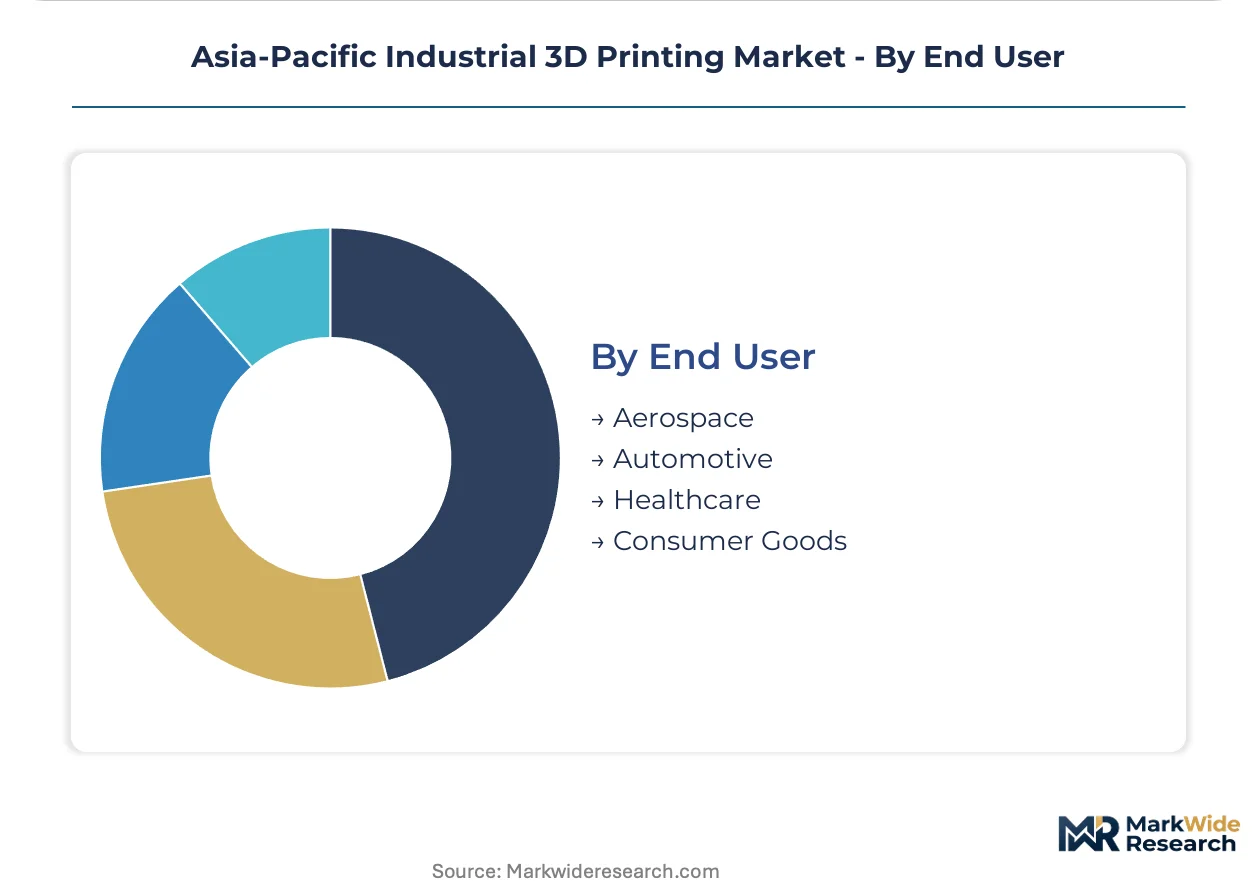
End User:
Customer type determines procurement authority, with regulated industries demanding certified supply chains that filter vendor pools.
- Aerospace:Turbine blade repair and lightweight bracket production drive metal powder bed fusion adoption at IHI Corporation and Australian defense aviation facilities, though airworthiness certification limits supplier flexibility.
- Automotive:Tooling and prototyping absorb the majority of additive capacity, with EV battery pack thermal management components emerging as a growth vector for aluminum printing in BYD and Hyundai supplier networks.
- Healthcare:Patient-specific implants and surgical guides command premium powder grades with full lot traceability, concentrating demand among Suzhou and Shenzhen device manufacturers with SAMR certification.
- Consumer Goods:Eyewear, footwear, and electronics housings utilize polymer systems for mass customization, though per-unit economics restrict additive to flagship product lines rather than commodity volumes.
Automotive absorbs the largest equipment shipments while healthcare delivers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metal powder supply chains concentrate among qualified suppliers in China, Japan, and South Korea, with certification requirements fragmenting procurement authority across national regulatory regimes. Demand clusters in eastern China's manufacturing belt, Japan's aerospace corridors, and Australia's defense maintenance networks.
China
Yangtze River Delta automotive and medical device producers drive powder bed fusion capacity expansion for conformal cooling molds and patient-specific implants. SAMR enforces GB standards for industrial equipment safety and metal powder environmental controls, compressing supplier lead times toward compliant OEMs. Suzhou and Shenzhen medical device manufacturers face steep certification curves as implant traceability requirements tighten.
Japan
IHI Corporation and Nagoya-area turbine manufacturers anchor metal additive adoption for nickel superalloy blade repair and lightweight bracket production. METI coordinates JIS certification pathways that determine market access for foreign printer OEMs, extending entry timelines for pre-certified equipment. Chubu region aerospace clusters integrate additive systems into connected production lines under smart factory mandates.
India
Pune and Chennai automotive supplier parks represent underpenetrated territory for binder jetting adoption in stainless steel mold inserts. BIS develops localized conformity assessment protocols for imported additive systems deployed under national manufacturing incentive programs. Western and southern industrial corridors await finalized certification timelines before production-scale installations proceed.
Australia
Sovereign industrial capability mandates in aerospace maintenance create localized demand for metal additive repair cells serving regional fighter and transport fleets. TGA-equivalent defense procurement standards filter vendor pools toward certified supply chains. Melbourne and Perth defense aviation facilities deploy wire-fed directed energy deposition systems to compress turbine component turnaround times.
South Korea
Hyundai supplier networks and Seoul Capital Area EV battery pack producers drive aluminum printing adoption for thermal management components. MFDS-aligned medical device regulations shape orthopedic implant certification pathways for cobalt-chrome and titanium geometries. Busan-Ulsan industrial parks host polymer powder bed fusion capacity for footwear midsole production serving Vietnamese athletic brands.
Asia-Pacific Industrial 3D Printing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with European-origin precision system vendors occupying premium positions against Chinese equipment manufacturers driving forty percent cost reductions. The vendor base stratifies across three tiers: multinational conglomerates with diversified industrial portfolios, specialized additive equipment pure-plays, and regional fabricators serving localized certification requirements. Dominant competitive moves include strategic partnerships for powder supply chain security and geographic expansion through compliance-first market entry strategies.
Among European-origin precision specialists, EOS GmbH and SLM Solutions Group AG exemplify technology leadership anchored in selective laser melting platforms. Stratasys Ltd. occupies a position representing polymer-based system specialization for prototyping workflows. HP Inc sits within the diversified conglomerate tier, extending multi-jet fusion architecture through high-volume tooling contracts. These three anchors illustrate how competitive positioning fragments across material-technology combinations rather than consolidating around integrated portfolios.
| Leading Market Players |
|---|
| 3D Systems Corporation |
| Stratasys Ltd. |
| EOS GmbH |
| Materialise NV |
| HP Inc |
| Autodesk Inc |
| ExOne Company |
| Voxeljet AG |
| SLM Solutions Group AG |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for nickel superalloy powder bind turbine blade manufacturers to fixed-volume commitments that lock in supply access while capping price visibility through indexed escalation clauses tied to LME nickel benchmarks. China's SAMR environmental certification requirements and Japan's METI smart factory mandates create tiered supplier qualification costs that propagate through equipment procurement budgets across the Yangtze River Delta and Chubu aerospace corridors.
Pricing Analysis
GB standards enforcement dictates the pricing tier structure for metal powder bed fusion systems, separating SAMR-certified OEMs from uncertified competitors through environmental compliance investment thresholds. Three-tier pricing structure across certified-premium, qualified-standard, and uncertified-economy levels reflects powder traceability grade and JIS pathway completion status. Cost compression in entry-level polymer systems is intensifying because Chinese equipment vendors drive forty percent price reductions against European-origin platforms. Automotive tooling buyers in Pune and Chennai supplier parks exhibit highest price sensitivity, while orthopedic implant manufacturers in Suzhou absorb premium powder grades with minimal negotiation leverage.
Supply Chain Analysis
Strategic stockpile preferences dominate nickel superalloy powder procurement, with aerospace MRO providers in Nagoya and Melbourne maintaining six-month inventory buffers against allocation constraints from limited qualified suppliers. Raw material flows center on titanium sponge from Japan and South Korea, cobalt-chrome precursor from Chinese integrated producers, and nickel powder from Australian mining operations. Single-source vulnerability concentrates in aerospace-grade superalloy supply, where qualification timelines prevent supplier switching. Distribution runs through authorized equipment distributors with certified technician networks, locking regional service coverage to vendor-approved partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific industrial 3D printing sits in early-cycle expansion, with binder jetting adoption for automotive tooling and directed energy deposition for turbine repair representing penetration tailwinds that remain under-executed across Indian and Australian supplier bases.
For Market Incumbents: Fortify powder supply chain security through backward integration into titanium and cobalt-chrome precursor production, eliminating allocation risk from qualified supplier concentration. Expand certified technician training pipelines in partnership with Nagoya and Melbourne technical institutes to constrain facility ramp rates for emerging competitors. Prioritize JIS and GB compliance investment to extend certification moats against Chinese equipment vendors driving cost-based disruption. For New Entrants and Emerging Players: Post-processing service gaps in wire-fed directed energy deposition for aerospace MRO represent immediate white-space opportunity, as incumbent OEMs under-serve repair-cell operators with parameter optimization support. Target Indian automotive tooling segment through binder jetting capacity deployment ahead of BIS protocol finalization, securing first-mover positioning in Pune and Chennai supplier parks. Pursue print-on-demand service bureau models in Vietnam and Thailand to shift capital risk from equipment buyers while capturing design flexibility demand from consumer electronics contract manufacturers. For Investors and Strategic Acquirers: Powder metallurgy specialists with captive superalloy production and established aerospace qualification pathways represent priority acquisition archetypes, offering defensible input cost positioning through the projection horizon. Long-term viability hinges on regulatory certification durability across SAMR, METI, and BIS regimes rather than technology differentiation alone. Monitor JIS pathway approval velocity for foreign printer OEMs as inflection indicator for competitive intensity normalization in Japanese aerospace corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Production | Captive nickel superalloy supply secures allocation priority for turbine blade manufacturers facing qualified supplier constraints. |
| Certified Technician Training Partnerships | Collaboration with Melbourne and Nagoya technical institutes constrains competitor facility ramp rates through capability scarcity. |
| Service Bureau Network Expansion | Print-on-demand capacity in Vietnam and Thailand shifts capital risk from automotive and electronics contract manufacturers. |
| Dual JIS-GB Compliance Investment | Parallel certification pathway completion extends market access timelines for pre-certified European-origin equipment. |
| Topology Optimization Software Integration | Conformal cooling mold insert partnerships with Yangtze River Delta automotive suppliers compress injection cycle times. |
Research Methodology
The analysis maps metal powder bed fusion, binder jetting, directed energy deposition, and material extrusion sub-sectors, each validated through process engineers at turbine blade manufacturers, procurement leads at orthopedic implant producers, and aftermarket service heads at aerospace MRO facilities. Primary interview data triangulates against MIIT certification filings, SAMR environmental compliance records, JIS pathway documentation, and customs trade data for titanium and cobalt-chrome powder flows. Bottom-up equipment shipment tallies reconcile with top-down manufacturing value-add estimates across the Yangtze River Delta, Chubu region, and Seoul Capital Area clusters.
Consistency checks validate volume and value outputs against external benchmarks including regional industrial production indices, aerospace component trade flows, and medical device export statistics. Segmentation dimensions span technology tier, material grade, application stage, and end-use vertical with regional regulatory cluster overlays. CAGRs derive from installed capacity expansion trajectories, qualification timeline assumptions, and substitution elasticity estimates for conformal cooling tooling against conventional machined inserts. Forecast inputs incorporate powder bed fusion laser configuration evolution and binder jetting throughput improvement curves.
Forecasts assume regulatory continuity in SAMR GB standards enforcement, METI smart factory integration mandates, and BIS conformity assessment protocol development; material policy shifts in any regime would require re-modeling. Practitioners should keep alternative scenarios live as nickel superalloy powder supply concentration and JIS pathway approval velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing Vacuum Furnaces Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
Additive Manufacturing Software Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
Digital 3D Printing Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
3D Printing in Aviation Market