
 3D Printed Prosthetics Market | 2026-2036
3D Printed Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Prosthetics Market Intelligence
Multi-material extrusion and AI-driven generative design is fragmenting traditional prosthetic fabrication into distributed, patient-specific production networks. Materialise NV leverages decades of medical imaging software integration to anchor digital workflow leadership. Open Bionics competes on affordability by specializing in myoelectric hands for children. Össur sustains premium positioning through titanium lattice research and direct-to-clinic service models.
3D printed prosthetics combine additive manufacturing processes such as selective laser sintering of nylon-12 powder or fused deposition modeling of polylactic acid with patient-specific anatomical data to produce sockets, limbs, and cosmetic covers matched to individual biomechanics. Upper limb prosthetics dominate current volume as traumatic injury and congenital limb deficiency drive replacement cycles, while lower limb applications capture higher per-unit value through carbon fiber-reinforced structural components. Photopolymer resins processed via digital light projection enable transparent diagnostic sockets that reduce fitting iterations, and FDM-based PLA limbs serve humanitarian segments where cost minimization overrides durability requirements.
FDA 510(k) clearance pathways and ISO 13485 quality management standards govern commercialization in the United States, while EMA medical device regulation and CE marking requirements shape European market access through clinical evidence thresholds. Veterans Health Administration procurement frameworks and national health technology assessment bodies in Germany and Japan increasingly reference additive manufacturing quality benchmarks during reimbursement decisions. Stakeholders must monitor evolving polymer biocompatibility standards and point-of-care manufacturing liability frameworks as distributed production models challenge traditional centralized regulatory inspection paradigms.
Market Dynamics
Generative design algorithms trained on patient biomechanical data are collapsing the traditional prosthetic socket fabrication timeline from weeks to hours, redistributing production authority from centralized manufacturing facilities toward hospital-based point-of-care installations.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for additive-manufactured limb devices compress premarket validation timelines, enabling faster clinical adoption in United States pediatric centers.
- Selective Laser Sintering of Nylon-12:Powder bed fusion delivers fatigue-resistant socket structures with porosity-tuned pressure distribution, replacing thermoformed polypropylene in transtibial applications.
- Veterans Health Administration Procurement Frameworks:Standardized additive manufacturing quality benchmarks in federal purchasing guidelines create institutional demand pull for certified 3D printed devices.
Market Restraints
- Biocompatible Photopolymer Supply Concentration:Photoinitiator and resin precursor production clusters in East Asian chemical manufacturing corridors expose Western device makers to input cost volatility and tariff exposure.
- ISO 13485 Certification Burden:Point-of-care manufacturing models challenge traditional centralized audit paradigms, creating compliance friction for distributed production networks seeking quality management accreditation.
- Titanium Powder Cost Structure:Plasma atomized Ti-6Al-4V feedstock prices constrain lattice-structured lower limb adoption, preserving carbon fiber composite dominance in load-bearing applications.
Strategic Opportunities
- India PLI Scheme for Medical Devices:Production-linked incentive frameworks for domestic manufacturing create tariff-advantaged export platforms serving South Asian and Middle Eastern humanitarian segments.
- AI-Driven Generative Design Convergence:Topology optimization algorithms integrated with DICOM-to-mesh pipelines enable automated socket generation, reducing prosthetist labor intensity per fitting.
- Direct-to-Clinic Digital Distribution:Cloud-based anatomical data transmission bypasses traditional orthotics and prosthetics distributor networks, capturing margin compression value in Germany and Japan reimbursement markets.
Industry Challenges
- Computational Prosthetist Training Gap:Workforce pipelines lack proficiency in mesh manipulation and print parameter optimization, creating bottleneck friction for clinical adoption of digital workflows.
- Point-of-Care Liability Framework Ambiguity:Jurisdictional uncertainty around hospital-based manufacturing defects complicates malpractice coverage and product liability allocation between device designers and fabricating institutions.
- Legacy EMR Integration Complexity:Anatomical capture systems require custom API development to interface with hospital information systems, extending deployment timelines and inflating implementation consulting costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Prosthetics Market |
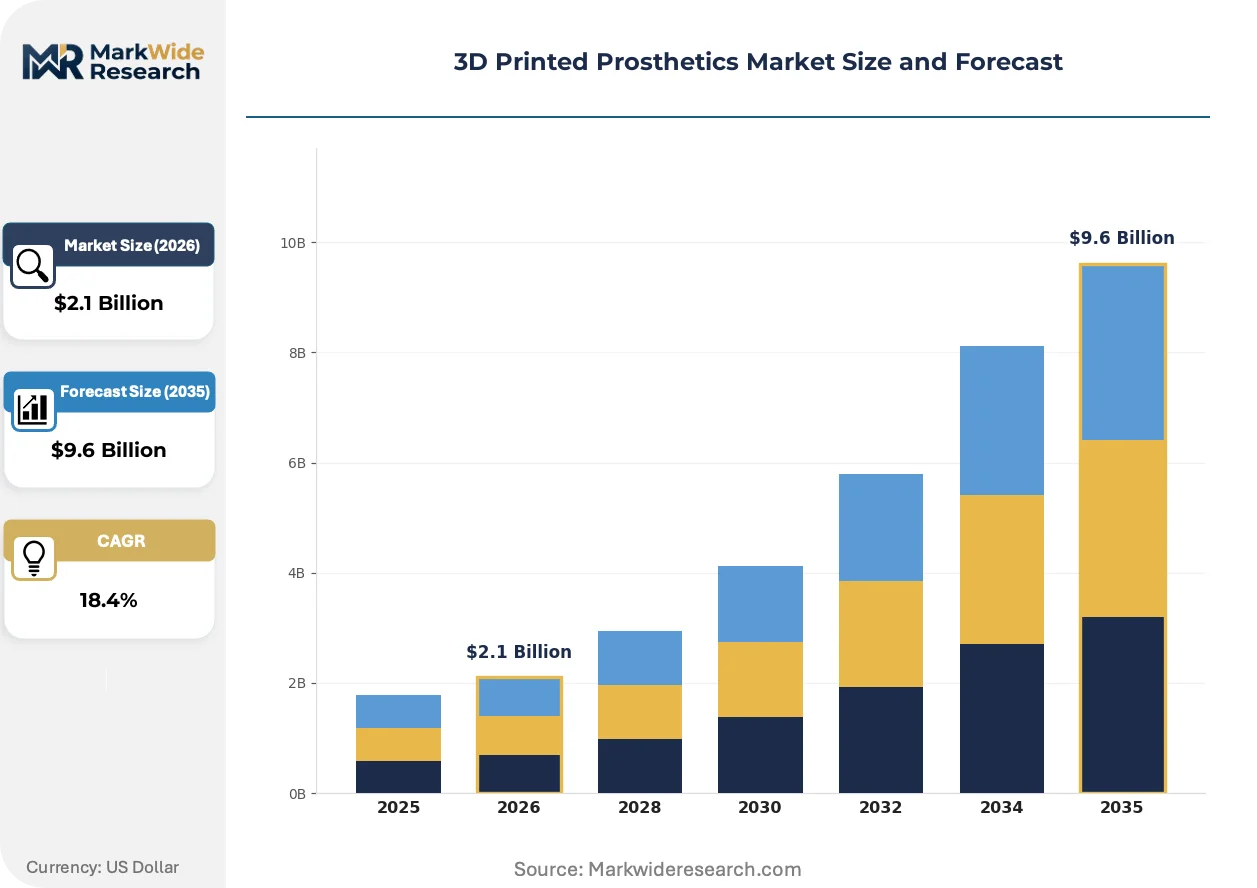
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.6 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
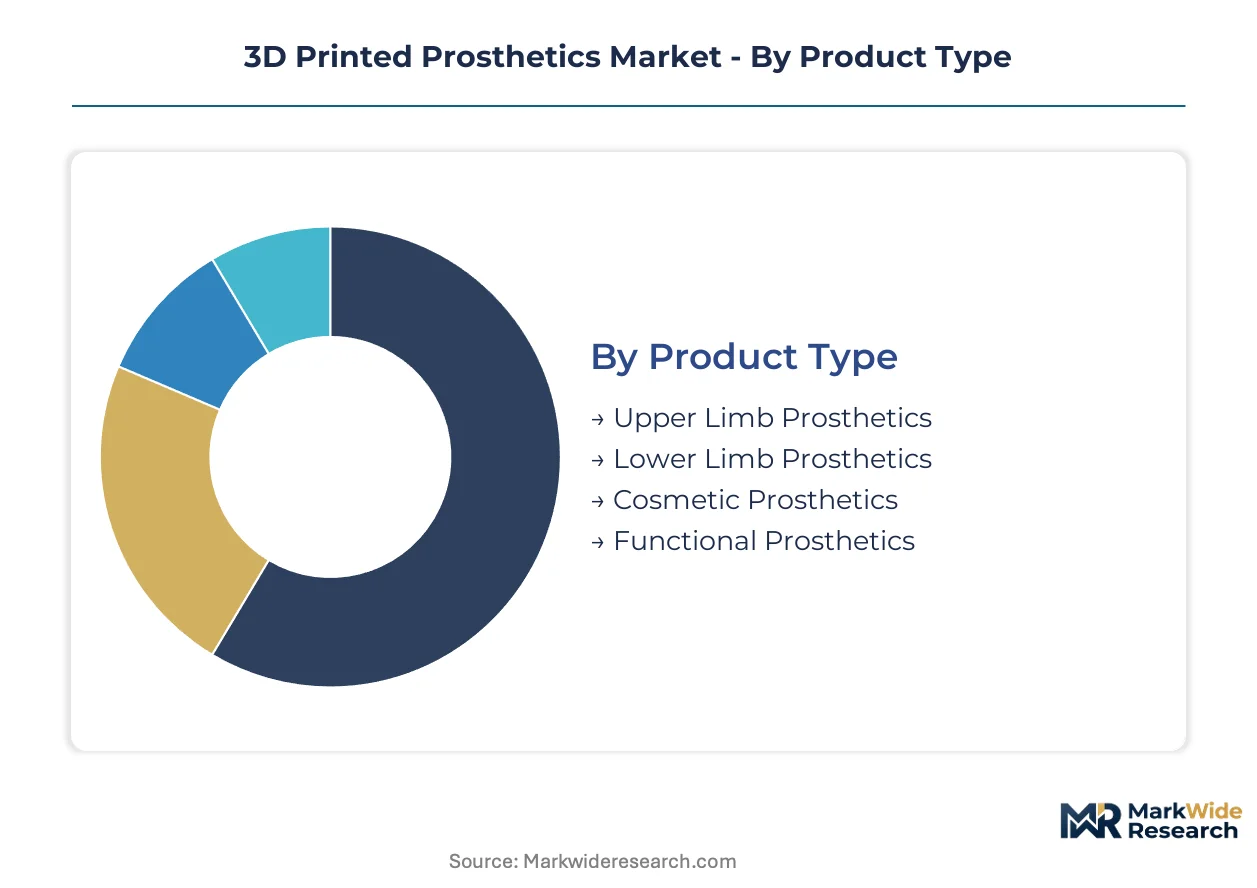
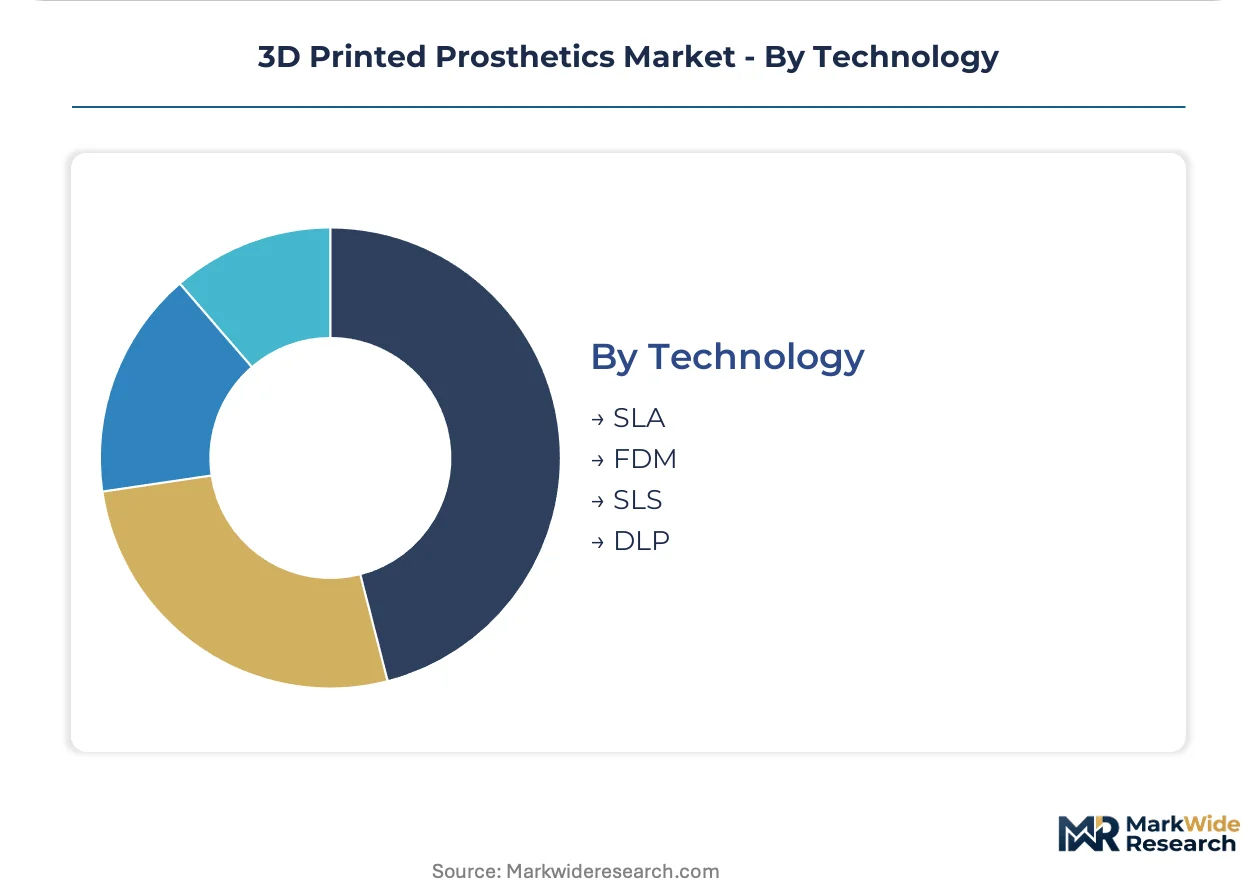
| Segmentation | Product Type: Upper Limb Prosthetics, Lower Limb Prosthetics, Cosmetic Prosthetics, Functional Prosthetics Material: PLA, ABS, Nylon, Photopolymer End User: Children, Adults, Amputees, Veterans Technology: SLA, FDM, SLS, DLP |
| Companies Covered | Materialise NV, Open Bionics, 3D Systems Corporation, Össur, UNYQ, Stratasys Ltd., Formlabs, Prodways Group, EnvisionTEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Prosthetics Market Strategic Shifts & Innovations
Digital light projection of transparent diagnostic resins and myoelectric sensor integration are converging to transform prosthetic fitting from iterative craft toward predictive, data-driven clinical workflows.
Photopolymer resins formulated for digital light processing now enable fully transparent diagnostic sockets that visualize tissue pressure distribution during dynamic loading. Prosthetists in United States academic medical centers deploy these transparent interfaces to reduce fitting iteration counts. Traditional opaque diagnostic socket fabrication is rendering obsolete as real-time biomechanical feedback compresses clinical appointment schedules and improves residual limb health outcomes.
EMA Medical Device Regulation Annex XVI expansion captures active implantable prosthetic components under enhanced clinical evidence requirements. Manufacturers must generate post-market surveillance data for myoelectric hand systems with embedded sensors. European notified bodies are extending review timelines for novel additive-manufactured limb categories, forcing device sponsors to front-load clinical trial investment before CE marking authorization.
Hospital systems are consolidating prosthetic procurement authority under value-based care administrators rather than decentralized orthopedic surgery departments. Bundled payment models in United States Medicare Advantage plans incentivize episode-cost containment over device acquisition price minimization. This purchasing concentration favors suppliers with integrated digital workflow platforms capable of delivering patient-matched devices within compressed episode windows.
3D Printed Prosthetics Market Segmentation
Patient-specific fabrication demands and regulatory compliance requirements create divergent technical specifications across product categories. Material selection and manufacturing technology choices cascade through reimbursement pathways and clinical adoption timelines.
Product Type:
Mature socket fabrication competes with emerging myoelectric integration as functional requirements stratify across amputation levels.
- Upper Limb Prosthetics:Myoelectric hand systems with embedded sensor arrays dominate pediatric and traumatic injury replacement cycles. United States academic medical centers concentrate demand for bionic integration where Veterans Health Administration procurement frameworks cover advanced device categories.
- Lower Limb Prosthetics:Carbon fiber-reinforced structural components and titanium lattice research address load-bearing biomechanics in transtibial and transfemoral applications. German reimbursement pathways for additive-manufactured devices accelerate adoption of fatigue-resistant socket structures.
- Cosmetic Prosthetics:Silicone surface matching and aesthetic finishing serve congenital limb deficiency patients prioritizing appearance over function.
- Functional Prosthetics:Task-specific terminal devices for vocational and recreational activities address activity-specific biomechanical requirements.
Upper limb prosthetics handle the majority of throughput; lower limb prosthetics are expanding most quickly on share as carbon fiber-titanium hybrid structures penetrate load-bearing applications.
Material:
Cost tier differentiation separates humanitarian deployment from premium clinical segments.
- Nylon:Selective laser sintering of nylon-12 powder delivers porosity-tuned pressure distribution in definitive sockets. Fatigue resistance and biocompatibility certification position this material for FDA 510(k) clearance pathways in transtibial applications.
- Photopolymer:Digital light projection of transparent diagnostic resins enables real-time tissue pressure visualization during dynamic loading. United States prosthetists deploy these interfaces to compress fitting iteration counts and improve residual limb health outcomes.
- PLA:Fused deposition modeling serves cost-minimization priorities in humanitarian segments where durability requirements are secondary to accessibility.
- ABS:Impact-resistant properties address pediatric applications requiring frequent replacement due to growth cycles.
Nylon dominates value throughput; photopolymer is climbing the fastest as transparent diagnostic protocols displace opaque fitting methods.
End User:
Customer type determines reimbursement complexity and device replacement frequency.
- Children:Growth-adjustable socket designs and myoelectric hands from specialized pediatric manufacturers address congenital limb deficiency and traumatic injury replacement cycles requiring frequent refitting.
- Veterans:Federal procurement frameworks and specialized rehabilitation centers in the United States create institutional demand pull for certified additive-manufactured devices with advanced sensor integration.
- Adults:Workforce reintegration and independent living priorities drive functional specification requirements across occupational categories.
- Amputees:General population coverage spans private insurance and national health system reimbursement pathways with varying evidence requirements.
Children represent the highest replacement frequency; veterans concentrate premium technology adoption through dedicated procurement channels.
Technology:
Volume scale separates distributed point-of-care installations from centralized production networks.
- SLS:Selective laser sintering anchors definitive socket production for load-bearing applications requiring fatigue resistance and precise porosity control.
- FDM:Fused deposition modeling enables hospital-based point-of-care manufacturing with minimal facility infrastructure requirements.
- SLA:Stereolithography delivers surface finish precision for cosmetic covers and detailed anatomical matching.
- DLP:Digital light projection accelerates transparent diagnostic socket fabrication with layerless curing speeds.
SLS handles structural throughput; DLP is gaining share fastest as diagnostic workflow compression becomes a clinical priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterans Health Administration procurement frameworks concentrate premium demand in the United States, while statutory health insurance reimbursement pathways in Germany and Japan anchor European and Asian adoption respectively.
United States
Federal procurement frameworks through the Veterans Health Administration generate institutional demand for certified additive-manufactured devices. FDA breakthrough device designation accelerates premarket review timelines for pediatric myoelectric applications. Academic medical centers in Baltimore and Boston deploy transparent diagnostic socket protocols to compress fitting iterations.
Germany
Statutory health insurance reimbursement for patient-matched socket designs drives adoption of selective laser sintering in transtibial applications. EMA medical device regulation and CE marking requirements shape quality management certification for distributed production networks. Industrial clusters around Munich and Stuttgart host medical imaging software integrators serving prosthetic fabrication workflows.
Japan
PMDA regulatory frameworks and METI industrial policy support additive manufacturing adoption in rehabilitation medicine. National health technology assessment bodies reference ISO 13485 quality benchmarks during reimbursement decisions for carbon fiber-reinforced lower limb devices. Tokyo and Osaka metropolitan areas concentrate prosthetist training programs for digital workflow proficiency.
India
Production-linked incentive schemes for domestic medical device manufacturing create export platforms serving South Asian humanitarian segments. CDSCO medical device rules govern import and manufacture of patient-matched prosthetic components. Industrial corridors in Maharashtra and Gujarat host contract manufacturers producing FDM-based PLA limbs for cost-minimization priorities.
United Kingdom
NHS England specialized commissioning frameworks determine access to myoelectric hand systems for congenital limb deficiency patients. MHRA regulations align with MDR requirements for post-market surveillance of active implantable prosthetic components. London and Manchester academic centers pilot AI-driven generative design convergence for automated socket generation.
3D Printed Prosthetics Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement authority. Medical imaging software integrators anchor digital workflow leadership while point-of-care equipment suppliers capture distributed production expansion. Three archetypes dominate: imaging-to-print platform owners, myoelectric component specialists, and materials-science-driven socket fabricators. Consolidation pressure runs through strategic partnerships between software vendors and hardware OEMs, plus backward integration into biocompatible resin formulation.
Among imaging-software-anchored players, Materialise NV exemplifies the platform-control archetype through decades of DICOM-to-mesh pipeline integration. Open Bionics occupies a position within the pediatric-specialist tier, competing on affordability vectors for myoelectric hand applications. Össur represents premium-tier positioning through titanium lattice research programs and direct-to-clinic service model development.
| Leading Market Players |
|---|
| Materialise NV |
| Open Bionics |
| 3D Systems Corporation |
| Össur |
| UNYQ |
| Stratasys Ltd. |
| Formlabs |
| Prodways Group |
| EnvisionTEC |
| Others |
Cost & Logistics Intelligence
Plasma-atomized titanium powder production clusters in Chinese and Japanese metallurgical corridors concentrate upstream margin capture, while downstream pricing power fragments across hospital-based point-of-care installations and centralized OEM fabricators competing on ISO 13485 certification tiers.
Pricing Analysis
Cost-plus contracts with titanium powder indexation dominate procurement between socket fabricators and aerospace-grade feedstock suppliers. Three-tier pricing structure across FDA-cleared premium devices, CE-marked standard systems, and humanitarian economy limbs differentiates on certification burden and sensor integration depth. Cost compression in FDM-based PLA segments intensifies as Indian contract manufacturers exploit PLI scheme tariff advantages. Pediatric amputee clinics exhibit highest price sensitivity due to frequent refitting cycles, while Veterans Health Administration procurement shows lowest sensitivity given federal reimbursement guarantees.
Supply Chain Analysis
Upstream photoinitiator and nylon-12 powder feedstock draws from East Asian chemical manufacturing corridors in China, Japan, and South Korea. Biocompatible resin precursors, plasma-atomized Ti-6Al-4V, and carbon fiber tow constitute critical input dependencies. Single-source vulnerability concentrates around photoinitiator formulations subject to export control reviews. Distribution runs through orthotics and prosthetics distributor networks in mature reimbursement markets, shifting toward direct-to-clinic digital transmission in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards scarce digital workflow proficiency and certified point-of-care manufacturing infrastructure, creating acquisition premiums for stakeholders controlling DICOM-to-mesh pipeline integration or FDA 510(k) clearance pathways.
For Market Incumbents: Insulate socket fabrication margins by deepening backward integration into biocompatible resin formulation and securing exclusive hospital system partnerships before bundled payment models consolidate procurement authority. Threat vectors include AI-driven generative design startups collapsing prosthetist labor intensity and EMA MDR Annex XVI surveillance burdens extending CE marking timelines. For New Entrants and Emerging Players: Pursue white-space capture in Indian PLI scheme export platforms serving Middle Eastern humanitarian segments, where cost-minimization priorities override durability specifications. Pediatric myoelectric hands in South Asian markets offer lowest competitive density. Go-to-market execution should leverage cloud-based anatomical data transmission to bypass entrenched O&P distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward imaging-to-print platform owners with embedded DICOM integration and established FDA quality management infrastructure, positioned for hospital system consolidation under value-based care administrators. Long-term viability hinges on reimbursement pathway maturation beyond United States, Germany, and Japan core markets. Monitor Veterans Health Administration additive manufacturing quality benchmark adoption rates as inflection signal for institutional demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates premarket validation for selective laser sintered nylon-12 socket structures in transtibial applications. |
| CE Marking Pathway | Enables European market access through EMA MDR compliance for myoelectric hand systems with embedded sensors. |
| Hospital System Partnership | Captures bundled payment value under Medicare Advantage episode-cost containment frameworks. |
| Software Companion Development | Integrates AI-driven generative design algorithms with existing DICOM-to-mesh clinical workflows. |
| Reimbursement Strategy | Secures statutory health insurance coverage for patient-matched socket designs in German and Japanese markets. |
Research Approach
The analysis maps upper limb prosthetics, lower limb prosthetics, diagnostic sockets, and cosmetic covers, each validated through prosthetists, biomedical engineers, hospital purchasing committees, and GPO contracts managers. Primary interviews with Veterans Health Administration procurement officers and pediatric amputee clinic directors combined with secondary validation from FDA 510(k) filings, EMA MDR submissions, CMS Medicare reimbursement databases, and ISO 13485 certification registries. Bottom-up patient-volume modeling and top-down medical device expenditure triangulation anchored market sizing.
Assumptions held reimbursement pathway maturation constant across the projection horizon while varying additive manufacturing technology adoption curves and photopolymer biocompatibility standard evolution. Segmentation dimensions modeled include product type, material grade tier, end-user category, and technology platform. CAGRs derived from fitted growth curves against historical prosthetic replacement cycle data and veterans' benefits expenditure trajectories. Forecast inputs incorporated titanium powder price volatility indices and PLI scheme utilization rates.
Sensitivities concentrate around FDA point-of-care manufacturing liability framework clarification and EMA MDR Annex XVI active implantable component surveillance timeline extensions. Cross-checking against Veterans Health Administration procurement volume disclosures and German statutory health insurance reimbursement authorization databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Joint Replacement Device Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
Medical Electrodes Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
US Clear Aligners Market
Medical Devices
Bedwetting Alarm Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Allografts Market
Medical Devices
Infusion Pump Market
Medical Devices
Robot Assisted PCI Market
Medical Devices
Ligament Stabilizers Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Rapid Infuser Market