
 3D Medical Implant Market | 2026-2036
3D Medical Implant Market Size, Share, and Industry Trends Forecast 2026-2036
3D Medical Implant Market Insights
Patient-specific implant design through computed tomography-derived digital workflows is reconfiguring surgical planning and device fabrication across the orthopedic sector. Stryker Corporation leverages integrated software-to-manufacturing platforms to anchor its position in cranial reconstruction. Materialise NV specializes in surgical guide engineering and medical image processing, sustaining competitive differentiation through regulatory-compliant quality systems. Zimmer Biomet Holdings Inc operates extensive orthopedic implant portfolios while navigating the transition toward additive production methods.
3D medical implants are patient-matched prosthetic devices fabricated through additive manufacturing processes, typically from titanium alloys, cobalt-chrome, or bioresorbable polymers with pore architectures ranging from 100 to 1000 micrometers to promote osseointegration. These devices restore anatomical function after trauma, degenerative disease, or congenital defect. Orthopedic applications dominate current revenue pools due to hip and knee replacement volumes, while dental segments show accelerating penetration for custom abutments and full-arch restorations. Metals command the largest material share given titanium's strength-to-weight ratio and established biocompatibility profile, though polymer and ceramic alternatives are gaining traction for resorbable and load-bearing applications respectively.
FDA 510(k) and De Novo pathways govern market access in the United States, while EMA Medical Device Regulation and CE marking requirements shape commercialization across European markets. China's NMPA has established dedicated technical review guidelines for additively manufactured medical devices, reflecting national priorities under dual carbon goals that favor material-efficient production. Stakeholders must monitor evolving post-market surveillance requirements and harmonization efforts between ISO 13485 quality management standards and jurisdiction-specific good manufacturing practice mandates.
Market Dynamics
Patient-matched fabrication workflows are compressing traditional implant supply chains by collapsing design-to-delivery timelines from months to days, forcing orthopedic device manufacturers to reconfigure quality systems around additive production.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's dedicated review track for additively manufactured devices accelerates commercialization timelines for titanium cranial plates and acetabular cups in the United States.
- Computed tomography-derived surgical planning:Digital workflows integrating DICOM data with lattice generation software enable patient-specific pore architectures that improve osseointegration outcomes in spinal fusion procedures.
- German orthopedic hub concentration:Centralized additive manufacturing clusters in Bavaria and Baden-Württemberg aggregate titanium powder supply, electron beam melting capacity, and regulatory expertise for European distribution.
Market Restraints
- Titanium powder supply concentration:Spherical Ti-6Al-4V feedstock production concentrates among a limited set of gas atomization facilities, creating input cost volatility for implant fabricators.
- EMA MDR technical documentation burden:The European Medical Device Regulation's enhanced clinical evidence requirements for patient-specific implants extend certification timelines and inflate regulatory compliance costs.
- CNC machining substitution threat:Five-axis milling of cobalt-chrome knee implants retains cost advantages at production volumes above 500 units annually, constraining additive penetration in high-volume joint replacement.
Strategic Opportunities
- China NMPA dedicated technical guidelines:China's national medical products administration has established specialized review pathways for additively manufactured devices, aligning regulatory incentives with dual carbon goals that favor material-efficient production.
- Bioresorbable polymer craniomaxillofacial applications:Polycaprolactone and polylactic acid lattice structures for pediatric skull reconstruction represent an emerging application with limited incumbent competition.
- Direct-to-hospital digital distribution:Cloud-based surgical planning platforms enable implant manufacturers to bypass traditional distributor networks and capture margin in academic medical center procurement.
Industry Challenges
- Additive manufacturing technician scarcity:Qualified operators for electron beam melting and selective laser sintering equipment remain concentrated among a small pool of trained personnel, constraining production scaling.
- ISO 13485 quality system reconfiguration:Legacy orthopedic manufacturers face complex integration requirements when grafting additive workflows onto established CNC-machining-based quality management systems.
- Post-processing bottleneck capacity:Hot isostatic pressing and precision machining of as-built implants require capital-intensive equipment that strains mid-tier fabricator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Medical Implant Market |
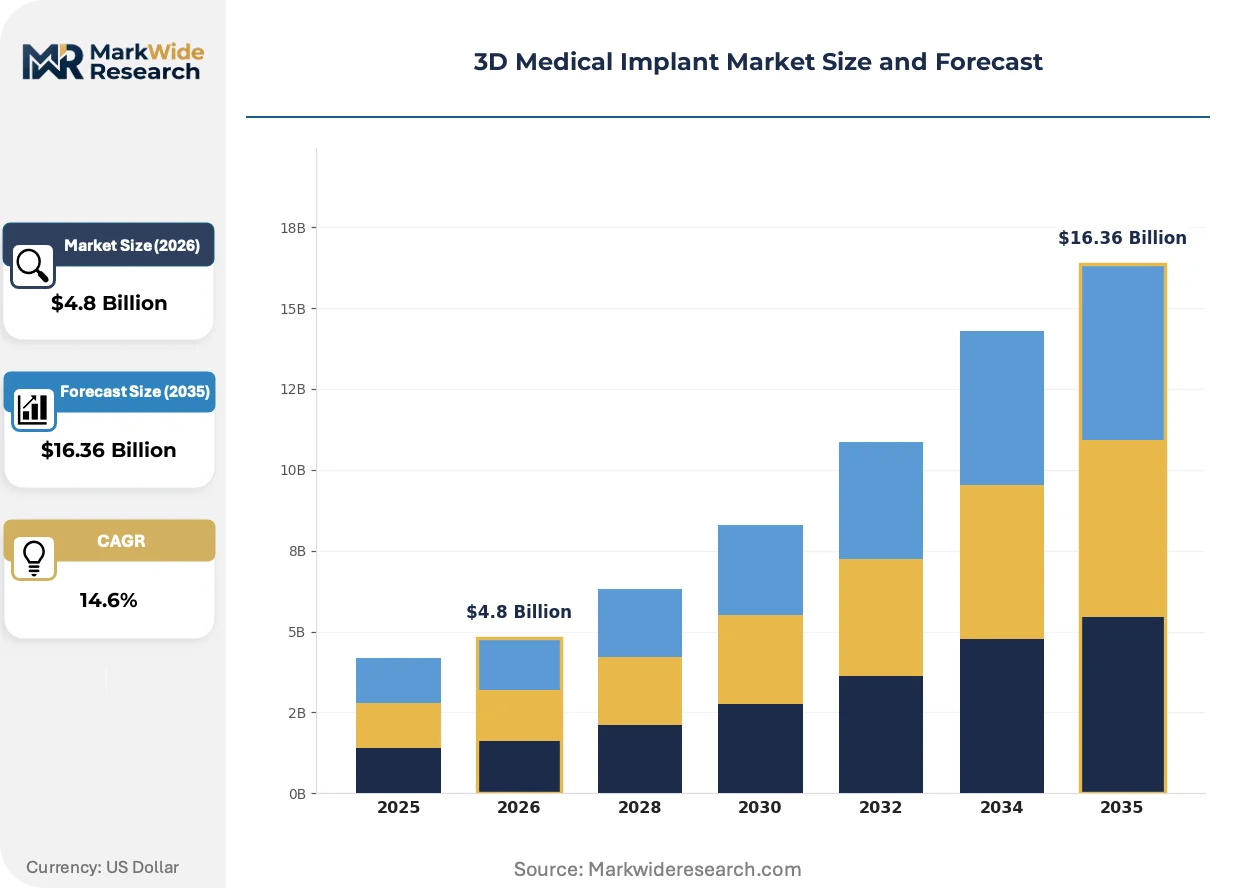
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic, Dental, Cranial, Spinal Material: Metals, Polymers, Ceramics, Composite Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing End User: Hospitals, Surgical Centers, Orthopedic Clinics, Dental Clinics |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings Inc, Materialise NV, 3D Systems Inc., Stratasys Ltd., Medtronic plc, Johnson & Johnson, EnvisionTEC GmbH, Arcam AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Medical Implant Market Trends and Innovations
Hybrid manufacturing workflows are collapsing the boundary between subtractive precision and additive complexity, enabling implant designs that were economically unviable under single-process fabrication.
Multi-material deposition systems are hybridizing titanium lattice structures with solid bearing surfaces in single build cycles. Orthopedic trauma centers in Germany and the United States are piloting these platforms for complex pelvic reconstruction cases. This convergence is compressing the traditional separation between porous ingrowth zones and load-bearing solid regions that previously required assembly or diffusion bonding.
China's NMPA technical review guidelines for additively manufactured medical devices are formalizing quality system expectations around powder traceability and build parameter validation. Domestic manufacturers in Shanghai and Beijing are restructuring documentation workflows to align with these standards ahead of anticipated enforcement tightening. The dental implant segment is responding fastest, with full-arch titanium frameworks now routinely submitted under the dedicated pathway.
Academic medical centers are consolidating implant procurement around integrated software-to-sterile-field service contracts. Hospital systems in the United States are displacing traditional distributor relationships with direct digital platform subscriptions that bundle pre-operative planning, device fabrication, and post-operative tracking. This shift is most visible in cranial reconstruction, where patient-specific titanium plates are now sourced through hospital-owned additive manufacturing partnerships rather than conventional device vendor catalogs.
3D Medical Implant Market Segmentation
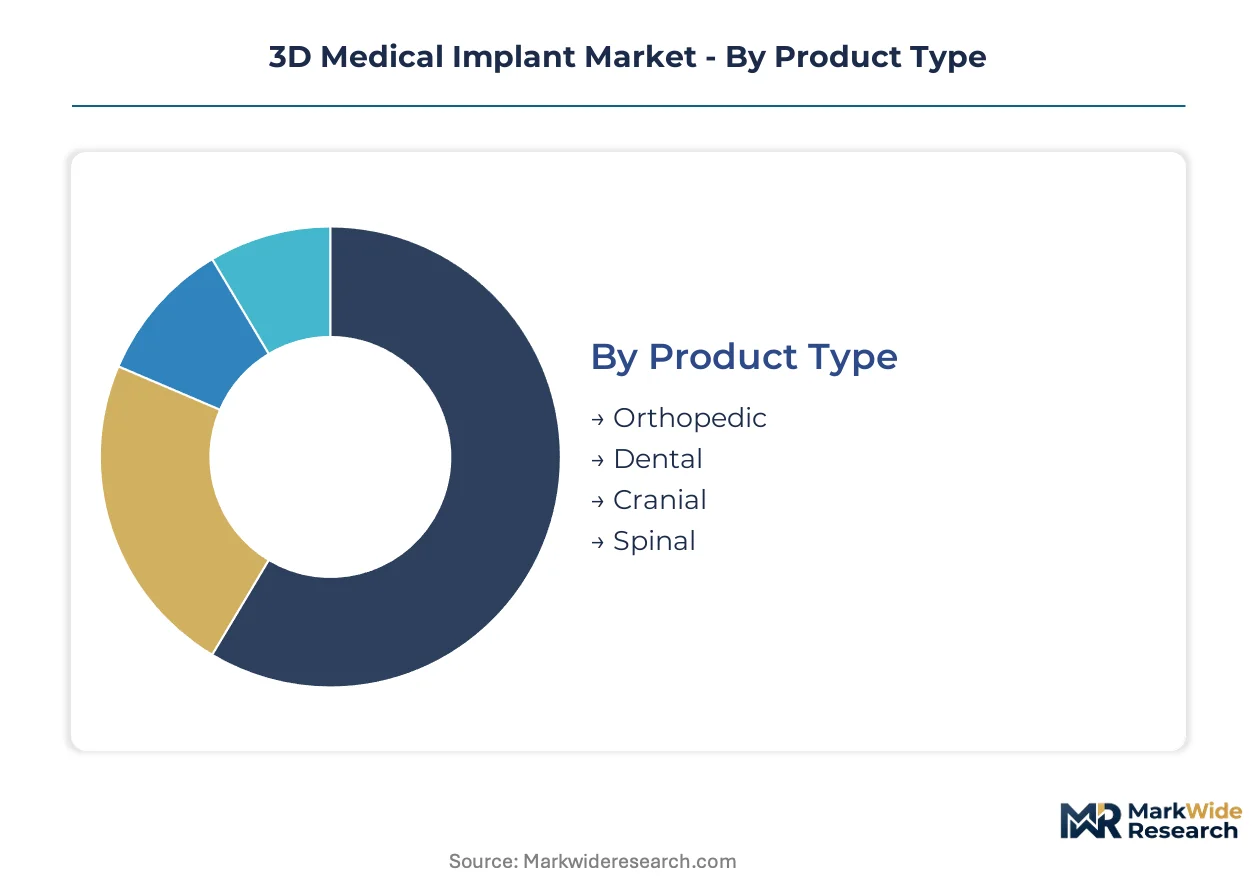
Segmentation in 3D medical implants reveals how fabrication technology, anatomical application, and procurement setting interact to determine pricing power and regulatory pathway. Each dimension carries distinct margin profiles and certification burdens that reshape competitive positioning across the value chain.
Product Type:
Application focus determines pore architecture requirements and surgical workflow integration depth across anatomical sites.
- Orthopedic:Titanium and cobalt-chrome hip stems, knee trays, and shoulder glenoids incorporate 300-800 micrometer lattice structures for bone ingrowth. Demand concentrates in German Bavarian manufacturing clusters and US academic medical centers where revision surgery volumes justify patient-specific fabrication.
- Dental:Custom titanium abutments and full-arch frameworks exploit direct-to-laboratory digital workflows. Chinese dental laboratories in Shenzhen and Guangzhou are absorbing the fastest capacity expansion as NMPA pathway streamlining accelerates domestic commercialization.
- Cranial:Patient-matched titanium plates restore skull contour after trauma or tumor resection.
- Spinal:Interbody fusion cages with optimized load-bearing surfaces target degenerative disc disease procedures.
Orthopedic holds installed capacity. Dental is rotating up the share rankings.
Material:
Cost tier and biocompatibility certification depth segment the supply base between established metal suppliers and emerging polymer specialists.
- Metals:Ti-6Al-4V ELI and cobalt-chrome alloys dominate load-bearing applications through electron beam melting and selective laser melting platforms. German gas atomization facilities in Hagen and Kamp-Lintfort anchor spherical powder supply, though Chinese titanium sponge integration is climbing the fastest.
- Polymers:Polycaprolactone and polylactic acid enable resorbable pediatric craniomaxillofacial implants that eliminate secondary removal surgery. US pediatric trauma centers in Boston and Philadelphia are piloting these applications ahead of broader FDA 510(k) accumulation.
- Ceramics:Alumina and zirconia address wear-resistant bearing surfaces in joint reconstruction.
- Composite:Polymer-ceramic hybrids target modulus-matched bone substitution.
Metals command volume leadership. Polymers are expanding most quickly in application breadth.
Technology:
Fabrication method determines surface finish, build speed, and geometric complexity ceiling for implant geometries.
- Selective Laser Sintering:Direct metal laser sintering of titanium and cobalt-chrome achieves 99.5% theoretical density with 20 micrometer surface roughness suitable for immediate osseointegration. German machine tool builders in Munich and Aachen control installed base expansion.
- Stereolithography:Photopolymer vat polymerization produces surgical guides and bioresorbable scaffolds with 25 micrometer feature resolution. US dental laboratories are displacing milled PMMA temporaries with same-day printed restorations.
- Fused Deposition Modeling:Thermoplastic extrusion serves low-cost surgical planning models and patient education tools.
- Digital Light Processing:Projector-based photopolymer curing accelerates dental restoration throughput.
Selective Laser Sintering holds precision-critical applications. Digital Light Processing is gaining share fastest in high-throughput dental production.
End User:
Procurement setting determines reimbursement pathway, quality system requirements, and distributor relationship structure.
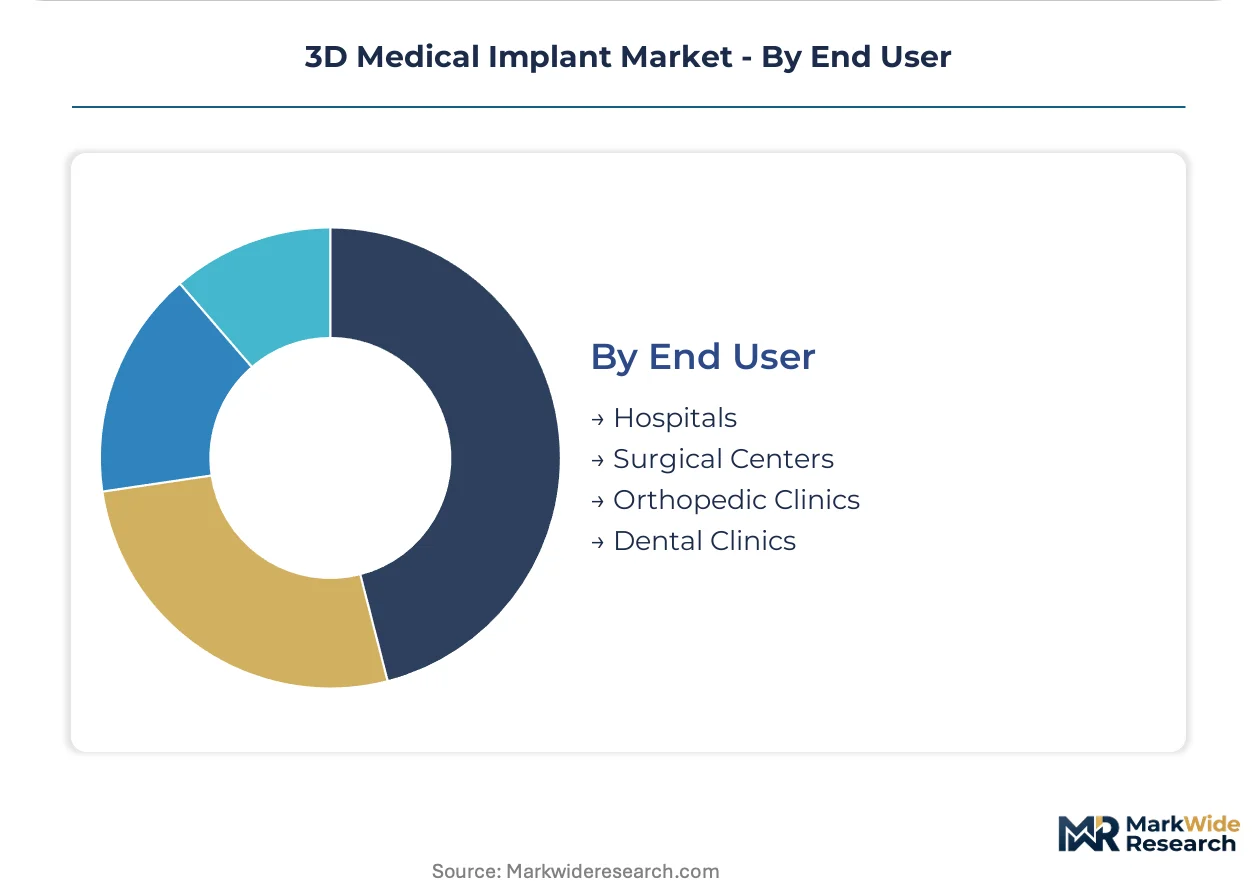
- Hospitals:Academic medical centers in the United States and university hospitals in Germany are consolidating implant procurement around integrated software-to-sterile-field contracts that bundle pre-operative planning with device fabrication. These institutions capture margin through direct additive manufacturing partnerships rather than traditional vendor catalogs.
- Surgical Centers:Ambulatory orthopedic facilities concentrate on high-volume joint replacement procedures where CNC-milled implants retain cost advantages, constraining additive penetration to complex revision cases.
- Orthopedic Clinics:Private practice settings drive demand for patient-specific cutting guides and instrumentation.
- Dental Clinics:Chairside intraoral scanning and same-day milling compress restoration timelines.
Hospitals anchor premium patient-specific volume. Surgical Centers are rotating up the share rankings as outpatient joint replacement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German titanium powder suppliers export spherical Ti-6Al-4V feedstock to additive manufacturing hubs in the United States and China, establishing a tripolar trade corridor that concentrates high-grade implant production across three regulatory jurisdictions.
United States
FDA 510(k) pathway streamlining accelerates commercialization timelines for titanium cranial plates and acetabular cups. Academic medical centers in Boston and Philadelphia consolidate procurement around integrated software-to-sterile-field contracts. The FDA's dedicated review track for additively manufactured devices compresses design-to-delivery timelines from months to days.
Germany
Bavarian and Baden-Württemberg manufacturing clusters aggregate titanium powder supply, electron beam melting capacity, and EMA regulatory expertise for European distribution. EMA MDR technical documentation requirements extend certification timelines but reinforce quality leadership. Gas atomization facilities in Hagen and Kamp-Lintfort anchor spherical powder supply for implant fabricators across the continent.
China
NMPA dedicated technical review guidelines for additively manufactured medical devices align regulatory incentives with dual carbon goals that favor material-efficient production. Domestic manufacturers in Shanghai and Beijing restructure documentation workflows to align with these standards. Shenzhen and Guangzhou dental laboratories absorb the fastest capacity expansion as pathway streamlining accelerates domestic commercialization.
Japan
PMDA regulatory frameworks govern patient-specific implant commercialization with emphasis on post-market surveillance harmonization with ISO 13485 standards. Kanto region orthopedic trauma centers pilot multi-material deposition systems for complex pelvic reconstruction. METI industrial policy supports additive manufacturing technician training programs to address qualified operator scarcity.
Switzerland
Swissmedic quality system requirements reinforce precision manufacturing traditions in orthopedic implant fabrication. Zurich and Basel clusters specialize in CNC machining substitution analysis for cobalt-chrome knee implants where additive methods compete with five-axis milling. The country's medical device export infrastructure serves as a distribution gateway for European and Middle Eastern markets.
3D Medical Implant Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates premium patient-specific volume among integrated software-to-manufacturing platforms while fragmenting dental and surgical guide segments among regional fabricators. Three archetypes dominate: diversified orthopedic conglomerates with additive manufacturing partnerships, pure-play additive technology licensors, and hospital-captive fabrication services. Competitive moves center on M&A for digital workflow integration and capacity expansion in electron beam melting installations.
Among diversified orthopedic conglomerates, Stryker Corporation and Zimmer Biomet Holdings Inc occupy positions anchored by extensive implant portfolios and transitioning quality systems. Materialise NV exemplifies the pure-play specialist archetype, sustaining differentiation through regulatory-compliant image processing and surgical guide engineering. These three entities represent distinct strategic postures within a competitive set that spans software-to-manufacturing integration, regulatory navigation, and hospital-direct distribution models.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings Inc |
| Materialise NV |
| 3D Systems Inc. |
| Stratasys Ltd. |
| Medtronic plc |
| Johnson & Johnson |
| EnvisionTEC GmbH |
| Arcam AB |
| Others |
Pricing and Supply Chain Analysis
German gas atomization facilities in Hagen and Kamp-Lintfort concentrate spherical Ti-6Al-4V powder supply, anchoring margin pools downstream with implant fabricators who index long-term contracts to titanium sponge commodity benchmarks. This upstream concentration forces orthopedic device manufacturers to absorb feedstock volatility while competing on patient-specific premium pricing.
Pricing Analysis
Cost-plus contracts with titanium powder indexation dominate procurement between German atomizers and implant fabricators, creating pricing stratification across premium patient-specific, standard modular, and economy catalog tiers. Price differentiation hinges on FDA 510(k) certification tier and surgical planning software bundling. Cost compression in economy-tier joint replacements intensifies as CNC-milled cobalt-chrome retains cost advantages above 500 annual units. Academic medical centers show lowest price sensitivity due to bundled software-to-sterile-field contracts, while ambulatory surgical centers prioritize per-unit procurement economics.
Supply Chain Analysis
Supplier-financing facilities extended by German powder producers ease working capital strain for mid-tier electron beam melting operators purchasing spherical Ti-6Al-4V feedstock. Supply concentrates in Germany, China, and the United States, with Chinese titanium sponge integration climbing fastest. Raw material dependencies center on gas-atomized titanium alloys, cobalt-chrome feedstock, and bioresorbable polymer pellets. Single-source vulnerability concentrates around limited qualified electron beam melting technicians. Distribution runs through direct-to-hospital digital platforms that displace traditional orthopedic device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron beam melting operator scarcity constrains production scaling across the value chain, rewarding stakeholders who secure qualified personnel or automated platform capacity ahead of demand inflection.
For Market Incumbents: Entrench software-to-manufacturing integration by acquiring surgical planning platform capabilities and expanding electron beam melting capacity in Bavarian clusters. CNC machining substitution for high-volume joint replacements threatens additive margin pools; counter through patient-specific revision surgery volume capture and hospital-captive fabrication partnerships that lock academic medical center procurement. For New Entrants and Emerging Players: Establish a beachhead in bioresorbable polymer craniomaxillofacial applications where polycaprolactone and polylactic acid lattice structures face limited incumbent competition. Pediatric trauma centers in Boston and Philadelphia represent the most penetrable end-user segment. Pursue direct-to-laboratory digital distribution for Shenzhen and Guangzhou dental laboratories to bypass established vendor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play additive technology licensors with regulatory-compliant quality systems and hospital-direct distribution infrastructure. Long-term viability across the analysis window favors entities bridging software-to-sterile-field service contracts. Watch FDA De Novo pathway accumulation for bioresorbable implants as the signal indicating inflection toward polymer-based patient-specific fabrication.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Streamlining | Accelerates titanium cranial plate and acetabular cup commercialization timelines. |
| Hospital System Partnership | Enables direct-to-sterile-field procurement bypassing traditional distributor networks. |
| Software Companion Development | Integrates DICOM-derived surgical planning with lattice generation for patient-specific pore architectures. |
| CE Marking Pathway | Opens European distribution through EMA MDR technical documentation alignment. |
| Reimbursement Strategy | Secures CMS and private payer coverage for patient-specific implant procedures. |
Research Methodology
Cross-validation between primary interviews with orthopedic surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers and secondary validation against FDA 510(k) filings, EMA MDR submissions, hospital procurement databases, and CMS Medicare reimbursement data anchors the qualitative findings. Bottom-up demand modeling triangulates with top-down market sizing across fabrication technology, anatomical application, and procurement setting segmentation.
Calibration against historical electron beam melting capacity expansion and selective laser sintering installation rates validates the analytical framework across the projection horizon. Segmentation dimensions include product type, material, technology, and end user, with patient-specific versus standard modular fabrication depth as an additional modeled layer. CAGRs derive from implant procedure volume trajectories and additive manufacturing adoption curves in orthopedic, dental, and cranial reconstruction segments.
Sensitivities concentrate around FDA review timeline variability, titanium powder supply disruption, and EMA MDR enforcement tightening. Forecasts reflect assumptions regarding regulatory pathway streamlining and hospital procurement consolidation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Veterinary Orthopedic Drills Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market
Orthopedic Devices
Animal External Fixation Market
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
Europe Orthopedic Navigation Systems Market
Orthopedic Devices
Global Artificial Joints Market