
 Bedwetting Alarm Market | 2026-2036
Bedwetting Alarm Market Size, Share, and Industry Trends Forecast 2026-2036
Bedwetting Alarm Market Insights
Pediatric home care is broadening as the dominant demand channel for bedwetting alarms, displacing institutional procurement. Malem Medical leverages decades of clinical validation to sustain brand authority across European pharmacies. Chummie specializes in compact, child-friendly form factors that anchor its position in direct-to-consumer online channels. DryBuddy competes through extended wireless range specifications that appeal to parents seeking monitoring flexibility.
A bedwetting alarm is a wearable or bedside electronic device that detects moisture through conductive sensors and triggers an audible, tactile, or visual alert to condition the user toward nocturnal continence; typical units operate at 20-85 decibels with moisture response thresholds under two seconds. Wired alarms retain cost advantages in bulk institutional procurement, while wireless alarms capture the fastest household growth due to improved child comfort and reduced false-trigger rates. Combination technology integrating sound, light, and mobile app connectivity commands premium positioning, whereas standalone sound-based units occupy the economy tier.
FDA 510(k) clearance requirements govern device safety and electromagnetic compatibility for products distributed in the United States, while CE marking under the EU Medical Device Regulation shapes market access across European Economic Area member states. ISO 13485 certification serves as a baseline quality management expectation that distributors and healthcare providers verify before contractual engagement. Stakeholders must monitor evolving digital health app regulations, as software-enabled alarms with cloud-based progress tracking attract heightened data governance scrutiny from regulators and privacy advocates alike.
Market Dynamics
Pediatric home care is displacing institutional procurement as the dominant channel, driven by statutory reimbursement frameworks and parental preference for privacy-preserving treatment environments. Wireless sensor miniaturization and mobile health integration are compressing product development cycles while elevating performance expectations.
Growth Catalysts
- Statutory Health Insurance Reimbursement:Germany's statutory health insurance system covers bedwetting alarms, eliminating out-of-pocket costs and accelerating household penetration beyond clinical settings.
- Bluetooth Low Energy:Wireless moisture detection systems with sub-two-second response thresholds are replacing wired units, improving child comfort and reducing false-trigger rates that previously undermined treatment adherence.
- Pediatric Urology Clinic Networks:Expanding specialist referral pathways in France, the United Kingdom, and the Netherlands are normalizing alarm-based enuresis management as first-line intervention.
Market Restraints
- Lithium Battery Supply Concentration:Dependence on East Asian cell manufacturers creates input cost volatility and extended lead times for wireless alarm production.
- FDA 510(k) Timeline Friction:Electromagnetic compatibility validation and clinical data requirements extend U.S. market entry by 12-18 months compared to CE-marked equivalents.
- Pharmaceutical Substitution:Desmopressin and anticholinergic prescriptions retain physician preference in markets with limited device reimbursement, compressing addressable demand.
Strategic Opportunities
- Direct-to-Consumer Telehealth Integration:Pediatric telehealth platforms in the United States and United Kingdom are creating embedded distribution channels that bypass traditional pharmacy and clinic procurement.
- Cloud-Based Progress Tracking:Software-enabled alarms with encrypted data storage align with GDPR and emerging FDA digital health guidance, opening subscription revenue models.
- India:Rising pediatric urology specialization and expanding private health insurance penetration create first-mover potential in an underpenetrated market with limited domestic manufacturing.
Industry Challenges
- ISO 13485 Certification Timeline:Quality management system implementation and notified body audits delay commercial launch for emerging manufacturers by 8-14 months.
- Electromagnetic Interference Testing:Ensuring compatibility with household Wi-Fi, baby monitors, and medical devices requires specialized lab capacity that concentrates in Germany, the United States, and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bedwetting Alarm Market |
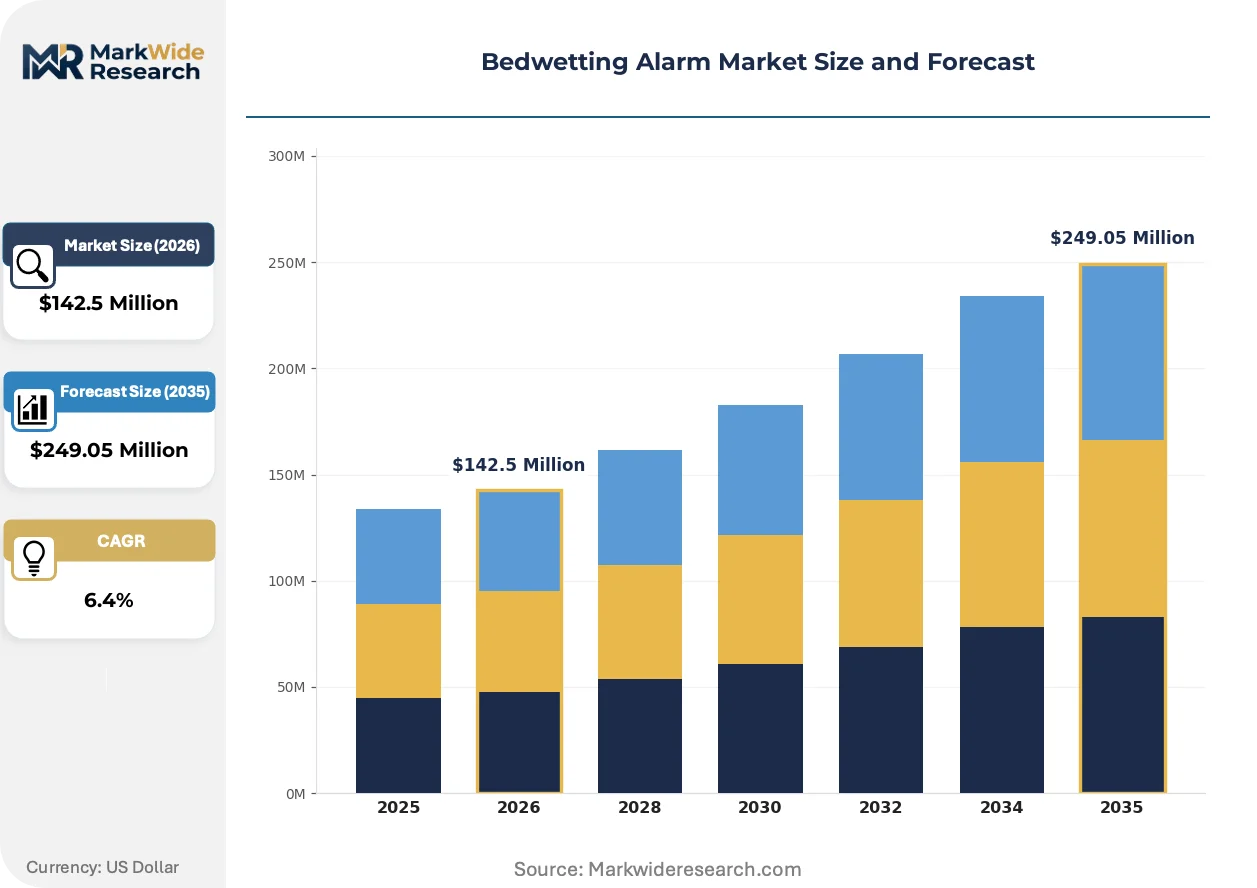
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $249.05 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Alarms, Wired Alarms, Vibration Alarms, Bed Sensors End User: Parents, Healthcare Providers, Retailers, Care Facilities Technology: Sound, Light, Mobile App, Combination Distribution Channel: Online Stores, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Shield, Guardian, Rodger, TheraPee, Wet-Stop, Malem Medical, Chummie, DryBuddy, DRI Sleeper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bedwetting Alarm Market Trends and Innovations
Moisture detection technology is converging with consumer electronics design languages, compressing the perceptual gap between medical devices and wearable wellness products. Regulatory frameworks for software-enabled medical devices are tightening simultaneously, reshaping competitive requirements.
Capacitive sensor arrays are integrating haptic feedback and multi-tone audible alerts into single wearable units, replacing discrete moisture pads with garment-integrated detection. Parents of children aged 5-10 are adopting these systems at the fastest rate, drawn by reduced sleep disruption and elimination of bedside hardware. This convergence is integrating sleep-monitoring functionality that previously required separate consumer devices, expanding per-unit value capture while compressing the addressable market for standalone sleep trackers.
CE marking under the EU Medical Device Regulation is requiring enhanced clinical evidence for wireless alarms with data transmission capabilities, elevating documentation burdens for manufacturers. Notified bodies in Germany and the Netherlands are applying heightened scrutiny to cybersecurity claims and cloud architecture disclosures. Pediatric urology distributors across France, Belgium, and Austria are prioritizing MDR-certified inventory, creating a two-tier market that favors established quality management systems over newer entrants.
Subscription-based remote monitoring is replacing one-time device sales in premium segments, with parents paying monthly fees for clinician dashboard access and automated progress reports. Hospital-affiliated home care programs in Sweden and Denmark are piloting this model, displacing traditional pharmacy retail for initial device acquisition. This shift is most visible in Nordic markets where integrated electronic health record systems enable seamless data exchange between home devices and pediatric clinics.
Bedwetting Alarm Market Segmentation
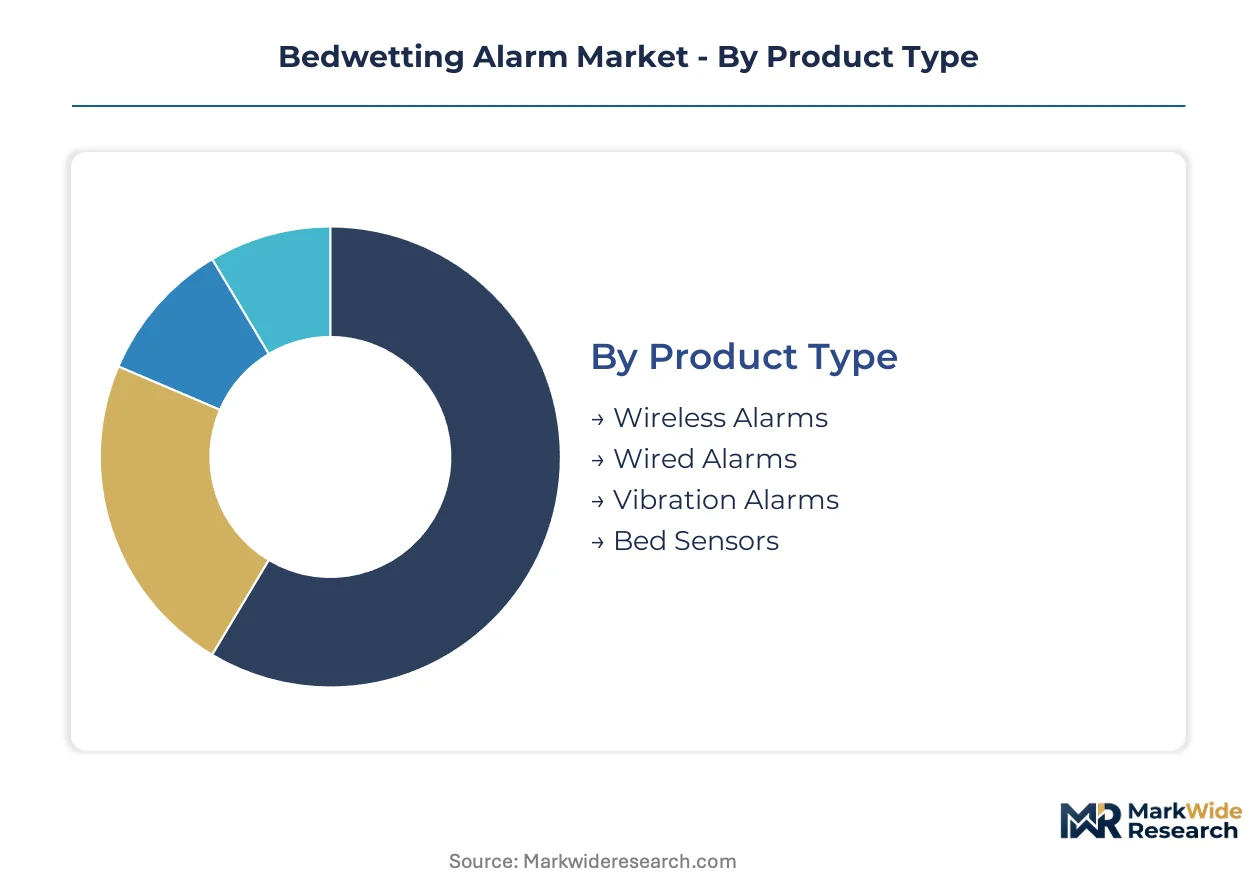
Bedwetting alarm manufacturers must align product architectures with distinct regulatory pathways and reimbursement eligibility. Segment boundaries increasingly blur as wireless connectivity and mobile health integration reshape hardware requirements across all categories.
Product Type:
FDA 510(k) clearance and CE marking under MDR impose divergent electromagnetic compatibility testing burdens depending on connectivity architecture and power source.
- Wireless Alarms:Bluetooth Low Energy modules with sub-two-second moisture response thresholds eliminate tethered connections that disrupt sleep positioning. Pediatric home care channels in Germany and the United States concentrate demand here, driven by statutory reimbursement frameworks and parental preference for child mobility.
- Wired Alarms:Conductive sensor cables connecting moisture pads to bedside control units retain cost advantages in institutional bulk procurement. Healthcare providers in France and the Netherlands specify these for clinic-based enuresis programs where device inventory turnover and standardized maintenance protocols outweigh convenience considerations.
- Vibration Alarms:Silent haptic alerts suit shared sleeping environments and hearing-impaired users. Compact wrist-worn form factors from Korean and Japanese manufacturers penetrate direct-to-consumer channels in urban households seeking discretion.
- Bed Sensors:Capacitive arrays integrated into mattress overlays detect moisture without wearable components. Specialist retailers in Sweden and Denmark stock these for parents rejecting garment attachment entirely.
Wireless Alarms sits at the top of the volume ranking, with Vibration Alarms climbing the fastest.
End User:
Procurement authority and reimbursement access create four distinct customer archetypes with incompatible purchasing rhythms and technical support expectations.
- Parents:Direct purchasers prioritize child comfort, false-trigger reduction, and mobile app integration for progress visualization. Online review platforms and pediatric telehealth referrals increasingly shape selection in the United States and United Kingdom.
- Healthcare Providers:Pediatric urology clinics and general practitioners specify devices based on clinical validation literature and distributor contractual terms. Procurement concentrates through group purchasing organizations in hospital-affiliated networks.
- Retailers:Pharmacy chains and medical supply distributors curate inventory based on margin structure, return rates, and regulatory documentation completeness. German pharmacy purchasing cooperatives enforce ISO 13485 verification before listing.
- Care Facilities:Residential treatment centers and group homes demand ruggedized hardware with centralized monitoring capabilities. Bulk pricing and extended warranty terms dominate vendor selection.
Parents command the largest addressable base, though Healthcare Providers are expanding most quickly through specialist referral pathway development.
Technology:
Alert modality selection determines software regulatory exposure and subscription revenue potential.
- Sound:Variable-frequency audible alerts between 20-85 decibels remain the baseline configuration. Economy-tier units rely exclusively on acoustic signaling without data capture capabilities.
- Light:Visual indicators supplement or replace auditory alerts for hearing-impaired users and households with multiple children. Nordic markets show concentration here due to inclusive design regulations.
- Mobile App:Cloud-connected progress tracking triggers GDPR compliance obligations and FDA digital health guidance scrutiny. Encrypted data architecture and clinician dashboard access command recurring subscription fees.
- Combination:Integrated sound, light, haptic, and app connectivity occupies premium positioning. MDR notified bodies in Germany and the Netherlands apply heightened cybersecurity documentation requirements to these systems.
Combination technology captures the steepest expansion trajectory as parents consolidate alert modalities and clinics seek remote monitoring integration.
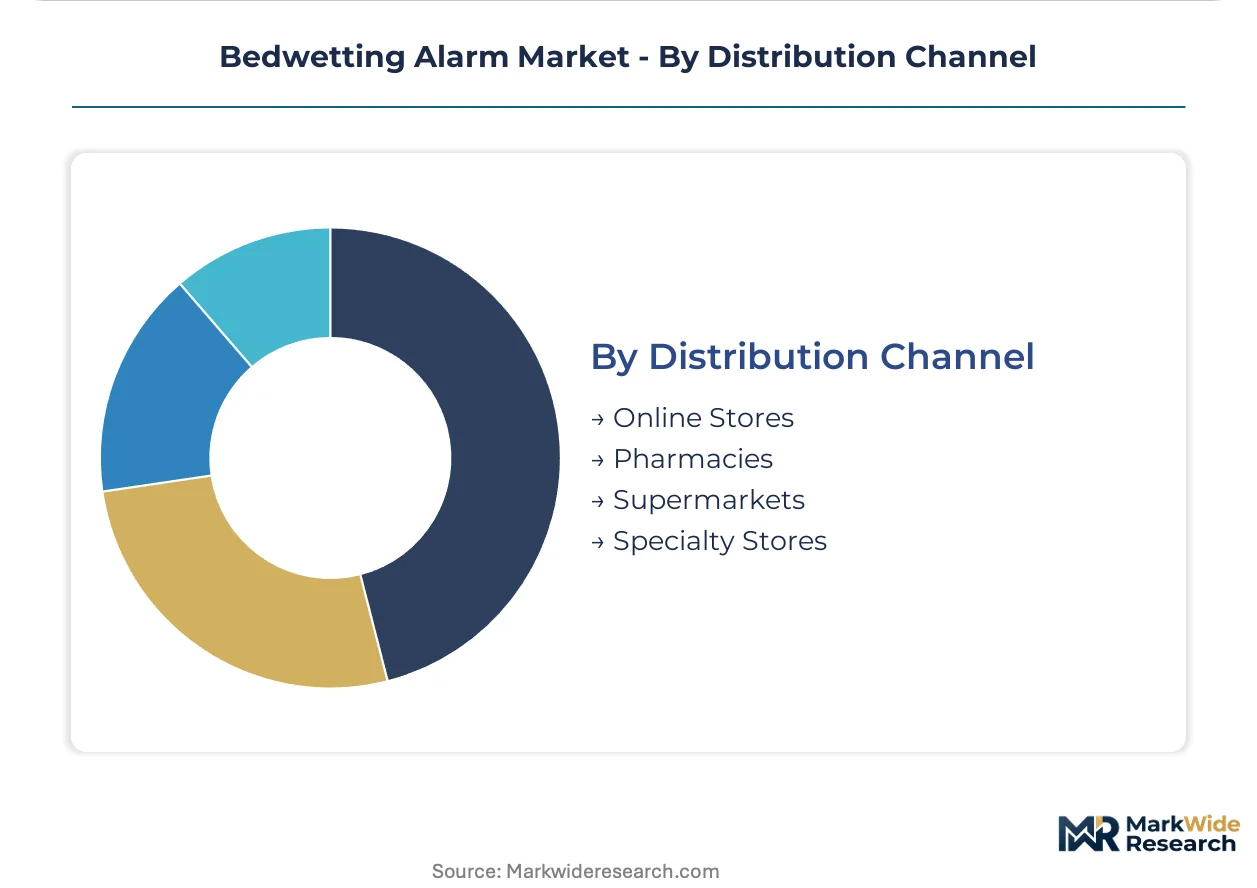
Distribution Channel:
Channel selection dictates pricing architecture, customer education burden, and post-purchase support infrastructure requirements.
- Online Stores:Direct-to-consumer platforms and marketplace aggregators dominate volume in markets with limited statutory reimbursement. Return logistics and customer service automation absorb significant operational overhead.
- Pharmacies:German statutory health insurance reimbursement flows exclusively through pharmacy networks, creating a protected channel with mandatory prescription or physician referral documentation.
- Supermarkets:Mass retail placement reaches price-sensitive segments with simplified, non-connected product variants. Shelf space negotiations favor established consumer health brands with existing foot traffic conversion.
- Specialty Stores:Medical supply retailers and pediatric equipment boutiques provide hands-on demonstration and fitting services. Higher staff training requirements limit geographic density.
Online Stores lead absolute transaction volume, with Specialty Stores gaining share fastest through personalized fitting services and insurance claims assistance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate final assembly to jurisdictions with streamlined medical device clearance pathways. CE marking under the EU Medical Device Regulation imposes shorter documentation timelines than FDA 510(k) processes, drawing wireless alarm assembly toward European contract manufacturers.
Germany
Statutory health insurance reimbursement eliminates out-of-pocket costs for pediatric households, driving the highest per-capita penetration rate among major economies. The BfArM and notified bodies in Berlin and Munich enforce MDR compliance with particular scrutiny of cybersecurity documentation for cloud-connected devices. Manufacturing clusters in Baden-Württemberg concentrate on precision sensor fabrication for export to Nordic markets.
United States
Pediatric telehealth expansion and direct-to-consumer online channels are displacing traditional pharmacy procurement. FDA 510(k) clearance requirements for electromagnetic compatibility extend market entry timelines by 12-18 months compared to European equivalents. Device assembly concentrates in Minnesota and Massachusetts medical technology corridors, leveraging proximity to pediatric urology research hospitals.
United Kingdom
NHS specialist referral pathways for enuresis management are normalizing alarm-based first-line intervention. The MHRA's post-Brexit regulatory framework maintains alignment with MDR standards while streamlining notified body access for domestic manufacturers. London and Cambridge clusters specialize in software-enabled alarms with encrypted progress tracking for GDPR compliance.
Sweden
Integrated electronic health record systems enable seamless data exchange between home devices and pediatric clinics, accelerating subscription-based remote monitoring pilots. The Swedish Medical Products Agency applies heightened scrutiny to cloud architecture disclosures for wireless alarms. Medical technology distributors in Stockholm and Gothenburg prioritize MDR-certified inventory with clinician dashboard capabilities.
India
Rising pediatric urology specialization and expanding private health insurance penetration create first-mover potential in an underpenetrated market. The CDSCO's medical device rules are converging toward ISO 13485 quality management expectations for imported alarms. Manufacturing investment concentrates in Karnataka and Tamil Nadu electronics corridors, targeting cost-sensitive wireless sensor production for domestic and Southeast Asian markets.
Bedwetting Alarm Market Competitive Landscape
Strategic partnerships dominate the current landscape as established players secure distribution access through pediatric telehealth platforms and pharmacy purchasing cooperatives. The vendor base fragments across three tiers: legacy clinical validators with decades of physician relationships, direct-to-consumer specialists optimizing child-friendly form factors, and wireless technology providers competing on sensor response specifications. Two archetypes define positioning: quality-system-heavy incumbents defending institutional procurement channels, and agile hardware startups capturing online household demand. Portfolio diversification into subscription software services and geographic expansion into underpenetrated Asian markets represent the dominant competitive moves.
Within the clinical validation tier, Malem Medical exemplifies decades-long brand authority sustained through European pharmacy networks and pediatric urology distributor relationships. Chummie occupies a position in the direct-to-consumer vector, its compact design archetype resonating with parents prioritizing child comfort and sleep disruption minimization. DryBuddy anchors the wireless specification segment, representing parental demand for monitoring flexibility through extended sensor-to-receiver range capabilities.
| Leading Market Players |
|---|
| Shield |
| Guardian |
| Rodger |
| TheraPee |
| Wet-Stop |
| Malem Medical |
| Chummie |
| DryBuddy |
| DRI Sleeper |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate spot pricing volatility cascades through wireless alarm manufacturing, compressing margins on Bluetooth-enabled units while amplifying cost advantages for wired sensor alternatives in institutional procurement channels.
Pricing Analysis
Pharmacy cooperative margins in Germany absorb statutory reimbursement flows, compressing manufacturer net pricing by 15-25 points versus direct-to-consumer online channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by connectivity architecture and certification grade, with MDR-notified body documentation commanding measurable premiums. Pricing pressure stems from East Asian cell manufacturer consolidation and extended FDA 510(k) timelines that defer revenue recognition. Parents purchasing through telehealth referrals exhibit lowest price sensitivity, while mass retail supermarket buyers demand stripped-down acoustic-only configurations.
Supply Chain Analysis
Direct-to-consumer channels handle hyperscale household demand through automated fulfillment networks, while pharmacy and clinic procurement flows through distributor intermediaries with ISO 13485 verification requirements. Manufacturing concentrates in Baden-Württemberg precision sensor clusters, Minnesota medical technology corridors, and Karnataka electronics assembly zones. Lithium-ion cells, conductive polymer sensors, and Bluetooth Low Energy modules constitute critical input dependencies. Single-source vulnerability in East Asian battery supply creates exposure to export licensing disruptions. Distribution runs through pediatric urology clinic networks in reimbursed markets and marketplace aggregators elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into competitive moats, with the EU Medical Device Regulation's enhanced clinical evidence requirements for wireless data transmission capabilities accelerating consolidation around established quality management systems.
For Market Incumbents: Anchor market position through backward integration into precision sensor fabrication and MDR certification maintenance. Pharmaceutical substitution pressure from desmopressin prescriptions demands defensive investment in clinician dashboard software to demonstrate outcome superiority. ISO 13485 audit readiness separates defendable institutional procurement relationships from vulnerable distributor arrangements.
For New Entrants and Emerging Players: Capture white-space opportunity in India's underpenetrated pediatric urology segment through CDSCO-aligned quality system investment and private insurance partnership development. Direct-to-consumer telehealth integration in the United States offers the most penetrable channel bypass. Lead with vibration-alarm form factors that sidestep electromagnetic compatibility documentation burdens of wireless connectivity.
For Investors and Strategic Acquirers: Asymmetric upside sits with software-enabled alarm developers possessing encrypted cloud architecture and GDPR-compliant data governance. Long-term viability hinges on subscription revenue model validation through Nordic hospital-affiliated home care pilots. Monitor FDA digital health guidance finalization as inflection signal for U.S. market entry timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway | Notified body documentation in Germany and the Netherlands unlocks pharmacy cooperative listing access. |
| Software Companion Development | Encrypted progress tracking aligns with GDPR and emerging FDA digital health guidance requirements. |
| Hospital System Partnership | NHS specialist referral pathways in the United Kingdom normalize alarm-based first-line intervention protocols. |
| Reimbursement Strategy | Statutory health insurance alignment in Germany eliminates household out-of-pocket cost barriers. |
| Geographic Expansion | CDSCO convergence toward ISO 13485 in India creates first-mover manufacturing and distribution positioning. |
Research Methodology
Coverage spans Germany, the United States, the United Kingdom, Sweden, and India, with primary inputs from each market cluster combining interviews with pediatric urologists, biomedical engineers, GPO contracts managers, and pharmacy purchasing cooperative representatives. Secondary validation draws from FDA 510(k) filings, BfArM device registrations, NHS procurement databases, and CDSCO import notifications. Bottom-up unit demand modeling triangulates against top-down reimbursement flow analysis.
Rate-of-change decomposition separates volume expansion from price trajectory shifts across the analysis window. Segmentation dimensions include product architecture, end-user procurement authority, alert modality technology, and distribution channel structure. CAGRs derive from regression analysis of historical statutory reimbursement expansion, telehealth platform penetration curves, and pediatric urology specialist density ratios. Bluetooth Low Energy adoption velocity and cloud-connected alarm subscription attach rates constitute industry-specific forecast inputs.
Regulatory timeline delays, battery supply disruption, and pharmaceutical substitution acceleration are the dominant revision risks warranting scenario overlay analysis. Forecasts reflect documented assumptions regarding reimbursement policy continuity and MDR notified body capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Helium Free MRI Scanners Market
Medical Devices
Robotic Catheterization Systems Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Microdebrider Market
Medical Devices
Australia Drug Delivery Devices Market
Medical Devices
Medical Smart Glasses Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Global Prosthetics Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
Canada Spinal Surgery Devices Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market