
 Ligament Stabilizers Market | 2026-2036
Ligament Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Ligament Stabilizers Market Analysis
Advanced composite weaving and 3D-printed lattice structures is reshaping how ligament stabilizers achieve anatomical conformity and load distribution. Bauerfeind AG leverages its German engineering heritage to sustain premium positioning across European physiotherapy channels. DJO Global, Inc competes through extensive hospital contracting networks in North America. THUASNE SA anchors its presence in professional sports partnerships, particularly within European football and rugby leagues.
Ligament stabilizers are orthopedic devices engineered to restrict pathological joint motion, typically constructed from neoprene composites with integrated aluminum or carbon fiber stays calibrated to specific torque thresholds, serving to protect healing grafts or prevent injury recurrence during dynamic loading. Braces dominate value capture due to reimbursement codes tied to post-surgical protocols, while tapes represent the fastest-expanding category among amateur sports participants seeking low-cost proprioceptive feedback. Neoprene formulations retain margin pools through material science differentiation, though nylon blends are gaining share in tropical climates where breathability determines compliance.
The FDA's 510(k) framework governs market entry for class II orthopedic devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on manufacturers seeking CE marking for European distribution. Germany's national reimbursement catalogue, maintained by the Institut für das Entgeltsystem im Krankenhaus, directly determines hospital purchasing volumes for post-operative brace provision. Stakeholders must monitor evolving sports concussion protocols that increasingly bundle lower-extremity injury prevention into comprehensive athlete health frameworks.
Market Dynamics
Advanced composite weaving and 3D-printed lattice structures are compressing traditional manufacturing timelines while forcing legacy brace architectures toward obsolescence. The FDA's 510(k) clearance pathway continues to filter which innovations reach ambulatory surgery centers fastest.
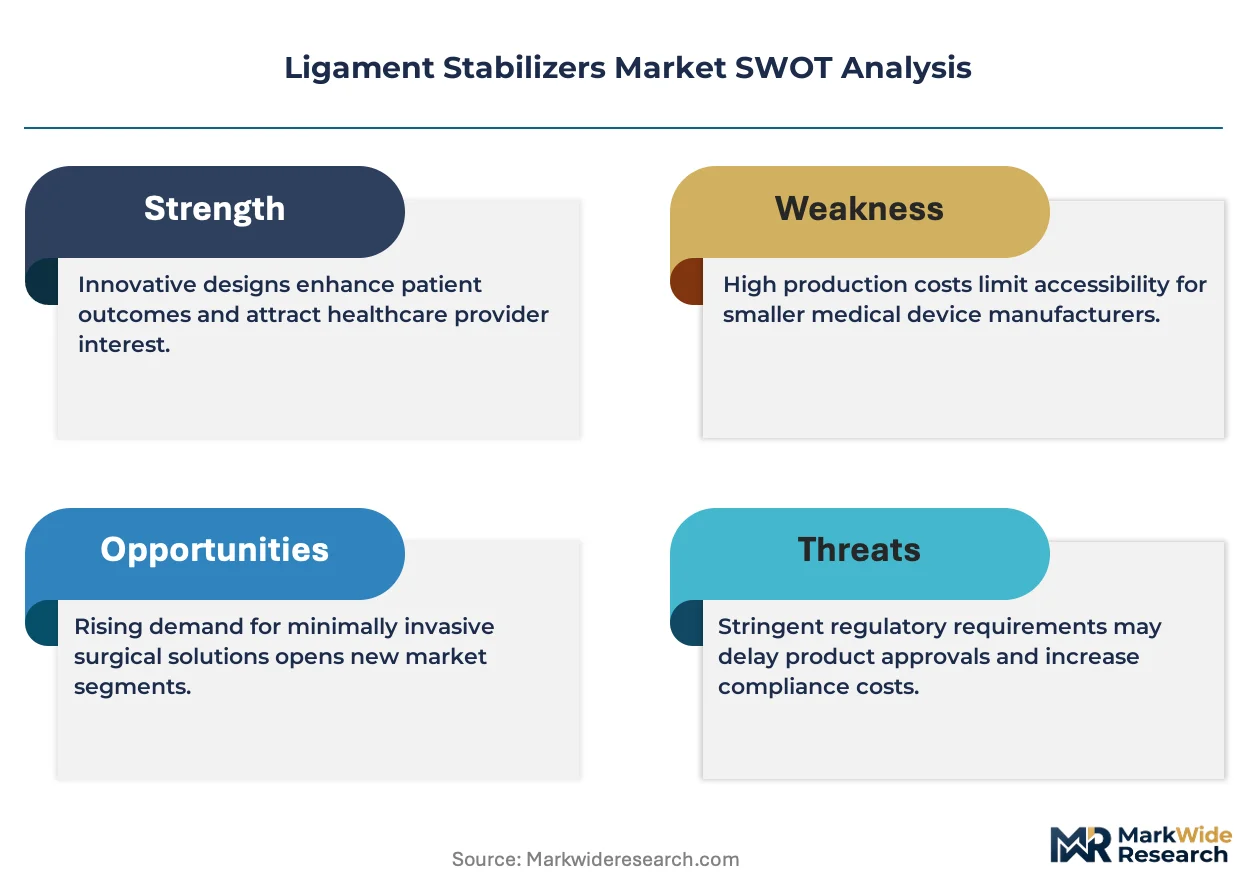
Growth Catalysts
- Collegiate Sports Medicine Expansion:University athletic departments are embedding functional braces into standardized anterior cruciate ligament injury protocols, creating institutional procurement pipelines that lock in multi-year supply agreements.
- EU Medical Device Regulation Harmonization:The MDR's stricter clinical evidence requirements are paradoxically accelerating consolidation among compliant manufacturers, concentrating market access for firms that invested early in European notified body relationships.
- Neoprene Formulation Science:Material scientists at polymer laboratories in Germany and Japan are engineering temperature-stable elastomers that maintain torque calibration across tropical and alpine climates, expanding addressable patient populations.
Market Restraints
- Aluminum Stay Input Volatility:Carbon fiber substitution rates remain constrained by aerospace sector competition for high-modulus fiber tows, limiting brace manufacturers' ability to hedge against aluminum price swings.
- Single-Source Geography Risk:Taiwan-based semiconductor foundries dominate the sensor chips embedded in smart braces, exposing orthopedic device firms to geopolitical supply interruptions without qualified secondary sources.
- Biomechanical Fidelity Ceiling:Current torque-threshold calibration methods cannot replicate the six degrees of freedom in natural knee kinematics, capping functional outcomes for complex multi-ligament reconstructions.
Strategic Opportunities
- Pediatric Underpenetration:Growth plate-sparing brace designs for adolescent athletes remain clinically underserved, with no dominant incumbent establishing pediatric-specific torque protocols.
- Telehealth Rehabilitation Bundling:Remote patient monitoring platforms are creating new reimbursement codes for brace-integrated motion sensors, opening direct-to-consumer channels previously blocked by prescription requirements.
- India's PLI Scheme Alignment:The Production Linked Incentive scheme for medical devices offers tariff advantages to manufacturers establishing domestic neoprene compounding and aluminum stay fabrication within Indian special economic zones.
Industry Challenges
- Biomechanical Engineering Talent Scarcity:Orthopedic device firms compete with automotive and robotics sectors for finite pools of musculoskeletal modeling specialists fluent in finite element analysis software.
- 510(k) Predicate Device Drift:FDA reviewers are increasingly rejecting substantial equivalence claims based on decades-old brace predicates, forcing manufacturers toward de novo pathways with unpredictable timeline and cost exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ligament Stabilizers Market |
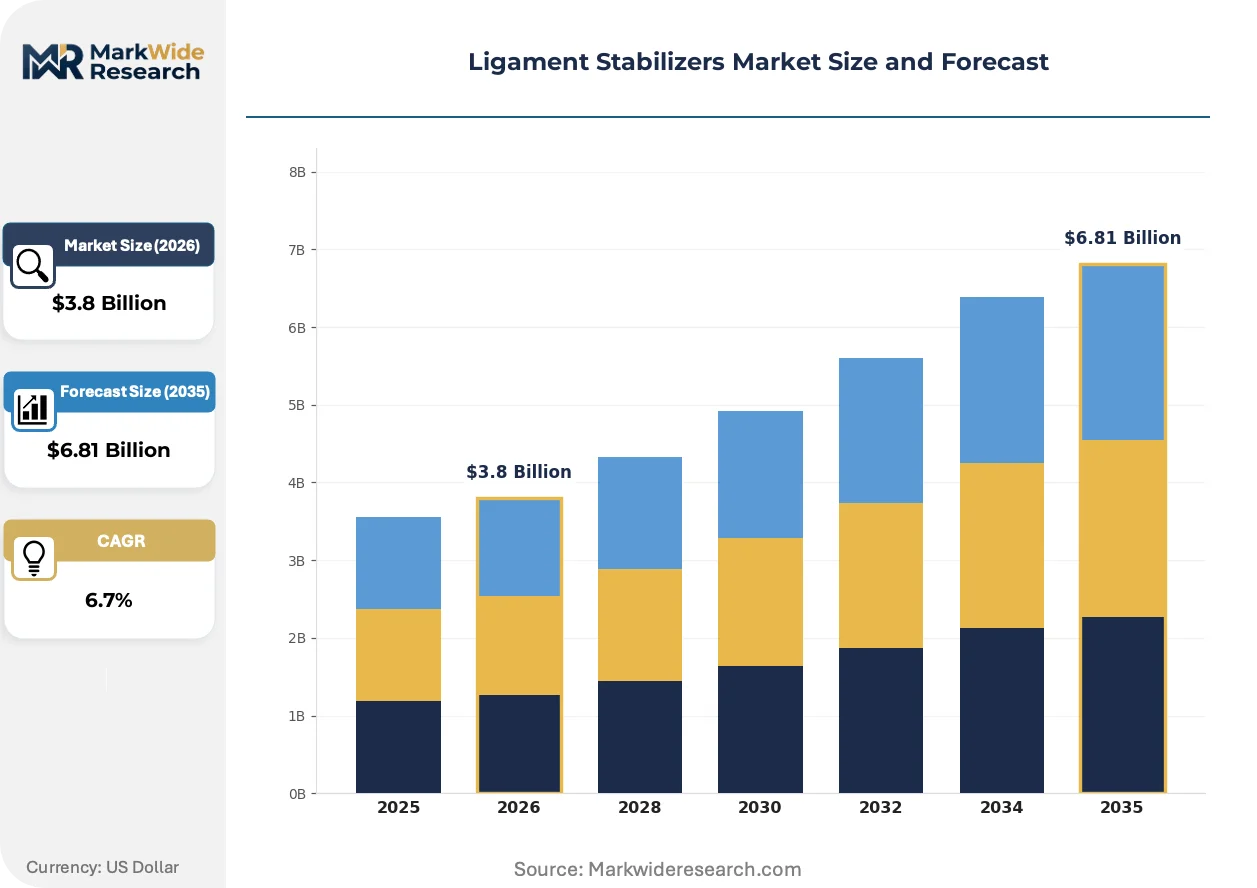
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Supports, Tapes, Sleeves Material: Nylon, Neoprene, Cotton, Plastic End User: Sports Players, Patients, Physiotherapists, Orthopedic Surgeons Distribution Channel: Online Stores, Pharmacies, Hospitals, Clinics |
| Companies Covered | Bauerfeind AG, Breg, Inc, THUASNE SA, Medi GmbH & Co. KG, Otto Bock Healthcare GmbH, Ossur hf, DeRoyal Industries, BSN Medical GmbH, DJO Global, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ligament Stabilizers Market Emerging Trajectories
Digital manufacturing workflows and sensor-embedded orthotics are collapsing the traditional separation between passive bracing and active rehabilitation monitoring. These converging streams are redrawing competitive boundaries between device manufacturers and software platforms.
3D-printed titanium lattice structures with patient-specific porosity gradients are rendering obsolete the manual bending of aluminum stays to approximate anatomical contours. Major orthopedic centers in Switzerland and Australia are adopting these patient-matched implants for revision ligament reconstructions requiring rigid external fixation. The technology is compressing the traditional brace-to-cast continuum into a single adjustable device category.
The EU Medical Device Regulation's post-market surveillance requirements are forcing manufacturers to maintain clinical follow-up databases that track brace performance across real-world rehabilitation timelines. German hospitals now demand these surveillance commitments as contract preconditions, filtering out smaller competitors lacking regulatory infrastructure. The burden falls heaviest on tape and soft-goods categories previously exempt from systematic clinical tracking.
Athletic trainers at professional football and rugby clubs are consolidating vendor relationships around single-source brace suppliers who bundle injury-risk analytics with hardware provision. This concentration is displacing the fragmented procurement patterns where individual physiotherapists selected devices based on personal preference. The shift is most visible in European leagues where club medical departments operate as centralized cost centers rather than decentralized coaching staff functions.
Ligament Stabilizers Market Segmentation
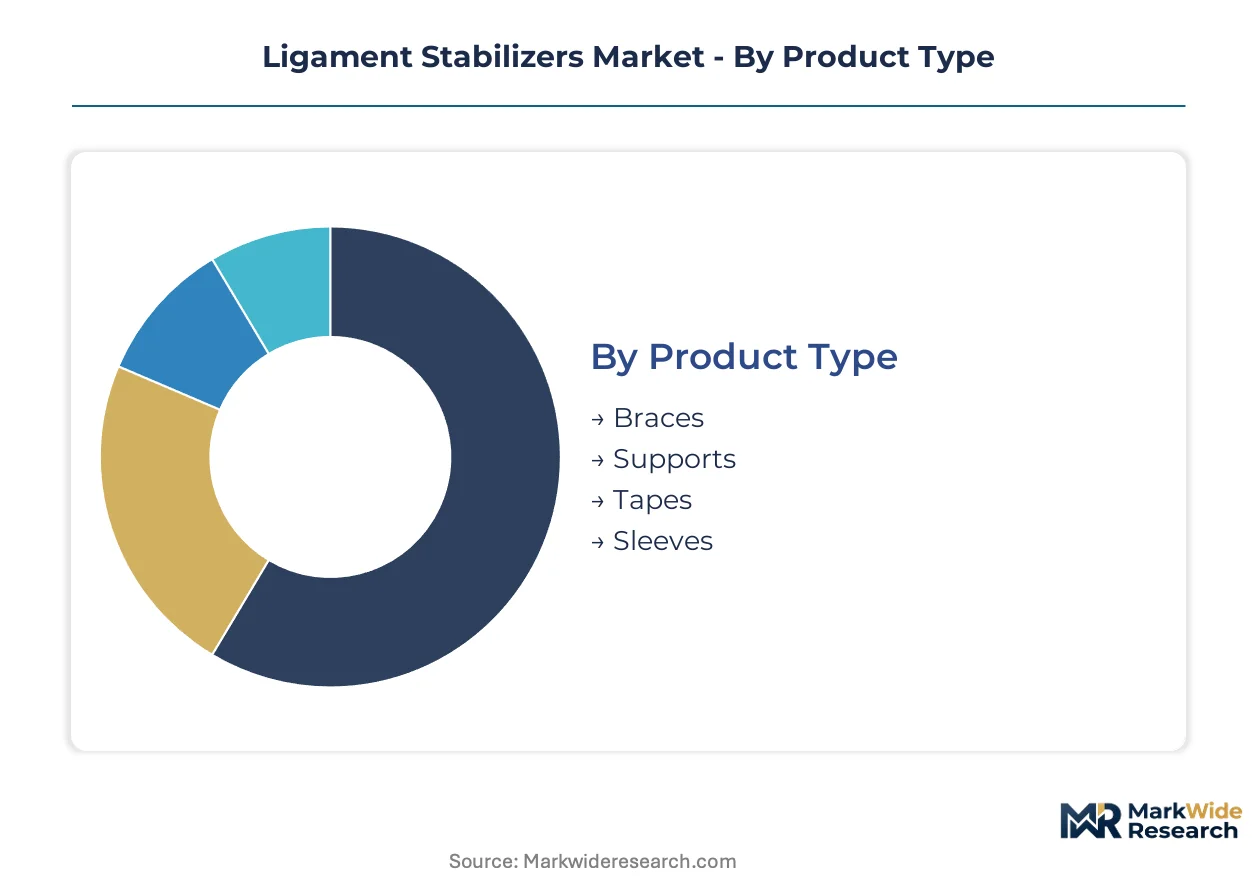
Product architecture in ligament stabilization spans passive mechanical devices through sensor-embedded systems, with procurement cycles varying from single-use tape purchases to multi-year brace contracts. Material selection and channel configuration further stratify margin profiles across acute care, retail, and direct-to-consumer pathways.
Product Type:
Replacement cycles compress from years for rigid braces to weeks for consumable tapes, reshaping inventory strategies across institutional and retail channels.
- Braces:Rigid or semi-rigid structures incorporating aluminum stays, carbon fiber struts, or injection-molded frames calibrated to specific torque thresholds for post-surgical protection. Hospital orthopedic departments in the United States bundle hinged knee braces into anterior cruciate ligament reconstruction discharge protocols, locking in preferred supplier relationships through value-based care contracts.
- Tapes:Adhesive cotton or synthetic strips applied directly to skin for proprioceptive feedback and joint position awareness during dynamic activity. Amateur sports participants in Germany and Australia drive volume through pharmacy and online channels, prioritizing low unit costs over clinical calibration.
- Supports:Elasticized wraps and strap systems providing adjustable compression without rigid structural elements. Physiotherapy clinics in Japan favor these for early-stage rehabilitation where range-of-motion preservation outweighs mechanical blocking.
- Sleeves:Tubular compression garments knitted with graduated elasticity for warmth and mild proprioceptive input. Retail pharmacies in the United Kingdom stock these as first-line self-treatment options for minor joint instability.
Braces anchor the volume base while tapes gain share at the steepest rate.
Material:
Cost tiers separate premium temperature-stable formulations from commodity inputs, with tropical climate demand pulling breathability innovation upward.
- Neoprene:Closed-cell synthetic rubber laminates providing thermal retention, moisture resistance, and consistent elastic modulus across temperature ranges. German polymer laboratories engineer proprietary neoprene blends for Bauerfeind AG's premium positioning in European physiotherapy channels.
- Nylon:Woven or knitted synthetic fibers offering superior moisture wicking and reduced skin irritation in humid environments. Sports medicine programs in Singapore and Brazil specify nylon-dominant constructions for outdoor training compliance.
- Cotton:Natural fiber tapes and wraps valued for skin breathability and hypoallergenic properties. India's domestic manufacturers leverage local cotton supply chains for cost-competitive tape production under the PLI scheme.
- Plastic:Injection-molded polypropylene or polyethylene components for structural frames and buckle systems. Swiss orthopedic centers specify medical-grade plastics for patient-matched 3D-printed lattice brace prototypes.
Neoprene formulations command premium positioning while nylon blends climb fastest on climate-adaptation demand.
End User:
Customer sophistication spans clinical prescription authority through self-directed retail selection, fragmenting go-to-market requirements.
- Orthopedic Surgeons:Specialist physicians prescribing rigid braces as post-operative medical devices with insurance reimbursement codes. United States ambulatory surgery centers integrate surgeon-preferred brands into bundled payment arrangements for ligament reconstruction episodes.
- Sports Players:Amateur through professional athletes purchasing tapes and sleeves for injury prevention and return-to-play confidence. Collegiate athletic departments in Texas and California standardize functional brace procurement across entire football and basketball rosters.
- Patients:Post-operative individuals and chronic instability sufferers obtaining devices through prescription fulfillment or direct retail. Japan's aging population drives pharmacy counter purchases of knee sleeves for osteoarthritis symptom management.
- Physiotherapists:Rehabilitation professionals selecting support-level products for exercise-based recovery protocols. Australian private practice networks negotiate volume discounts for elastic wraps used in anterior cruciate ligament rehabilitation programs.
Orthopedic surgeons anchor the volume base while sports players expand most quickly through direct-to-consumer channel development.
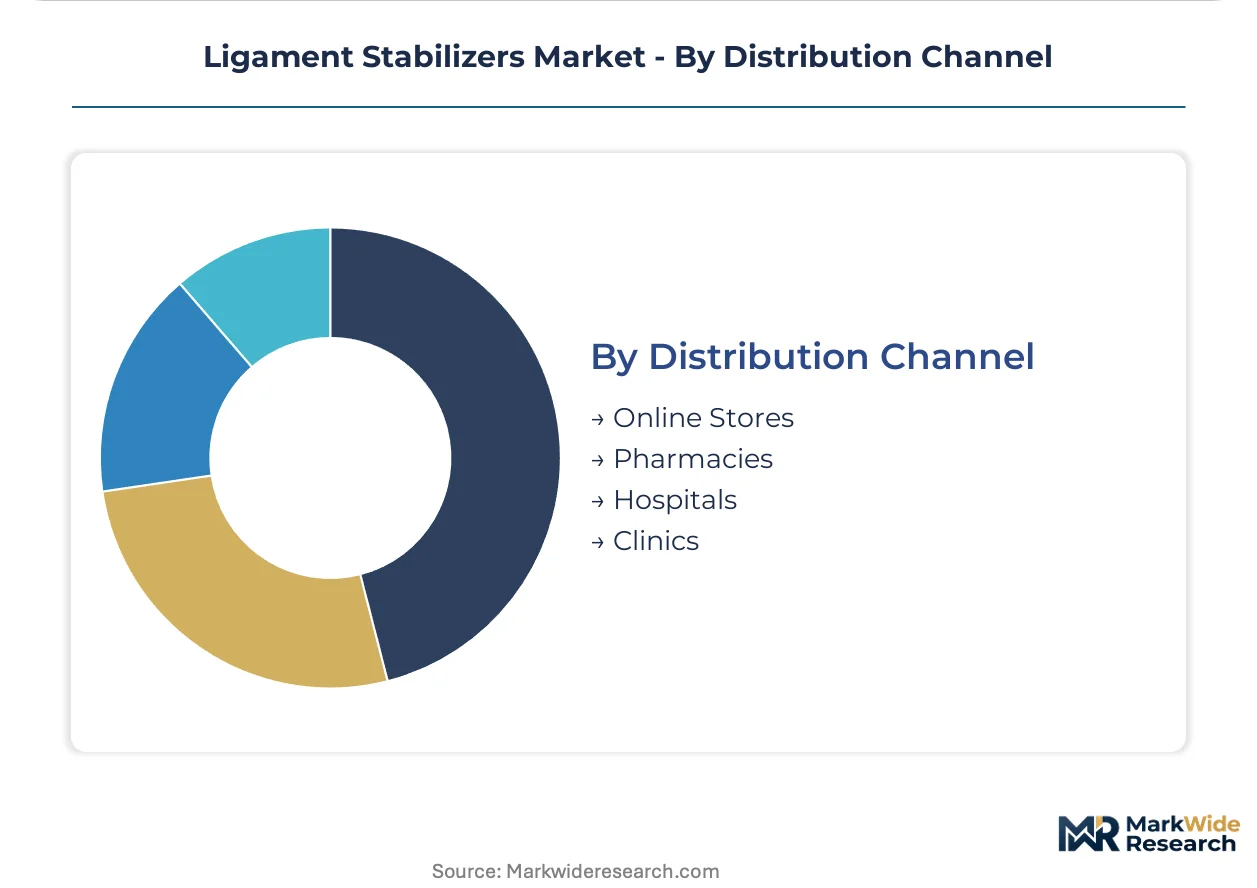
Distribution Channel:
Channel concentration reflects reimbursement system architecture, with institutional procurement separated from retail and digital pathways.
- Hospitals:Integrated delivery networks purchasing braces through group purchasing organizations with contracted formulary restrictions. Germany's Institut für das Entgeltsystem im Krankenhaus reimbursement catalogue directly determines post-operative brace provision volumes.
- Online Stores:E-commerce platforms enabling direct consumer access to tapes, sleeves, and entry-level supports without prescription barriers. Australia's TGA-regulated online pharmacies expand market reach for remote and rural patient populations.
- Pharmacies:Retail drugstore chains stocking consumer-grade supports and tapes for immediate purchase. Boots and Superdrug in the United Kingdom dedicate shelf space to neoprene knee sleeves for self-treating joint pain.
- Clinics:Outpatient orthopedic and sports medicine practices dispensing braces as part of treatment episodes. Physiotherapy clinics in Switzerland bundle brace fitting with manual therapy sessions for comprehensive care delivery.
Hospitals anchor the volume base while online stores gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered neoprene braces to United States ambulatory surgery centers, while Taiwanese semiconductor foundries supply sensor chips for smart brace integration across North American and European assembly lines.
United States
Collegiate athletic departments in Texas and California embed functional braces into standardized anterior cruciate ligament protocols, creating institutional procurement pipelines. The FDA's 510(k) clearance pathway filters which innovations reach ambulatory surgery centers fastest. Minneapolis and San Diego host concentrated orthopedic device clusters where manufacturers refine torque-threshold calibration methods.
Germany
The Institut für das Entgeltsystem im Krankenhaus reimbursement catalogue directly determines hospital purchasing volumes for post-operative brace provision. The EU Medical Device Regulation imposes stricter clinical evidence requirements on manufacturers seeking CE marking. Bavaria's polymer laboratories engineer proprietary neoprene blends sustaining premium positioning across European physiotherapy channels.
Japan
An aging population drives pharmacy counter purchases of knee sleeves for osteoarthritis symptom management in Tokyo and Osaka metropolitan areas. METI oversees medical device standards while PMDA regulates market authorization timelines. The Kansai region concentrates physiotherapy clinic networks negotiating volume discounts for elastic wraps used in rehabilitation programs.
Australia
The TGA-regulated online pharmacies expand market reach for remote and rural patient populations seeking tapes and entry-level supports. Private practice networks in Sydney and Melbourne bundle brace fitting with manual therapy sessions. Swiss-style patient-matched 3D-printed lattice brace prototypes gain traction at major orthopedic centers in Brisbane.
India
The Production Linked Incentive scheme for medical devices offers tariff advantages to manufacturers establishing domestic neoprene compounding within special economic zones. CDSCO regulates orthopedic device imports while state-level health procurement in Maharashtra and Gujarat expands public hospital brace provision. Domestic cotton supply chains support cost-competitive tape production for export to Southeast Asian markets.
Ligament Stabilizers Market Vendor Landscape
On the supply side, the industry is tiered between premium European engineering houses and scale-driven North American distributors. German and Swiss specialists concentrate around material science differentiation and physiotherapy channel relationships. North American players compete through hospital contracting networks and collegiate sports procurement. The dominant competitive moves are strategic partnerships bundling injury-risk analytics with hardware provision, and geographic expansion into India's PLI-advantaged manufacturing zones.
Among German fabricators, Bauerfeind AG and Medi GmbH & Co. KG occupy positions exemplifying the premium engineering archetype sustained through proprietary polymer formulations. DJO Global, Inc represents the North American scale-driven tier competing through extensive institutional contracting networks. THUASNE SA anchors the professional sports partnership vector, particularly within European football and rugby league medical departments.
| Leading Market Players |
|---|
| Bauerfeind AG |
| Breg, Inc |
| THUASNE SA |
| Medi GmbH & Co. KG |
| Otto Bock Healthcare GmbH |
| Ossur hf |
| DeRoyal Industries |
| BSN Medical GmbH |
| DJO Global, Inc |
| Others |
Supply Flow & Price Mechanics
Aluminum stay input volatility compresses margin pools across brace manufacturers while simultaneously forcing supply chain reconfiguration toward carbon fiber substitution and geographic diversification of metal sourcing. This commodity exposure propagates through pricing tiers, widening spreads between premium torque-calibrated devices and economy-grade alternatives.
Pricing Analysis
Next-generation 3D-printed lattice structures command substantial premiums over conventional aluminum-stay braces and legacy neoprene wraps. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, German-engineered polymer formulations, and volume procurement scale. Cost compression in the economy tier intensifies because Indian PLI-advantaged manufacturers expand neoprene compounding capacity. Amateur sports participants exhibit highest price sensitivity, while United States ambulatory surgery centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Extended payment terms from German polymer laboratories and Taiwanese semiconductor foundries strain working capital for brace assemblers lacking supply-chain finance facilities. Manufacturing concentrates in Germany, the United States, and India, with raw material dependencies spanning aerospace-grade carbon fiber tows, medical-grade neoprene laminates, and motion-sensor chipsets. Single-source vulnerability around Taiwan-based foundries exposes orthopedic device firms to geopolitical interruption. Distribution runs through hospital group purchasing organizations, physiotherapy clinic networks, and direct-to-consumer online pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth rehabilitation bundling represents a service-attach opportunity expanding faster than hardware, as remote patient monitoring platforms create new reimbursement codes for brace-integrated motion sensors.
For Market Incumbents: Entrench market position through backward integration into neoprene compounding within India's PLI-advantaged special economic zones, and deepen regulatory infrastructure investments to satisfy EU Medical Device Regulation post-market surveillance commitments that German hospitals now demand as contract preconditions. Carbon fiber substitution threats from aerospace sector competition for high-modulus fiber tows necessitate captive supply arrangements or alternative material science partnerships. For New Entrants and Emerging Players: Pediatric growth plate-sparing brace designs for adolescent athletes represent the most penetrable entry point, as no dominant incumbent has established pediatric-specific torque protocols. India's expanding public hospital procurement in Maharashtra and Gujarat offers institutional volume access, while direct-to-consumer channels bypass prescription barriers through TGA-regulated online pharmacy partnerships in Australia. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors manufacturers with established European notified body relationships and software companion development capabilities. Long-term viability over the next decade hinges on bridging hardware provision with injury-risk analytics platforms. Watch FDA 510(k) predicate device drift as an inflection indicator, as increasingly rejected substantial equivalence claims force de novo pathways with unpredictable timeline exposure.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation's stricter clinical evidence requirements filter market access for prepared manufacturers. |
| Hospital System Partnership | United States ambulatory surgery centers lock in preferred supplier relationships through value-based care contracts. |
| Software Companion Development | Remote patient monitoring platforms create new reimbursement codes for brace-integrated motion sensors. |
| Reimbursement Strategy | Germany's Institut für das Entgeltsystem im Krankenhaus catalogue directly determines post-operative brace provision volumes. |
| Geographic Expansion | India's Production Linked Incentive scheme offers tariff advantages for domestic neoprene compounding and aluminum stay fabrication. |
Methodological Framework
Operator-level perspectives from orthopedic surgeons, biomedical engineers, hospital purchasing committee members, and physiotherapy clinic directors anchored the qualitative base. These primary interviews combined with secondary validation from FDA 510(k) clearance databases, GPO contract filings, CMS Medicare reimbursement schedules, and EU Medical Device Regulation notified body documentation. Bottom-up demand modeling across product types and materials triangulated against top-down macroeconomic indicators.
Scenario-bracketing around regulatory timeline variability and raw material price volatility shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, material formulation, end-user sophistication, and distribution channel concentration. CAGRs derived from fitted growth curves applied to hospital procurement volumes, collegiate athletic department spending patterns, and aging population joint instability prevalence. Industry-specific inputs encompassed FDA review cycle duration trends and German reimbursement catalogue revision schedules.
Macroeconomic conditions sit as an overlay; deviation in aluminum commodity prices, semiconductor foundry capacity allocation, or healthcare reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and supply chain continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Eye Drop Dispenser Market
Medical Devices
Power Smart Bed Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
France Ultrasound Devices Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
Cheek Implants Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
Engine-Driven Endodontic File Market