
 US Clear Aligners Market | 2026-2036
US Clear Aligners Market Size, Share, and Industry Trends Forecast 2026-2036
US Clear Aligners Market Intelligence
The base of professional prescribers for clear aligners is expanding beyond traditional orthodontic clinics to include general dental practices. Align Technology, Inc. leverages its established network with orthodontists for its Invisalign brand. SmileDirectClub, conversely, competes using a direct-to-consumer model, altering traditional distribution channels. Dentsply Sirona positions its offerings to integrate with existing digital dentistry workflows in private practices.
Clear aligners are a series of custom-made, transparent plastic trays designed to incrementally shift teeth into a desired position. These devices are typically fabricated from medical-grade thermoplastic materials like polyurethane using advanced 3D printing or thermoforming processes. While conventional aligners form a mature base, 3D printed aligners represent the fastest-growing product type due to customization capabilities. Treatment for mild malocclusion and moderate misalignment constitutes the largest application share, offering a shorter treatment duration than severe cases.
The US Food and Drug Administration (FDA) regulates clear aligners as Class II medical devices, requiring 510(k) premarket notification for market entry. State dental boards also influence market access by defining the scope of practice and supervision requirements for teledentistry and direct-to-consumer models. Future competitive advantage will hinge on navigating the evolving regulatory landscape for remote patient monitoring and AI-driven treatment planning.
Market Dynamics
The expansion of the professional prescriber base beyond specialized orthodontists to include general dental practitioners represents the central structural force shaping the US clear aligners market, democratizing access and altering established distribution and care delivery models.
Growth Catalysts
- Advanced Manufacturing:The adoption of custom 3D printing improves treatment precision and patient comfort, enabling faster production cycles and greater customization compared to traditional thermoforming methods.
- Aesthetic Demand:Rising aesthetic consciousness and high disposable incomes, particularly in states like California and Florida, fuel patient demand for discreet orthodontic solutions over traditional metal braces.
- Channel Expansion:The integration of clear aligner systems into the workflows of general dental practices broadens the prescriber network, increasing patient access points beyond specialized orthodontic clinics.
Market Restraints
- Treatment Cost:The high out-of-pocket cost for clear aligner therapy, which is often not fully covered by dental insurance plans, remains a significant barrier to adoption for a large segment of the US population.
- Clinical Limitations:Clear aligners are most effective for mild to moderate malocclusion, with conventional braces remaining the superior treatment option for complex or severe orthodontic cases involving significant tooth extraction or jaw surgery.
- Regulatory Scrutiny:Varying state-level dental board regulations concerning teledentistry and the scope of practice for direct-to-consumer models create compliance complexities and limit uniform market access across the US.
Strategic Opportunities
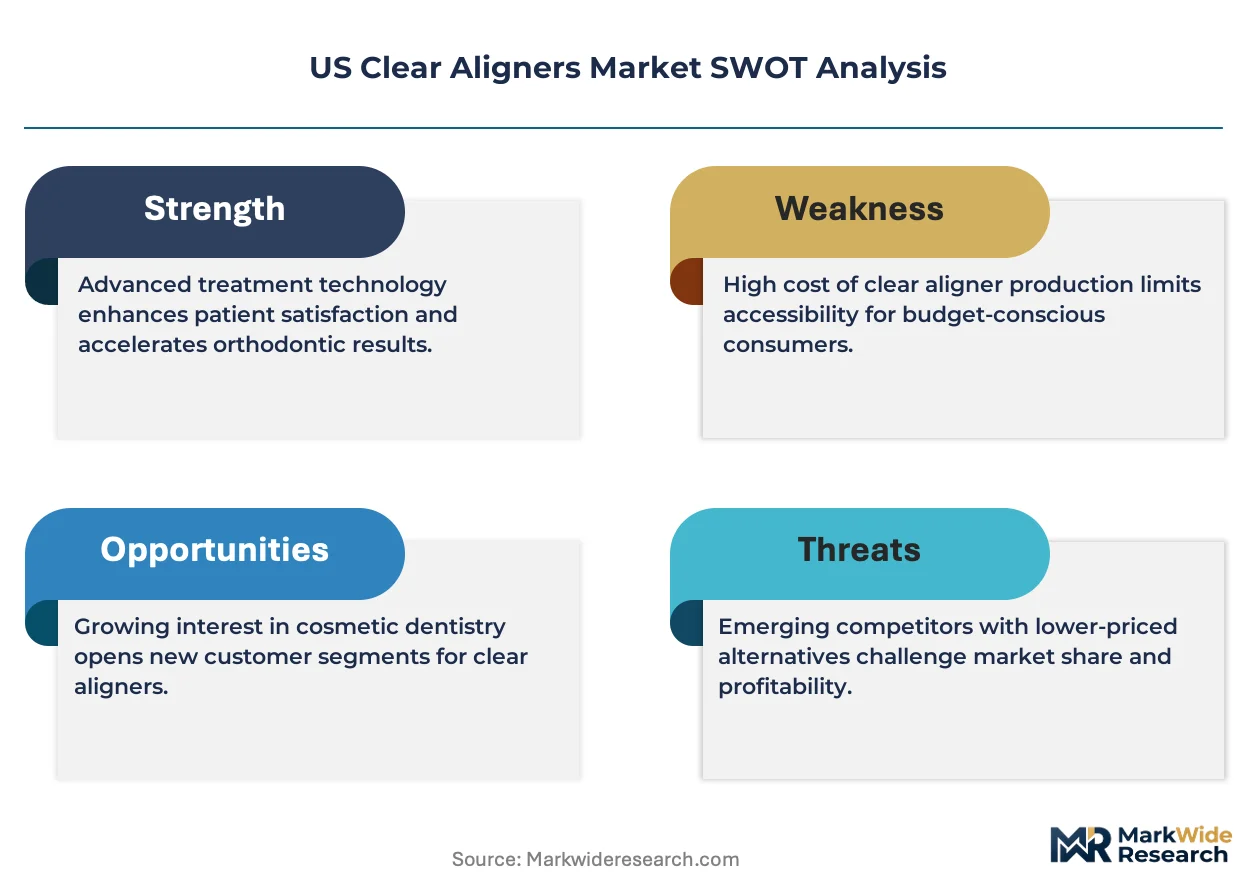
- Technology Integration:Combining AI-powered treatment planning software with remote patient monitoring tools offers an opportunity to enhance treatment efficacy, reduce in-office visits, and improve the overall patient experience.
- Underserved Demographics:There is significant white space in marketing directly to the adult population seeking minor cosmetic teeth correction, a segment that is often hesitant to commit to traditional orthodontic appliances.
- Hybrid Care Models:Developing partnerships between teledentistry platforms and local dental clinics can create a hybrid model that offers the convenience of remote monitoring with the safety of in-person clinical oversight.
Industry Challenges
- Practitioner Training:Ensuring general dentists receive adequate training and support to competently utilize digital intraoral scanners and treatment planning software is a critical challenge for successful case outcomes.
- Intellectual Property Litigation:The market is characterized by frequent and costly patent disputes related to aligner design, material composition, and manufacturing processes, creating uncertainty for manufacturers.
- FDA Compliance Burden:Obtaining 510(k) premarket notification from the FDA for new materials, software updates, or manufacturing methods is a time-consuming and resource-intensive process that can delay innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Clear Aligners Market |
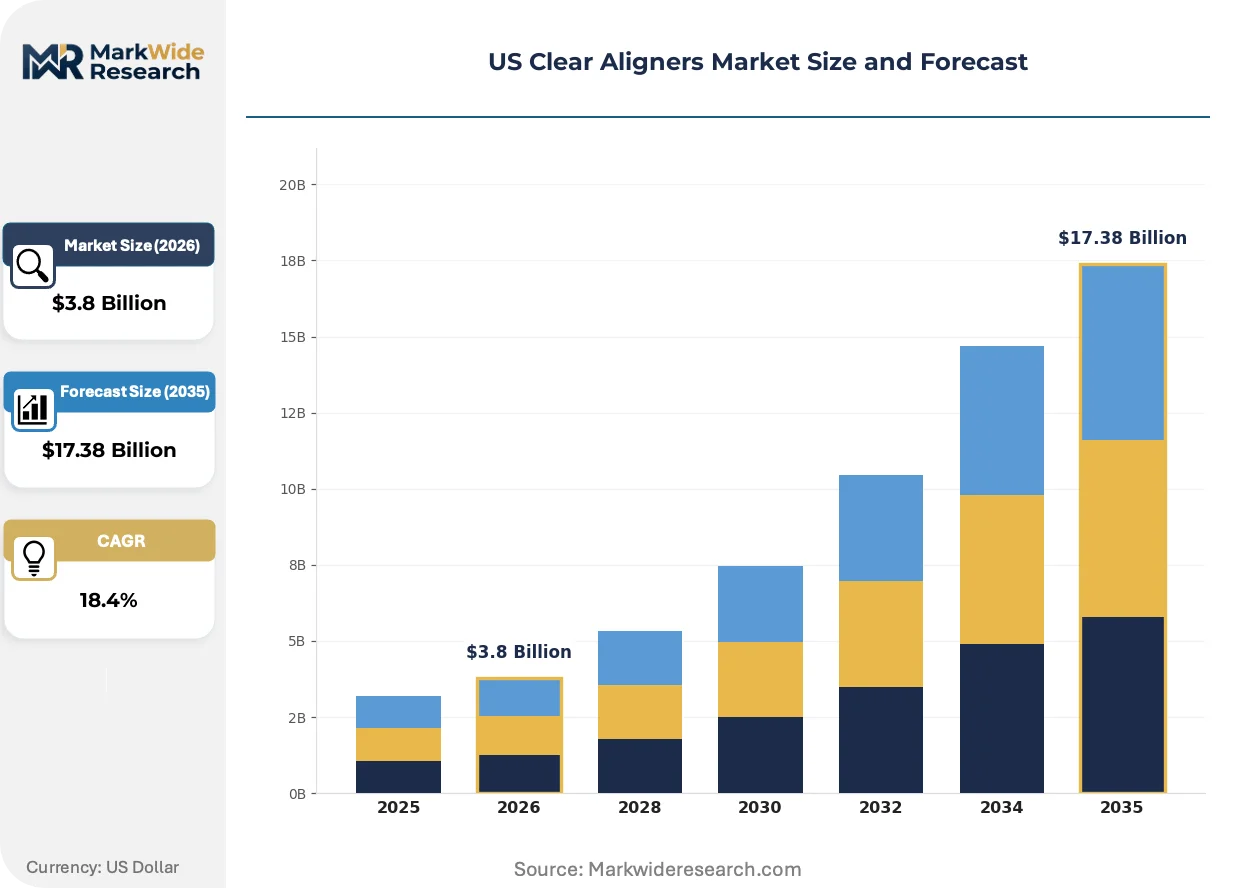
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Aligners, 3D Printed Aligners, Hybrid Aligners, Smart Aligners Application: Mild Malocclusion, Moderate Misalignment, Severe Crowding, Crossbite Correction, Open Bite Treatment End User: Orthodontic Clinics, Dental Hospitals, Private Dental Practices, Cosmetic Dentistry Centers Distribution Channel: Online Retail, Dental Distributors, Direct Manufacturer Sales, Specialty Stores |
| Companies Covered | Align Technology, Inc., Dentsply Sirona, Ormco Corporation (Envista), 3M, Henry Schein, Inc., SmileDirectClub, Argen Corporation, TP Orthodontics, Inc., Candid Care Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Clear Aligners Market Strategic Shifts & Innovations
The convergence of advanced digital technologies and personalized patient care is fundamentally altering the US clear aligners market. This shift is driven by innovations in AI, materials science, and digital scanning, which are making treatment more predictable, efficient, and accessible.
Digital intraoral scanners generate highly accurate 3D models of a patient’s teeth and gums, replacing traditional physical impressions. General dental practices are rapidly adopting these devices to broaden their service offerings beyond routine care. This technology is unifying the separate stages of diagnosis, treatment simulation, and aligner manufacturing into a cohesive digital workflow, compressing timelines and improving accuracy.
State dental boards across the US are actively establishing and refining regulations governing teledentistry and the required levels of professional supervision. This regulatory activity results in a varied landscape that directly influences the business models of direct-to-consumer aligner companies. Operations in states with clearly defined and permissive teledentistry frameworks gain a significant advantage in market penetration and scalability.
A notable behavioral shift involves patients increasingly accepting their general dentist as the primary provider for orthodontic correction. This trend disrupts the historical referral pathway to specialist orthodontists, empowering general practitioners who have invested in digital dentistry platforms. This pattern is particularly visible in US markets where access to orthodontic specialists is geographically limited, expanding the overall addressable market.
US Clear Aligners Market Segmentation
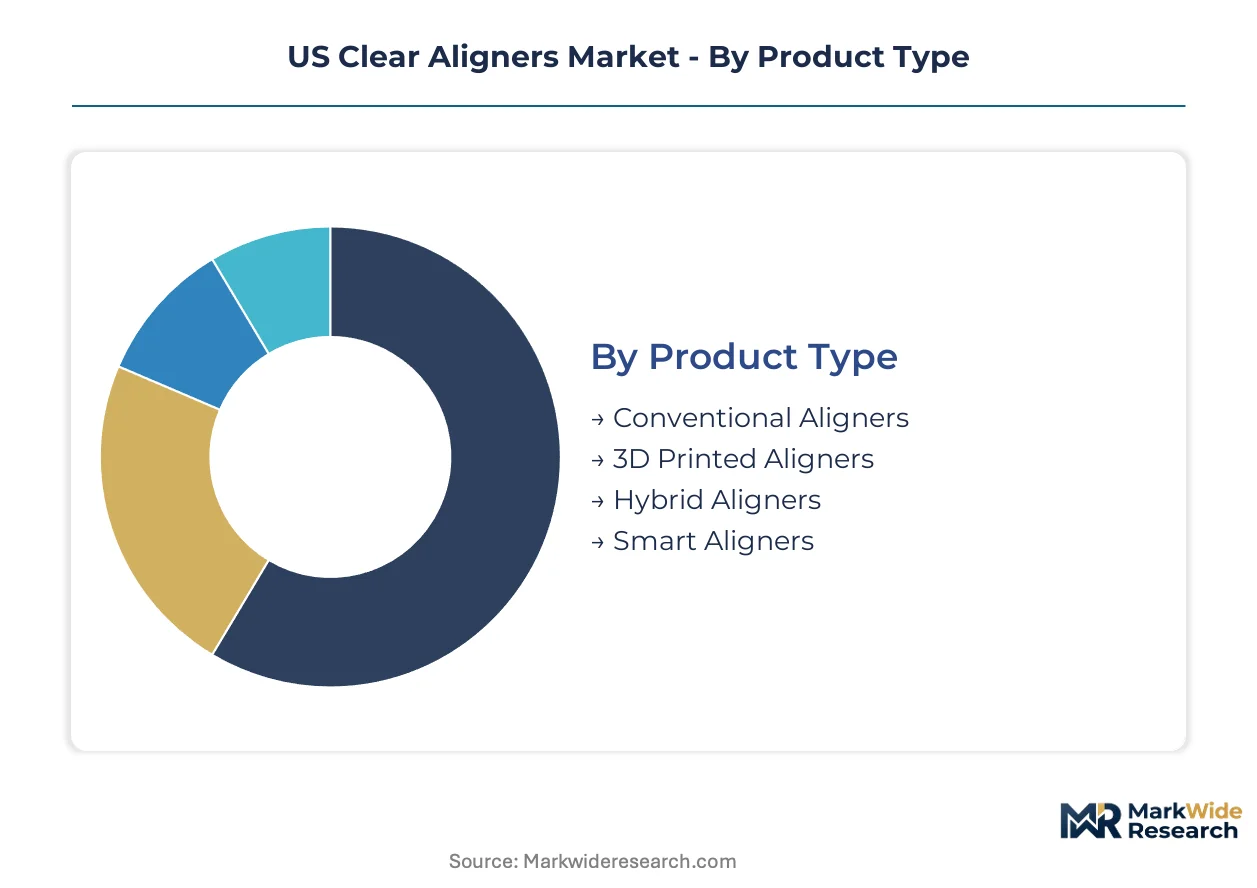
The US clear aligners market segments by product, application, end-user, and distribution, reflecting diverse patient needs and evolving delivery models. Understanding these distinctions clarifies how manufacturers target specific practitioner types and patient demographics. This segmentation highlights the structural shifts altering traditional orthodontic care pathways.
Product Type:
Product type differentiation in the US clear aligners market hinges on manufacturing precision and material innovation, directly impacting treatment accuracy and patient comfort.
- 3D Printed Aligners:These custom devices are fabricated using advanced additive manufacturing processes, leveraging digital models for superior fit and incremental tooth movement. Demand concentrates in cosmetic dentistry centers and private practices, driven by customization capabilities and faster production cycles.
- Conventional Aligners:Typically thermoformed from medical-grade plastic sheets, these aligners represent the foundational technology in clear aligner therapy. They form the mature base of the market, widely adopted across established orthodontic clinics for routine cases.
- Hybrid Aligners:These systems combine clear aligners with traditional orthodontic components like braces or attachments for complex tooth movements.
- Smart Aligners:Incorporating embedded sensors or advanced material properties, these aligners aim to monitor treatment progress or enhance biomechanical forces.
Volume sits with Conventional Aligners; growth tilts toward 3D Printed Aligners.
Application:
The specific orthodontic issue being addressed drives application segmentation, influencing treatment duration and aligner system complexity.
- Mild Malocclusion:This application involves minor aesthetic corrections, such as small gaps or slight rotations, requiring shorter treatment periods and fewer aligner sets. It represents the largest application share in general dental practices due to its straightforward nature.
- Moderate Misalignment:These cases involve more pronounced dental irregularities, including moderate crowding or spacing, necessitating a more extended series of aligners. Demand for this application is significant across both orthodontic and general dental practices, offering a balance of efficacy and convenience.
- Severe Crowding:This application addresses significant tooth overlap or displacement, often requiring comprehensive treatment plans that may combine aligners with other orthodontic tools.
- Crossbite Correction:Clear aligners can address situations where upper teeth bite inside lower teeth, especially for single-tooth or anterior crossbites.
- Open Bite Treatment:This application targets cases where front teeth do not meet when the mouth is closed, often requiring specific bite correction strategies.
Demand for clear aligners is highest for Mild Malocclusion, with Moderate Misalignment expanding most quickly.
End User:
Patient access points and practitioner specialization define the end-user segments, reflecting different care delivery models for clear aligner therapy.
- Private Dental Practices:General dentists increasingly offer clear aligner treatments, broadening the prescriber base and integrating these services into routine patient care. This segment is experiencing rapid expansion as general practitioners adopt digital dentistry workflows and seek to retain patients for orthodontic needs.
- Orthodontic Clinics:These specialized practices traditionally serve as the primary providers for comprehensive orthodontic treatment, including complex clear aligner cases. They leverage established expertise and infrastructure for detailed treatment planning and oversight.
- Dental Hospitals:Academic and larger institutional settings provide clear aligner treatment, often handling complex cases or serving specific patient populations.
- Cosmetic Dentistry Centers:These centers focus on aesthetic improvements, offering clear aligners as a discreet solution for patients seeking smile enhancement.
The largest patient volume flows through Orthodontic Clinics, while Private Dental Practices are gaining share fastest.
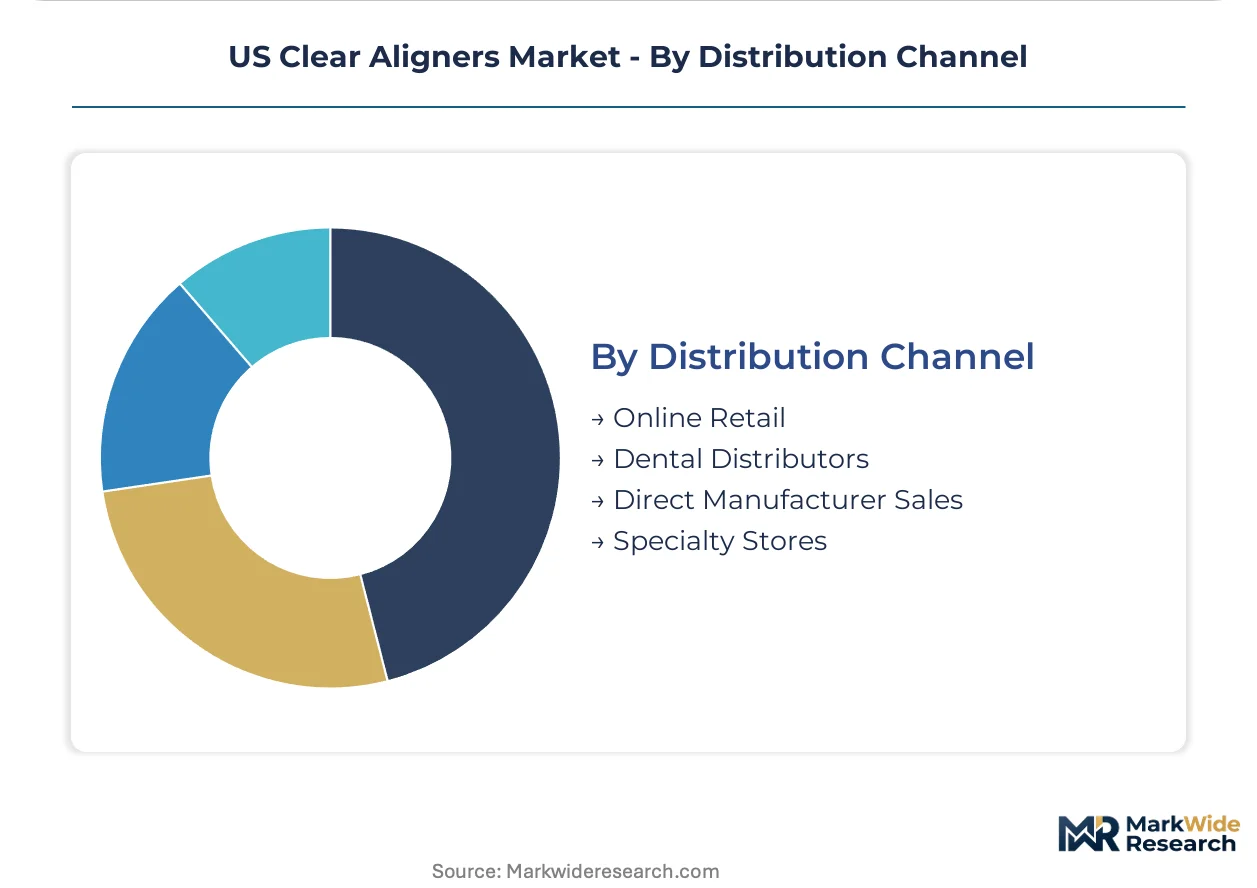
Distribution Channel:
The go-to-market strategy for clear aligner manufacturers shapes distribution channel dynamics, influencing product accessibility and consumer engagement.
- Direct Manufacturer Sales:Companies like SmileDirectClub utilize a direct-to-consumer model, bypassing traditional dental professionals for initial patient engagement and aligner delivery. This channel alters established distribution pathways, appealing to price-sensitive or convenience-seeking consumers.
- Dental Distributors:These traditional intermediaries supply clear aligner products and related equipment to dental practices and clinics across the US. They provide logistical support and product access for a wide network of professional prescribers.
- Online Retail:While limited for direct aligner sales, online platforms facilitate initial consultations, information dissemination, and accessory purchases for clear aligner users.
- Specialty Stores:Some brands operate physical retail locations or pop-up stores for consultations and 3D scanning, offering a unique consumer-facing experience.
Traditional channels account for most sales, but Direct Manufacturer Sales are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for clear aligners in the US market is pronounced in states characterized by high disposable incomes and a strong aesthetic consciousness. These regional dynamics are influenced by local economic conditions, regulatory frameworks for dental practice, and the density of dental professionals adopting digital dentistry solutions.
California
High disposable incomes and a strong focus on personal aesthetics drive significant patient demand for discreet orthodontic solutions in California. The California Dental Board establishes guidelines for teledentistry, impacting direct-to-consumer models. Silicon Valley and Southern California metropolitan areas serve as innovation hubs, promoting early adoption of advanced digital scanning and AI-powered treatment planning.
Florida
Florida's large retiree population and robust tourism sector contribute to a sustained demand for cosmetic dental procedures, including clear aligner therapy. The Florida Board of Dentistry oversees the scope of practice for general dentists offering orthodontic services. Major coastal cities like Miami and Orlando exhibit high concentrations of cosmetic dentistry centers, integrating clear aligners into their service portfolios.
New York Metro
The dense urban environment and affluent consumer base within the New York Metropolitan area foster a strong market for premium clear aligner treatments. New York's State Board for Dentistry defines supervision requirements for remote patient monitoring. Manhattan and surrounding affluent suburbs show a high density of specialized orthodontic clinics and private dental practices equipped with digital intraoral scanners.
Texas
Texas experiences a growing demand for clear aligners, fueled by a rapidly expanding population and increasing access to dental care across its major cities. The Texas State Board of Dental Examiners regulates the provision of teledentistry services. Houston and Dallas represent significant medical and dental hubs, attracting investment in advanced dental technologies and training for practitioners.
Pacific Northwest
The Pacific Northwest, particularly regions around Seattle and Portland, demonstrates a rising adoption of clear aligners, supported by a tech-savvy population open to innovative healthcare solutions. State dental boards in Washington and Oregon are actively shaping policies around digital dentistry. Tech clusters in Seattle and Portland drive a consumer base that values convenience and aesthetic appeal in healthcare services.
US Clear Aligners Market Key Industry Players
US-based manufacturers anchor one tier, focusing on established professional channels, while emerging direct-to-consumer US specialists hold another, altering traditional distribution. The market structure exhibits a tiered competitive environment, with players differentiating themselves through technology integration and distribution models. Key strategic archetypes include established professional providers, direct-to-consumer innovators, and digital dentistry solution integrators. Dominant competitive moves involve strategic partnerships with general dental practices and continuous investment in advanced manufacturing capabilities.
Within the established professional provider archetype, Align Technology, Inc. and Dentsply Sirona exemplify companies with extensive networks among orthodontists and general dentists. These entities focus on integrating clear aligner systems with existing digital dentistry workflows and providing comprehensive support for practitioners. SmileDirectClub represents the direct-to-consumer innovator archetype, utilizing a different distribution model to reach price-sensitive or convenience-seeking consumers directly.
| Leading Market Players |
|---|
| Align Technology, Inc. |
| Dentsply Sirona |
| Ormco Corporation (Envista) |
| 3M |
| Henry Schein, Inc. |
| SmileDirectClub |
| Argen Corporation |
| TP Orthodontics, Inc. |
| Candid Care Co. |
| Others |
Cost & Logistics Intelligence
Polyurethane resin spot prices, a key input for clear aligner manufacturing, cascade through the supply chain, influencing the final pricing tiers for both professional and direct-to-consumer models. This interaction highlights how raw material availability and processing costs directly impact market-level affordability and competitive positioning.
Pricing Analysis
Volume-driven segments experience tighter margins, while specialized applications command premium pricing in the US clear aligners market. Pricing stratifies across premium, standard, and economy tiers, influenced by customization level and bundled after-sales support for practitioners. Pricing pressure stems from the proliferation of direct-to-consumer models and increasing competition among manufacturers. Consumers seeking basic aesthetic corrections exhibit high price sensitivity, contrasting with lower sensitivity for complex cases managed by specialist orthodontists.
Supply Chain Analysis
Dual-sourcing requirements for critical medical-grade polymers are gaining importance, driven by supply chain resilience concerns among clear aligner manufacturers. The supply of advanced thermoplastic polymers primarily draws from specialized chemical producers in the US, Germany, and Japan. Intellectual property litigation represents a structural risk, potentially disrupting access to specific manufacturing processes or aligner designs. Downstream distribution runs through dental distributors and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US clear aligners market is undergoing a vertical-integration race, with players pursuing control over digital dentistry workflows as a key lever for competitive advantage.
For Market Incumbents:Lock in general dental practices by offering comprehensive digital platforms that integrate intraoral scanning, AI-powered treatment planning, and aligner ordering. Invest in advanced 3D printing capabilities to maintain a lead in customization and production efficiency against emerging direct-to-consumer models. Develop robust practitioner training programs to ensure successful case outcomes, mitigating risks associated with general dentists expanding their orthodontic services.
For New Entrants and Emerging Players:Launch via hybrid care models, combining the convenience of teledentistry platforms with localized in-person clinical oversight through partnerships with general dental clinics. Target the underserved adult population seeking minor cosmetic teeth correction, a segment often hesitant about traditional orthodontic appliances. The mild malocclusion segment within private dental practices offers a penetrable entry point due to its straightforward nature and broad demand.
For Investors and Strategic Acquirers:Distressed-cycle entries favor digital dentistry solution integrators in the US, given the market's long-term viability driven by aesthetic demand and technological advancements. Focus on companies with proprietary AI-driven treatment planning software or specialized material science innovations. A key signal to watch is the evolving regulatory landscape for remote patient monitoring, which will shape the scalability of teledentistry-focused models.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-powered treatment planning software | Enhances treatment predictability and reduces chair time for practitioners. |
| Platform Integration: Incorporating remote patient monitoring tools | Improves patient convenience and optimizes clinical oversight for general dentists. |
| Strategic Partnership: Collaborating with general dental practices | Expands prescriber network and democratizes access to clear aligner therapy. |
| Manufacturing Scale-Up: Investing in advanced 3D printing capabilities | Accelerates production cycles and enables greater customization of aligner products. |
| Regulatory Approval Pathway: Navigating FDA 510(k) for new material composites | Ensures market access and validates safety for innovative aligner designs. |
Research Approach
Independent corroboration across industry interviews, secondary market data, and regulatory filings underwrites the qualitative findings within this analysis. Primary research involved discussions with orthodontists, general dental practitioners, clear aligner manufacturers, and state dental board representatives. Secondary data sources included FDA 510(k) clearances, state dental board regulations, patent databases, and dental industry trade publications, enabling robust bottom-up and top-down triangulation.
The forecast framework anchored the analysis window to historical market performance and established growth trajectories for clear aligner adoption. Segmentation dimensions modeled included product type, application, end-user, distribution channel, and regional economic indicators. Compound annual growth rates were derived from historical data analysis and projected market dynamics, incorporating key inputs such as disposable income trends and aesthetic consciousness indices across the modeling period.
The model assumes a particular technology adoption path; alternative pathways for AI-driven treatment planning or advanced material science would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and sustained investment in digital dentistry. Deviation in teledentistry regulatory frameworks would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Global Insufflation Devices Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
Endocavity Transducer Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
Muscle Stimulation Devices Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Middle Ear Implants Market