
 Nonablative Laser Resurfacing Devices Market | 2026-2036
Nonablative Laser Resurfacing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nonablative Laser Resurfacing Devices Market Analytics
Israeli laser OEM supply is consolidating around vertically integrated platforms. Candela Medical leverages integrated aesthetic delivery systems to sustain its installed base across North American dermatology practices. Lumenis anchors its position through fiber laser R&D intensity and direct service networks in European capitals. Alma Lasers competes on diode laser cost structures while extending manufacturing scale across Asian production hubs.
Nonablative laser resurfacing devices deliver controlled thermal injury to dermal collagen without epidermal ablation, typically operating at wavelengths between 1320 nm and 1550 nm with pulse durations in the millisecond range to stimulate neocollagenesis for skin texture improvement. Fractional laser configurations now dominate capital procurement budgets due to their tunable density settings and reduced adverse event profiles compared to full-field alternatives. Dermatology centers represent the fastest-growing end user channel as physician-owned practices consolidate aesthetic service lines away from hospital outpatient departments.
FDA 510(k) premarket notification requirements govern device safety and efficacy claims for US market entry, while the EU Medical Device Regulation mandates notified body conformity assessment for CE marking across European member states. ISO 13485 quality management certification has become a baseline procurement filter for institutional buyers evaluating vendor risk. Stakeholders must monitor evolving cybersecurity guidance from FDA for networked laser platforms as connectivity features expand in next-generation systems.
Market Dynamics
Patient preference for minimal-downtime aesthetic procedures is compressing demand away from ablative alternatives and toward fractional nonablative platforms with tunable thermal injury parameters.
Growth Catalysts
- EU MDR conformity pathways:Tightened CE marking requirements for laser medical devices are filtering out marginal suppliers and elevating procurement confidence among institutional dermatology buyers.
- South Korea medical tourism infrastructure:K-beauty influence and government-backed cosmetic surgery clusters are driving premium device procurement from international OEMs.
- Fractional laser density tuning:Advanced micro-optical arrays now enable customizable thermal column patterns, reducing adverse event rates and expanding treatable patient phenotypes.
Market Restraints
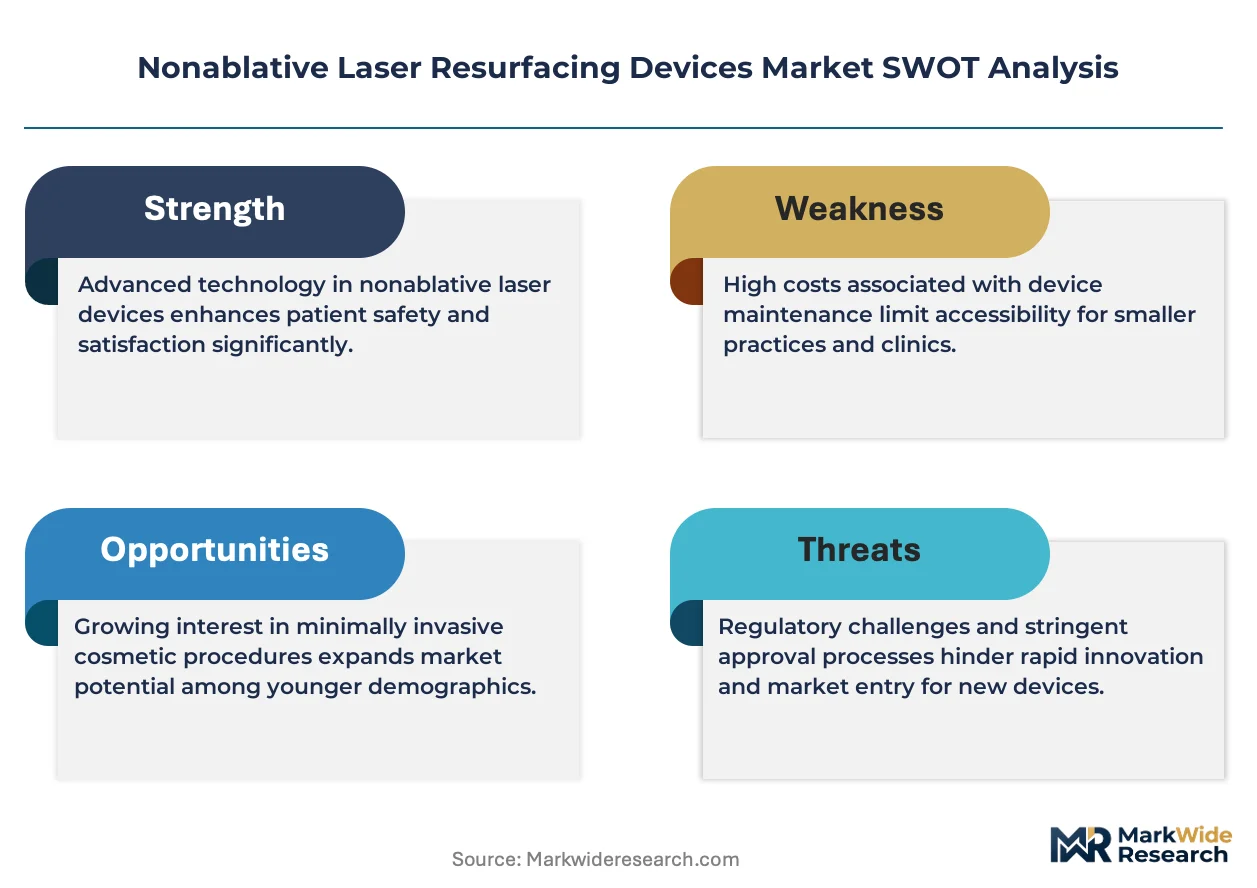
- Ytterbium-doped fiber laser component costs:Rare-earth element price volatility and limited foundry capacity for specialized gain fibers compress OEM margins.
- Israeli supply concentration:Three dominant laser OEMs control critical diode and fiber laser IP, creating single-source vulnerability for device assemblers.
- Radiofrequency microneedling substitution:Lower capital entry barriers and comparable collagen remodeling outcomes divert mid-market clinic budgets from laser platforms.
Strategic Opportunities
- Southeast Asia clinic densification:Thailand, Vietnam, and Indonesia exhibit sub-15% laser penetration among aesthetic practices versus South Korean benchmarks.
- At-home adjunct device convergence:LED photomodulation panels paired with professional fractional protocols create recurring revenue streams through hybrid treatment models.
- US IRA aesthetic tax incentives:Section 179 depreciation expansion for medical equipment purchases accelerates capital replacement cycles in physician-owned practices.
Industry Challenges
- Laser safety officer certification bottlenecks:ANSI Z136.3-compliant training programs face 6-9 month waitlists, constraining clinic expansion timelines.
- FDA 510(k) cybersecurity documentation:Networked laser platforms now require software bill of materials and vulnerability management protocols, extending submission preparation by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonablative Laser Resurfacing Devices Market |
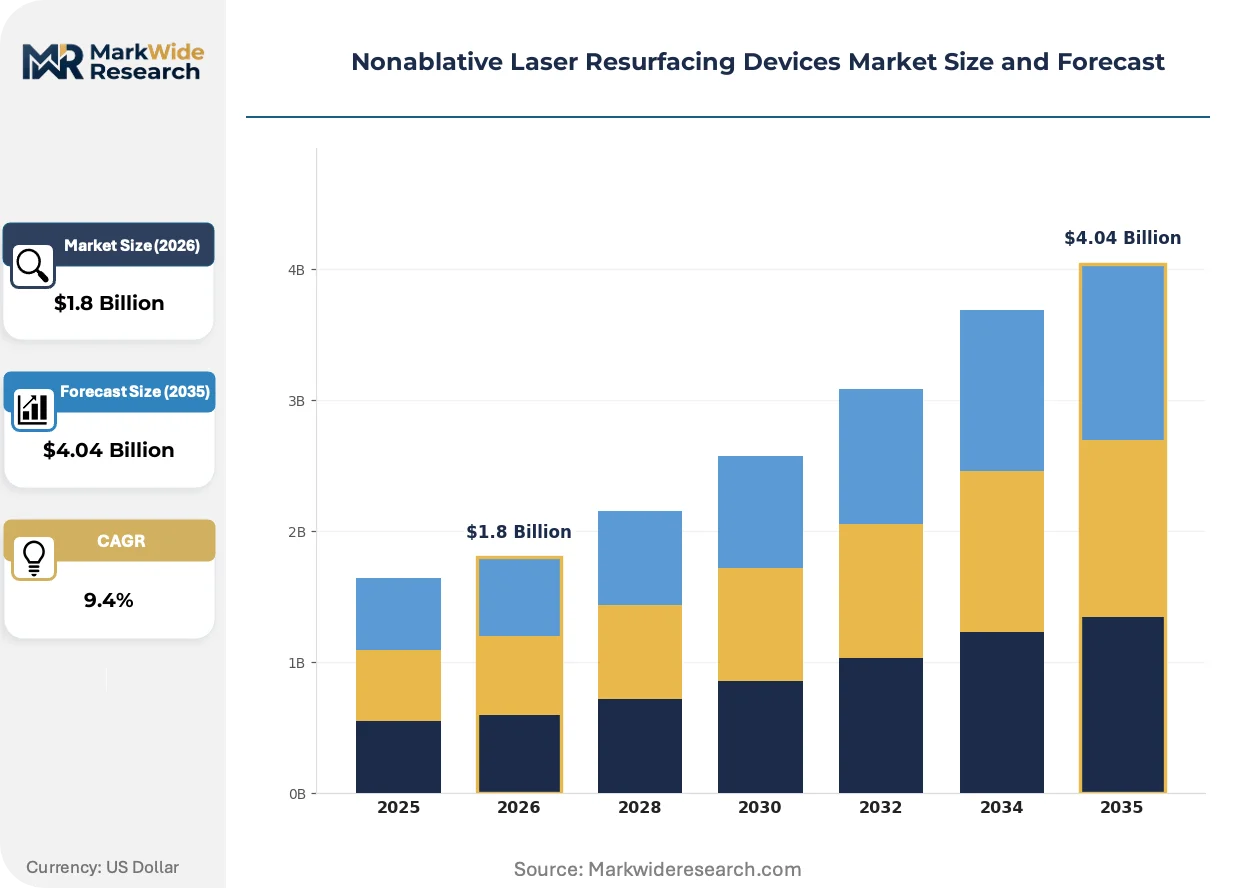
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fractional Laser, Pulsed Dye Laser, Nd:YAG Laser, CO2 Laser End User: Clinics, Hospitals, Spas, Dermatology Centers Technology: Diode Laser, Fiber Laser, Solid-State Laser, Gas Laser Application: Skin Rejuvenation, Acne Scar Treatment, Anti-Aging, Pigmentation Removal |
| Companies Covered | Candela Medical, Lumenis, Cynosure, Alma Lasers, Cutera, Sciton, Lutronic Corporation, Quanta System, Fotona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonablative Laser Resurfacing Devices Market Evolving Landscape
Real-time epidermal temperature feedback systems are eliminating the empirical fluence-titration that previously defined operator training curves.
Picosecond-domain nonablative lasers operating at 755 nm and 1064 nm wavelengths are automating melanosome-selective photothermolysis with reduced thermal diffusion to surrounding collagen. Academic medical centers in the United States are adopting these platforms for post-inflammatory hyperpigmentation protocols previously managed by topical regimens alone. The technology is automating treatment standardization and compressing the experience gradient between novice and expert operators.
EU MDR Annex XVI expansion now captures aesthetic laser devices previously regulated under lower-risk classifications, mandating clinical investigation reports and post-market surveillance systems. Notified bodies in Germany and the Netherlands have extended conformity assessment timelines from 9 to 18 months. Mid-cap OEMs without legacy technical documentation are exiting the European market, concentrating procurement options among established multinationals with robust quality management systems.
Subscription-based device access models are displacing outright capital purchases in US dermatology roll-ups and private equity-backed clinic platforms. Per-procedure leasing arrangements bundle consumables, service contracts, and software updates into predictable monthly expenditures. This financing restructuring is most visible in Texas and Florida metropolitan corridors where multi-site aesthetic chains are consolidating independent practices.
Nonablative Laser Resurfacing Devices Market Segmentation
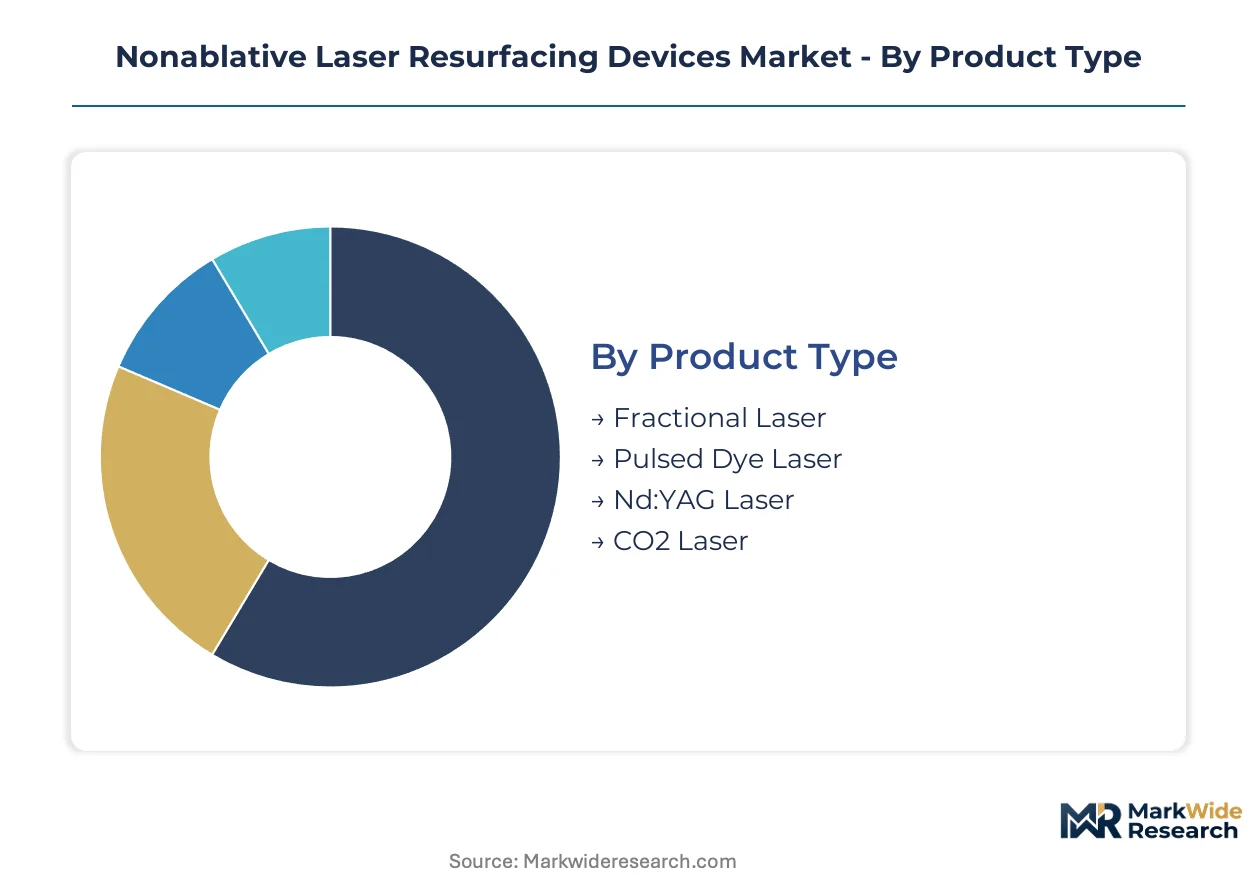
Device segmentation in nonablative laser resurfacing reflects divergent capital deployment strategies across clinical settings. Procurement patterns vary sharply between standalone installations in physician-owned practices and integrated platforms within hospital outpatient departments. Understanding these segment boundaries clarifies where OEMs must configure modular versus fixed-architecture systems.
Product Type:
Standalone fractional systems dominate dermatology suites, while embedded pulsed dye configurations anchor multi-modality aesthetic workstations in hospital settings.
- Fractional Laser:Micro-optical arrays deliver tunable thermal column densities between 1320 nm and 1550 nm wavelengths. Dermatology centers in South Korea and the United States concentrate procurement here, driven by patient demand for minimal-downtime protocols with adjustable treatment depths.
- Pulsed Dye Laser:Selective photothermolysis at 585 nm and 595 nm wavelengths targets vascular lesions without collateral thermal diffusion. Hospital outpatient departments favor these platforms for pediatric and rosacea applications where hemoglobin specificity reduces adverse event documentation burdens.
- Nd:YAG Laser:1064 nm wavelength penetrates deeply for darker skin phototypes with reduced epidermal melanin absorption.
- CO2 Laser:10,600 nm wavelength remains confined to hybrid ablative-nonablative platforms despite thermal injury depth.
Volume placements concentrate in Fractional Laser; the faster expansion belongs to Pulsed Dye Laser as vascular indication protocols expand.
End User:
Customer type determines service bundling complexity and financing structure preference across the procurement cycle.
- Dermatology Centers:Physician-owned practices consolidate aesthetic service lines with subscription-based device access models. Texas and Florida metropolitan corridors exhibit dense clustering of multi-site chains negotiating per-procedure leasing arrangements.
- Clinics:Independent aesthetic practices prioritize diode laser cost structures with rapid payback periods under 18 months.
- Hospitals:Academic medical centers demand FDA 510(k) clearance documentation and cybersecurity vulnerability management protocols for networked installations.
- Spas:Non-medical aesthetic facilities face ANSI Z136.3 laser safety officer certification bottlenecks constraining expansion timelines.
Capital commitment intensity peaks at Dermatology Centers; Spas climb the fastest as medical tourism infrastructure penetrates Southeast Asian markets.
Technology:
Technology selection traces supply chain concentration in Israeli fiber laser foundries and Asian diode manufacturing clusters.
- Fiber Laser:Ytterbium-doped gain fibers enable precise pulse control with reduced thermal drift. European dermatology practices in Germany and the Netherlands prioritize these platforms for EU MDR conformity assessment confidence.
- Diode Laser:Compact solid-state architectures drive cost structures below fiber alternatives. Alma Lasers extends manufacturing scale across Asian production hubs to serve mid-market clinic budgets.
- Solid-State Laser:Nd:YAG and Er:YAG crystal rods dominate legacy installed bases requiring service contract renewal.
- Gas Laser:CO2 discharge tubes persist in hybrid platforms despite maintenance intensity and gas refill logistics.
Installed base concentration favors Fiber Laser; Diode Laser gains share fastest as Southeast Asia clinic densification accelerates.
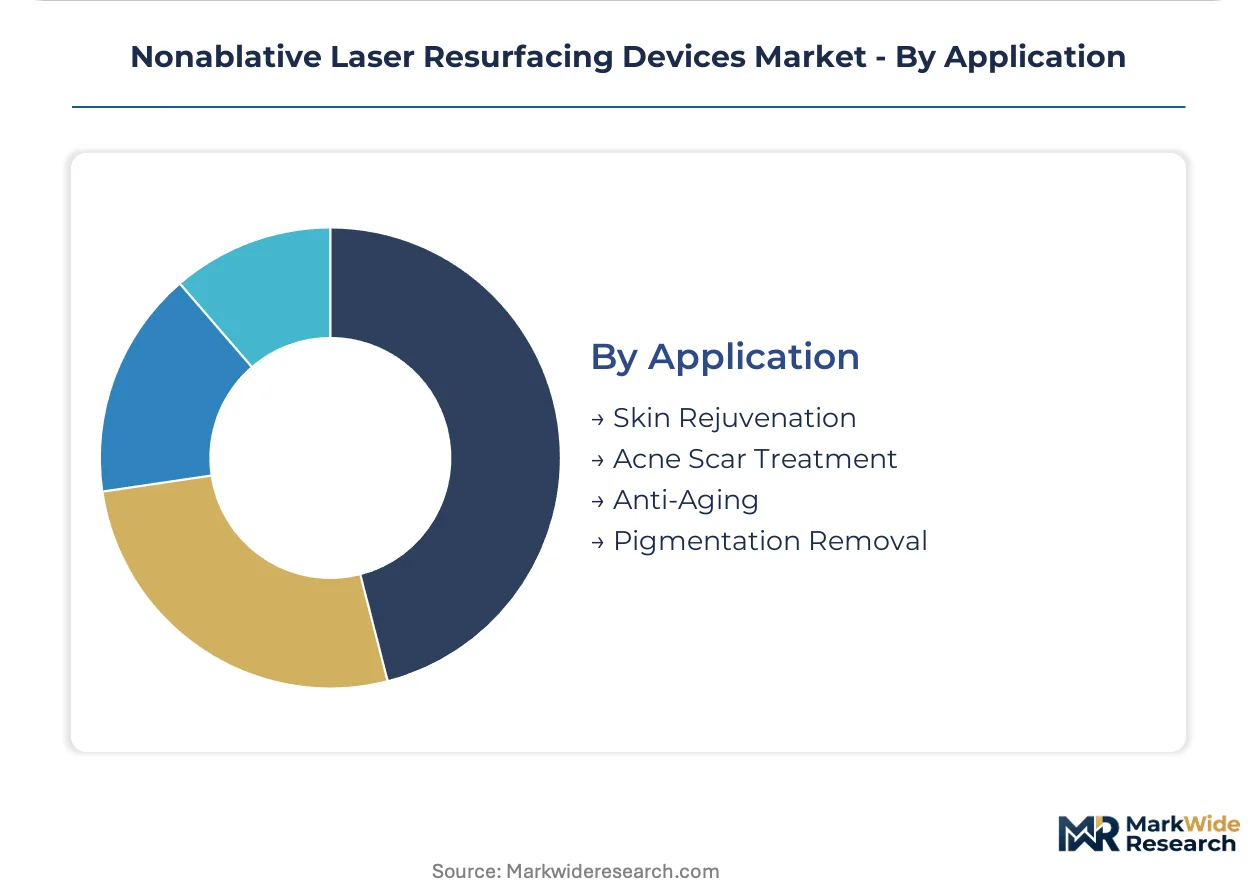
Application:
Clinical indication expansion reshapes training protocol standardization and reimbursement documentation requirements.
- Skin Rejuvenation:Neocollagenesis stimulation protocols address photodamage and fine rhytides through controlled dermal thermal injury. United States dermatology centers deploy picosecond-domain platforms at 755 nm and 1064 nm for post-inflammatory hyperpigmentation management.
- Acne Scar Treatment:Fractional nonablative parameters target atrophic scarring with reduced erythema duration versus ablative alternatives. South Korean medical tourism clusters market these protocols to international patients through K-beauty influence channels.
- Anti-Aging:Preventative treatment protocols expand addressable patient demographics below traditional cosmetic surgery age thresholds.
- Pigmentation Removal:Melanosome-selective photothermolysis automates treatment standardization across operator experience gradients.
Procedure volume concentrates in Skin Rejuvenation; Acne Scar Treatment expands most quickly as social media documentation drives patient awareness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ytterbium-doped fiber laser foundries in Israel and diode manufacturing clusters in East Asia anchor the geographic footprint of nonablative laser device supply chains. Procurement patterns concentrate where medical tourism infrastructure, dermatology practice consolidation, and regulatory clarity converge.
United States
Physician-owned dermatology roll-ups in Texas and Florida metropolitan corridors drive subscription-based device access models. FDA 510(k) premarket notification requirements and emerging cybersecurity documentation mandates shape vendor selection criteria. Academic medical centers in Boston and California deploy picosecond-domain platforms for post-inflammatory hyperpigmentation protocols.
South Korea
K-beauty influence and government-backed cosmetic surgery clusters in Seoul propel premium device procurement from international OEMs. MFDS regulatory frameworks align with global standards while supporting medical tourism visa facilitation. Gangnam District aesthetic practices concentrate fractional laser installations serving international patient flows.
Germany
EU MDR conformity assessment confidence elevates fiber laser platform preference among dermatology practices. Notified body timelines extending to 18 months filter marginal suppliers from procurement consideration. Munich and Frankfurt hospital outpatient departments anchor multi-modality aesthetic workstation installations.
Israel
Vertically integrated laser OEM supply concentrates critical diode and fiber laser IP within three dominant manufacturers. ANSI Z136.3-compliant training program bottlenecks constrain clinic expansion timelines domestically. Tel Aviv and Haifa industrial zones host R&D intensity for next-generation fractional micro-optical arrays.
Japan
PMDA regulatory pathways and METI industrial policy support adoption of real-time epidermal temperature feedback systems. Tokyo and Osaka dermatology centers prioritize treatment standardization technologies that compress operator experience gradients. Aging demographics expand addressable patient cohorts for minimal-downtime rejuvenation protocols.
Nonablative Laser Resurfacing Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and service network density. The vendor base clusters around three strategic archetypes: vertically integrated platform OEMs controlling critical laser IP, modular system assemblers leveraging Asian diode cost structures, and specialty manufacturers focused on single-wavelength applications. Competitive moves concentrate on backward integration into rare-earth fiber foundries and per-procedure leasing arrangement proliferation.
Among Israeli-origin platform specialists, Candela Medical, Lumenis, and Alma Lasers occupy positions spanning the premium-to-mid-market spectrum. Candela Medical exemplifies the integrated aesthetic delivery system archetype through sustained installed base management across North American dermatology practices. Lumenis anchors the fiber laser R&D intensity segment with direct service network presence in European capitals. Alma Lasers represents the manufacturing scale archetype through Asian production hub extension and diode laser cost structure optimization.
| Leading Market Players |
|---|
| Candela Medical |
| Lumenis |
| Cynosure |
| Alma Lasers |
| Cutera |
| Sciton |
| Lutronic Corporation |
| Quanta System |
| Fotona |
| Others |
Value Network & Pricing Analysis
EU MDR Annex XVI expansion gates qualified supply access and premium-tier pricing power by mandating clinical investigation reports for aesthetic laser devices previously under lower-risk classifications. Device OEMs without legacy technical documentation face exclusion from European procurement consideration, compressing vendor options and elevating price floors for compliant platforms.
Pricing Analysis
Warranty bundling and service contract structures differentiate pricing tiers across the installed base, with comprehensive multi-year coverage commanding 15-25% premiums over bare hardware transactions. Price differentiation rests on ISO 13485 certification tier and direct service network density, with FDA-cleared fiber laser platforms from established Israeli OEMs sustaining premium positioning against Asian diode alternatives. Cost compression in mid-market diode segments is intensifying because Alma Lasers extends manufacturing scale across production hubs, forcing legacy solid-state vendors toward margin-tightening volume discounts. Independent aesthetic clinics exhibit highest price sensitivity, while academic medical centers prioritize cybersecurity documentation and regulatory compliance over acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle demand from dermatology roll-ups and private equity-backed clinic platforms, while distributor networks serve independent aesthetic practices in Southeast Asia. Geographic supply concentration centers on Israeli ytterbium-doped fiber laser foundries and East Asian diode manufacturing clusters in China and South Korea. Raw material dependencies include rare-earth gain fibers, precision micro-optical arrays, and medical-grade laser diodes. Single-source vulnerability around critical IP held by three dominant Israeli OEMs creates structural supply risk. Distribution runs through authorized service networks for premium platforms and third-party logistics for cost-optimized diode systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity pathways function as a cost-of-compliance moat, filtering marginal suppliers from European procurement consideration and consolidating viable vendor options among multinationals with robust quality management systems.
For Market Incumbents: Extend backward integration into rare-earth fiber foundries to secure captive supply of ytterbium-doped gain fibers against price volatility and foundry capacity constraints. Deepen per-procedure leasing arrangement proliferation across Texas and Florida metropolitan corridors where multi-site aesthetic chains consolidate independent practices. Radiofrequency microneedling substitution threatens mid-market laser placement volumes; counter by bundling real-time epidermal temperature feedback systems as standard features that compress operator training curves and elevate switching costs. For New Entrants and Emerging Players: Picosecond-domain nonablative platforms at 755 nm and 1064 nm wavelengths offer technology-first entry into post-inflammatory hyperpigmentation protocols at academic medical centers previously managed by topical regimens alone. Southeast Asia clinic densification in Thailand, Vietnam, and Indonesia presents the most penetrable geography, with sub-15% laser penetration versus South Korean benchmarks. Target hybrid at-home adjunct device convergence through LED photomodulation panel partnerships that create recurring revenue streams alongside professional fractional protocols. For Investors and Strategic Acquirers: FDA 510(k) cybersecurity documentation extending submission preparation by 4-6 months is the leading indicator that regulatory compliance capabilities are becoming the primary scarcity factor in vendor consolidation. Mid-cap OEMs exiting European markets due to EU MDR technical documentation gaps represent acquisition targets with installable base value but stranded regulatory assets. Watch for ANSI Z136.3 laser safety officer certification bottleneck resolution as the signal that clinic expansion timelines can accelerate and capital deployment intensity will follow.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Investment | Notified body timelines extending to 18 months filter marginal competitors from German and Dutch procurement consideration. |
| Backward Integration into Fiber Foundries | Captive ytterbium-doped gain fiber production insulates Israeli OEM margins from rare-earth price volatility. |
| Per-Procedure Leasing Arrangement Proliferation | Subscription models displace capital purchases in Texas and Florida dermatology roll-ups seeking predictable monthly expenditures. |
| Real-Time Temperature Feedback Integration | Automated epidermal monitoring eliminates empirical fluence-titration and compresses novice-to-expert operator gradients. |
| Southeast Asia Distribution Partnership | Thailand, Vietnam, and Indonesia clinic densification accelerates diode laser placement against sub-15% penetration benchmarks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across dermatology practice owners, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, MFDS regulatory frameworks, and ISO 13485 certification registries provided secondary validation. Bottom-up device placement tracking triangulated against top-down market sizing derived from OEM revenue disclosures and capital expenditure patterns across the analysis window.
Data-stream reconciliation across product type, technology architecture, end-user channel, and application indication dimensions shaped the analytical framework. CAGRs were derived from segmented volume and value trajectories modeled through the projection horizon. Industry-specific forecast inputs included ytterbium-doped fiber laser component cost curves, dermatology practice consolidation rates in US metropolitan corridors, and medical tourism visa facilitation trends in South Korea.
Several conditions sit outside the modeled scope, including speculative regulatory shifts beyond current EU MDR and FDA cybersecurity guidance, geopolitical disruption to Israeli supply chains, and breakthrough substitution technologies not yet in commercial development. Forecasts reflect assumptions around continued K-beauty influence, stable rare-earth element pricing, and ANSI Z136.3 certification bottleneck persistence. Periodic stress-testing of base assumptions is recommended against laser safety officer training program waitlist resolution and fractional laser density tuning adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Invisible Orthodontics Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Breathing Circuits Market
Medical Devices
Artificial Retina Market
Medical Devices
Nasal Packing Devices Market
Medical Devices
Prefilled Glass Syringes Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
Memory Implants Market
Medical Devices
Global Hernia Repair Devices and Consumables Market
Medical Devices
US Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Epilepsy Devices Market
Medical Devices
Transcranial Magnetic Stimulation System Market
Medical Devices
Middle East and Africa Non-Surgical Procedures Market