
 Prosthetic Disc Nucleus Market | 2026-2036
Prosthetic Disc Nucleus Market Size, Share, and Industry Trends Forecast 2026-2036
Prosthetic Disc Nucleus Market Analysis
Hospital procurement consortiums across North America and Western Europe are reshaping how prosthetic disc nucleus devices reach surgical suites. Stryker Corporation leverages its integrated spine platform to secure long-term supply contracts with major hospital systems. Zimmer Biomet Holdings Inc. anchors its position through specialized sales forces focused on orthopedic and neurosurgical divisions. NuVasive Inc. competes by concentrating on minimally invasive access technologies that pair with nucleus replacement implants.
A prosthetic disc nucleus is a biomechanical implant designed to replace the gelatinous core of an intervertebral disc, typically constructed from polyurethane or silicone elastomers that replicate native nucleus pulposus viscoelasticity under compressive and shear loading. Its primary purpose is to restore disc height, maintain segmental motion, and delay or prevent adjacent-level degeneration in patients with early-stage disc disease. Nucleus replacement products lead procedural volume due to lower invasiveness compared with total disc replacement, while polyurethane-based implants command attention for fatigue resistance and biostability. Minimally invasive techniques are expanding fastest as surgical training and specialized instrumentation reduce approach-related morbidity.
The FDA premarket notification process and EU MDR conformity assessment impose escalating clinical evidence and post-market surveillance obligations on manufacturers of permanent spinal implants. ISO 10993 biocompatibility testing series and ASTM F2077 mechanical testing standards govern material qualification and device durability validation for nucleus replacement systems. Stakeholders must monitor evolving reimbursement decisions by CMS and national health technology assessment bodies, as coverage determinations for motion-preserving spine procedures will shape commercial viability faster than regulatory clearance alone.
Market Dynamics
EU MDR conformity assessment timelines and FDA premarket notification pathways are compressing commercialization windows for nucleus replacement systems, forcing manufacturers to front-load clinical evidence generation and biocompatibility validation before securing reimbursement eligibility.
Growth Catalysts
- Motion-Preserving Reimbursement Frameworks:CMS coverage determinations in the United States for nucleus replacement procedures are expanding procedural access for degenerative disc disease patients previously restricted to fusion surgery.
- Polyurethane Elastomer Advances:Fatigue-resistant polymer formulations are extending implant durability under cyclic loading, reducing revision rates and broadening candidate selection criteria.
- Minimally Invasive Surgical Training:Specialized instrumentation and cadaveric simulation programs are reducing approach-related morbidity, accelerating hospital adoption of nucleus replacement over total disc arthroplasty.
Market Restraints
- Silicone Raw Material Concentration:Medical-grade silicone supply chains cluster in Northeast Asian chemical processing hubs, exposing manufacturers to input volatility and geopolitical disruption risk.
- Adjacent-Level Degeneration Uncertainty:Long-term biomechanical data on segmental motion preservation remains incomplete, constraining orthopedic surgeon confidence in prophylactic intervention timing.
- EU MDR Technical Documentation Burden:Expanded clinical evaluation requirements and notified body capacity constraints are extending time-to-market for novel nucleus replacement designs by 18-24 months.
Strategic Opportunities
- Japan's Aging Surgical Population:PMDA streamlined review pathways for priority medical devices create expedited market entry for nucleus replacement systems demonstrating non-inferiority to fusion.
- Outpatient Surgery Center Penetration:Ambulatory surgical facilities in the United States are adopting same-day discharge protocols for minimally invasive spine procedures, displacing traditional hospital inpatient volumes.
- Digital Surgical Planning Convergence:Integration of patient-specific 3D modeling with intraoperative navigation is enabling precision implant sizing and positioning, reducing operative time and revision risk.
Industry Challenges
- Biomechanical Testing Talent Scarcity:ISO 10993 and ASTM F2077 validation expertise concentrates in specialized contract research organizations, creating recruitment bottlenecks for in-house regulatory affairs teams.
- Post-Market Surveillance Infrastructure:EU MDR mandates for active implant monitoring require manufacturers to build proprietary patient registries, demanding sustained capital deployment without immediate revenue offset.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prosthetic Disc Nucleus Market |
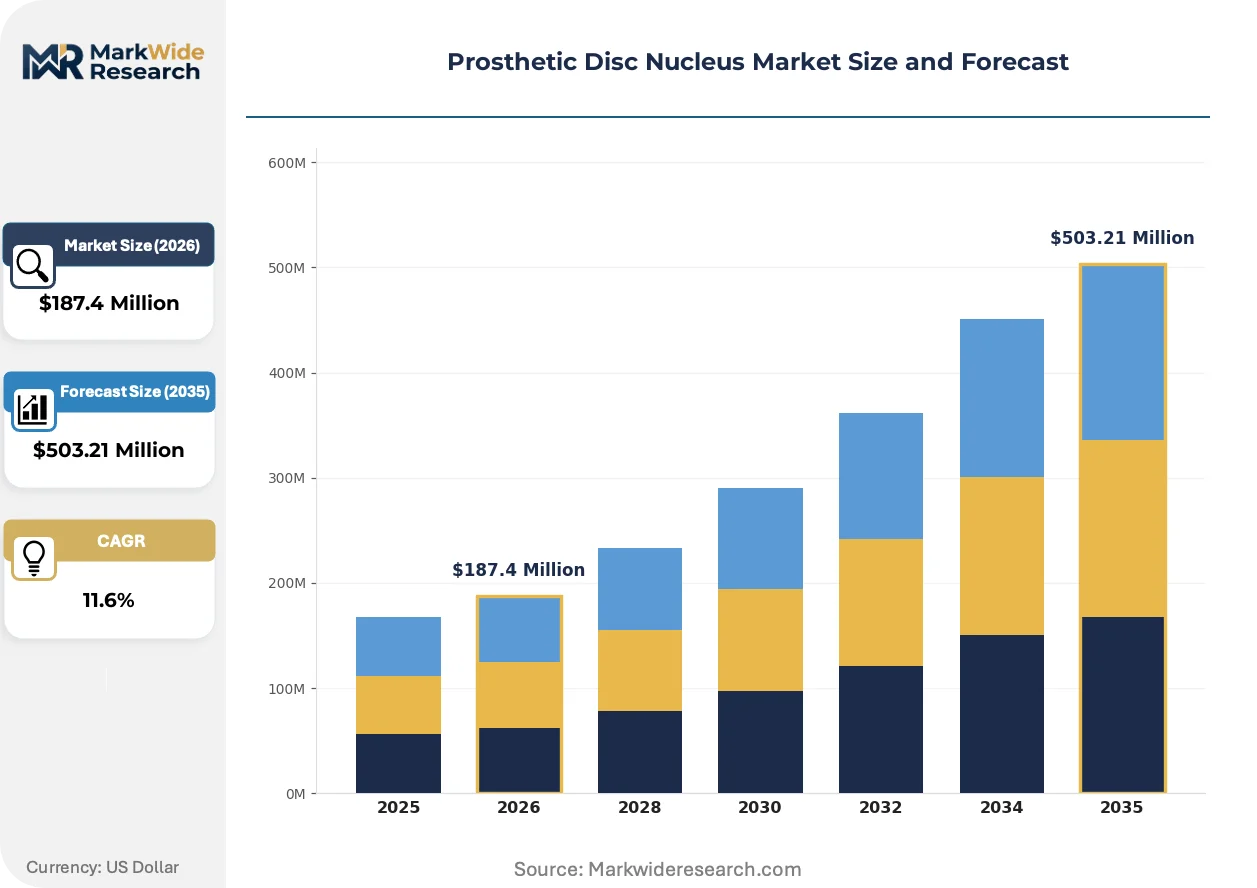
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nucleus Replacement, Intervertebral Spacer, Total Disc Replacement, Anterior Lumbar Interbody Fusion Material: Polyurethane, Titanium, Polyethylene, Silicone End User: Hospitals, Clinics, Rehabilitation Centers, Outpatient Surgical Facilities Technology: 3D Printing, Biocompatible Materials, Computer-Assisted Surgery, Minimally Invasive Techniques |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings Inc., NuVasive Inc., DePuy Synthes, Medtronic plc, Replication Medical Inc., Spine Wave Inc., Orthofix Medical Inc., Globus Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prosthetic Disc Nucleus Market Emerging Trajectories
Computational biomechanics and patient-specific implant design are converging to displace empirical sizing methods, while regulatory frameworks on both sides of the Atlantic tighten evidentiary standards for permanent spinal implants.
Polyurethane-hydrogel composite cores are virtualizing traditional silicone nucleus designs by matching native nucleus pulposus viscoelasticity across compressive and shear loading profiles. Academic medical centers in Germany and the United States are piloting these materials in prospective registries. This convergence is virtualizing the historical silicone-polyurethane material segmentation, compressing supplier differentiation to fatigue testing performance.
EU MDR Article 54 and Annex XIV clinical evaluation requirements are mandating prospective post-market clinical follow-up for class III implantable devices, including nucleus replacement systems. Manufacturers must now commit to 10-15 year patient surveillance protocols before CE marking. Small and mid-cap device developers without existing registry infrastructure face disproportionate compliance costs, accelerating consolidation toward integrated spine platforms.
Hospital value analysis committees are consolidating purchasing authority for high-cost spinal implants, displacing individual surgeon preference as the primary procurement determinant. Integrated delivery networks in the United States are negotiating multi-year sole-source agreements with manufacturers offering bundled instrument and implant pricing. This concentration is most visible in Midwestern and Southeastern hospital systems where orthopedic service line integration has advanced furthest.
Prosthetic Disc Nucleus Market Segmentation
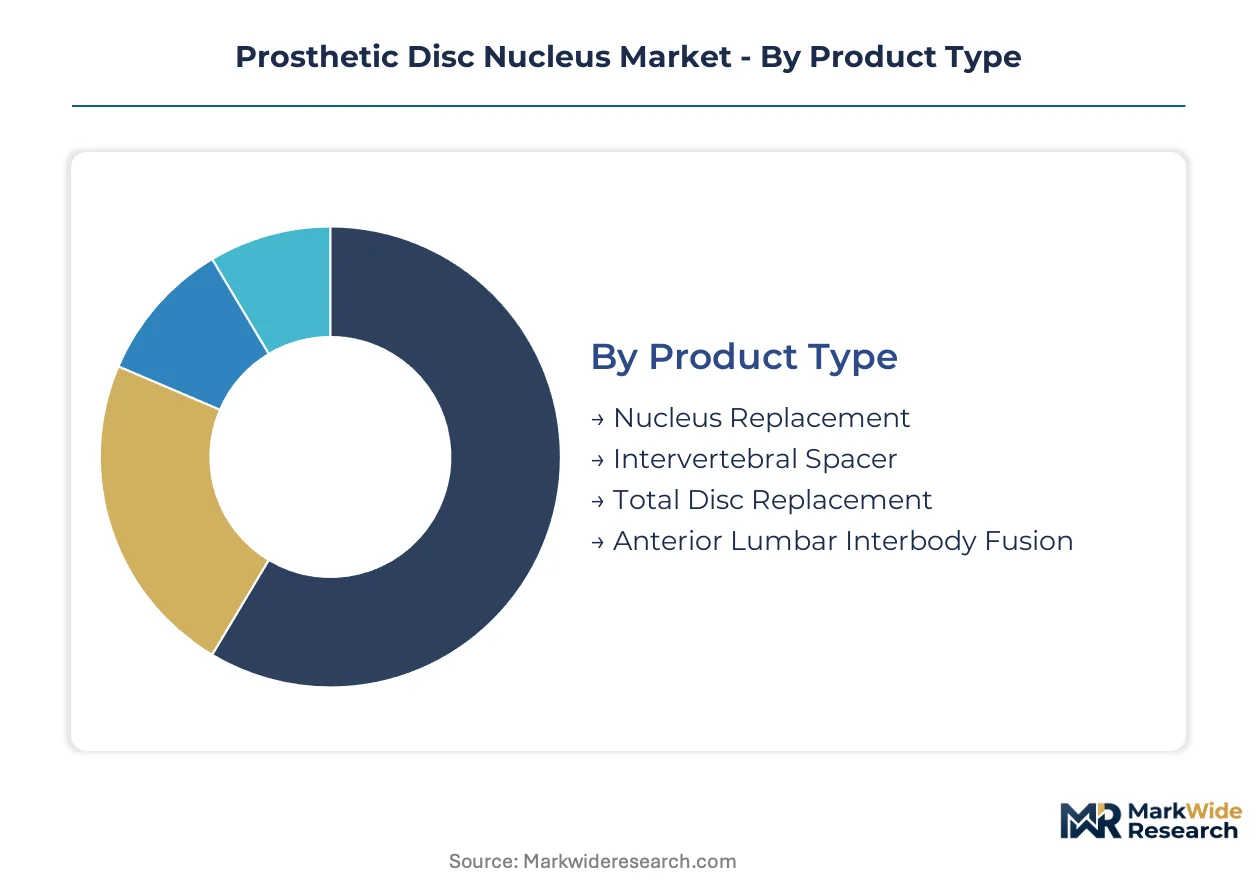
Prosthetic disc nucleus manufacturers configure product portfolios across four intersecting dimensions. Each segmentation axis carries distinct regulatory, reimbursement, and technical requirements that shape commercial strategy.
Product Type:
Cost tier stratification separates motion-preserving implants from fusion alternatives, with procedure invasiveness and hospital reimbursement levels determining placement.
- Nucleus Replacement:Polyurethane or silicone elastomer cores replicate native nucleus pulposus viscoelasticity under cyclic loading. German and United States hospitals are expanding procedural volume for early-stage degenerative disc disease where disc height preservation remains achievable.
- Total Disc Replacement:Complete functional spinal unit reconstruction using metal-on-polyethylene or metal-on-metal articulating surfaces. United States CMS coverage determinations and private payer prior authorization requirements constrain adoption to specialized orthopedic centers with established motion-preserving surgical programs.
- Intervertebral Spacer:Titanium or PEEK cages maintain disc space during bony fusion. Demand concentrates in trauma and revision settings where immediate structural support outweighs motion preservation objectives.
- Anterior Lumbar Interbody Fusion:Anterior approach cages with integrated fixation enable single-position surgery. Adoption tracks general spine fusion volume trends without distinct nucleus replacement growth characteristics.
Nucleus replacement commands the established base. The steepest expansion runs through total disc replacement as long-term durability data accumulates.
Material:
Application requirements dictate material selection, with fatigue resistance and biostability governing polymer formulations while osseointegration drives metal surface engineering.
- Polyurethane:Segmented block copolymer formulations deliver tunable stiffness and hydrolytic stability under physiological conditions. ASTM F2077 testing protocols validate cyclic fatigue performance, with United States and German manufacturers prioritizing this chemistry for next-generation nucleus cores.
- Silicone:Cross-linked polydimethylsiloxane networks provide established biocompatibility profiles and processing scalability. Raw material concentration in Northeast Asian chemical processing hubs exposes supply chains to geopolitical disruption risk.
- Titanium:Porous surface architectures promote bone ongrowth for interbody fusion applications. Machining and additive manufacturing routes compete on cost and geometric complexity.
- Polyethylene:Ultra-high molecular weight grades serve as bearing surfaces in total disc replacement articulating couples. Oxidative degradation resistance determines clinical longevity in vivo.
Polyurethane anchors the innovation pipeline. Silicone retains the largest installed base.
End User:
Customer type fragmentation reflects site-of-care migration and reimbursement differential between inpatient and ambulatory settings.
- Hospitals:Integrated delivery networks in the United States Midwest and Southeast negotiate multi-year sole-source agreements for high-cost spinal implants. Value analysis committees consolidate purchasing authority, displacing individual surgeon preference.
- Outpatient Surgical Facilities:Same-day discharge protocols for minimally invasive spine procedures are gaining traction in United States ambulatory surgery centers. CMS reimbursement parity with hospital outpatient departments accelerates volume shift.
- Clinics:Conservative management settings drive diagnostic and referral volume without direct implant procurement.
- Rehabilitation Centers:Post-acute care facilities manage functional recovery following surgical intervention, representing downstream demand rather than procurement decision points.
Hospitals command the established base. Outpatient surgical facilities are climbing the fastest.
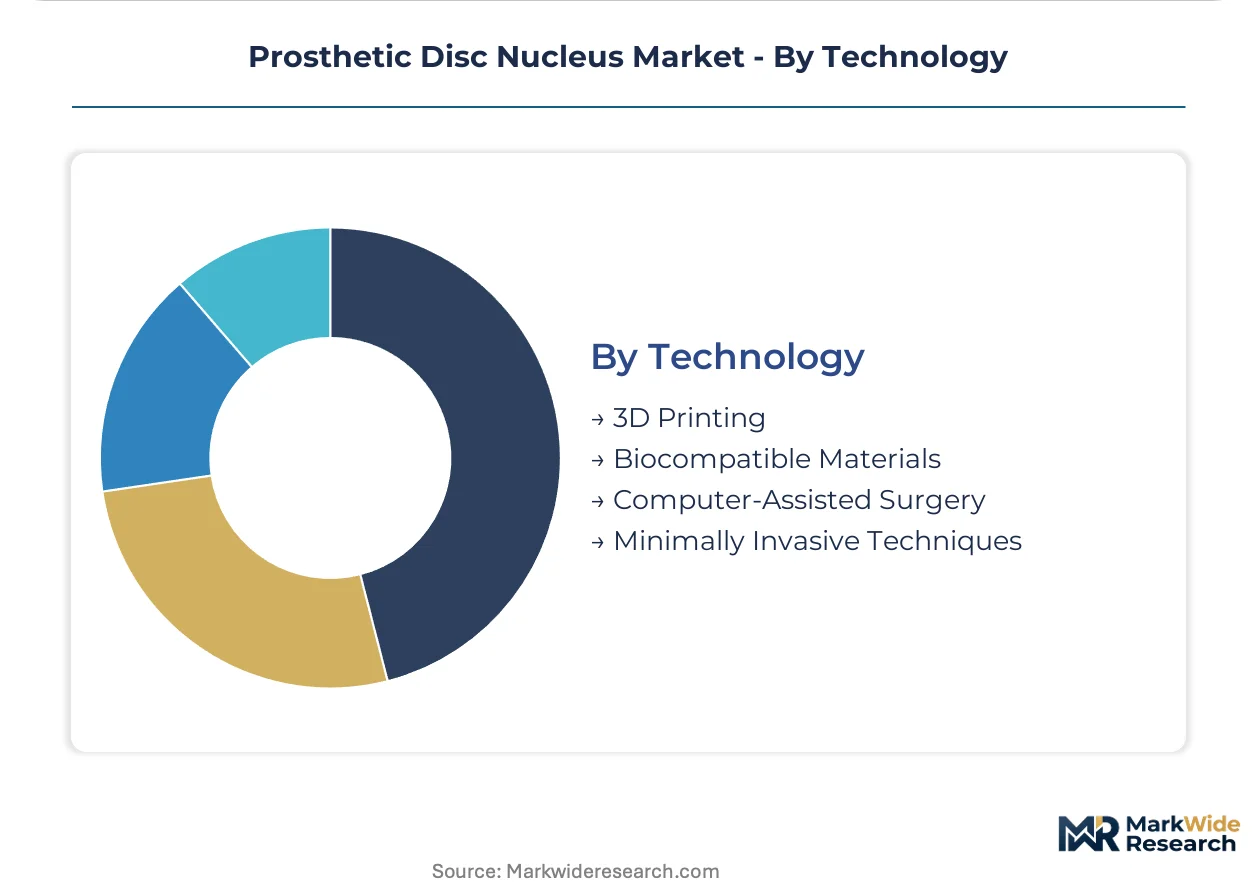
Technology:
Volume concentration in minimally invasive access routes is reshaping instrumentation requirements and surgeon training investments.
- Minimally Invasive Techniques:Specialized retractor systems and intraoperative imaging reduce approach-related morbidity. Cadaveric simulation programs at United States academic medical centers accelerate surgeon learning curves.
- Computer-Assisted Surgery:Navigation platforms enable precision implant positioning, reducing operative time and revision risk. Integration with patient-specific 3D modeling is emerging in German and United States tertiary centers.
- 3D Printing:Additive manufacturing enables patient-specific interbody cages and porous titanium architectures. Regulatory pathways for printed spinal implants remain under development at FDA and under EU MDR.
- Biocompatible Materials:Surface modification chemistries and drug-eluting coatings represent incremental innovation rather than discrete technology platforms.
Minimally invasive techniques command the established base. Computer-assisted surgery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's central role in European medical device distribution, connecting polyurethane raw material suppliers to implant manufacturing clusters.
United States
CMS reimbursement determinations for motion-preserving spine procedures are expanding procedural access beyond fusion-restricted patient populations. FDA premarket notification pathways impose escalating clinical evidence requirements on nucleus replacement manufacturers. The Minneapolis-Saint Paul corridor anchors specialized spine device development, with academic medical centers piloting patient-specific implant designs.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are expanding nucleus replacement volumes for early-stage degenerative disc disease. EU MDR conformity assessment through notified bodies in Berlin and Munich extends time-to-market for novel designs by 18-24 months. The Stuttgart-Tübingen medical technology cluster concentrates fatigue-testing expertise for polyurethane elastomer validation.
Japan
PMDA streamlined review pathways for priority medical devices are expediting market entry for nucleus replacement systems demonstrating non-inferiority to fusion. METI industrial policy supports domestic production of medical-grade silicone alternatives. The Kobe-Osaka medical device corridor hosts specialized polymer processing facilities serving spinal implant manufacturers.
United Kingdom
NICE health technology assessments are tightening evidentiary thresholds for motion-preserving spine procedures in NHS commissioning frameworks. MHRA post-Brexit regulatory autonomy is diverging from EU MDR implementation timelines. The Cambridge-Oxford-London golden triangle concentrates computational biomechanics research for patient-specific implant modeling.
Switzerland
Swissmedic's expedited review pathways for breakthrough devices attract spinal implant developers seeking faster European market access. The country's precision manufacturing heritage supports micron-level tolerance production for nucleus replacement cores. The Lake Geneva region clusters orthopedic research institutes collaborating with polymer chemistry specialists from Basel's pharmaceutical corridor.
Prosthetic Disc Nucleus Market Vendor Landscape
On the supply side, the industry is consolidating around integrated spine platforms with established hospital contracting relationships and specialized regulatory affairs infrastructure. Tier-one manufacturers with multi-decade FDA master files dominate procurement decisions at United States integrated delivery networks. Mid-cap specialists concentrate on single-technology nucleoplasty systems. Dominant competitive moves include backward integration into medical-grade polymer compounding and exclusive distribution partnerships with ambulatory surgery center chains.
Within the integrated platform tier, Stryker Corporation and Zimmer Biomet Holdings Inc. occupy positions defined by instrument-and-implant bundling capabilities and multi-hospital system contracting authority. NuVasive Inc. exemplifies the access-technology specialist archetype, pairing minimally invasive surgical training infrastructure with implant distribution. These three entities represent distinct strategic postures: full-line spine integration, orthopedic-neurosurgical cross-selling, and procedure-specific ecosystem control.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings Inc. |
| NuVasive Inc. |
| DePuy Synthes |
| Medtronic plc |
| Replication Medical Inc. |
| Spine Wave Inc. |
| Orthofix Medical Inc. |
| Globus Medical Inc. |
| Others |
Supply Flow & Price Mechanics
Medical-grade silicone raw material concentration in Northeast Asian chemical processing hubs exposes manufacturers to input volatility and tariff disruption risk, compressing margin spreads between premium polyurethane-based nucleus replacements and standard silicone-core alternatives while simultaneously forcing supply chain restructuring toward dual-source polymer qualification.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between United States integrated delivery networks and implant manufacturers, with three-tier pricing separating FDA-breakthrough-designation premium cores from standard CE-marked devices and economy-grade fusion alternatives. Price differentiation hinges on ISO 10993 biocompatibility certification tier and surgeon training program bundling. Pricing pressure stems from hospital value analysis committee consolidation in Midwestern and Southeastern health systems. Ambulatory surgery centers exhibit highest price sensitivity due to CMS reimbursement parity constraints, while academic medical centers prioritize clinical evidence depth over unit cost.
Supply Chain Analysis
Export-control regime scrutiny of advanced polymer processing equipment limits technology transfer to medical-grade elastomer compounders in Germany and Switzerland, constraining capacity expansion outside established Northeast Asian chemical hubs. Supply concentration centers on Japan for silicone monomer feedstock, Germany for polyurethane block copolymer formulation, and the United States for precision molding instrumentation. Raw material dependencies encompass polydimethylsiloxane precursors, segmented polyether-urethane intermediates, and titanium porous substrates. Single-source vulnerability pervades medical-grade silicone supply chains. Distribution runs through hospital procurement consortiums and specialized orthopedic distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades the prosthetic disc nucleus landscape as outpatient surgery center penetration in the United States creates procurement niches outside integrated delivery network contracting umbrellas.
For Market Incumbents: Harden regulatory affairs infrastructure against EU MDR Annex XIV clinical evaluation burdens by building proprietary patient registries before CE marking commitments mature. Deepen backward integration into medical-grade polyurethane compounding to insulate margin structures from Northeast Asian silicone price volatility. Prioritize hospital system partnerships in Germany and the United States where motion-preserving reimbursement frameworks are expanding fastest. For New Entrants and Emerging Players: Establish a beachhead in ambulatory surgery center distribution channels where traditional orthopedic implant incumbents maintain weaker contractual lock-in. Target Japan's priority medical device review pathway for expedited PMDA clearance leveraging non-inferiority trial designs against fusion benchmarks. Deploy digital surgical planning software bundling as the primary go-to-market wedge to differentiate commodity implant hardware. For Investors and Strategic Acquirers: EU MDR Article 54 post-market surveillance mandates reshape the acquisition landscape by inflating compliance costs disproportionately for mid-cap developers lacking existing registry infrastructure. Long-term viability concentrates in platforms with demonstrated 10-15 year patient follow-through capabilities and notified body relationships in Berlin or Munich. Target acquisition archetypes include specialized polyurethane fatigue-testing contract research organizations and ambulatory surgery center chain distribution networks. Watch FDA breakthrough device designation grants as the signal indicating which nucleus replacement technologies will secure accelerated reimbursement coverage determinations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates CMS reimbursement coverage determinations for motion-preserving spine procedures. |
| EU MDR Notified Body Partnership | Secures conformity assessment capacity in Berlin and Munich for CE marking pathways. |
| Hospital System Sole-Source Contracting | Locks in multi-year procurement agreements with United States integrated delivery networks. |
| Patient Registry Infrastructure Buildout | Satisfies Annex XIV post-market clinical follow-up mandates for class III implantable devices. |
| Digital Surgical Planning Integration | Enables precision implant sizing partnerships with German and United States academic centers. |
Methodological Framework
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital purchasing committee members, biomedical engineers specializing in spinal biomechanics, and regulatory affairs directors at implant manufacturers, then refined through secondary validation against FDA 510(k) premarket notification databases, EU MDR notified body public summaries, CMS national coverage determination records, and ASTM F2077 mechanical testing standards. Bottom-up procedural volume estimates from hospital procurement databases were triangulated against top-down market sizing derived from polyurethane and silicone raw material consumption patterns reported in chemical industry trade data.
Demand-supply-balance framing anchored the forecast framework across the analysis window, with segmentation modeling across product type, material chemistry, end-user site of care, and surgical access technology dimensions. CAGRs were derived from elasticity-adjusted procedure volume projections and average selling price trajectories indexed to reimbursement rate movements. Industry-specific forecast inputs incorporated EU MDR implementation timeline delays and PMDA priority review pathway admission rates.
Sensitivities concentrate around FDA premarket notification pathway duration variability, EU notified body capacity constraints extending conformity assessment timelines, and CMS coverage determination reversals for motion-preserving spine procedures. Forecasts reflect documented assumptions regarding silicone raw material price stability and hospital consolidation pace. Material shifts in United States ambulatory surgery center reimbursement parity or EU MDR post-market surveillance enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Human Enhancement Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Global Medical Device Connectors Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
Europe Implantable Medical Devices Market
Medical Devices
Clear Aligners Market
Medical Devices
Contact Lenses Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Struts Implants Market
Medical Devices
Global Cosmetic Implants Market