
 Cerebral Folate Deficiency Market | 2026-2036
Cerebral Folate Deficiency Market Size, Share, and Industry Trends Forecast 2026-2036
Cerebral Folate Deficiency Market Outlook
Single-source API procurement for folate derivatives is pivoting toward multi-source agreements as manufacturers seek supply security. Pfizer leverages its biologics manufacturing scale to secure raw material volumes for injectable folate formulations. Hikma Pharmaceuticals anchors its position through generic oral folate portfolios distributed across hospital networks. Eli Lilly and Company differentiates via neuroscience R&D pipelines targeting inborn errors of metabolism.
Cerebral folate deficiency denotes a neurological disorder characterized by insufficient 5-methyltetrahydrofolate transport across the blood-brain barrier, typically quantified by cerebrospinal fluid folate levels below normal thresholds, requiring exogenous folinic acid or 5-MTHF supplementation to restore central nervous system methylation processes. Supplements dominate current volume as first-line maintenance therapy, while injections capture premium positioning for acute depletion cases requiring rapid CNS saturation. Pediatric end users represent the fastest-expanding addressable base, driven by expanded newborn screening programs and early genetic diagnosis of FOLR1 mutations.
The FDA orphan drug framework and EMA's rare disease incentives shape competitive entry timelines and exclusivity value for novel folate transport modulators. The EPA and national pharmacovigilance bodies enforce purity standards for medical foods and compounded folate preparations, directly influencing formulation costs and batch release protocols. Stakeholders must monitor evolving blood-brain barrier delivery technologies and regulatory harmonization between FDA and EMA rare disease pathways to anticipate portfolio prioritization shifts.
Market Dynamics
The FDA's orphan drug designation pathway is compressing development timelines for rare metabolic disorders while specialized metabolic centers concentrate diagnostic capacity in urban clusters, creating supply-demand asymmetries for folate-based therapeutics.
Growth Catalysts
- Newborn screening expansion:State-level mandates in the United States are capturing FOLR1 mutations earlier, routing infants into pediatric neurology clinics before irreversible neurological damage occurs.
- EMA rare disease incentives:The European regulator's protocol assistance and fee reductions accelerate market entry timelines for novel folate transport modulators targeting blood-brain barrier penetration.
- Injectable formulation demand:Acute depletion cases in emergency metabolic settings require rapid CNS saturation, creating pull-through for hospital-based infusion protocols.
Market Restraints
- API supply concentration:Single-source procurement for 5-MTHF and folinic acid precursors creates vulnerability to batch contamination or geopolitical trade friction.
- Blood-brain barrier delivery limitations:Current oral and injectable routes achieve suboptimal cerebrospinal fluid folate restoration in severe transport-deficient phenotypes.
- Compounded preparation oversight:The EPA and state pharmacy boards enforce evolving purity standards that extend batch release timelines and elevate formulation costs.
Strategic Opportunities
- Gene therapy convergence:AAV-mediated FOLR1 expression vectors, combined with nanoliposomal folate encapsulation, could displace chronic supplementation paradigms.
- Direct-to-patient channels:Telehealth-integrated metabolic specialty practices are emerging as a distribution innovation for maintenance folate prescriptions.
- Japan's orphan drug framework:PMDA's Sakigake designation offers priority review for pediatric neurological indications with unmet need.
Industry Challenges
- Metabolic geneticist scarcity:The specialized workforce required for accurate FOLR1 sequencing interpretation and treatment protocol design remains concentrated in academic medical centers.
- CSF monitoring standardization:Cerebrospinal fluid folate assay harmonization across reference laboratories delays treatment initiation and confounds outcome measurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerebral Folate Deficiency Market |
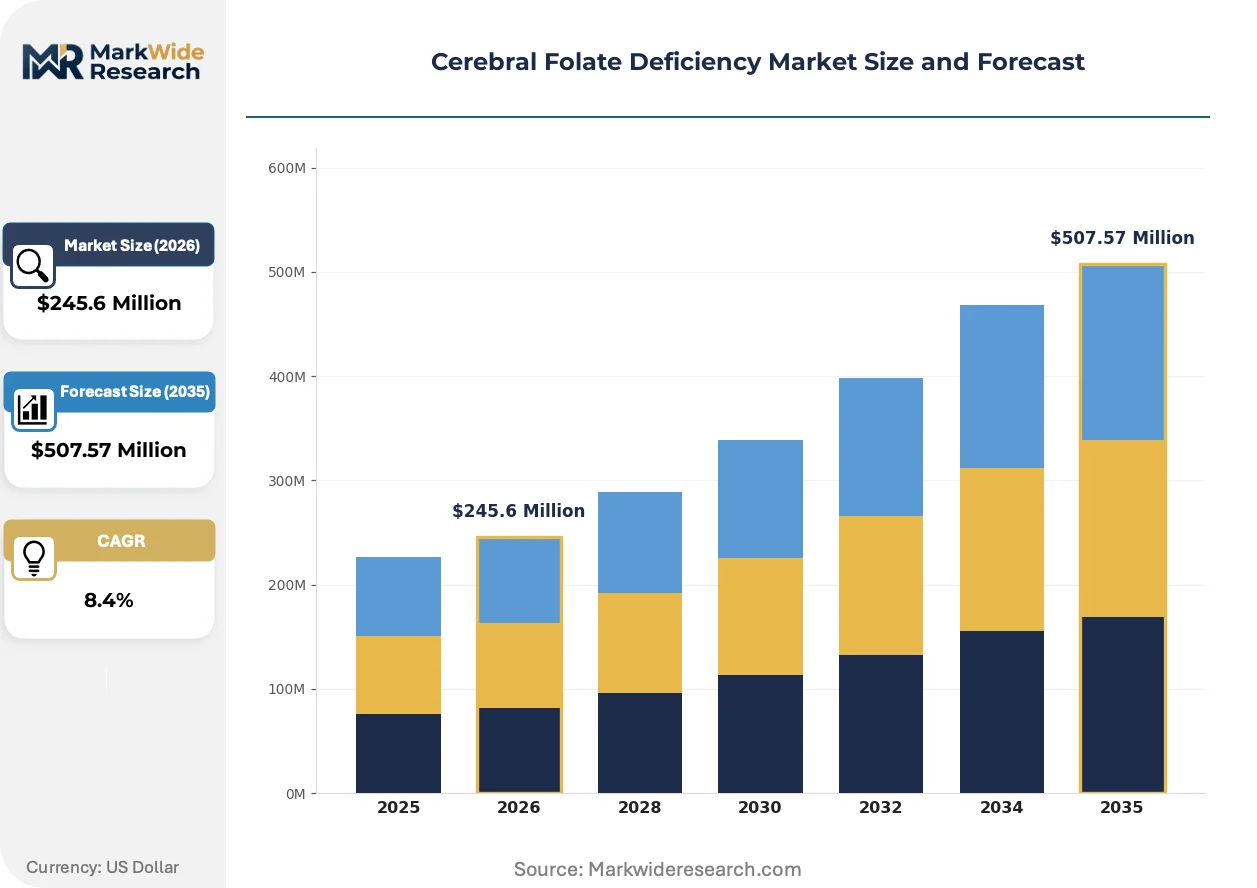
| Market Size in 2026 | $245.6 Million |
| Market Size in 2035 | $507.57 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supplements, Injections, Oral Solutions, Medical Foods End User: Pediatrics, Geriatrics, Neurology Clinics, Research Institutions Application: Therapeutic, Diagnostic, Preventive, Research Distribution Channel: Pharmacies, Online Retail, Hospitals, Specialty Stores |
| Companies Covered | Pfizer, Hikma Pharmaceuticals, Eli Lilly and Company, Sagent Pharmaceuticals, Jiangsu Hengrui Medicine, GSK, Vitaflo International Ltd, BASF SE, DSM Nutritional Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerebral Folate Deficiency Market Strategic Shifts
Nanoliposomal delivery systems and point-of-care genetic testing are compressing diagnostic-to-treatment intervals while regulatory incentives restructure competitive entry economics.
Lipid-encapsulated 5-methyltetrahydrofolate formulations achieve superior blood-brain barrier penetration compared to unconjugated analogs. Pediatric metabolic centers in Boston and San Francisco are piloting these platforms for rapid CNS saturation protocols. The technology is integrating into first-line acute management algorithms, displacing high-dose intravenous folinic acid in severe transport-deficient presentations.
The FDA's Rare Pediatric Disease Priority Review Voucher program creates transferable value for sponsors completing pivotal trials in cerebral folate deficiency. This incentive compresses effective development costs and attracts venture funding toward mechanistically novel programs. Early-stage biotechnology firms are restructuring trial designs to capture voucher eligibility, prioritizing pediatric-enriched enrollment strategies.
Hospital procurement committees are consolidating metabolic therapeutics under centralized pharmacy formularies, displacing individual prescriber autonomy in folate product selection. Academic medical centers with dedicated biochemical genetics divisions are capturing disproportionate volume as referral hubs concentrate. This concentration is most visible in the United States, where Medicaid managed care carve-outs for rare disease create network exclusivity pressures.
Cerebral Folate Deficiency Market Segmentation
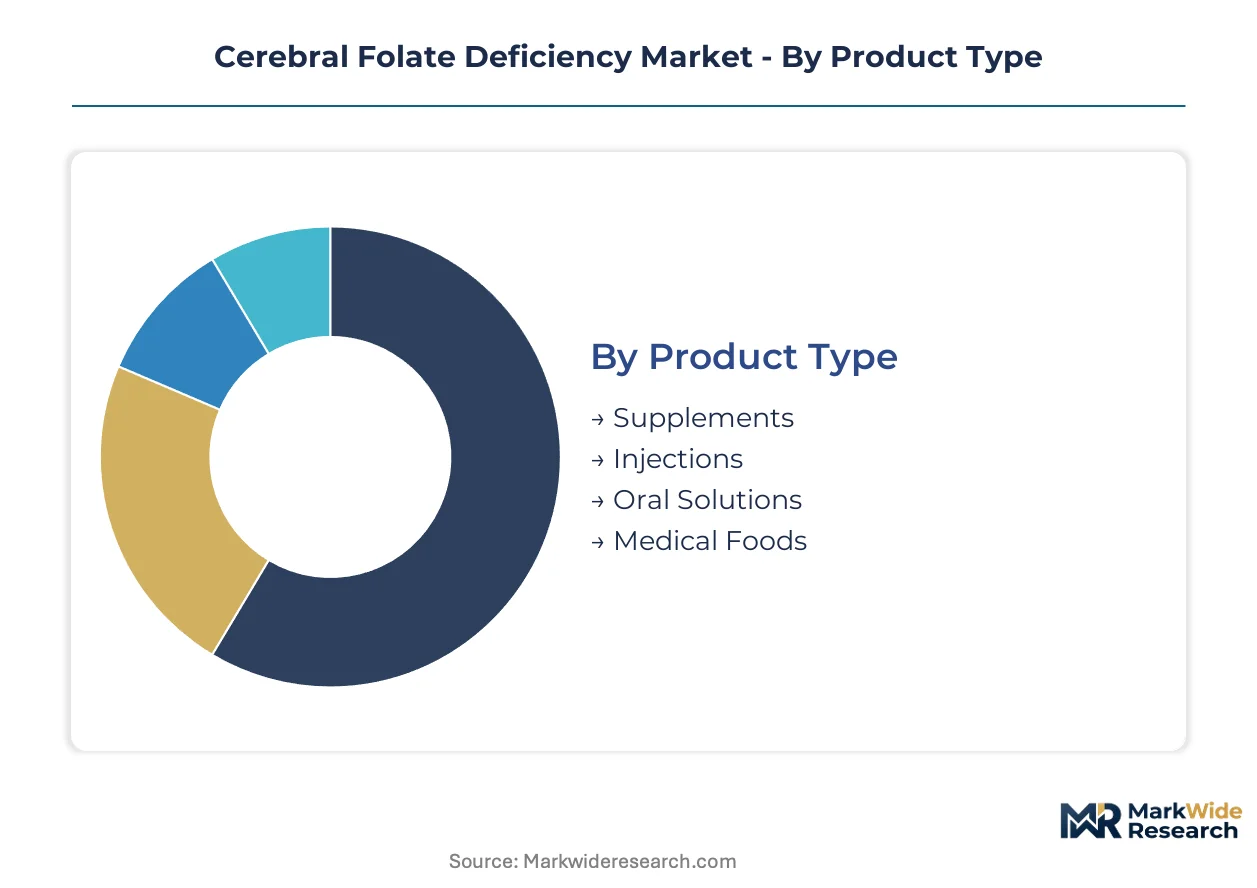
Segmentation in cerebral folate deficiency therapeutics reveals distinct clinical workflows and procurement pathways. Product form dictates blood-brain barrier delivery efficiency, while end-user concentration shapes regulatory prioritization and reimbursement negotiations.
Product Type:
Standardized formulations dominate high-volume maintenance protocols, whereas customized compounding serves refractory phenotypes with transport-protein mutations.
- Supplements:Oral folinic acid and 5-MTHF tablets constitute first-line maintenance therapy for confirmed FOLR1 deficiency. Pediatric neurology clinics in Boston and San Francisco route stable patients toward mail-order pharmacy fulfillment for chronic dosing. Demand concentrates in Medicaid managed care networks where prior authorization pathways favor generic oral formulations.
- Injections:Intravenous folinate calcium and 5-MTHF achieve rapid cerebrospinal fluid saturation in acute depletion crises. Hospital-based metabolic emergency protocols at academic medical centers in Philadelphia and Houston specify injectable thresholds for CSF folate below critical thresholds. Supply contracts with group purchasing organizations secure vial volumes for tier-one pediatric hospitals.
- Oral Solutions:Liquid 5-MTHF formulations enable dose titration in infants unable to swallow tablets.
- Medical Foods:FDA-regulated specialty preparations target inborn errors of folate metabolism requiring nutritional management.
Leading the category by volume: Supplements. Growing fastest: Injections.
End User:
Pediatric metabolic centers capture disproportionate diagnostic volume, while geriatric presentations remain underrecognized in standard neurological workups.
- Pediatrics:Newborn screening expansion in Texas, New York, and California routes FOLR1 mutation carriers into early-intervention protocols before irreversible neurodevelopmental injury. State laboratory networks report CSF folate assays within 72 hours of positive genetic screening.
- Geriatrics:Late-onset cerebral folate deficiency mimics neurodegenerative dementia, delaying accurate diagnosis. Academic memory clinics in Baltimore and Cleveland are piloting CSF folate panels for atypical cognitive decline presentations.
- Neurology Clinics:Specialized movement disorder and epilepsy practices manage complex folate transport phenotypes.
- Research Institutions:NIH-funded centers in Bethesda and university laboratories in Cambridge conduct natural history studies and biomarker validation.
Pediatrics commands the largest addressable base. Geriatrics shows the steepest expansion trajectory as diagnostic awareness penetrates dementia differential protocols.
Application:
Reimbursement intensity separates therapeutic utilization from preventive screening programs, with diagnostic applications concentrated in reference laboratory networks.
- Therapeutic:Chronic 5-MTHF supplementation restores CNS methylation capacity in confirmed transport-deficient patients. Maintenance dosing protocols at metabolic centers in Chicago and Los Angeles specify CSF monitoring intervals to guide dose escalation.
- Diagnostic:Lumbar puncture folate assays and FOLR1 sequencing confirm transport deficiency etiology. Commercial laboratories in North Carolina and Washington state compete on turnaround time for genetic panel interpretation.
- Preventive:High-risk pregnancy folate protocols target neural tube defect prevention.
- Research:Natural history registries and treatment outcome databases support orphan drug development.
Therapeutic applications generate the highest prescription volume. Diagnostic testing is climbing fastest as expanded screening mandates multiply confirmatory assay demand.
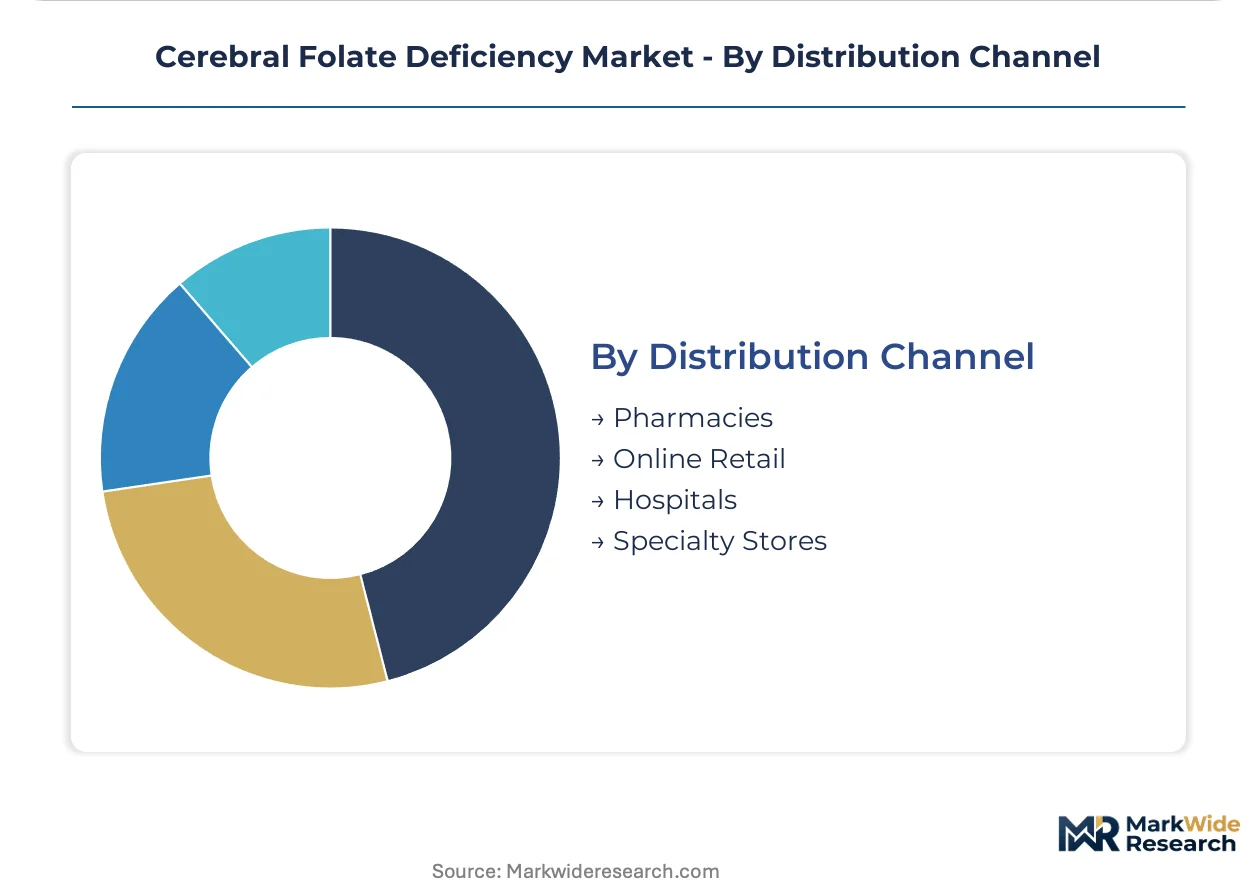
Distribution Channel:
Hospital consolidation is displacing independent pharmacy dispensing for acute injectable products, while specialty distributors capture medical food fulfillment.
- Pharmacies:Retail chains and independent compounders fill maintenance oral prescriptions for stable outpatients. CVS and Walgreens formulary committees in Florida and Ohio negotiate 5-MTHF generic pricing for chronic metabolic conditions.
- Hospitals:Centralized pharmacy operations at children's hospitals in Atlanta and Seattle control injectable folate procurement for emergency metabolic protocols. 340B pricing programs reduce acquisition costs for eligible pediatric institutions.
- Online Retail:Direct-to-consumer supplement platforms serve caregiver-managed maintenance dosing.
- Specialty Stores:Medical food distributors and metabolic nutrition suppliers serve institutional contracts.
Hospitals lead channel volume through injectable concentration. Online retail is expanding most quickly as telehealth-integrated metabolic practices enable remote prescription management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
5-methyltetrahydrofolate precursor manufacturing concentrates in Germany and Switzerland, anchoring European supply security for folate-based neurological therapeutics while specialized metabolic centers in the United States and Japan drive clinical protocol innovation.
United States
State-level newborn screening mandates in Texas, New York, and California capture FOLR1 mutations at birth, routing infants into early-intervention protocols. The FDA's orphan drug designation pathway compresses development timelines for rare metabolic disorders. Pediatric metabolic centers in Boston and Philadelphia concentrate diagnostic capacity and treatment protocol design.
Germany
Specialized biochemical genetics divisions at university hospitals in Munich and Heidelberg manage complex folate transport phenotypes with standardized CSF monitoring intervals. The EMA's rare disease incentives accelerate market entry timelines for novel folate transport modulators. Industrial chemical production in Ludwigshafen supplies pharmaceutical-grade folate precursors to European formulation facilities.
Japan
PMDA's Sakigake designation offers priority review for pediatric neurological indications with unmet need, attracting development programs for blood-brain barrier delivery technologies. The country's national pharmaceutical regulator enforces purity standards for medical foods that elevate batch release protocols. Tokyo and Osaka anchor metabolic specialty practices that integrate telehealth for maintenance folate prescription management.
United Kingdom
Academic medical centers in London and Cambridge conduct natural history studies and biomarker validation for orphan drug development. The country's national pharmaceutical regulator aligns with EMA rare disease pathways while maintaining distinct pediatric trial requirements. Specialized metabolic centers in Birmingham and Manchester capture regional referral volume for confirmed FOLR1 deficiency cases.
Switzerland
Swissmedic oversees quality standards for high-potency folate formulations used in severe transport-deficient presentations. Basel anchors pharmaceutical R&D concentration for neurological metabolic disorders. The country's specialized metabolic centers in Zurich and Geneva participate in multinational treatment outcome registries.
Cerebral Folate Deficiency Market Competitive Environment
Portfolio diversification dominates the current landscape as participants restructure around pediatric metabolic specialization and blood-brain barrier delivery innovation. The market exhibits tiered concentration with global pharmaceutical conglomerates, regional generic specialists, and nutrition-focused chemical producers occupying distinct strategic positions. Three archetypes prevail: large-cap diversified pharmaceutics with biologics manufacturing scale, mid-cap generic houses with hospital network penetration, and chemical-nutrition hybrids with API backward integration. M&A activity and technology licensing agreements represent the dominant competitive vectors reshaping participant positioning.
Among large-cap diversified pharmaceutics, Pfizer exemplifies biologics manufacturing scale applied to injectable folate formulation security, while Eli Lilly and Company occupies a position within neuroscience R&D pipelines targeting inborn errors of metabolism. Hikma Pharmaceuticals represents the generic-specialist archetype with hospital network distribution concentration for oral folate portfolios.
| Leading Market Players |
|---|
| Pfizer |
| Hikma Pharmaceuticals |
| Eli Lilly and Company |
| Sagent Pharmaceuticals |
| Jiangsu Hengrui Medicine |
| GSK |
| Vitaflo International Ltd |
| BASF SE |
| DSM Nutritional Products |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade 5-methyltetrahydrofolate precursor costs cascade from German and Swiss chemical manufacturers through formulation tollers to hospital procurement committees, with purity-grade differentials separating reference-standard injectables from maintenance oral tablets. This input-cost transmission creates pricing stratification across premium acute-care formulations, standard maintenance generics, and economy-tier compounded alternatives.
Pricing Analysis
Service bundling separates acute-care injectable packages with CSF monitoring protocols from unbundled oral maintenance prescriptions filled through retail channels. Three-tier pricing structure across premium, standard, and economy levels reflects FDA certification status, with 503B compounding pharmacy products commanding discounts against branded folinic acid. Cost compression in the generic oral tier is intensifying as Medicaid managed care formularies consolidate preferred drug lists. Pediatric metabolic centers show lowest price sensitivity due to urgency of treatment initiation, while caregiver-managed maintenance dosing exhibits highest sensitivity to out-of-pocket supplement costs.
Supply Chain Analysis
Dual-sourcing requirements mandated by hospital procurement committees now qualify at least two API suppliers for 5-MTHF and folinic acid precursors to mitigate batch contamination risk. Manufacturing concentrates in Germany, Switzerland, and India, with Ludwigshafen and Basel anchoring European pharmaceutical-grade output and Hyderabad supplying generic oral intermediates. Raw material dependencies include para-aminobenzoic acid, glutamic acid derivatives, and specialized reduction catalysts. Single-source vulnerability persists for nanoliposomal encapsulation technologies. Distribution runs through group purchasing organizations for injectable hospital products and specialty metabolic distributors for medical foods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API manufacturing capacity for pharmaceutical-grade folate derivatives operates at effective constraint, with only three qualified suppliers globally serving the acute-care injectable segment and propping premium pricing tiers.
For Market Incumbents: Anchor manufacturing security through captive supply of 5-MTHF precursors or long-term offtake agreements with Ludwigshafen and Basel chemical producers. Gene therapy vectors targeting FOLR1 expression threaten chronic supplementation paradigms; incumbents should secure exclusive licensing for nanoliposomal delivery platforms to defend formulation differentiation. Investment in FDA Rare Pediatric Disease Priority Review Voucher capture compresses effective development costs for novel transport modulators. For New Entrants and Emerging Players: The premium-economy price gap in oral maintenance folate creates entry space for 503B compounding specialists with validated purity protocols. Telehealth-integrated metabolic practices represent the most penetrable channel, enabling direct-to-patient fulfillment bypassing hospital formulary gatekeepers. Target geriatric neurology clinics in Baltimore and Cleveland with CSF folate assay bundling to capture late-onset diagnostic expansion. For Investors and Strategic Acquirers: FDA orphan drug designation grants for novel blood-brain barrier delivery technologies are the leading indicator that mechanistic innovation is achieving regulatory validation and venture-scale returns. Five-to-ten year viability hinges on displacement risk from gene therapy convergence; prioritize acquisition targets with nanoliposomal formulation IP and pediatric trial infrastructure. Watch for PMDA Sakigake designations in Tokyo and Osaka as early signals of Japanese market prioritization for blood-brain barrier platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA orphan drug designation compresses timelines for rare metabolic disorder therapeutics. |
| Backward Integration | Captive API production secures supply against German and Swiss chemical manufacturer constraints. |
| Hospital System Partnership | Academic medical center formulary placement locks in emergency metabolic protocol adoption. |
| Pipeline Diversification | Gene therapy vectors targeting FOLR1 expression address long-term chronic supplementation displacement. |
| Reimbursement Strategy | Medicaid managed care carve-out negotiations determine pediatric maintenance prescription access. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with primary interviews involving drug development executives at metabolic therapeutics firms, regulatory affairs leads specializing in orphan drug pathways, hospital procurement managers at pediatric academic medical centers, and formulary directors within Medicaid managed care organizations. Bottom-up prescription volume modeling triangulated against top-down metabolic center capacity estimates.
Historical trendline analysis of newborn screening expansion rates and CSF folate assay volumes established baseline growth trajectories across the projection horizon. Segmentation dimensions included product form, end-user concentration, application intensity, and regional regulatory cluster. CAGRs derived from treatment protocol adoption curves and diagnostic penetration rates, with inputs from FOLR1 mutation carrier frequency studies and metabolic geneticist workforce projections.
Underlying measurement precision varies by segment; pediatric therapeutic applications carry tighter precision than geriatric diagnostic testing due to standardized newborn screening data availability. Forecasts reflect assumptions regarding regulatory harmonization between FDA and EMA rare disease pathways and sustained Medicaid funding for metabolic specialty care. Deviation in gene therapy clinical trial readouts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Personalized Medicine Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Necrotizing Fasciitis Treatment Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market