
 Neurovascular Stent Market | 2026-2036
Neurovascular Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Neurovascular Stent Market Analysis
Nitinol is hardening its position against stainless steel in neurovascular stent construction as superelasticity and biocompatibility reduce vessel wall trauma. Stryker leverages its endovascular portfolio breadth to sustain hospital contracting power across integrated delivery networks. Medtronic anchors its competitive stance through deep interventional neuroscience specialization and physician training infrastructure.
A neurovascular stent is a tubular metallic or polymeric implant deployed endoluminally within intracranial or extracranial vessels to maintain patency, typically manufactured from nitinol wire mesh laser-cut into geometries between 2.5 and 4.5 mm diameter with wall thickness below 0.1 mm, serving to treat cerebral aneurysms, intracranial stenosis, and acute ischemic stroke. Self-expanding stents dominate procedural volumes due to conformability in tortuous cerebrovascular anatomy, while drug-eluting technology commands premium positioning as endothelialization control becomes a decisive functional parameter. Bioresorbable stents represent the fastest-growing technology segment as physicians seek to eliminate permanent foreign body retention in younger stroke patients.
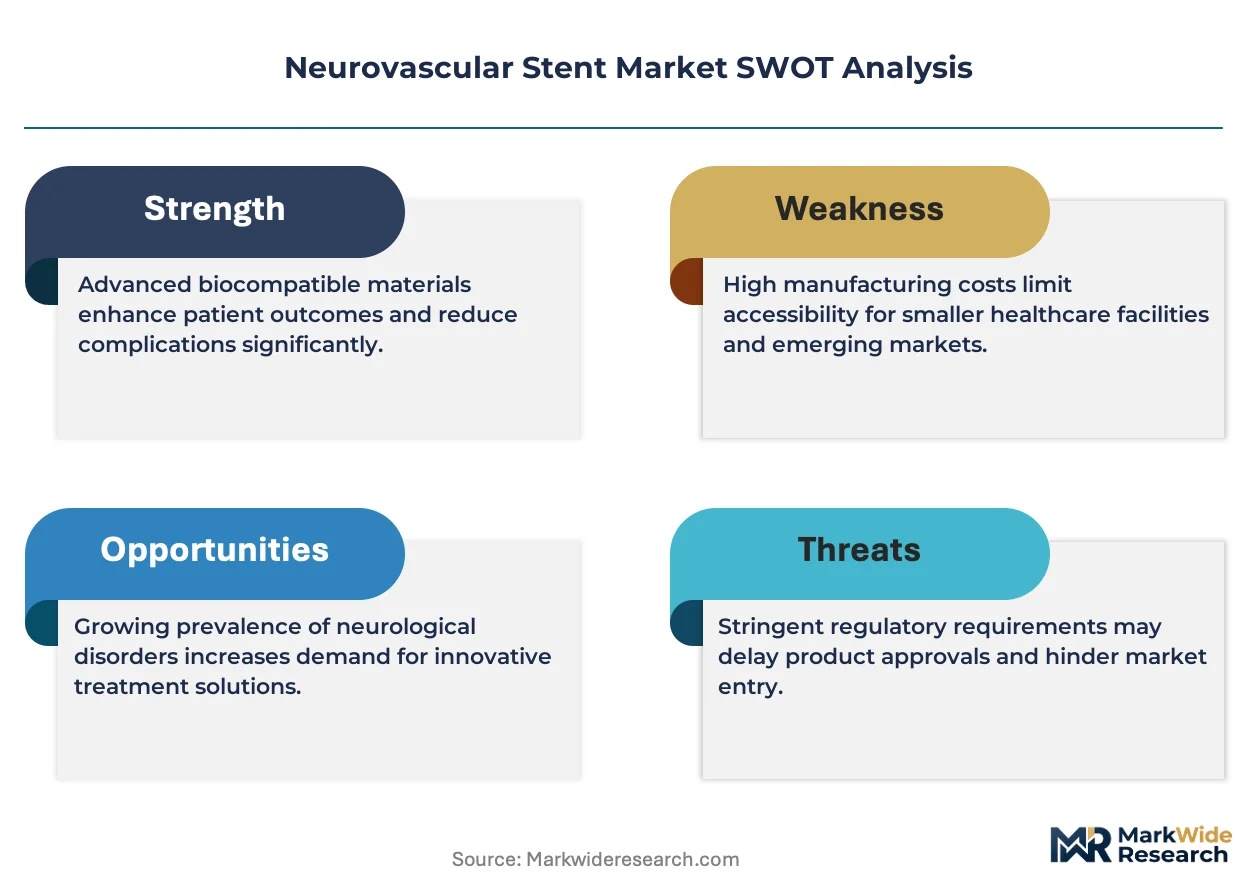
FDA premarket approval requirements and EU MDR technical documentation standards shape clinical trial investment thresholds and timeline risk for manufacturers seeking commercial access. Japan's PMDA enforces stringent QMS inspections that filter out smaller entrants lacking dedicated regulatory affairs capacity in Tokyo. Stakeholders must monitor reimbursement compression dynamics and real-world evidence mandates as payers shift from procedural volume toward outcome-validated technology access.
Market Dynamics
Nitinol superelasticity is displacing stainless steel as the dominant material platform, compressing manufacturing learning curves while FDA and EU MDR tighten clinical evidence thresholds for market entry.
Growth Catalysts
- Japan's aging stroke burden:PMDA reimbursement pathways for flow diversion procedures are expanding hospital neurointerventional capacity in Tokyo and Osaka stroke centers.
- EU MDR technical documentation:Stricter conformity assessment requirements are filtering out marginal competitors and consolidating procurement toward established nitinol device manufacturers.
- Bioresorbable magnesium alloys:Next-generation scaffold materials are opening pediatric and young-adult indications previously closed to permanent metallic implants.
Market Restraints
- Nitinol raw material concentration:Superelastic wire supply concentrates among three specialized metallurgical suppliers in Germany and the United States, creating input cost volatility.
- FDA premarket approval timelines:Extended clinical trial requirements for novel stent geometries delay commercialization by 24-36 months versus predicate device pathways.
- Intracranial stenting substitution:Mechanical thrombectomy devices and aspiration catheters are capturing acute ischemic stroke cases previously routed to stent-assisted therapy.
Strategic Opportunities
- India's underpenetrated stroke infrastructure:CDSCO regulatory harmonization and private hospital chain expansion in Mumbai and Delhi are creating first-mover positioning for self-expanding stent platforms.
- Flow diversion for unruptured aneurysms:Pipeline embolization indications are broadening beyond posterior circulation to include complex anterior communicating artery lesions.
- Digital surgery integration:AI-powered intraoperative navigation is converging with robotic delivery systems to reduce radiation exposure and procedure time in catheterization laboratories.
Industry Challenges
- Interventional neuroradiologist scarcity:Fellowship-trained physicians capable of navigating tortuous cerebrovascular anatomy remain concentrated in academic medical centers, limiting procedural volume expansion.
- EU MDR notified body capacity:Consolidation of certification bodies under stricter designation requirements is extending technical documentation review timelines and compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurovascular Stent Market |
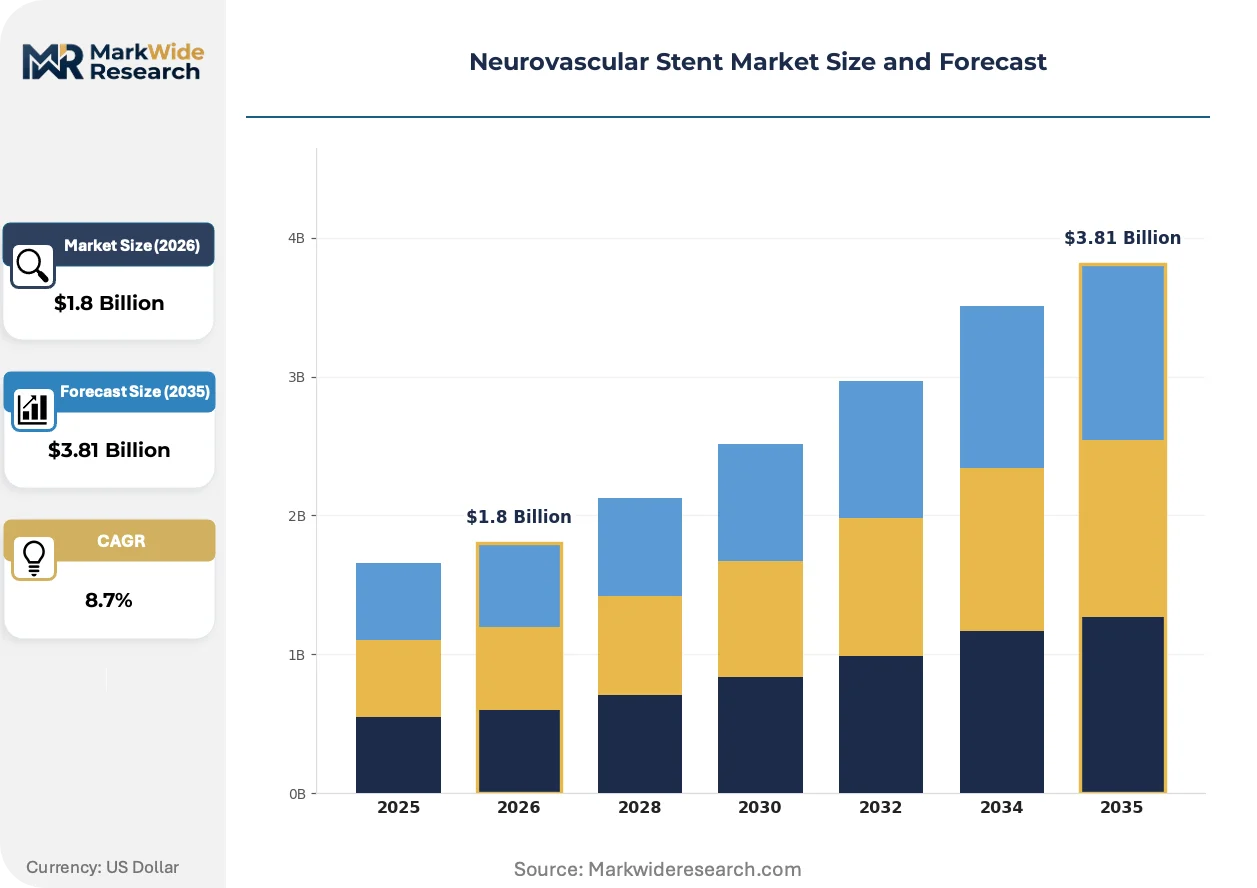
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon-Expandable Stents, Self-Expanding Stents, Hybrid Stents, Covered Stents Material: Stainless Steel, Nitinol, Polymer, Coated Alloys Technology: Drug-Eluting Stents, Bare Metal Stents, Bioresorbable Stents, Coated Stents End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes |
| Companies Covered | Stryker, Johnson & Johnson Services Inc., Terumo Corporation, Medtronic, Boston Scientific Corporation, MicroPort Scientific Corporation, Abbott Laboratories, W. L. Gore & Associates, Acandis GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurovascular Stent Market Emerging Trajectories
Computational modeling and advanced manufacturing are compressing device development cycles while regulatory science evolves toward real-world evidence acceptance.
Robot-assisted catheter navigation is automating precise deployment in tortuous intracranial vessels. Academic stroke centers in Germany and Japan are piloting these platforms to reduce fluoroscopy time and operator radiation exposure. The technology is automating standardization of stent placement accuracy previously dependent on individual physician tactile skill.
EU MDR post-market surveillance requirements are mandating systematic collection of long-term patient outcomes. Manufacturers must now maintain active implant registries tracking aneurysm occlusion rates and in-stent stenosis across diverse European hospital settings. Small-cap device firms lacking dedicated regulatory affairs infrastructure in Brussels are exiting the neurovascular category rather than absorbing compliance costs.
Hospital procurement committees are consolidating vendor contracts around comprehensive stroke program partnerships rather than transactional device purchasing. Integrated delivery networks in the United States are bundling stent procurement with physician training and 24-hour technical support commitments. This behavioral shift is most visible in Florida and Texas, where for-profit hospital systems are reducing their active neurovascular supplier rosters from six to two preferred vendors.
Neurovascular Stent Market Segmentation
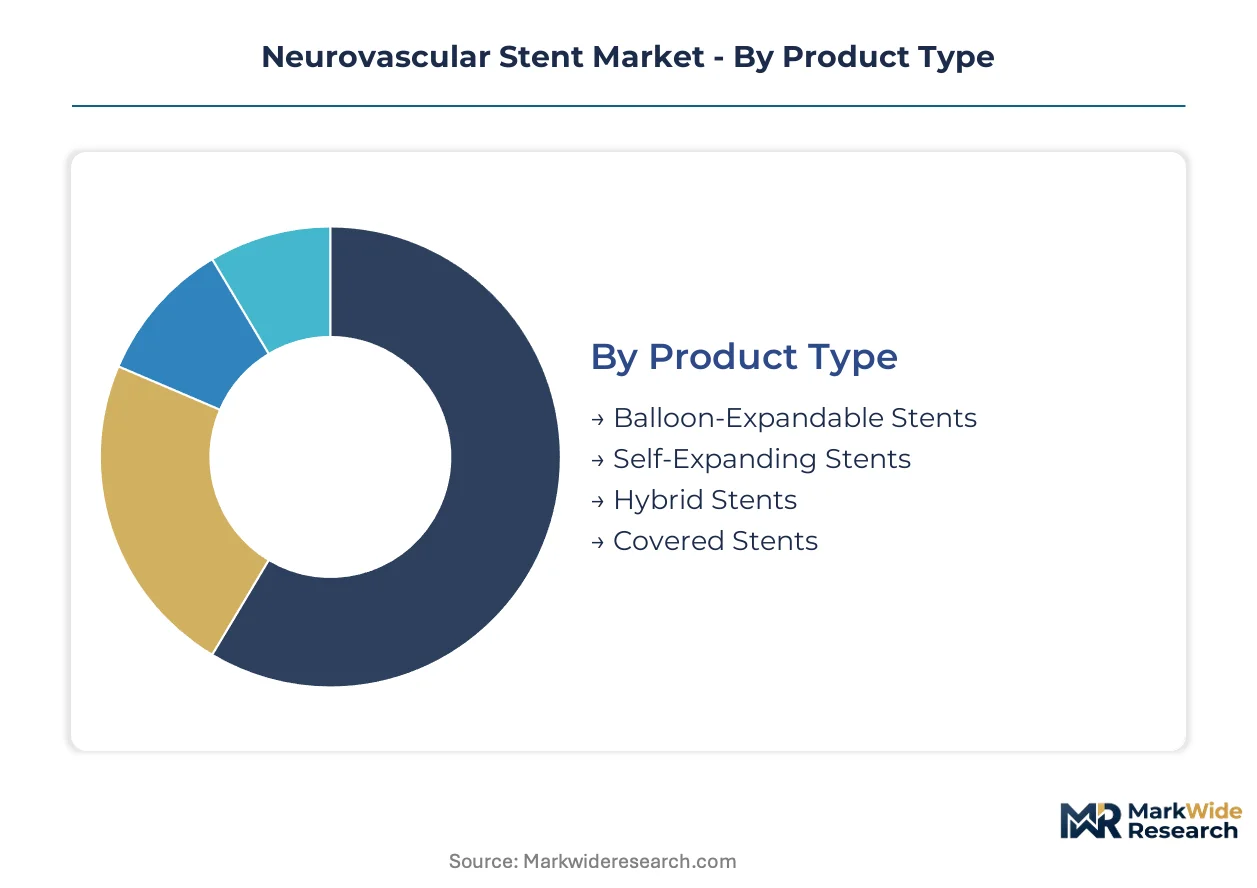
Neurovascular stent procurement decisions hinge on anatomical complexity, lesion morphology, and reimbursement pathways. Manufacturers align R&D spending and regulatory submissions against segments where procedural volumes and price premiums intersect most favorably.
Product Type:
Capital intensity peaks in platforms requiring proprietary laser-cutting infrastructure and superelastic wire processing capabilities.
- Self-Expanding Stents:Nitinol wire mesh constructions between 2.5-4.5 mm diameter deploy through microcatheters without balloon inflation. Demand concentrates in United States stroke centers where tortuous posterior circulation anatomy requires conformable scaffolding. PMDA reimbursement expansion in Japan's Tokyo and Osaka clusters is accelerating hospital conversion from balloon-expandable alternatives.
- Balloon-Expandable Stents:Stainless steel or cobalt-chromium platforms mounted on delivery balloons enable precise diameter control in proximal intracranial stenosis. German academic medical centers favor these devices for anterior circulation lesions where vessel straightness permits rigid scaffolding. FDA premarket approval timelines stretch 24-36 months for novel geometries, compressing manufacturer cash conversion cycles.
- Hybrid Stents:Combines balloon-expandable proximal segments with self-expanding distal elements for transitional vessel zones.
- Covered Stents:PTFE or ePTFE membrane barriers exclude blood flow from aneurysm sacs in carotid blowout or pseudoaneurysm salvage.
Most installed capacity flows through Self-Expanding Stents. Expansion is steepest in Hybrid Stents.
Material:
Raw material sourcing strategies diverge sharply between captive metallurgical operations and third-party wire procurement.
- Nitinol:Nickel-titanium superelastic alloys with Af temperature tuned to body temperature enable crimped delivery and thermal shape recovery. United States and German metallurgical suppliers dominate superelastic wire production, creating input cost volatility for device manufacturers lacking long-term supply agreements. EU MDR technical documentation requirements favor established nitinol processors with validated quality systems.
- Stainless Steel:316LVM grade offers radial strength and radiopacity at lower material cost. Balloon-expandable platforms in India's emerging stroke centers default to stainless steel where procurement committees prioritize unit economics over conformability. CDSCO regulatory harmonization is expanding addressable market for cost-optimized constructions.
- Polymer:Bioresorbable scaffolds in magnesium or polylactic acid eliminate permanent foreign body retention.
- Coated Alloys:Carbon, silicon carbide, or phosphorylcholine surface modifications reduce thrombogenicity.
Procurement volume concentrates in Nitinol. Technology transition is most visible in Polymer.
Technology:
Clinical evidence thresholds and pricing power separate premium-eluting platforms from commodity metal scaffolding.
- Drug-Eluting Stents:Sirolimus, paclitaxel, or zotarolimus coatings suppress neointimal hyperplasia and in-stent stenosis. Japanese stroke centers command premium pricing for endothelialization control in younger patients with longer life expectancy. PMDA post-market surveillance mandates track late thrombotic events across diverse hospital settings.
- Bioresorbable Stents:Magnesium alloy scaffolds resorb within 12-24 months, restoring vessel vasomotion. Pediatric and young-adult indications previously closed to permanent implants are opening in German academic centers with specialized interventional neuroradiology fellowship programs. EU MDR active implant registries must document resorption kinetics and late lumen loss.
- Bare Metal Stents:Uncoated nitinol or stainless steel platforms without pharmaceutical payload.
- Coated Stents:Passive surface modifications without drug elution.
Revenue concentration sits with Drug-Eluting Stents. Steepest volume expansion is occurring in Bioresorbable Stents.
End User:
Capital equipment requirements and case volume thresholds determine addressable customer base.
- Hospitals:Comprehensive stroke centers with 24-hour neurointerventional coverage and biplane angiography suites generate procedural volumes exceeding 200 cases annually. United States integrated delivery networks in Florida and Texas are consolidating vendor contracts around comprehensive stroke program partnerships. Bundled procurement agreements now encompass physician training and technical support commitments.
- Ambulatory Surgical Centers:Selective aneurysm embolization and diagnostic angiography in stabilized patients shift lower-acuity cases from inpatient settings. German outpatient reimbursement pathways for elective flow diversion are expanding ASC neurointerventional capacity where regulatory frameworks permit.
- Specialty Clinics:Focused cerebrovascular practices without full hospital infrastructure.
- Research Institutes:Preclinical and first-in-human trial sites for novel scaffold technologies.
Device deployment concentrates in Hospitals. Fastest volume growth is appearing in Ambulatory Surgical Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's stroke center clusters anchor procedural volume concentration, with reimbursement pathways and aging demographics dictating regional expansion trajectories across major neurointerventional markets.
United States
Integrated delivery networks in Florida and Texas consolidate vendor contracts around comprehensive stroke program partnerships, bundling device procurement with physician training commitments. FDA premarket approval timelines for novel stent geometries extend commercialization cycles by 24-36 months. Hospital procurement committees in these states reduce active supplier rosters from six to two preferred vendors.
Germany
Academic medical centers in Bavaria and Baden-Württemberg favor balloon-expandable platforms for anterior circulation lesions where vessel straightness permits rigid scaffolding. EU MDR technical documentation requirements filter out marginal competitors and consolidate procurement toward established nitinol device manufacturers. Stuttgart and Munich host specialized interventional neuroradiology fellowship programs piloting robot-assisted catheter navigation.
Japan
PMDA reimbursement pathways for flow diversion procedures expand hospital neurointerventional capacity in Tokyo and Osaka stroke centers. Post-market surveillance mandates track late thrombotic events across diverse hospital settings. Japanese stroke centers command premium pricing for drug-eluting platforms in younger patients with extended life expectancy.
India
Private hospital chain expansion in Mumbai and Delhi creates first-mover positioning for self-expanding stent platforms. CDSCO regulatory harmonization expands addressable market for cost-optimized stainless steel constructions where procurement committees prioritize unit economics. Maharashtra and Karnataka clusters drive procedural volume growth in underpenetrated stroke infrastructure.
United Kingdom
London and Southeast England concentrate comprehensive stroke centers with 24-hour neurointerventional coverage and biplane angiography suites. NHS procurement frameworks emphasize outcome-validated technology access over procedural volume metrics. Academic centers in Cambridge and Oxford pilot bioresorbable magnesium alloy scaffolds for pediatric indications.
Neurovascular Stent Market Vendor Landscape
Global majors compete with regional champions across regulatory compliance capabilities and physician training infrastructure, creating tiered market access where FDA and PMDA approvals separate premium positioning from commodity participation. The vendor base stratifies between integrated medtech conglomerates with endovascular portfolio breadth and specialized interventional neuroscience firms. Three archetypes dominate: comprehensive stroke program partners, nitinol processing specialists, and emerging bioresorbable technology developers. M&A activity targets regulatory affairs capacity in Tokyo and Brussels, while strategic partnerships secure long-term superelastic wire supply agreements.
Among diversified medtech conglomerates, Stryker and Medtronic anchor competitive positioning through hospital contracting power and deep interventional neuroscience specialization. Terumo Corporation exemplifies regional champions leveraging domestic PMDA relationships to secure reimbursement expansion. Boston Scientific Corporation occupies a position bridging comprehensive portfolio scale with targeted neurovascular technology development. Johnson & Johnson Services Inc. and Abbott Laboratories represent diversified healthcare majors applying cross-divisional resources to stroke program partnerships.
| Leading Market Players |
|---|
| Stryker |
| Johnson & Johnson Services Inc. |
| Terumo Corporation |
| Medtronic |
| Boston Scientific Corporation |
| MicroPort Scientific Corporation |
| Abbott Laboratories |
| W. L. Gore & Associates |
| Acandis GmbH |
| Others |
Supply Flow & Price Mechanics
Superelastic nitinol wire feedstock moves from German and United States metallurgical suppliers through laser-cutting facilities to hospital procurement committees, with EU MDR certification tiers separating premium device pricing from commodity stainless steel alternatives in India's emerging stroke centers.
Pricing Analysis
Input-cost pass-through from concentrated nitinol wire suppliers compresses margins for device manufacturers lacking long-term supply agreements. Three-tier pricing structure across premium drug-eluting, standard bare-metal, and economy stainless steel levels reflects FDA approval status and endothelialization performance. Pricing pressure stems from mechanical thrombectomy substitution in acute ischemic stroke cases. Academic medical centers in Germany and Japan show lowest price sensitivity due to outcome-validated procurement frameworks, while private hospital chains in India prioritize unit economics.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO regulatory harmonization are reshaping sourcing toward local stainless steel processing for cost-optimized constructions. Manufacturing draws from Germany, United States, and Japan for superelastic wire, laser-cutting infrastructure, and coating technologies. Single-source vulnerability concentrates in nitinol raw material among three specialized metallurgical suppliers. Distribution runs through integrated delivery networks bundling device procurement with physician training commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between Japan's premium reimbursement pathways for flow diversion and India's cost-optimized stainless steel demand, with regulatory compliance cost differentials exceeding manufacturing labor spreads.
For Market Incumbents: Anchor competitive positioning through captive nitinol supply agreements and Brussels regulatory affairs infrastructure. Defend against bioresorbable magnesium substitution by accelerating pediatric indication trials. Prioritize vertical integration into superelastic wire processing to offset raw material concentration risk.
For New Entrants and Emerging Players: Specialized interventional neuroradiology fellowship programs offer partnership pathways for robot-assisted navigation platforms. India's underpenetrated stroke infrastructure in Maharashtra and Karnataka presents first-mover positioning for self-expanding stent platforms. Pursue CDSCO regulatory harmonization to access cost-sensitive procurement committees.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR technical documentation requirements exceed smaller firms' regulatory capacity. Five-to-ten-year viability favors manufacturers with Tokyo PMDA relationships and validated quality systems. Target acquisition archetype: regional champions with reimbursement expansion track records. Watch FDA premarket approval timeline extensions as inflection indicator for cash conversion compression.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Reimbursement Strategy | Secures flow diversion procedure coverage in Tokyo and Osaka stroke centers. |
| EU MDR Technical Documentation | Filters marginal competitors and consolidates procurement toward established nitinol processors. |
| Hospital System Partnership | Bundles device procurement with 24-hour technical support in Florida and Texas IDNs. |
| Bioresorbable Scaffold Development | Opens pediatric indications previously closed to permanent metallic implants in German academic centers. |
| Robot-Assisted Navigation Platform | Reduces fluoroscopy time and operator radiation exposure in Stuttgart and Munich pilot programs. |
Methodological Framework
Coverage spans United States, Germany, Japan, India, and United Kingdom, with primary inputs from each market cluster. Interviews with interventional neuroradiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with FDA 510(k) filings, PMDA reimbursement databases, EU MDR notified body registers, and hospital procurement records. Secondary validation drew from CMS Medicare data, Japanese Ministry of Health statistics, and CDSCO regulatory harmonization documents. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue allocations.
Rate-of-change decomposition separated volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, material platform, technology tier, and end-user setting, with regional regulatory cluster as an additional neurovascular-specific dimension. CAGRs derived from logistic diffusion curves for technology adoption and demographic-adjusted stroke incidence projections. Forecast inputs incorporated PMDA reimbursement pathway expansion timelines and EU MDR notified body capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to mechanical thrombectomy substitution rates and bioresorbable scaffold resorption kinetics. Forecasts reflect documented assumptions regarding regulatory approval timelines and reimbursement expansion trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Dose Monitoring Devices Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Condylar Plate Fixation System Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Smart Vision Aids Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
Smart Pills Drug Delivery Market
Medical Devices
Motorized Prosthesis Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
North America and Europe Medical Technology Market
Medical Devices
Mexico General Surgical Devices Market