
 Dual Chamber Prefilled Syringes Market | 2026-2036
Dual Chamber Prefilled Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Chamber Prefilled Syringes Market Analysis
Asset-light contract manufacturing and project-based leasing arrangements for sterile fill-finish capacity is reshaping competitive entry in dual chamber prefilled syringes. Gerresheimer AG leverages its integrated glass-to-syringe platform to control quality across the value chain. West Pharmaceutical Services anchors its position through proprietary elastomer and seal technologies that address container closure integrity. Vetter Pharma-Fertigung GmbH & Co. KG specializes in aseptic manufacturing partnerships that reduce capital barriers for biotech innovators.
A dual chamber prefilled syringe is a single-dose drug delivery device with two physically separated compartments—typically one holding lyophilized drug powder and the other holding diluent—joined by a bypass channel that enables in-situ reconstitution immediately prior to injection. The device employs cyclic olefin polymer or borosilicate glass barrels with precisely engineered plunger stoppers to maintain sterility and dosage accuracy for complex biologics. Glass syringes dominate current volume due to established compatibility with sensitive proteins and regulatory familiarity, while plastic syringes represent the fastest-expanding segment as polymer science advances reduce extractables and enable integrated safety systems. Diabetes and immunology therapy areas command the largest share of current demand, though neurology applications are emerging as a concentrated margin pool given the precision dosing requirements of emerging antibody therapies.
The FDA enforces strict container closure integrity standards under 21 CFR Part 211, while the EMA's MDR and Annex 1 revisions elevate sterility assurance requirements for combination products. These frameworks compel manufacturers to validate dual chamber systems against particulate limits, endotoxin thresholds, and plunger release force specifications before market authorization. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards for extractables and leachables testing, as divergent requirements threaten to fragment approval pathways and inflate compliance costs for global biologic launches.
Market Dynamics
Biologic drug pipelines are concentrating demand for lyophilized reconstitution formats, forcing fill-finish networks to absorb capacity constraints while regulators tighten sterility assurance thresholds across major markets.
Growth Catalysts
- Oncology biologics expansion:Antibody-drug conjugates and immune checkpoint inhibitors require precise reconstitution protocols that dual chamber systems standardize across dosing sites.
- EMA Annex 1 revisions:The updated sterile manufacturing guidance elevates barrier isolation requirements, accelerating shifts toward pre-sterilized, ready-to-use container formats.
- Cyclic olefin polymer advances:Reduced extractables profiles in engineered plastics are opening dual chamber applications beyond traditional glass-dependent biologics.
Market Restraints
- Borosilicate glass supply concentration:Germany and Japan control premium tubing supply for syringe barrels, creating single-source vulnerability for manufacturers without backward integration.
- Elastomer formulation complexity:Plunger stopper compatibility with diverse biologic excipients requires lengthy extractables validation, extending development timelines.
- Lyophilization equipment intensity:Capital requirements for aseptic freeze-dry capacity exceed $50 million per production line, excluding mid-scale entrants from integrated manufacturing.
Strategic Opportunities
- Neurology antibody penetration:Multiple sclerosis and Alzheimer's therapeutic pipelines are creating concentrated demand for precision-dosing dual chamber formats in injectable biologics.
- Home administration expansion:Self-injection training protocols and connected device integration are unlocking ambulatory care settings previously restricted to clinical environments.
- ISO 11040 harmonization:Converging international standards for prefilled syringe performance are reducing redundant testing burdens for multi-regional product registrations.
Industry Challenges
- Aseptic processing workforce scarcity:Qualified personnel for isolator-based fill-finish operations remain concentrated at established manufacturing clusters, constraining geographic expansion.
- Container closure integrity validation:Demonstrating seal performance across temperature excursions and transport stress requires probabilistic modeling capabilities few contract manufacturers possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Chamber Prefilled Syringes Market |
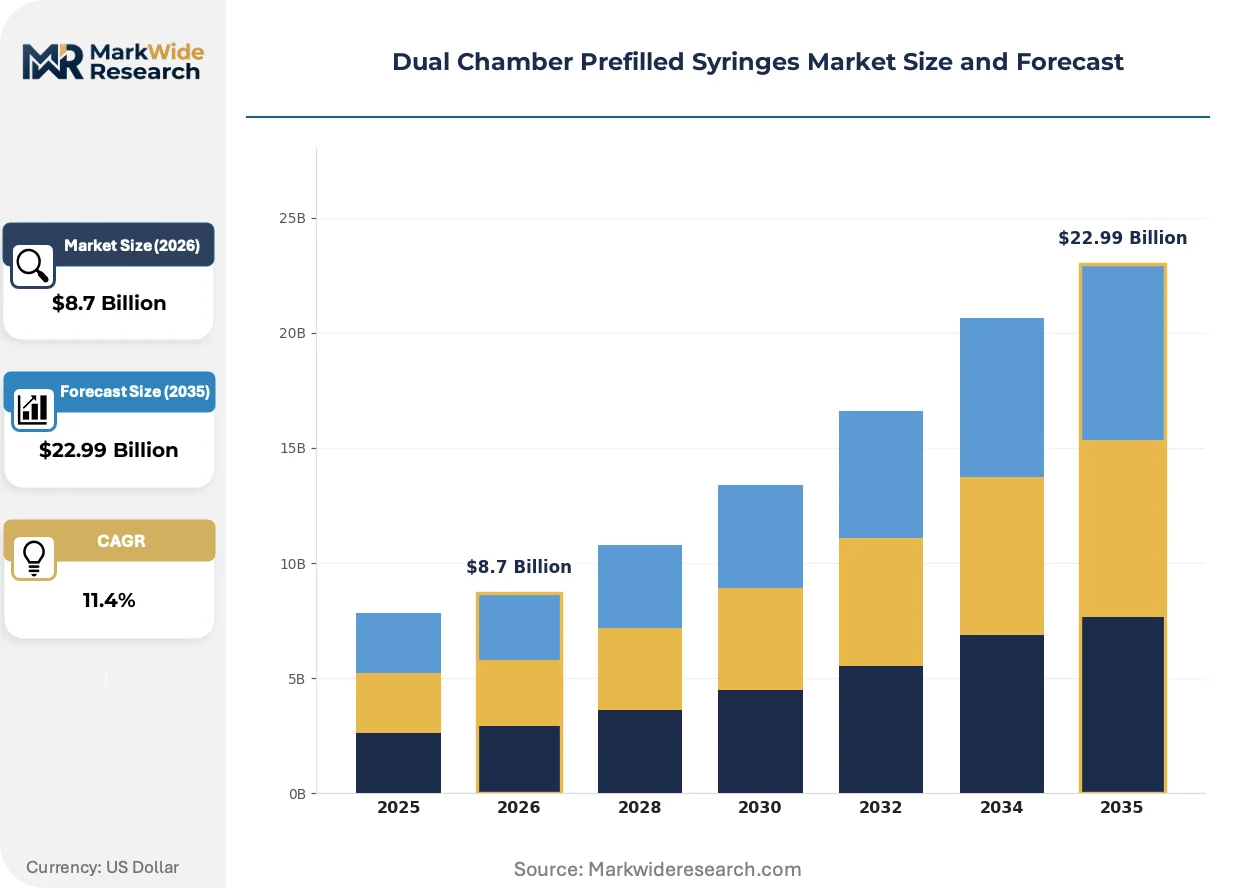
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Syringes, Plastic Syringes, Standard Syringes, Specialty Syringes Therapy Area: Diabetes, Cancer, Immunology, Neurology End User: Hospitals, Clinics, Homecare, Ambulatory Surgery Centers Package Type: Blister Packs, Cartons, Tray Packs, Others |
| Companies Covered | Gerresheimer AG, West Pharmaceutical Services, Inc., Credence MedSystems, Inc., Vetter Pharma-Fertigung GmbH & Co. KG, SCHOTT Pharma, Nipro Corporation, Stevanato Group, ARTE Corporation, MAEDA INDUSTRY Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Chamber Prefilled Syringes Market Emerging Trajectories
Device architecture is converging with digital traceability and automated reconstitution, compressing the boundary between primary packaging and connected drug delivery systems.
Hybrid barrier technologies combining cyclic olefin polymer barrels with glass-lined drug contact surfaces are hybridizing material selection tradeoffs. Biologic manufacturers seeking extractables reduction without protein stability risk are piloting these formats in immunology portfolios. The approach is hybridizing supplier relationships as polymer specialists partner with established glass converters to co-develop qualification protocols.
REACH restrictions on certain phthalate plasticizers in elastomer components are forcing compound reformulation across European supply chains. Manufacturers must validate alternative stopper materials against existing biologic license commitments, compressing formulation windows. Oncology applications face the steepest compliance burden given the volume of legacy products requiring material continuity assurances.
Hospital procurement consortia are consolidating purchasing for prefilled delivery systems, displacing fragmented distributor networks with direct manufacturer agreements. Academic medical centers in the United States are leading this consolidation, leveraging case volume to extract technical service commitments and supply security guarantees. The shift concentrates price negotiation leverage while elevating vendor qualification requirements for integrated safety systems.
Dual Chamber Prefilled Syringes Market Segmentation
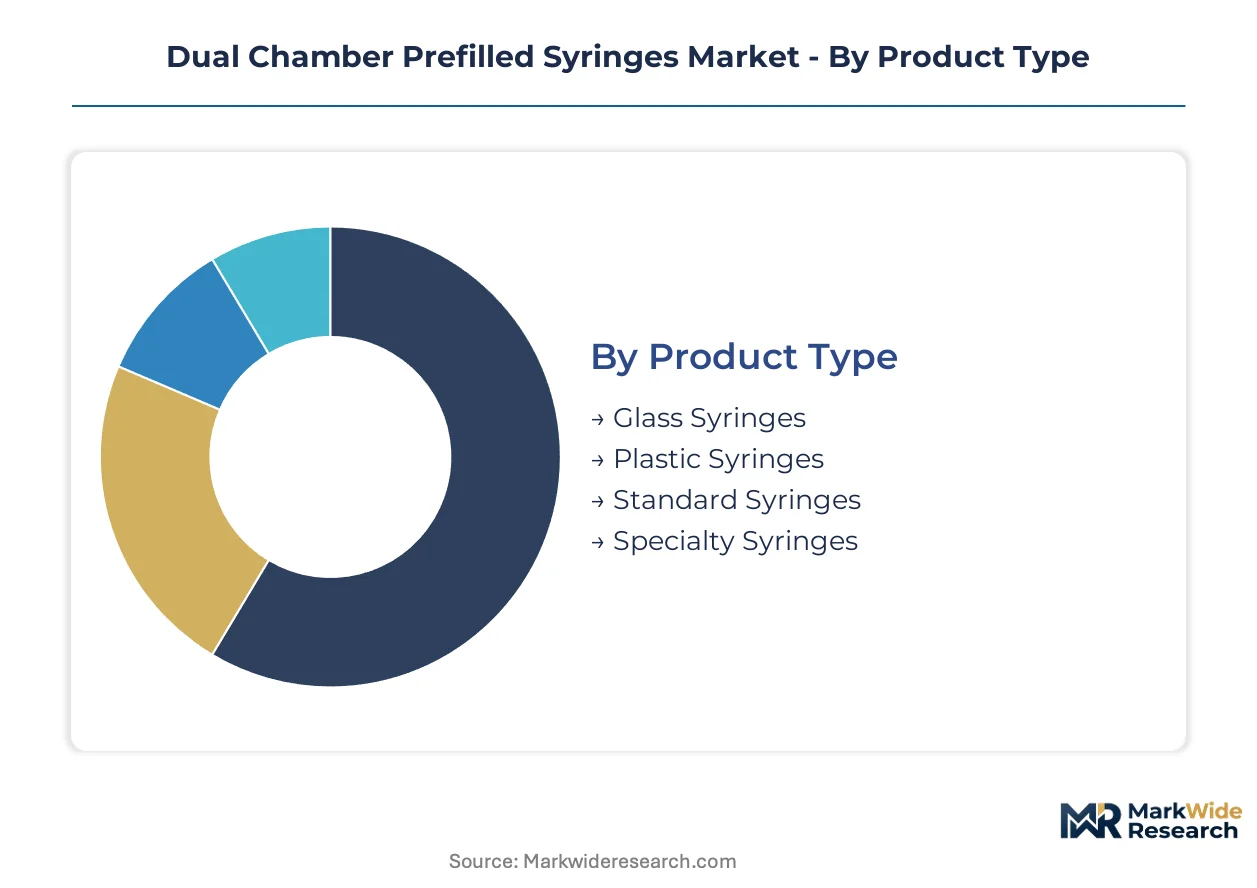
Segmentation in dual chamber prefilled syringes reveals how material science, clinical setting requirements, and packaging complexity create distinct margin pools. Each dimension carries different capital intensity, regulatory burden, and customer concentration profiles that shape vendor positioning.
Product Type:
Cycle times diverge sharply: plastic syringes move from mold to sterilization in weeks, while glass-dependent formats require months of tubing qualification and extractables validation.
- Glass Syringes:Borosilicate Type I tubing maintains established compatibility with sensitive biologics and protein formulations. Oncology and immunology pipelines in the United States, Germany, and Japan anchor demand where regulatory familiarity with glass extractables profiles accelerates approval timelines.
- Plastic Syringes:Cyclic olefin polymer barrels with engineered barrier layers reduce weight and enable integrated safety mechanisms. Self-injection protocols in ambulatory diabetes care are concentrating orders for these formats where breakage risk and disposal weight drive procurement decisions.
- Standard Syringes:Conventional dual chamber architectures without integrated needle safety or connectivity features serve cost-sensitive institutional contracts.
- Specialty Syringes:Custom bypass geometries and plunger designs address specific reconstitution kinetics for high-viscosity biologics.
Glass syringes anchor the volume base while plastic syringes gain share at the steepest rate.
Therapy Area:
Margin structures stratify by clinical outcome pricing power and dosing precision requirements, with chronic disease management offering volume scale and acute oncology applications commanding premium positioning.
- Diabetes:Long-acting insulin and GLP-1 analog reconstitution drives standardized high-volume procurement through hospital consortia. Home administration expansion in North American and European markets is pulling demand toward connected device compatibility and simplified reconstitution steps.
- Cancer:Antibody-drug conjugates and checkpoint inhibitors require exact diluent-to-lyophilized ratios that dual chamber systems standardize across infusion centers. Manufacturing partnerships between biotech innovators and aseptic fill-finish specialists concentrate supply security negotiations for these high-value doses.
- Immunology:Rheumatoid arthritis and psoriasis biologics with established lyophilized formats represent mature demand with stable specification requirements.
- Neurology:Multiple sclerosis antibody therapies with narrow therapeutic windows are emerging as a concentrated margin segment where precision dosing mechanisms justify premium packaging investments.
Diabetes commands the largest installed base while neurology applications expand most quickly as new molecular entities advance through late-stage pipelines.
End User:
Procurement sophistication and technical service requirements scale with patient acuity, creating four distinct customer archetypes with diverging vendor qualification criteria.
- Hospitals:Academic medical centers and integrated delivery networks leverage case volume for direct manufacturer agreements with technical service commitments. Container closure integrity documentation and supply security guarantees dominate sourcing criteria for oncology and immunology formularies.
- Clinics:Outpatient infusion centers prioritize standardization across limited product portfolios to reduce training burden and waste from expired multi-dose vials.
- Homecare:Self-injection training protocols and patient adherence programs are unlocking ambulatory settings previously restricted to clinical environments, with connectivity features and simplified reconstitution mechanics driving format selection.
- Ambulatory Surgery Centers:Same-day procedure volumes concentrate demand for pre-sterilized, ready-to-use formats that minimize pharmacy compounding steps and periprocedural delays.
Hospitals retain the dominant procurement volume position while homecare channels climb the fastest as biologic therapies migrate from infusion suites to patient-administered settings.
Package Type:
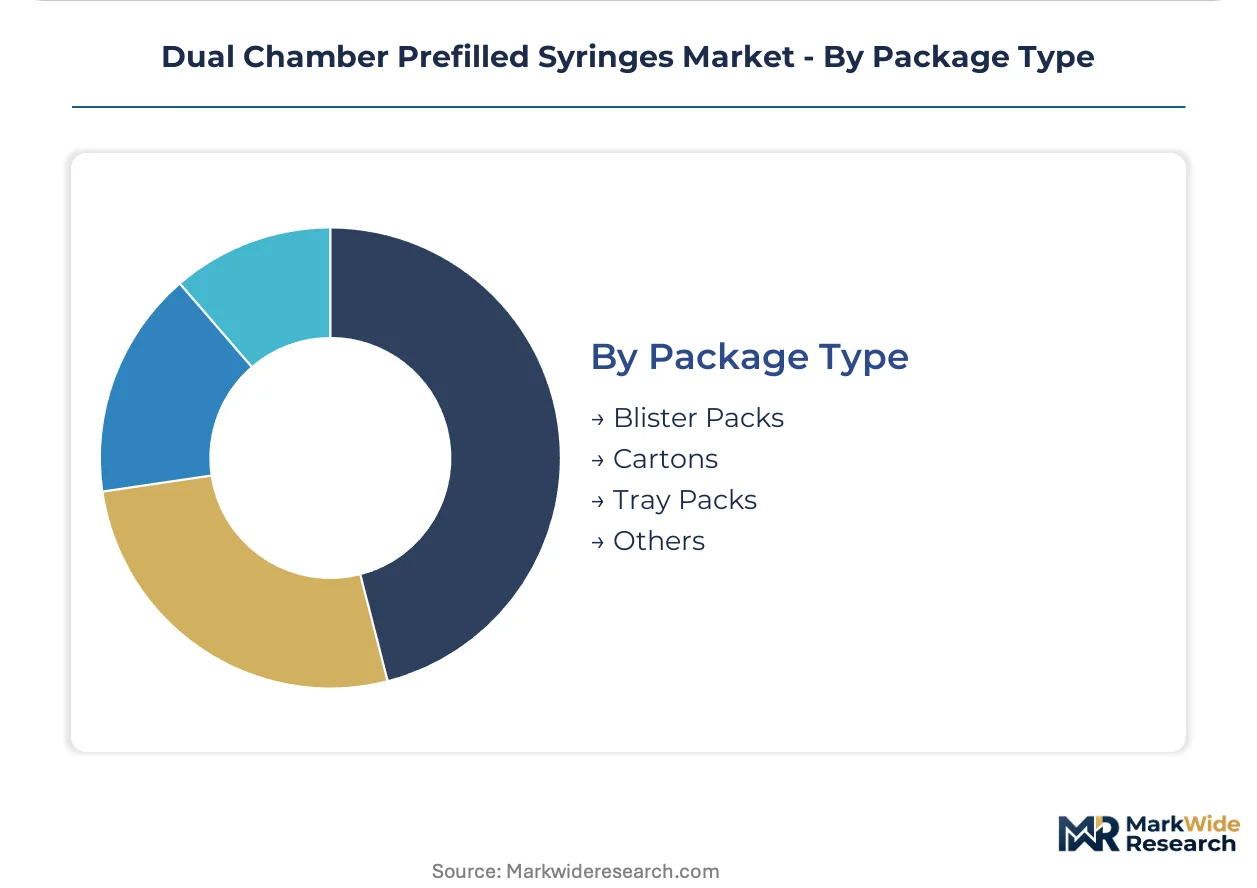
Secondary packaging investments correlate with distribution distance and temperature excursion risk, with cold chain biologics demanding higher protection tiers than room-temperature stable formulations.
- Blister Packs:Individual unit presentation with tamper-evident sealing supports automated dispensing systems and unit-of-use tracking requirements in hospital pharmacies.
- Cartons:Standard folding carton configurations with printed dosing instructions serve institutional procurement where manual handling predominates.
- Tray Packs:Rigid thermoformed trays with individual syringe nests protect glass barrels through distribution stress and enable presentation in surgical kits.
- Others:Pouch configurations and custom kit assemblies address specific contract manufacturing arrangements and regional regulatory labeling requirements.
Cartons maintain the broadest application base while tray packs capture expanding share in kit-integrated oncology and surgery center supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in dual chamber prefilled syringes tilt toward net-import dependence in markets with concentrated biologic drug manufacturing, while Germany and the United States retain export capacity through integrated glass-to-device production platforms.
United States
Oncology biologics from Boston and San Francisco clusters drive concentrated demand for lyophilized reconstitution formats. FDA container closure integrity rules under 21 CFR Part 211 compel validation investments that favor established suppliers with probabilistic modeling capabilities. New Jersey and North Carolina manufacturing corridors host fill-finish partnerships between biotech innovators and aseptic specialists.
Germany
Glass tubing supply from Bavarian and Thuringian foundries anchors European production networks for borosilicate syringe barrels. EMA Annex 1 sterile manufacturing revisions accelerate shifts toward pre-sterilized formats among Frankfurt and Munich-based drug manufacturers. Baden-Württemberg polymer specialists partner with glass converters to develop hybrid barrier technologies.
Japan
PMDA quality standards for combination products create regulatory familiarity that sustains glass-dependent biologics pipelines from Tokyo and Osaka clusters. Aging demographics expand home administration protocols for immunology therapies, pulling demand toward simplified reconstitution mechanics. Kanto region manufacturing maintains premium positioning through precision molding capabilities.
India
CDSCO accelerated approval pathways for biosimilars concentrate fill-finish demand in Hyderabad and Bengaluru contract manufacturing corridors. Domestic biologic pipelines from Maharashtra and Gujarat drive procurement of standard dual chamber formats for cost-sensitive institutional contracts. Import dependence persists for specialty elastomer components and precision plunger assemblies.
Switzerland
Swissmedic combination product oversight elevates vendor qualification requirements for Basel and Zurich-based biologic innovators. Precision dosing requirements for neurology antibody therapies create concentrated demand for specialty syringe architectures. Geneva and Lausanne clusters prioritize supply security guarantees through direct manufacturer agreements.
Dual Chamber Prefilled Syringes Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of controlling quality across glass sourcing, elastomer formulation, and aseptic fill-finish operations. Three strategic archetypes dominate: backward-integrated glass converters with captive tubing supply, specialized contract manufacturers offering asset-light partnership models, and component specialists leveraging proprietary seal technologies. Capacity expansion and strategic technology licensing represent the dominant competitive moves as mid-scale entrants seek alternatives to capital-intensive lyophilization infrastructure.
Among German fabricators, Gerresheimer AG and Vetter Pharma-Fertigung GmbH & Co. KG exemplify contrasting platform strategies. West Pharmaceutical Services anchors the component-specialist archetype through elastomer and seal expertise. These three entities represent the tier capable of delivering integrated container closure integrity validation required for FDA and EMA combination product approvals.
| Leading Market Players |
|---|
| Gerresheimer AG |
| West Pharmaceutical Services, Inc. |
| Credence MedSystems, Inc. |
| Vetter Pharma-Fertigung GmbH & Co. KG |
| SCHOTT Pharma |
| Nipro Corporation |
| Stevanato Group |
| ARTE Corporation |
| MAEDA INDUSTRY Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European aseptic fill-finish networks is driving supplier selectivity and pricing leverage toward integrated platform providers with captive glass tubing supply. Contract manufacturers with isolator-based capacity report utilization rates above 85%, enabling premium positioning for combination product validation services while forcing biotech innovators into longer-term offtake commitments.
Pricing Analysis
Hospital procurement consortia anchor contract-based long-term offtake pricing for dual chamber prefilled syringes, with three-tier pricing structure across premium, standard, and economy levels differentiated by ISO 11040 certification tier and container closure integrity documentation depth. Pricing pressure stems from consolidation among academic medical centers in the United States extracting technical service commitments alongside unit pricing. Homecare channels exhibit highest price sensitivity due to reimbursement constraints, while oncology biologics manufacturers show lowest sensitivity given supply security priorities.
Supply Chain Analysis
Vetter Pharma-Fertigung GmbH & Co. KG, Gerresheimer AG, and West Pharmaceutical Services hold concentrated contract manufacturing capacity for sterile fill-finish operations. Supply draws from Germany, Japan, and the United States for borosilicate glass tubing, elastomer formulations, and precision plunger assemblies. Single-source vulnerability in premium glass tubing from Bavarian and Thuringian foundries creates structural risk for manufacturers lacking backward integration. Distribution runs through direct manufacturer agreements with hospital consortia, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dual chamber prefilled syringes market is entering a cyclical recovery phase as biologic drug pipelines expand and FDA container closure integrity enforcement tightens, driving replacement demand for validated combination product formats.
For Market Incumbents: Pre-empt emerging polymer specialists by deepening captive supply of cyclic olefin polymer barrier technologies and accelerating hybrid glass-polymer qualification protocols. Secure isolator-based fill-finish capacity additions in North Carolina and Baden-Württemberg corridors before mid-scale entrants achieve EMA Annex 1 compliance. Lock in exclusive elastomer formulation partnerships to forestall plunger stopper commoditization. For New Entrants and Emerging Players: Establish a beachhead in neurology antibody packaging where precision dosing requirements and limited validated supplier pools create penetrable white space. Target homecare connectivity integration as regulatory familiarity with self-injection protocols expands addressable settings beyond infusion centers. Lead with simplified reconstitution mechanics and patient adherence program bundling to differentiate from institutional-focused incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward contract manufacturers with isolator-based aseptic capacity and existing FDA combination product approval track records, positioned for sustained viability through the biologics patent cliff window. Monitor CDSCO accelerated biosimilar approval volumes as inflection indicator for emerging market fill-finish demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Based Capacity Expansion | EMA Annex 1 revisions elevate barrier isolation requirements for sterile manufacturing. |
| Hybrid Barrier Technology Development | Cyclic olefin polymer-glass hybrids address extractables reduction without protein stability risk. |
| Direct Hospital Consortium Agreements | Academic medical centers leverage case volume for supply security guarantees. |
| Elastomer Formulation Partnership | REACH restrictions force compound reformulation across European supply chains. |
| Connected Device Integration | Self-injection training protocols unlock ambulatory care settings previously restricted to clinics. |
Methodological Framework
Desk research of FDA 510(k) filings, EMA combination product submissions, and USP extractables guidance documents preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and aseptic manufacturing specialists. Secondary validation drew from ClinicalTrials.gov protocol specifications, formulary databases, and glass tubing trade flow records. Bottom-up unit demand estimates triangulated against top-down biologic drug pipeline forecasts.
Fixed assumptions across the modeling period include sustained FDA enforcement of 21 CFR Part 211 container closure integrity standards, continued EMA Annex 1 barrier isolation requirements, and stable pharmacopeial harmonization trajectories among USP, EP, and JP. Segmentation dimensions modeled encompass material type, therapy area, end-user channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year estimates, with cross-checks against biologic drug launch timelines and lyophilization capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in biotech venture funding levels, reimbursement policy for self-administered biologics, or trade restrictions on borosilicate glass tubing would shift the trajectory. Forecasts reflect assumptions about regulatory continuity and sterile manufacturing workforce availability. Quarterly review of CDSCO biosimilar approval cadence, EMA combination product opinion volumes, and hospital GPO contract award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Syndesmosis Repair System Market
Medical Devices
Heart Closure Devices Market
Medical Devices
Microwave Ablation Devices Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Venous Device Market
Medical Devices
Cervical Retractors Market
Medical Devices
Wearable Artificial Kidney Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Medical Coatings Market
Medical Devices
Peritoneal Dialysis Solutions Market
Medical Devices
Mexico General Surgical Devices Market