
 Medical Electrodes Market | 2026-2036
Medical Electrodes Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Electrodes Market Intelligence
The shift towards single-use products, creating an asset-light procurement model for hospitals, is reshaping competitive positioning. 3M leverages its material science and large-scale manufacturing to lead in disposable surface electrodes. Medtronic specializes in high-value implantable and neural monitoring electrodes for its device ecosystems. Ambu A/S competes with a focused portfolio of single-use diagnostic products for hospital settings.
Medical electrodes are conductive devices that transfer the body's ionic currents into electrical signals for diagnostic equipment. They typically feature a silver/silver chloride layer and a conductive gel to minimize skin-to-electrode impedance and ensure signal clarity. Disposable electrodes for electrocardiography applications constitute the largest market segment by volume, driven by hospital infection control policies. In contrast, reusable and needle electrodes hold higher value in specialized neurology and electromyography procedures.
Market access requires adherence to stringent regulatory frameworks, including the FDA's 510(k) clearance process in the United States and the EU's Medical Device Regulation. China's NMPA imposes its own specific testing and biocompatibility requirements, governing product approvals for its domestic market. Navigating these varied standards for material safety and electrical performance is a critical competency for all manufacturers. The key decision for stakeholders is how to balance cost pressures from healthcare providers with investments in advanced, higher-fidelity materials.
Market Dynamics
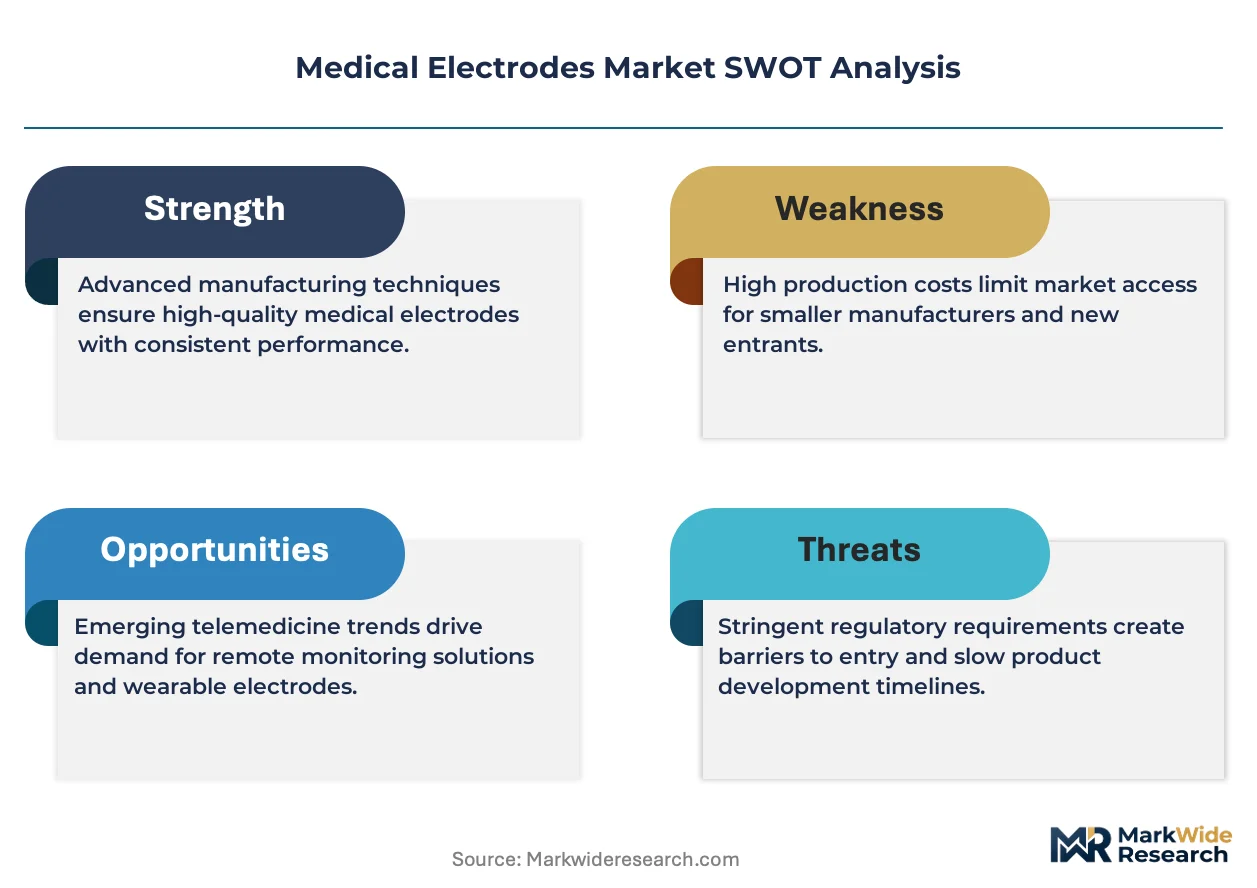
The medical electrodes market is defined by the fundamental tension between healthcare providers' cost-containment pressures and the clinical necessity for high-fidelity signals. This dynamic forces manufacturers to innovate materials and designs that improve performance without substantially increasing per-procedure costs.
Growth Catalysts
- Demographic Shifts:Aging populations in developed nations, particularly Germany and Japan, require more frequent cardiac and neurological monitoring, directly increasing the utilization of ECG and EEG electrodes in diagnostic and long-term care settings.
- Material Science Advancement:The adoption of novel conductive polymer materials in place of traditional gels improves signal fidelity, enhances patient comfort for long-term wear, and supports the development of electrodes for sensitive skin applications.
- Infection Control Mandates:Hospital policies aimed at reducing healthcare-associated infections (HAIs) strongly favor the use of single-use, disposable surface electrodes over reusable alternatives, particularly for high-volume procedures like electrocardiography.
Market Restraints
- Pricing Pressure:Intense price competition, driven by consolidated purchasing through Group Purchasing Organizations (GPOs) in North America and Europe, compresses margins for manufacturers of high-volume disposable electrodes like those for ECG.
- Regulatory Fragmentation:Navigating the disparate and stringent requirements of regulatory bodies such as the US FDA, the EU's Medical Device Regulation (MDR), and China's NMPA adds significant cost, complexity, and time to market entry.
- Input Material Cost:The performance of many electrodes depends on a silver/silver chloride coating, a material subject to commodity price volatility that can impact manufacturing cost structures and profitability for suppliers.
Strategic Opportunities
- Wearable Health Monitors:The expansion of remote patient monitoring and consumer wellness devices creates a significant opportunity for developing flexible, long-duration electrodes designed for integration into smart textiles and wearable patches.
- Emerging Economies:Increasing healthcare expenditure and infrastructure development in countries across Latin America and Southeast Asia represent an underpenetrated market for diagnostic electrodes as access to cardiology and neurology services expands.
- Smart Electrode Development:There is a clear opportunity to integrate micro-sensors and basic processing capabilities directly into the electrode, enabling pre-processing of signals to reduce noise and improve diagnostic accuracy for specialized applications.
Industry Challenges
- Supply Chain Stability:Manufacturers face the operational challenge of securing a consistent and cost-effective supply of critical raw materials, including medical-grade adhesives and conductive gels, while managing relationships with a limited number of specialized suppliers.
- Post-Market Surveillance Burden:Compliance with the EU's MDR framework requires manufacturers to undertake extensive and continuous post-market surveillance activities, demanding significant investment in data collection and analysis systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Electrodes Market |
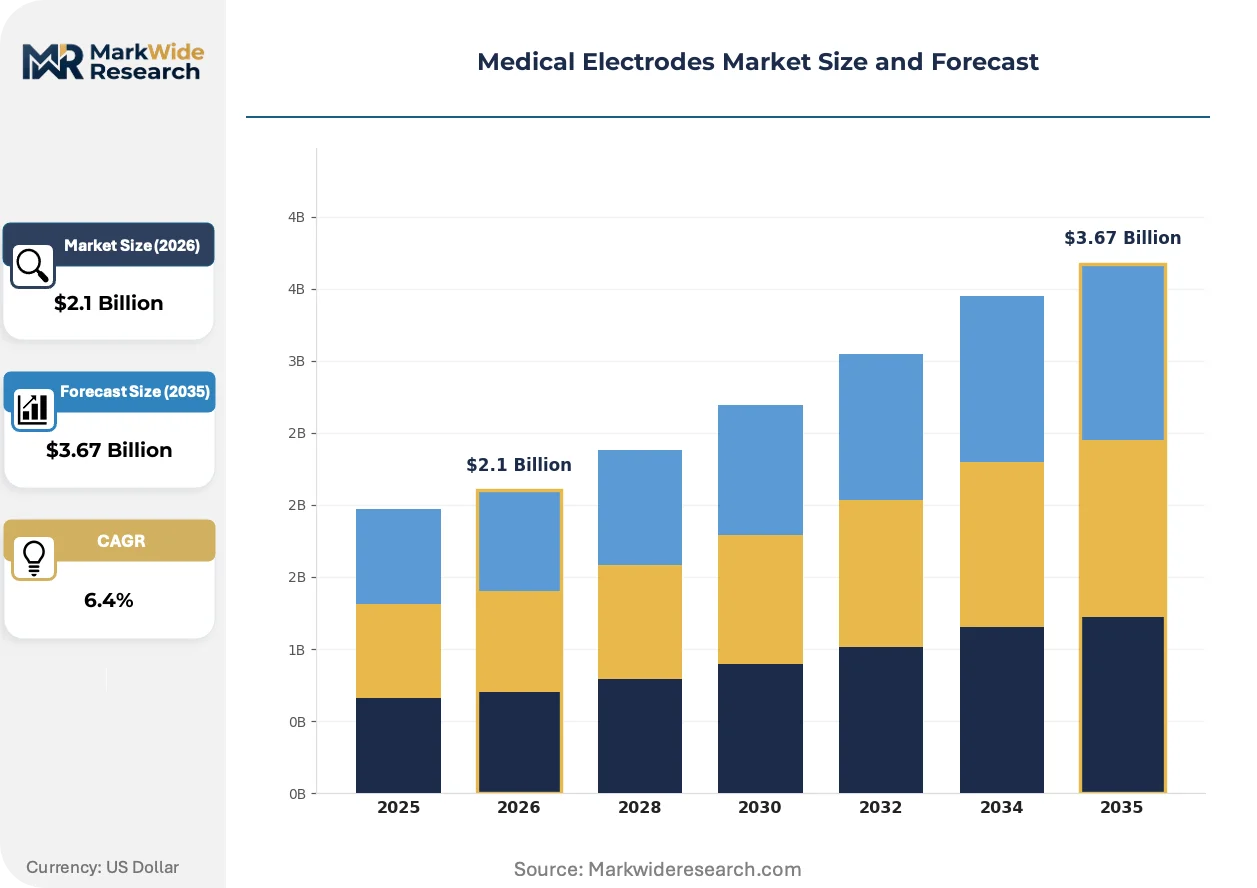
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Electrodes, Reusable Electrodes, Needle Electrodes, Surface Electrodes, Implantable Electrodes Technology: Silver/Silver Chloride, Carbon, Foam, Gel-Based, Conductive Polymer Application: Electrocardiography, Electromyography, Electroencephalography, Defibrillation, Neural Monitoring End User: Hospitals, Diagnostic Laboratories, Ambulatory Surgical Centers, Cardiology Clinics, Neurology Centers |
| Companies Covered | 3M, Medtronic, Ambu A/S, Cardinal Health, CONMED Corporation, Natus Medical Incorporated, Nihon Kohden Corporation, Koninklijke Philips N.V., ZOLL Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Electrodes Market Strategic Shifts & Innovations
Material science and connectivity are converging to redefine the electrode's role from a passive conductor to an active component in a digital health ecosystem. This evolution is driven by demands for better patient outcomes and more efficient clinical workflows.
Printable electronics and conductive inks are enabling the creation of thin, flexible, and conformable electrodes that can be applied like a temporary tattoo. These devices are gaining traction in sports science and chronic disease management for unobtrusive, long-term physiological monitoring. This integration of circuitry onto skin-contact substrates is digitizing the point of signal acquisition, allowing for direct data transmission to patient-side monitors or mobile applications.
The European Union's Medical Device Regulation (MDR) has introduced a more rigorous regulatory landscape for all device classes. This policy increases the burden of proof for clinical safety and performance, requiring more extensive technical documentation and lifecycle management. Disposable electrode manufacturers are most affected, as they must now generate more robust clinical evidence to obtain and maintain the CE marking required for access to the European market.
Hospital procurement behavior is moving away from capital-intensive reusable systems toward operational, per-procedure expenditures that favor disposables. This change disrupts traditional sales channels for reusable neurology needles and favors suppliers offering single-use diagnostic kits that integrate with hospital inventory management. This trend is most advanced in the United States, where health systems prioritize predictable costs and mitigating infection risks.
Medical Electrodes Market Segmentation
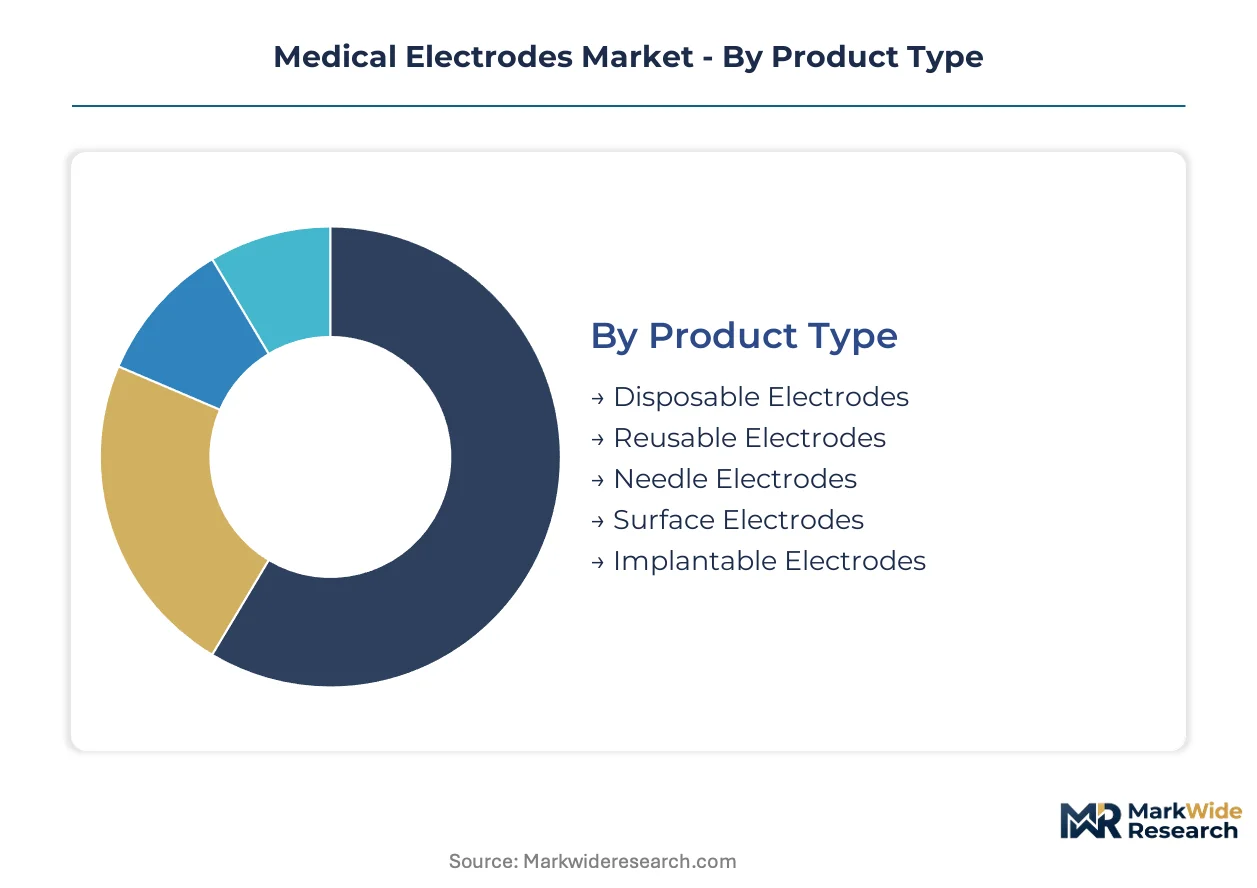
The medical electrodes market segmentation reveals diverse product types and technologies addressing varied clinical requirements. Understanding these distinct segments helps manufacturers align innovation with specific end-user demands. This granular view clarifies competitive landscapes and strategic opportunities across the value chain.
Product Type:
Product type segmentation distinguishes electrodes by their typical usage cycle, ranging from single-procedure disposables to long-term implantable devices.
- Disposable Electrodes:These single-use devices feature a silver/silver chloride layer and conductive gel, designed for immediate disposal after one patient application. Demand concentrates in hospitals for high-volume electrocardiography, driven by stringent infection control mandates.
- Implantable Electrodes:These specialized electrodes are surgically placed within the body, often featuring biocompatible materials for long-term neural or cardiac pacing. Growth in Germany and Japan reflects aging populations requiring continuous monitoring for chronic conditions.
- Reusable Electrodes:These durable electrodes are designed for multiple uses after sterilization, primarily in specialized diagnostic settings.
- Needle Electrodes:Fine-gauge electrodes penetrate the skin for electromyography and nerve conduction studies, providing precise signal acquisition.
- Surface Electrodes:Applied externally to the skin, these electrodes capture bio-signals for non-invasive diagnostic procedures.
Disposable Electrodes dominate the installed base for routine diagnostics. Implantable Electrodes represent the fastest-growing trajectory due to expanding neurological and cardiac interventions.
Technology:
Technology segmentation differentiates electrodes by their core conductive material and design, directly influencing signal fidelity and application suitability.
- Silver/Silver Chloride:These electrodes employ a stable electrochemical interface, offering low impedance and high signal clarity for critical diagnostic applications. Demand remains strong across hospitals for reliable ECG and EEG monitoring.
- Conductive Polymer:Utilizing advanced polymer materials, these electrodes provide enhanced flexibility, reduced skin irritation, and improved signal stability for long-term wear. Wearable health monitors are driving adoption in remote patient care.
- Carbon:Carbon-based electrodes offer a cost-effective alternative for certain diagnostic and therapeutic applications.
- Foam:Foam electrodes provide conformability and adhesion, often used as a backing material for disposable surface electrodes.
- Gel-Based:These electrodes rely on a conductive gel interface to optimize skin contact and minimize signal artifact.
Silver/Silver Chloride technology underpins high-volume traditional electrodes. Conductive Polymer technologies command higher value due to specialized performance attributes.
Application:
Application segmentation categorizes electrodes based on the specific clinical procedure or physiological signal they are designed to capture.
- Electrocardiography:ECG electrodes measure the heart's electrical activity, crucial for diagnosing cardiac conditions in both hospital and ambulatory settings. Hospital infection control policies drive demand for single-use ECG electrodes.
- Neural Monitoring:These electrodes track brain and nerve activity, essential for epilepsy diagnosis, sleep studies, and intraoperative monitoring. Demand is increasing with the rising prevalence of neurological disorders in developed nations.
- Electromyography:EMG electrodes assess muscle electrical activity for diagnosing neuromuscular disorders.
- Electroencephalography:EEG electrodes record brainwave patterns, vital for neurological diagnostics and research.
- Defibrillation:Defibrillation electrodes deliver therapeutic electrical shocks to restore normal heart rhythm in emergencies.
Electrocardiography applications account for the largest volume of electrode usage. Neural Monitoring represents a specialized segment with high growth potential.
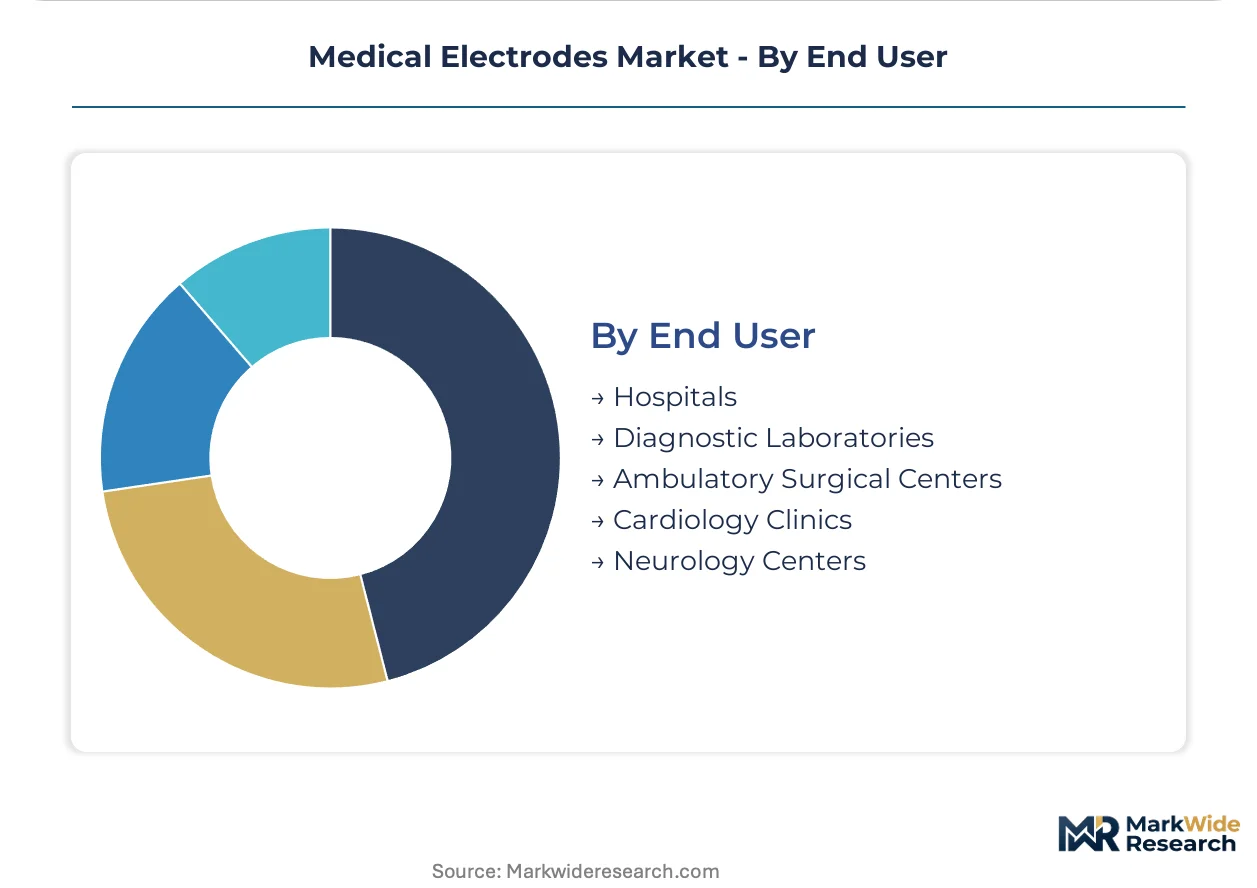
End User:
End-user segmentation distinguishes where medical electrodes are primarily utilized, reflecting varying procurement models and clinical environments.
- Hospitals:These large healthcare institutions are the primary consumers of medical electrodes for a broad range of diagnostic and monitoring procedures. Cost-containment pressures influence procurement decisions for high-volume disposable electrodes.
- Ambulatory Surgical Centers:ASCs utilize electrodes for outpatient surgical procedures and diagnostics, favoring single-use products for efficiency and infection control. Higher utilization in these centers drives overall market expansion.
- Diagnostic Laboratories:These facilities use electrodes for specialized testing, often requiring high-fidelity signal acquisition.
- Cardiology Clinics:Focused on heart health, these clinics are significant users of ECG and long-term cardiac monitoring electrodes.
- Neurology Centers:Specialized centers employ electrodes for EEG, EMG, and nerve conduction studies for neurological disorder diagnosis.
Hospitals serve as the central hub for electrode consumption. Ambulatory Surgical Centers and specialized clinics signify a trend towards more distributed care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government initiatives promoting healthcare access and digital health solutions influence medical electrode demand across key global markets. Policies supporting remote patient monitoring and early disease detection drive adoption of advanced diagnostic devices. This fosters innovation in wearable and high-fidelity electrode technologies.
United States
Demand for disposable electrodes in the United States stems from high volumes of cardiac and neurological monitoring procedures. The FDA's 510(k) clearance process ensures product safety and efficacy for market entry. Medical device manufacturing hubs in California and Massachusetts drive innovation in flexible electrode designs for consumer health.
Germany
Germany's aging population and robust healthcare system fuel consistent demand for ECG and EEG electrodes in diagnostic and long-term care settings. Compliance with the EU's Medical Device Regulation (MDR) ensures high standards for clinical performance and post-market surveillance. The Bavarian region, with its strong medical technology sector, specializes in advanced neuro-monitoring electrode development.
Japan
Japan experiences significant demand for implantable and high-fidelity electrodes due to its rapidly aging demographic requiring extensive cardiac and neurological care. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees stringent approval processes for medical devices. Tokyo's medical device cluster focuses on integrating micro-sensors into smart electrodes for remote patient management.
China
Healthcare infrastructure expansion and rising chronic disease prevalence in China increase the utilization of diagnostic electrodes. The National Medical Products Administration (NMPA) sets specific testing and biocompatibility requirements for market access. Manufacturing centers in the Yangtze River Delta are scaling production of cost-effective disposable electrodes for domestic hospitals.
India
India's expanding healthcare expenditure and increasing access to cardiology services propel demand for basic and advanced diagnostic electrodes. The Central Drugs Standard Control Organization (CDSCO) regulates medical device imports and manufacturing within the country. Bengaluru's burgeoning med-tech ecosystem supports local development of affordable ECG electrode solutions.
Medical Electrodes Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with large diversified players alongside specialized niche providers. Strategic archetypes include diversified healthcare giants leveraging extensive distribution networks, focused single-use product specialists optimizing cost-efficiency, and high-value implantable device innovators driving technological advancements. Companies engage in strategic partnerships to expand geographic reach and invest in technology licensing for advanced material development. Capacity expansion in emerging markets is also a common competitive move.
Within the diversified healthcare giant archetype, 3M, a U.S.-based corporation, leverages its material science expertise to produce a broad range of disposable surface electrodes. Medtronic, another U.S.-based entity, occupies a position in high-value implantable and neural monitoring electrodes, integrating them within its extensive device ecosystems. Denmark's Ambu A/S exemplifies the focused single-use product specialist, offering a portfolio designed for efficiency and infection control in hospital settings. These companies collectively demonstrate the varied approaches to market penetration and value capture across the medical electrodes landscape.
| Leading Market Players |
|---|
| 3M |
| Medtronic |
| Ambu A/S |
| Cardinal Health |
| CONMED Corporation |
| Natus Medical Incorporated |
| Nihon Kohden Corporation |
| Koninklijke Philips N.V. |
| ZOLL Medical Corporation |
Cost & Logistics Intelligence
Commodity price volatility for silver/silver chloride, a critical input, determines both pricing tier spreads and supply chain shape for medical electrodes. This material cost fluctuation directly impacts manufacturing profitability for suppliers of traditional electrodes.
Pricing Analysis
Regulatory certification level creates the primary spread in medical electrode pricing. Per-unit transactional pricing dominates disposable electrodes, while implantable devices often command value-based pricing. Price differentiation stems from signal fidelity, patient comfort features, and adherence to FDA 510(k) or EU MDR standards. Pricing pressure intensifies on high-volume disposable electrodes due to consolidated purchasing by Group Purchasing Organizations. Hospitals exhibit high price sensitivity for routine diagnostics, while specialized neurology centers prioritize performance over cost for complex procedures.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common in the medical electrode market, particularly for large hospital systems. Geographic supply concentration centers on China for cost-effective disposables, while the United States and Germany specialize in advanced material development for high-fidelity and implantable electrodes. Raw material dependencies include silver/silver chloride, medical-grade adhesives, and conductive gels. Single-source vulnerability for specialized conductive polymers presents a structural risk. Distribution runs through direct sales channels to large hospitals and Ambulatory Surgical Centers, complemented by specialized distributors for niche high-value products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical electrodes market offers a service-attach opportunity, with remote patient monitoring platforms and data analytics subscriptions expanding faster than hardware sales.
For Market Incumbents:Build regulatory compliance moats by investing heavily in R&D for advanced conductive polymers and micro-sensor integration. Acquire specialized technology firms focusing on flexible electronics to counter emerging entrant threats from printable devices. Leverage existing distribution networks to bundle advanced electrodes with data analytics platforms. Strategic partnerships with healthcare IT providers can also enhance integrated solutions.
For New Entrants and Emerging Players:Establish a beachhead in wearable health monitors and remote patient care devices. The consumer wellness segment represents the most penetrable market due to less stringent regulatory hurdles initially. Focus on developing flexible, long-duration electrodes for smart textiles and patches. A direct-to-consumer go-to-market angle, potentially through partnerships with technology companies, can accelerate adoption.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors specialized technology developers poised for integration into digital health ecosystems. Long-term viability remains strong, driven by aging populations and the expansion of remote care. Target acquisition archetypes include innovators in advanced conductive materials or micro-sensor integration capabilities. Expansion of insurance reimbursement for remote diagnostic data is a key signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Secure access to the regulated European market for new diagnostic devices. |
| Hospital System Partnership | Integrate disposable electrode procurement with large healthcare network supply chains. |
| Software Companion Development | Enhance electrode utility through data analytics and remote monitoring platforms. |
| Conductive Polymer R&D | Develop next-generation flexible electrodes for long-term patient comfort. |
| Emerging Market Capacity Expansion | Scale production of cost-effective electrodes for growing healthcare infrastructure. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase, combining in-depth interviews with secondary validation. Clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers provided direct insights. Secondary data sources included FDA filings, EU MDR documentation, NMPA guidelines, and medical device industry reports. Bottom-up and top-down triangulation ensured data consistency.
The calibration approach involved a multi-factor analytical framework applied across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived through regression analysis and expert consensus. Key industry-specific forecast inputs included demographic shifts, such as aging populations, and evolving healthcare expenditure trends.
Stress conditions across raw material costs and regulatory shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding a stable regulatory environment and consistent raw material supply. Geopolitical events impacting supply chains or unforeseen technological disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cryoablation Devices Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Neuroprosthetics Market
Medical Devices
Latin America General Surgical Devices Market
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
External Pacemakers Market
Medical Devices
Microcirculation Microscope Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Retinal Implant Market
Medical Devices
Digital Impression System Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
Pen Injectors Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Annuloplasty Rings Market