
 Allografts Market | 2026-2036
Allografts Market Size, Share, and Industry Trends Forecast 2026-2036
Allografts Market Outlook
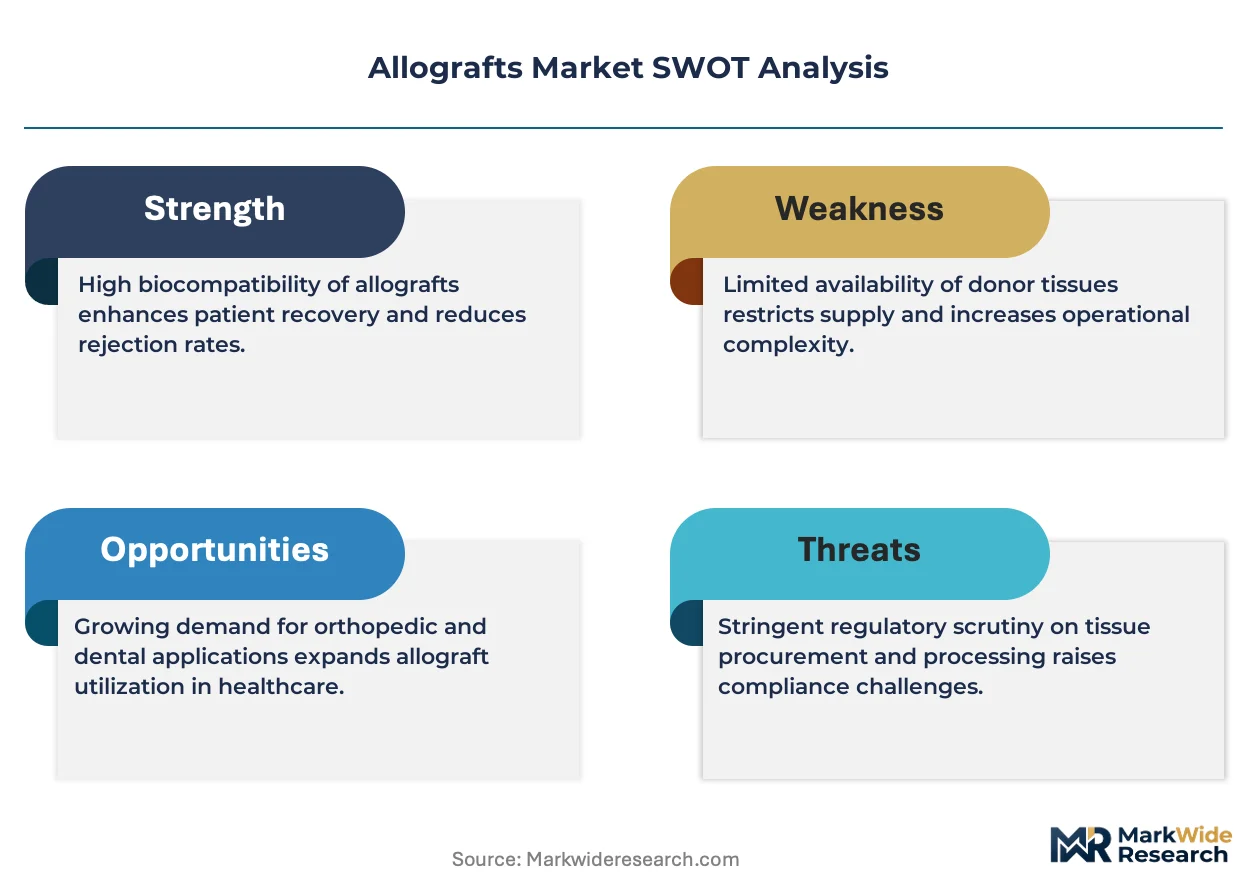
Decellularization technology is narrowing the immunogenicity gap between allografts and synthetic alternatives, altering how orthopedic and wound care products compete for surgeon preference. AlloSource leverages its vertically integrated tissue recovery network across US transplant centers to sustain supply continuity. RTI Surgical anchors its position through precision-machined bone grafts for spinal fusion. MTF Biologics differentiates via nonprofit tissue banking credentials that resonate with hospital ethics committees.
Allografts are transplantable human tissues recovered from deceased donors, processed through aseptic technique, cryopreservation, or terminal sterilization, and distributed for surgical reconstruction of bone, tendon, skin, or cartilage defects. Bone grafts dominate current revenue flows due to spine and trauma procedure volumes, though tendon grafts for anterior cruciate ligament repair represent the fastest-expanding margin pool. Hospitals remain the primary end user channel, but ambulatory surgical centers are capturing a growing share of outpatient orthopedic applications as anesthesia protocols advance.
The US FDA enforces Current Good Tissue Practice regulations that mandate donor eligibility screening and process validation, while the EMA's Human Tissue and Cell Directive shapes European procurement standards. These frameworks elevate compliance costs for smaller processors and accelerate consolidation toward scaled operators with dedicated quality systems. Stakeholders must monitor how minimally invasive delivery modes reshape graft form factor requirements and sterilization trade-offs.
Market Dynamics
Hospital consolidation into integrated delivery networks concentrates purchasing power and forces allograft processors to demonstrate validated sterilization documentation. This structural shift compresses vendor margins while elevating compliance barriers for smaller tissue banks.
Growth Catalysts
- Aging demographics in developed economies:Joint reconstruction volumes climb as populations over 65 require spine and orthopedic interventions. Surgeons in tertiary hospitals increasingly specify allografts over autografts to reduce donor-site morbidity.
- FDA Current Good Tissue Practice enforcement:Tighter donor screening protocols eliminate marginal suppliers and accelerate accreditation investments by scaled processors. This regulatory elevation professionalizes procurement standards.
- Decellularization protocols:Advanced processing removes cellular antigens while preserving extracellular matrix scaffolding. The technology expands allograft applicability into immunologically sensitive wound care applications.
Market Restraints
- Donor tissue supply volatility:Recovery rates fluctuate with regional mortality patterns and consent authorization variability. Geographic concentration of Organ Procurement Organizations creates regional availability gaps.
- Cryopreservation infrastructure capex:Validated cold-chain maintenance requires specialized equipment and redundant power systems. Smaller processors face capital constraints for terminal sterilization platform upgrades.
- Synthetic bone substitute convergence:Ceramic and polymer scaffolds with osteoconductive coatings compete in spinal fusion. Price-sensitive hospital procurement committees evaluate total cost of ownership against biologic premiums.
Strategic Opportunities
- Ambulatory surgical center expansion:Outpatient ACL reconstruction and arthroscopic procedures migrate from hospital settings. Anesthesia protocol advances enable same-day discharge with allograft tendon implants.
- EMA Human Tissue and Cell Directive harmonization:Cross-border tissue exchange standardization reduces regulatory fragmentation across EU member states. Accredited banks gain passporting advantages for multi-country distribution.
- 3D bioprinting convergence with decellularized matrices:Customized graft geometries match patient-specific defect morphologies. Orthopedic surgeons in academic medical centers pilot personalized reconstruction workflows.
Industry Challenges
- Quality systems specialist scarcity:Tissue banking operations require personnel fluent in both aseptic processing and FDA QSR documentation. Recruitment competition with pharmaceutical manufacturing elevates compensation costs.
- Legacy ERP integration with track-and-trace mandates:Donor-to-recipient chain of custody documentation demands real-time inventory visibility. Established processors face system architecture constraints for lot-level serialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allografts Market |
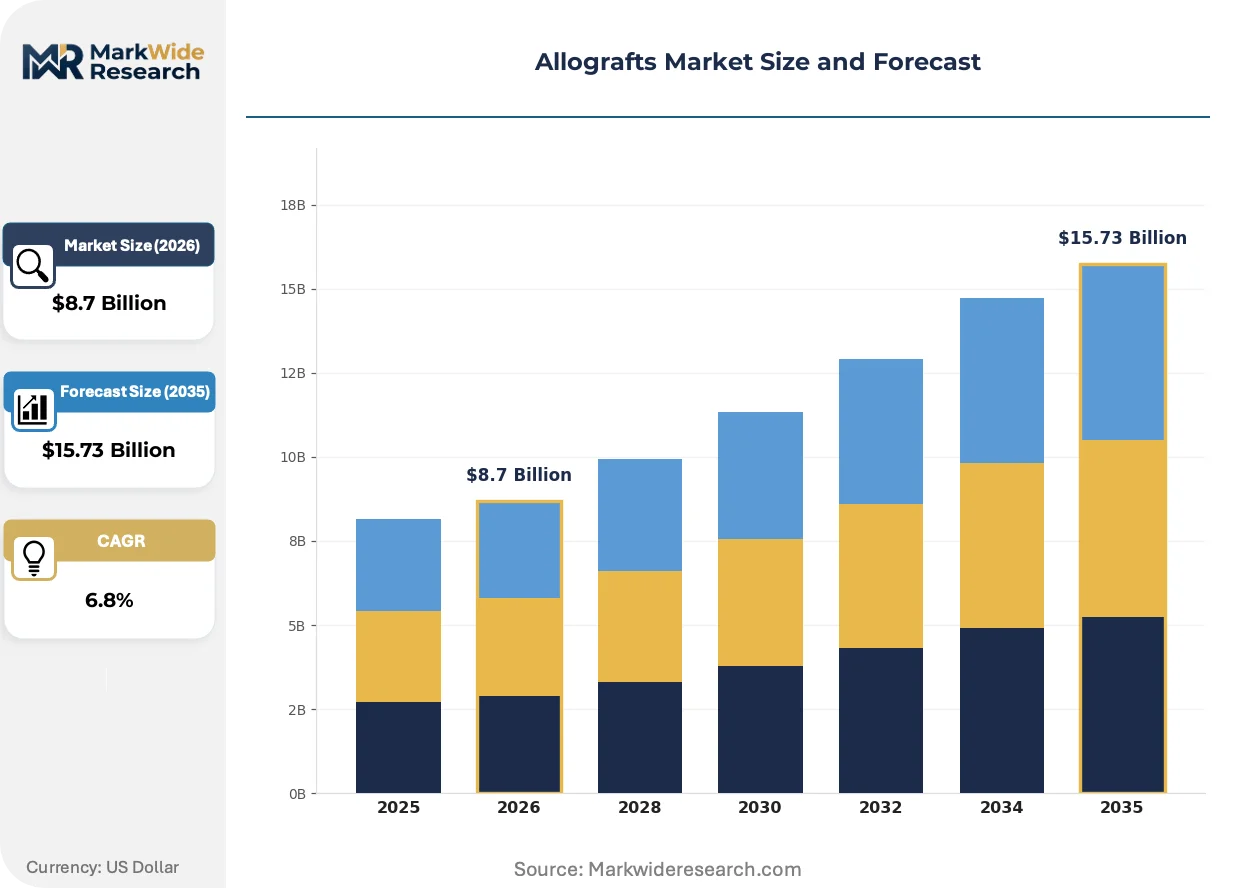
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Grafts, Tendon Grafts, Skin Grafts, Cartilage Grafts Application: Orthopedics, Dental, Wound Healing, Cardiovascular End User: Hospitals, Ambulatory Surgical Centers, Research Institutions, Specialty Clinics Delivery Mode: Surgical, Minimally Invasive, Direct, Cryopreserved |
| Companies Covered | AlloSource, RTI Surgical, MTF Biologics, CONMED Corporation, Integra LifeSciences, Stryker, Arthrex, MiMedx Group, Organogenesis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allografts Market Strategic Shifts
Processing technology and procurement models are restructuring competitive advantage in allograft supply. Three developments dominate the current transformation window.
Supercritical carbon dioxide sterilization is migrating from terminal sterilization of bone blocks toward soft tissue applications including tendons and dermal grafts. Academic medical center tissue banks pilot this platform to preserve biomechanical properties while achieving sterility assurance levels. The technology is compressing validation timelines for processors seeking alternatives to gamma irradiation.
REACH chemical substance restrictions in Europe are compelling reformulation of cleaning agents and disinfectants used in tissue recovery. Processors serving EU distribution channels audit supplier portfolios for SVHC compliance. Spinal fusion allografts with extended European supply chains face elevated documentation burdens for customs clearance.
Hospital value analysis committees now require outcome tracking for biologic implant expenditures. Integrated delivery networks in the United States negotiate performance guarantees linking graft incorporation rates to payment terms. This behavioral shift pressures processors to invest in clinical registry participation and real-world evidence generation.
Allografts Market Segmentation
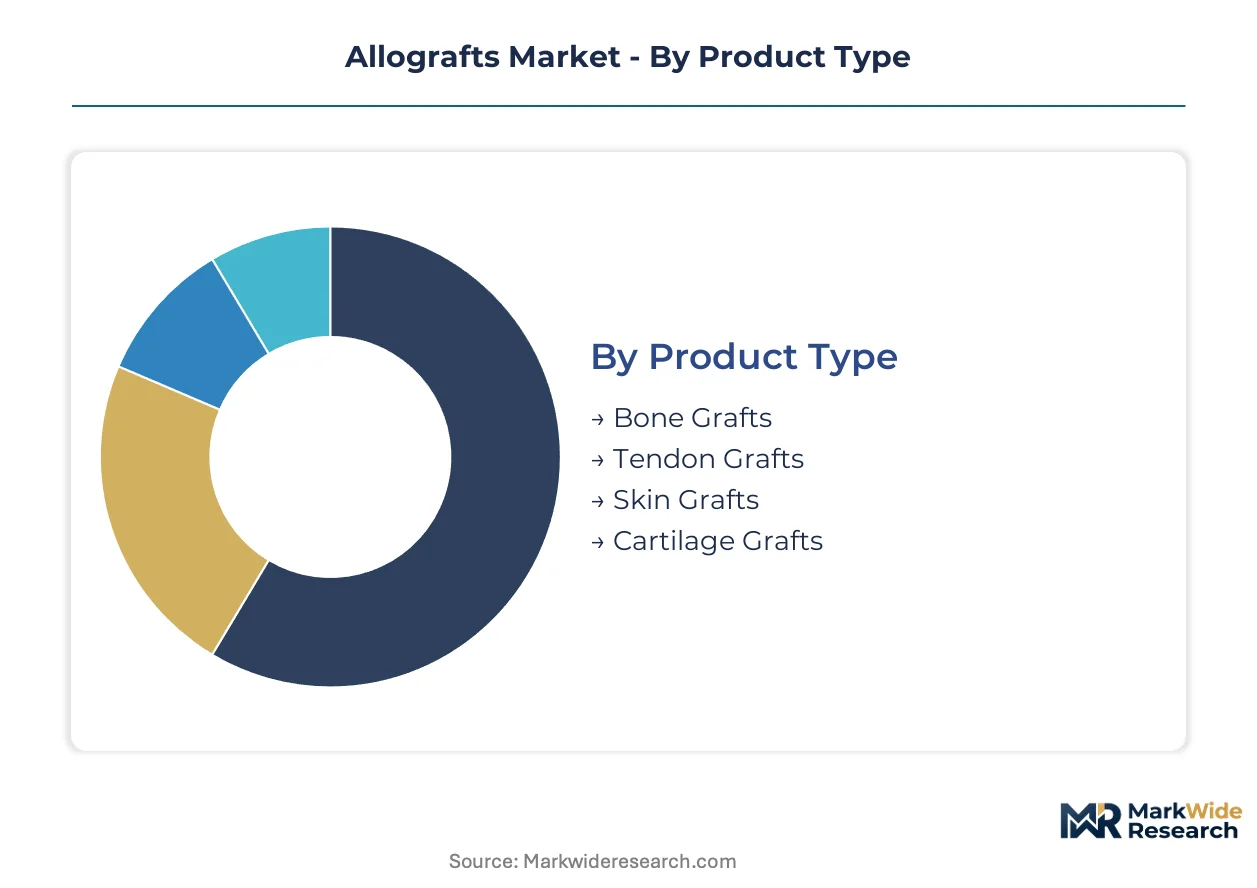
Segmentation in allografts reveals how processing complexity, surgical setting, and reimbursement pathways reshape procurement patterns. Each dimension exposes distinct margin structures and compliance burdens that processors must navigate.
Product Type:
Mature bone grafting applications coexist with emerging soft tissue categories where decellularization protocols are still validating.
- Bone Grafts:Cortical and cancellous matrices processed through terminal sterilization or cryopreservation serve spinal fusion and trauma reconstruction. Demand concentrates in United States tertiary hospitals where integrated delivery networks negotiate volume contracts for validated sterilization documentation. FDA Current Good Tissue Practice enforcement has eliminated marginal suppliers, consolidating procurement among scaled processors with dedicated quality systems.
- Tendon Grafts:Soft tissue allografts for anterior cruciate ligament repair undergo supercritical carbon dioxide sterilization to preserve biomechanical properties. Ambulatory surgical centers in the United States capture expanding volumes as anesthesia protocols enable same-day discharge. This segment climbs the fastest on share as outpatient orthopedic migration accelerates.
- Skin Grafts:Dermal matrices processed for wound reconstruction and burn care.
- Cartilage Grafts:Osteochondral allografts for joint surface restoration in academic medical centers.
Bone grafts handle the majority of throughput; tendon grafts are the fastest mover on share.
Application:
Cost tier differentiation separates high-reimbursement orthopedic procedures from price-sensitive wound care categories.
- Orthopedics:Spine fusion, joint reconstruction, and sports medicine procedures drive premium pricing. Surgeon preference for allografts over autografts to reduce donor-site morbidity sustains demand in United States hospital systems. EMA Human Tissue and Cell Directive harmonization is reducing cross-border distribution friction for European orthopedic applications.
- Wound Healing:Chronic wound matrices compete with synthetic alternatives on total cost of ownership. Hospital value analysis committees require outcome tracking for biologic implant expenditures, pressuring processors to invest in clinical registry participation.
- Dental:Periodontal and maxillofacial reconstruction applications.
- Cardiovascular:Vascular patch and cardiac repair applications with specialized processing requirements.
Orthopedics commands the revenue concentration; wound healing is expanding most quickly as decellularization technology opens immunologically sensitive applications.
End User:
Customer type stratification reflects the migration of procedures from inpatient to outpatient settings.
- Hospitals:Tertiary centers and academic medical centers perform complex multi-level spinal fusions requiring substantial graft volumes. Consolidation into integrated delivery networks has concentrated purchasing power, compressing vendor margins while elevating compliance barriers.
- Ambulatory Surgical Centers:Outpatient arthroscopic procedures and ACL reconstructions migrate from hospital settings as anesthesia protocols advance. These facilities demand streamlined inventory management and just-in-time delivery of cryopreserved grafts.
- Specialty Clinics:Orthopedic and wound care focused practices with direct procurement relationships.
- Research Institutions:Academic tissue banks piloting 3D bioprinting convergence with decellularized matrices.
Hospitals retain the dominant procurement volume; ambulatory surgical centers are gaining share fastest as procedure site migration accelerates.
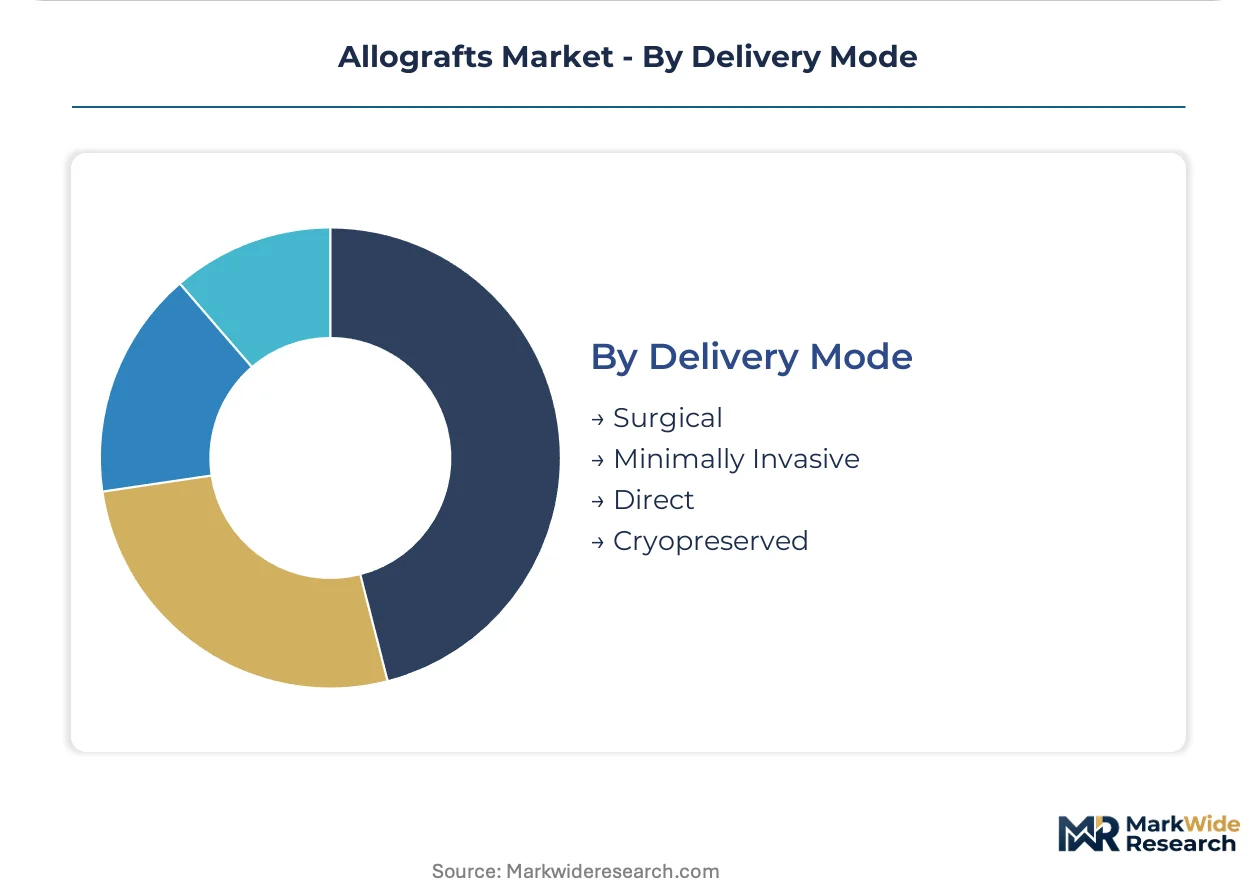
Delivery Mode:
Supply concentration varies sharply between validated cold-chain infrastructure and point-of-care preparation capabilities.
- Cryopreserved:Maintains cellular viability for osteochondral and soft tissue applications requiring fresh transplantation. Regional concentration of Organ Procurement Organizations creates geographic availability gaps that processors must navigate through distributed recovery networks.
- Minimally Invasive:Precision-machined grafts and injectable matrices adapted for arthroscopic and percutaneous delivery. Surgeon training programs in United States academic centers are expanding adoption of these form factors.
- Surgical:Standard open-procedure grafts with established handling protocols.
- Direct:Fresh osteochondral allografts with minimal processing for immediate transplantation.
Cryopreserved delivery handles the majority of soft tissue throughput; minimally invasive formats are climbing fastest as surgical technique evolves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial allograft trade surplus through its vertically integrated tissue recovery networks, while European processors navigate REACH chemical restrictions and cross-border harmonization under the EMA Human Tissue and Cell Directive. Import dependency concentrates in markets lacking domestic Organ Procurement Organization infrastructure.
United States
Hospital consolidation into integrated delivery networks concentrates purchasing power among tertiary centers performing multi-level spinal fusions. FDA Current Good Tissue Practice enforcement eliminates marginal suppliers and accelerates accreditation investments by scaled processors. The Denver-Aurora corridor anchors AlloSource's recovery network across transplant centers.
Germany
Aging demographics drive joint reconstruction volumes in academic medical centers across Bavaria and North Rhine-Westphalia. EMA Human Tissue and Cell Directive harmonization reduces regulatory fragmentation for cross-border tissue exchange. Berlin-Brandenburg hosts pilot programs for 3D bioprinting convergence with decellularized matrices.
United Kingdom
NHS value analysis committees require outcome tracking for biologic implant expenditures, pressuring processors toward clinical registry participation. MHRA alignment with EMA standards streamlines import pathways from accredited European banks. London's academic medical centers lead adoption of minimally invasive delivery form factors.
Japan
PMDA oversight of human tissue products maintains stringent donor screening protocols that elevate compliance costs for foreign suppliers. METI initiatives support domestic bioprinting research to reduce import dependency. The Kanto region around Tokyo concentrates procurement from university hospitals performing osteochondral allograft transplantation.
Australia
TGA regulation of biologicals mandates traceability systems that favor established processors with dedicated quality infrastructure. Geographic isolation from major tissue recovery networks creates supply continuity challenges for regional hospitals. New South Wales and Victoria host the majority of orthopedic procedure volumes driving allograft consumption.
Allografts Market Competitive Environment
On the supply side, the industry is consolidating toward scaled operators with validated sterilization platforms and dedicated quality systems. Tiered competitive positioning separates nonprofit tissue banks, commercial processors, and diversified medical device conglomerates. Dominant competitive moves include strategic partnerships with Organ Procurement Organizations and portfolio diversification into decellularized soft tissue applications.
Among nonprofit tissue banks, MTF Biologics exemplifies the credential-driven archetype that resonates with hospital ethics committees. RTI Surgical occupies a position within the precision-machining specialist tier, while AlloSource anchors the vertically integrated recovery network model. These three entities represent distinct strategic postures that processors must navigate amid tightening regulatory enforcement and concentrated purchasing power.
| Leading Market Players |
|---|
| AlloSource |
| RTI Surgical |
| MTF Biologics |
| CONMED Corporation |
| Integra LifeSciences |
| Stryker |
| Arthrex |
| MiMedx Group |
| Organogenesis |
| Others |
Value Chain & Pricing Dynamics
Organ Procurement Organization concentration across the United States Midwest and Southeast funnels donor tissue through a limited processor tier, concentrating margin capture among scaled operators with validated sterilization platforms and dedicated quality systems.
Pricing Analysis
Integrated delivery network buyers anchor contract-based long-term procurement structures in the allografts market. Three-tier pricing structure across premium decellularized soft tissue, standard terminal-sterilized bone, and economy unprocessed matrices reflects FDA Current Good Tissue Practice certification tiers and volume scale. Cost compression in the standard tier is intensifying because synthetic bone substitutes compete on total cost of ownership for spinal fusion. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize validated documentation over unit cost.
Supply Chain Analysis
Extended payment terms from hospital value analysis committees strain processor working capital, accelerating supply-chain finance facility adoption among mid-tier tissue banks. Geographic supply concentration centers on the United States, Germany, and Australia, where established Organ Procurement Organization infrastructure supports recovery continuity. Raw material dependencies encompass donor screening reagents, cryopreservation media, and validated packaging systems. Single-source vulnerability runs through regional Organ Procurement Organization coverage gaps. Distribution runs through direct hospital contracts and group purchasing organization channels with just-in-time cold-chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The allografts market follows orthopedic procedure cyclicality tied to elective surgery deferral patterns during economic contraction phases. Joint reconstruction volumes recover as patient confidence and insurance authorization normalize.
For Market Incumbents: Insulate market position through backward integration into donor recovery networks and accelerated decellularization platform validation. Synthetic bone substitute advancement threatens spinal fusion pricing power. Capacity addition in ambulatory surgical center-focused geographies preserves volume access as procedure sites migrate. For New Entrants and Emerging Players: Build out specialized processing capabilities for supercritical carbon dioxide sterilization of soft tissue grafts, where technical barriers limit incumbent replication speed. Wound healing applications in European markets offer the most penetrable segment given REACH compliance requirements that disadvantage established processors. Go-to-market leverage rests on clinical registry participation demonstrating real-world evidence to hospital value analysis committees. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated tissue banks with captive Organ Procurement Organization relationships and established FDA quality systems. Long-term viability across the next decade hinges on regulatory accreditation durability rather than product differentiation alone. The signal to watch is EMA Human Tissue and Cell Directive harmonization progress, which would unlock passporting advantages for multi-country distribution and reshape acquisition premiums for EU-accredited operators.| Strategic Initiative | Industry Significance |
|---|---|
| Decellularization Platform Validation | FDA Current Good Tissue Practice enforcement elevates compliance barriers for processors lacking advanced tissue engineering capabilities. |
| Organ Procurement Organization Partnership | Vertical recovery network control secures donor tissue supply continuity against regional mortality pattern volatility. |
| Ambulatory Surgical Center Distribution Agreement | Outpatient orthopedic migration demands just-in-time cryopreservation logistics and streamlined inventory management systems. |
| Clinical Registry Participation | Hospital value analysis committees require outcome tracking for biologic implant expenditure authorization. |
| EMA Accreditation Pathway Investment | Human Tissue and Cell Directive harmonization enables passporting advantages for cross-border EU tissue exchange. |
Study Parameters
Initial hypotheses were tested against primary input from tissue bank operations directors, orthopedic surgeons, hospital procurement managers, and regulatory affairs specialists and refined through secondary validation against FDA guidance documents, EMA regulatory filings, hospital procurement databases, and Organ Procurement Organization recovery statistics. Bottom-up demand modeling from procedure volumes and top-down market sizing from processor revenue triangulation anchored value estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeled by product type, application, end user, and delivery mode alongside regional regulatory cluster differentiation. CAGRs derived from procedure volume elasticity to demographic aging and reimbursement pathway stability. Forecast inputs incorporated surgeon preference shifts between allograft and autograft techniques and synthetic substitute competitive intensity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by diversified medical device conglomerates would shift outcomes beyond modeled ranges. Macroeconomic contraction affecting elective surgery volumes, regulatory deviation in donor screening protocols, or breakthrough synthetic scaffold efficacy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Spinal Non-Fusion Technologies Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Face Mask Device Market
Medical Devices
China Diabetes Devices Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
Prescription Goggles Market
Medical Devices
Cytology Brush Market
Medical Devices
Infusion Management Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Cardiac Resynchronization Therapy (CRT) Devices Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
North America Invisible Orthodontics Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Endoscope Procedure Kits Market