
 Robot Assisted PCI Market | 2026-2036
Robot Assisted PCI Market Size, Share, and Industry Trends Forecast 2026-2036
Robot Assisted PCI Market Analytics
Modular system bundling is recalibrating how hospitals evaluate capital commitments for robotic catheterization platforms. Siemens Healthineers leverages integrated imaging-to-robotics workflows to anchor premium positioning in European installations. Medtronic competes through backward integration into proprietary guidewire and catheter ecosystems that lock in recurring consumable revenue. Robocath specializes in compact, single-table robotic architectures that occupy a differentiated niche in mid-tier cath labs with space constraints.
Robot assisted percutaneous coronary intervention employs electromechanical navigation platforms that translate operator hand motions into sub-millimeter catheter manipulations within the vascular tree, typically achieving positioning accuracy below one millimeter while reducing fluoroscopic radiation exposure to interventional cardiologists. The technology serves primarily to standardize procedural outcomes across operator experience levels and to enable remote teleoperation for structural heart interventions. Penetrating robotics systems currently dominate installed base metrics due to their established track record in complex coronary lesions, while teleoperated systems represent the fastest-expanding technology category as 5G network latency improvements unlock real-time remote surgery applications. Among end users, hospitals capture the majority of capital equipment placements, though surgical centers are emerging as a concentrated margin pool where outpatient peripheral procedures generate faster equipment turnover cycles.
FDA premarket notification pathways and EU MDR conformity assessments shape product development timelines and commercial launch sequencing for manufacturers targeting dual-market approval. The EPA and OSHA maintain secondary influence through cath lab radiation safety standards and occupational exposure limits that robotic systems must demonstrably improve. Japan's PMDA operates a distinct approval track that prioritizes clinical evidence from domestic academic medical centers, creating a bottleneck for foreign entrants. Stakeholders must monitor how reimbursement coding evolution for robot-assisted procedures in Medicare and major European sickness funds determines the economic viability of hospital adoption beyond early-adopter academic institutions.
Market Dynamics
Teleoperated catheter navigation architectures are compressing the latency gap between operator hand motion and robotic instrument response, enabling real-time remote PCI procedures across metropolitan hospital networks.
Growth Catalysts
- FDA 510(k) premarket notification:Streamlined clearance for electromechanical navigation platforms accelerates commercial launch sequencing for manufacturers targeting dual US-EU approval pathways.
- 5G network infrastructure:Sub-10 millisecond latency specifications in urban Japanese and German deployments unlock synchronous teleoperation for structural heart interventions previously restricted to on-site robotics.
- Cath lab radiation exposure protocols:OSHA occupational limits and EPA safety standards mandate fluoroscopy reduction, positioning robotic systems as compliance instruments for interventional cardiology departments.
Market Restraints
- Capital equipment intensity:Single-table robotic architectures require cath lab renovation and imaging integration, constraining adoption to academic medical centers with dedicated structural heart programs.
- Consumable ecosystem lock-in:Proprietary guidewire and catheter compatibility restrictions tether hospitals to single-vendor supply chains, limiting competitive sourcing flexibility.
- PMDA domestic evidence requirements:Japan's pharmaceutical and medical device agency prioritizes clinical data from Japanese academic centers, creating approval bottlenecks for foreign robotic platform entrants.
Strategic Opportunities
- Mid-tier cath lab retrofit:Compact robotic systems occupy space-constrained European and Japanese facilities bypassed by full-scale penetrating robotics installations.
- EU MDR conformity acceleration:CE marking harmonization under the medical device regulation creates streamlined pathway for robotics manufacturers seeking European market entry.
- Peripheral vascular expansion:Lower-extremity arterial intervention applications extend robotic platform utilization beyond coronary procedures into outpatient surgical center settings.
Industry Challenges
- Interventional cardiologist training pipelines:Teleoperation competency requires simulation-based credentialing programs not yet standardized across residency curricula.
- Legacy imaging system integration:Robotic navigation platforms must interface with heterogeneous fluoroscopy and intravascular ultrasound installations across installed cath lab bases.
- Reimbursement coding evolution:Medicare and major European sickness funds lack discrete procedure codes for robot-assisted PCI, compressing economic viability assessments at non-academic hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot Assisted PCI Market |
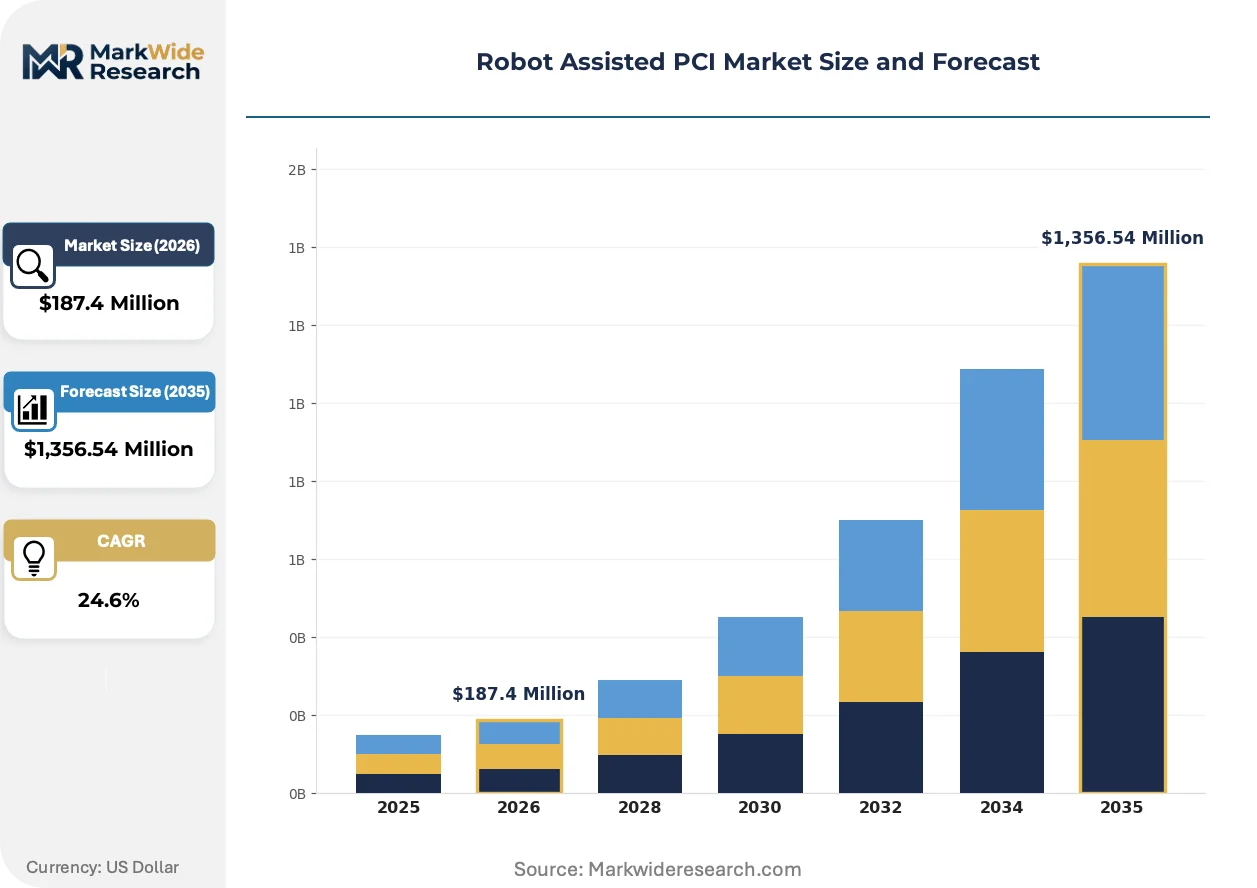
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,356.54 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Catheters, Guidewires, Accessories Technology: Penetrating Robotics, Non-Penetrating Robotics, Hybrid Systems, Teleoperated Systems End User: Hospitals, Surgical Centers, Cardiology Clinics, Academic Institutions Application: Coronary Procedures, Peripheral Procedures, Structural Heart Interventions, Electrophysiology |
| Companies Covered | Medtronic, Intuitive Surgical, Siemens Healthineers, Johnson & Johnson, Robocath, Philips, Stereotaxis, Auris Health, Smith+Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot Assisted PCI Market Evolving Landscape
Electromechanical catheter manipulation is displacing manual navigation in complex coronary lesions, while regulatory harmonization and procurement model evolution reshape competitive positioning across developed cath lab markets.
Haptic feedback integration is overtaking pure visual navigation in next-generation robotic platforms. The technology transmits force and torque sensation from catheter tip to operator console, enabling tactile lesion assessment without direct hand contact. Academic medical centers in Germany and Japan are piloting these systems for chronic total occlusion procedures. This sensory restoration is overtaking the historical trade-off between radiation protection and procedural feel that constrained earlier robotic adoption.
EU MDR Article 120 transition timelines are compressing conformity assessment windows for robotics manufacturers. The regulation mandates notified body involvement for medium-risk active devices, extending technical documentation requirements beyond previous medical device directive scopes. Siemens Healthineers and Robocath are restructuring quality management systems to align with post-market surveillance obligations, with German installations facing the most immediate compliance deadlines.
Service unbundling is fragmenting traditional capital-plus-consumable contracting. Hospitals now procure robotic platform access through procedure-volume commitments rather than outright equipment purchase, transferring utilization risk to vendors. This model is concentrating in United States integrated delivery networks and Japanese hospital groups with centralized cath lab governance, where equipment turnover cycles align with outpatient peripheral procedure expansion.
Robot Assisted PCI Market Segmentation
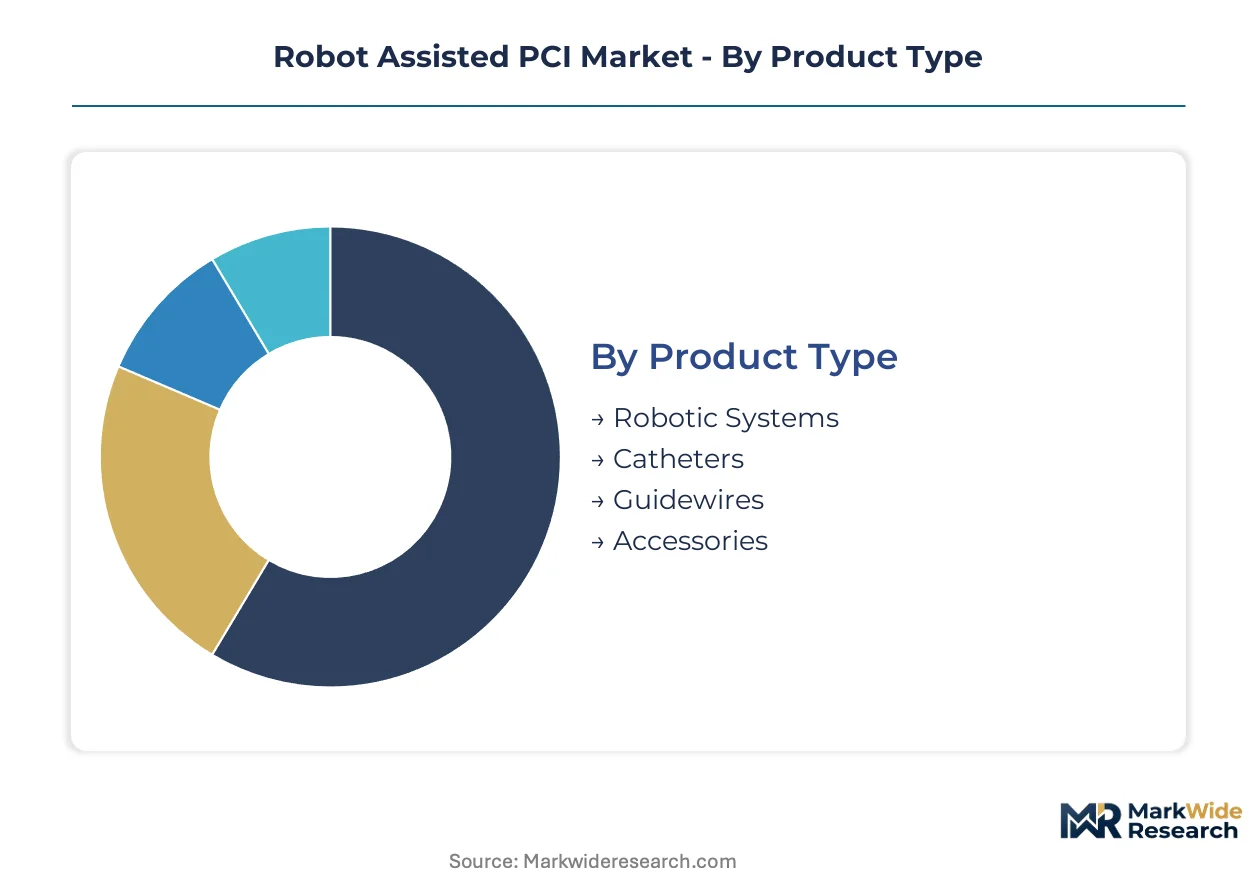
Segmentation in the Robot Assisted PCI Market reveals how regulatory pathways, capital intensity, and clinical workflows partition demand across equipment categories. Each dimension carries distinct certification burdens and procurement constraints that reshape vendor go-to-market strategies.
Product Type:
FDA 510(k) clearance timelines stretch longest for electromechanical platforms, while single-use catheters and guidewires navigate streamlined premarket notification pathways.
- Robotic Systems:Capital-intensive electromechanical platforms integrating haptic feedback consoles with catheter manipulation arms. Demand concentrates in German and Japanese academic medical centers where structural heart programs justify cath lab renovation costs and radiation safety compliance investments.
- Catheters:Single-use disposable components engineered for robotic gripper compatibility with proprietary torque transmission specifications. Surgical centers in the United States drive volume through outpatient peripheral procedure expansion, prioritizing rapid equipment turnover cycles over capital ownership.
- Guidewires:Torque-responsive navigation wires with robotic interface compatibility.
- Accessories:Sheaths, introducers, and sterile drapes completing procedural kits.
Robotic Systems sits at the top of the volume ranking, with Catheters climbing the fastest.
Technology:
CE marking under EU MDR Article 120 imposes divergent conformity assessment burdens depending on whether systems incorporate active electromechanical navigation or passive mechanical assistance.
- Penetrating Robotics:Established platforms with decades of coronary intervention track records, utilizing integrated imaging-to-robotics workflows. German cath labs anchor installed base metrics through Siemens Healthineers deployments, though capital intensity restricts expansion beyond dedicated structural heart centers.
- Teleoperated Systems:5G-enabled remote operation architectures translating operator hand motions across metropolitan networks. Japanese urban hospital networks pilot these systems for chronic total occlusion procedures, leveraging sub-10 millisecond latency specifications to enable real-time tele-surgery.
- Non-Penetrating Robotics:External navigation assistance without intravascular mechanical components.
- Hybrid Systems:Configurations blending on-site robotics with teleoperation capabilities.
Penetrating Robotics commands the largest revenue base, while Teleoperated Systems expands most quickly as network infrastructure matures.
End User:
Procurement authority and reimbursement coding access determine which facility types can absorb robotic platform capital commitments and consumable lock-in contracts.
- Hospitals:Integrated delivery networks with centralized cath lab governance and dedicated structural heart programs. United States academic medical centers dominate placements due to Medicare reimbursement flexibility and radiation safety compliance mandates from OSHA.
- Surgical Centers:Outpatient-focused facilities generating faster equipment turnover through peripheral vascular procedures. Japanese hospital groups with centralized procurement are piloting procedure-volume commitment models rather than capital purchase.
- Cardiology Clinics:Specialist practices with limited cath lab infrastructure.
- Academic Institutions:Training centers developing simulation-based credentialing curricula.
Hospitals retain the dominant share of capital placements, with Surgical Centers gaining share fastest through outpatient procedure expansion.
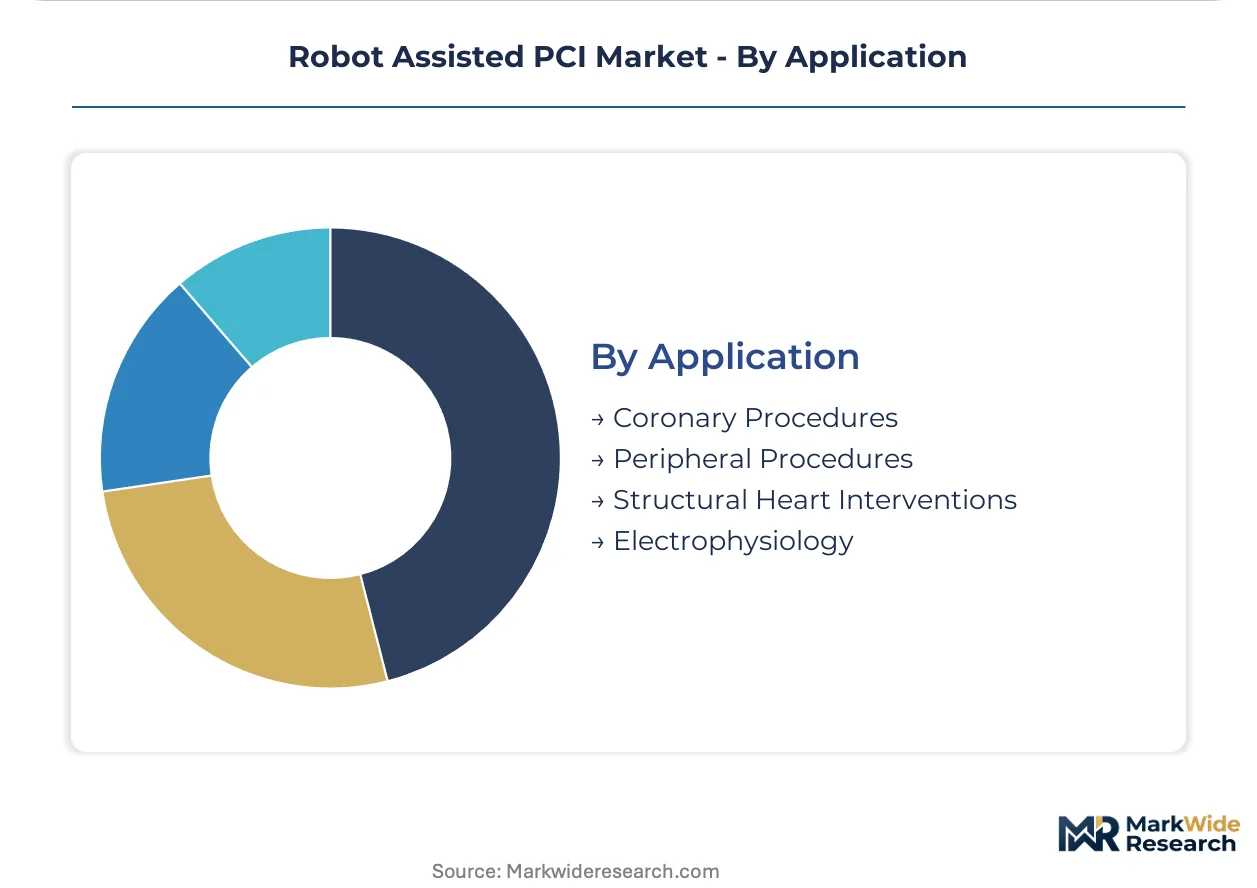
Application:
Clinical evidence requirements from Japan's PMDA and procedural complexity determine which applications justify robotic navigation overhead.
- Coronary Procedures:Complex lesion navigation including chronic total occlusions requiring sub-millimeter positioning accuracy. German centers lead utilization for haptic feedback-enabled tactile lesion assessment, standardizing outcomes across operator experience levels.
- Structural Heart Interventions:Transcatheter valve replacements and left atrial appendage closures demanding precise device deployment. Japanese academic medical centers generate PMDA-prioritized domestic evidence for foreign platform entrants.
- Peripheral Procedures:Lower-extremity arterial interventions extending robotic utilization into outpatient settings.
- Electrophysiology:Ablation catheter navigation for arrhythmia treatment.
Coronary Procedures maintains the highest procedure volume, with Structural Heart Interventions showing the steepest expansion trajectory as valve programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Robot-assisted PCI technology originated in German and Japanese academic cath labs during the early 2000s, where radiation safety concerns first drove electromechanical navigation development. These founding markets continue to anchor installed base metrics while newer entrants reshape competitive dynamics.
United States
Academic medical centers in Boston and Cleveland drive capital placements through Medicare reimbursement flexibility and OSHA-mandated fluoroscopy reduction. FDA 510(k) pathways accelerate commercial sequencing for dual-approval manufacturers. Integrated delivery networks in the Southeast are piloting procedure-volume commitment models rather than outright equipment purchase.
Germany
Siemens Healthineers anchors European installations through integrated imaging-to-robotics workflows in Bavarian and North Rhine-Westphalian structural heart centers. EU MDR Article 120 transition timelines compress conformity assessment windows for medium-risk active devices. The Eindhoven-to-Munich medical technology corridor concentrates haptic feedback pilot programs for chronic total occlusion procedures.
Japan
PMDA domestic evidence requirements create approval bottlenecks for foreign platform entrants, privileging clinical data from Tokyo and Osaka academic centers. METI-funded 5G infrastructure in urban hospital networks enables sub-10 millisecond latency teleoperation. Kansai-region hospital groups centralize procurement for outpatient peripheral procedure expansion.
United Kingdom
NHS England specialized commissioning frameworks concentrate robotic PCI adoption in London and Manchester tertiary centers with dedicated structural heart programs. MHRA convergence with EU MDR standards streamlines CE-marked device recognition post-Brexit. The Oxford-Cambridge arc generates health economics evidence for NICE technology appraisal pathways.
Switzerland
Swissmedic operates parallel conformity assessment tracks that attract manufacturers seeking early European market validation. Geneva and Zurich university hospitals host multinational clinical trials for teleoperated navigation platforms. The country's private hospital sector absorbs premium-tier capital equipment outside NHS-style budget constraints.
Robot Assisted PCI Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the capital-consumable bundling dimension, with integrated imaging-to-robotics workflows commanding price premiums over standalone navigation platforms. The vendor base stratifies into three tiers: diversified medical technology conglomerates with cath lab ecosystem control; pure-play robotics specialists with compact single-table architectures; and catheter-focused manufacturers backward-integrated into proprietary consumable streams. Dominant competitive moves include strategic partnerships between robotics developers and imaging system vendors, plus geographic expansion through procedure-volume contracting rather than capital sale.
Among diversified conglomerates, Siemens Healthineers and Medtronic exemplify contrasting ecosystem strategies, with the former anchoring premium positioning through imaging integration and the latter locking recurring revenue through proprietary guidewire and catheter compatibility. Robocath occupies a differentiated niche as a compact-system specialist targeting space-constrained mid-tier European and Japanese facilities bypassed by full-scale installations. These three archetypes represent the structural fault lines reshaping procurement negotiations across developed cath lab markets.
| Leading Market Players |
|---|
| Medtronic |
| Intuitive Surgical |
| Siemens Healthineers |
| Johnson & Johnson |
| Robocath |
| Philips |
| Stereotaxis |
| Auris Health |
| Smith+Nephew |
| Others |
Value Network & Pricing Analysis
Capital-consumable bundling divergence separates integrated imaging-to-robotics workflows from standalone navigation platforms, concentrating pricing power with vendors controlling proprietary catheter ecosystems while compressing margins for hardware-only suppliers tethered to third-party disposable sourcing.
Pricing Analysis
Procedure-volume commitment models are displacing outright capital purchase across United States integrated delivery networks and Japanese hospital groups, transferring utilization risk to vendors while locking buyers into multi-year consumable contracts. Price differentiation hinges on haptic feedback integration and FDA 510(k) clearance tier, with academic medical centers absorbing premium positioning for radiation safety compliance. Pricing pressure intensifies in mid-tier cath labs where compact single-table architectures from Robocath challenge full-scale Siemens Healthineers installations. Surgical centers exhibit highest price sensitivity due to faster equipment turnover cycles, while German structural heart programs prioritize performance over procurement cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German precision electromechanical component suppliers feeding haptic feedback console manufacturing. Robotic catheterization platforms draw from Taiwan semiconductor foundries for motion control processors, German optical sensor manufacturers for sub-millimeter positioning systems, and United States fluoroscopy integration modules. Tariff exposure runs through EU MDR notified body bottlenecks extending conformity assessment timelines. Distribution runs through direct vendor-hospital contracting with GPO intermediaries consolidating United States purchasing leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Robot Assisted PCI Market compounds steadily as chronic total occlusion procedural volumes climb and radiation safety mandates harden across OECD cath lab networks.
For Market Incumbents: Extend imaging-to-robotics workflow integration to capture premium positioning against compact-system challengers. Siemens Healthineers should deepen proprietary catheter ecosystem control to defend recurring revenue streams from Medtronic's backward integration into guidewire supply. Locking Japanese academic medical center evidence generation neutralizes PMDA approval bottlenecks for foreign entrants. For New Entrants and Emerging Players: Mid-tier European cath labs with space constraints represent the most penetrable buyer archetype, bypassed by capital-intensive penetrating robotics installations. Target outpatient surgical centers in the United States Southeast where procedure-volume commitment models concentrate procurement authority. Lead with teleoperated system pilots leveraging existing 5G infrastructure rather than demanding cath lab renovation. For Investors and Strategic Acquirers: Consolidation pressure builds where haptic feedback patent estates overlap with teleoperation software stacks. Pure-play robotics specialists with compact architectures and Japanese regulatory clearance offer acquisition profiles aligned with five-to-ten-year outpatient procedure expansion. Watch Medicare reimbursement coding evolution for robot-assisted PCI as the inflection signal determining economic viability beyond academic institutions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates dual US-EU approval sequencing for electromechanical platforms. |
| CE Marking Pathway | EU MDR Article 120 compliance anchors German market access through notified body restructuring. |
| Hospital System Partnership | Procedure-volume commitment models transfer utilization risk to vendors in United States IDNs. |
| Software Companion Development | Teleoperation latency compression unlocks real-time remote PCI across metropolitan Japanese networks. |
| Reimbursement Strategy | Medicare coding evolution determines economic viability for non-academic hospital adoption. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement schedules, and hospital procurement records. Bottom-up equipment installation tracking and top-down cath lab infrastructure surveys triangulated market sizing.
Comparable historical reference periods anchored the projection horizon across product type, technology architecture, end-user facility tier, and application complexity dimensions. CAGRs derived from segmented procedure volume growth rates, capital equipment replacement cycles, and consumable attach rate assumptions. Forecast inputs incorporated 5G network latency specifications, EU MDR transition timelines, and PMDA domestic evidence requirements.
Underlying measurement precision varies by segment; penetrating robotics installations carry tighter precision than emerging teleoperated system pilots. Forecasts reflect assumptions about reimbursement coding evolution, regulatory harmonization pace, and interventional cardiologist training pipeline maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Urometer Market
Medical Devices
Osteotomy Plates Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
Sinus Dilation Devices Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Non-Invasive Ventilators Market
Medical Devices
Blood Irradiator Device Market