
 Point-Of-Care Breathalyzer Market | 2026-2036
Point-Of-Care Breathalyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Point-Of-Care Breathalyzer Market Analytics
Workplace safety managers are bifurcating from law enforcement agencies as the fastest-growing buyer archetype for point-of-care breathalyzers. Drägerwerk AG & Co. KGaA leverages its German engineering heritage to dominate medical-grade certification standards across European clinics. BACtrack competes aggressively in the smartphone-integrated segment, while Intoximeters sustains deep relationships with emergency services through ruggedized hardware platforms.
Point-of-care breathalyzers are electrochemical or optical devices that measure blood alcohol concentration through exhaled breath analysis, typically achieving accuracy within 0.001% BAC using fuel cell oxidation or infrared spectroscopy methods. These instruments serve clinical diagnostics, occupational safety compliance, and roadside law enforcement screening with results available in 10-30 seconds. Fuel cell technology anchors the premium tier with superior specificity against acetone and other interferents, while smartphone-integrated models represent the fastest-growing structural segment as telehealth platforms absorb remote monitoring workflows. Semiconductor sensors occupy the high-volume, lower-accuracy economy tier where price sensitivity shapes procurement in developing markets.
FDA 510(k) clearance requirements and OSHA workplace testing protocols shape product development roadmaps and channel access for manufacturers targeting the United States. Germany's KBA type-approval standards and Japan's METI certification frameworks create parallel compliance barriers for devices entering those markets. Stakeholders must monitor evolving cannabis-impairment detection mandates as jurisdictions expand point-of-care testing beyond alcohol to multi-substance panels.
Market Dynamics
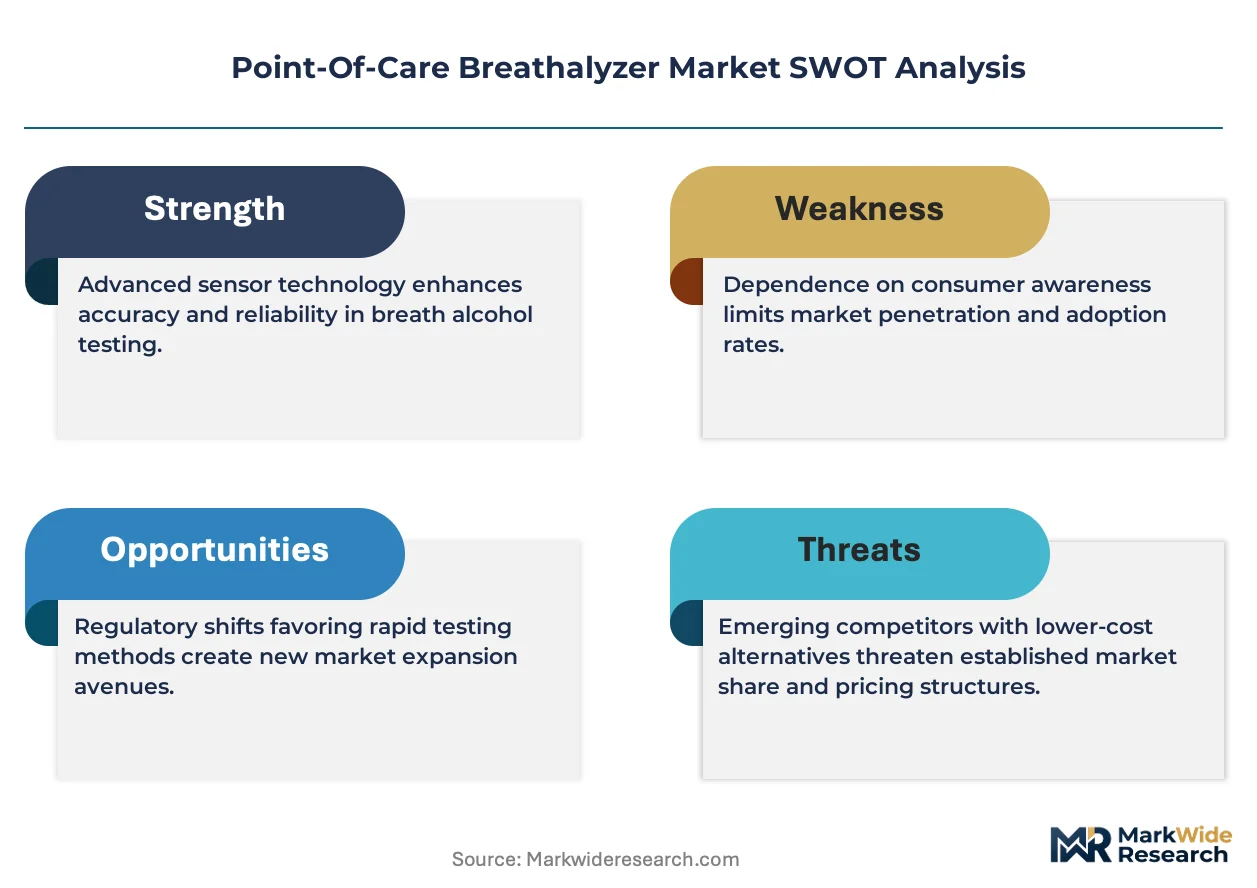
Fuel cell oxidation technology is consolidating its dominance over semiconductor sensors as workplace safety programs and roadside law enforcement tighten accuracy requirements, creating a bifurcation between premium medical-grade certification and economy-tier procurement.
Growth Catalysts
- OSHA workplace testing mandates:United States employers face expanding compliance obligations for alcohol screening protocols, driving replacement cycles for legacy semiconductor devices.
- Telehealth platform integration:Remote patient monitoring workflows are absorbing smartphone-connected breathalyzers for substance use disorder management and post-operative care.
- KBA type-approval standards:Germany's medical-grade certification requirements create premium procurement tiers that European clinics and occupational health services prioritize over uncertified alternatives.
Market Restraints
- Platinum catalyst cost volatility:Fuel cell electrodes depend on platinum group metals, exposing manufacturers to commodity price swings that compress margins on fixed-price contracts.
- Acetone interference limitations:Semiconductor sensors suffer false positives from ketone bodies, restricting their deployment in diabetic populations and clinical settings where metabolic variability is high.
- FDA 510(k) pathway duration:United States clearance timelines extend 12-18 months for novel sensor technologies, delaying commercialization and freezing R&D amortization schedules.
Strategic Opportunities
- Cannabis-impairment detection mandates:Jurisdictions expanding point-of-care testing beyond alcohol create demand for multi-substance panels and hybrid sensor arrays.
- Japan's METI certification frameworks:Medical-grade device standards in Japanese occupational health programs open premium procurement channels for certified manufacturers.
- Subscription-based calibration services:Remote sensor monitoring and predictive maintenance contracts transform one-time hardware sales into recurring revenue streams.
Industry Challenges
- Electrochemical sensor engineering talent scarcity:Specialized expertise in fuel cell miniaturization and interferent suppression concentrates in German and Japanese industrial clusters, constraining workforce expansion elsewhere.
- Legacy fleet integration complexity:Enterprise customers demand backward compatibility with existing data management systems, forcing manufacturers to maintain obsolete communication protocols alongside modern IoT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point-Of-Care Breathalyzer Market |
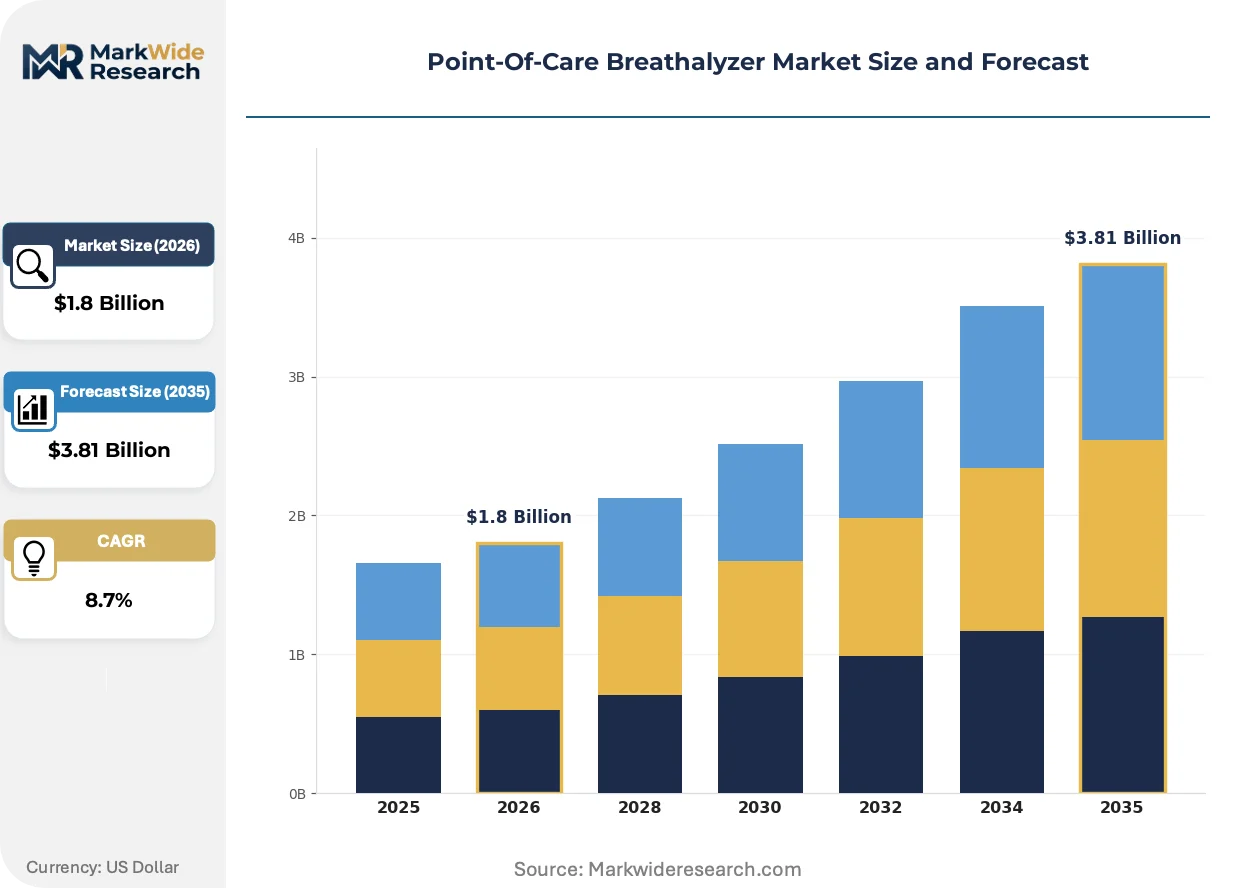
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Wall-Mounted, Portable, Smartphone-Integrated End User: Clinics, Emergency Services, Law Enforcement, Rehabilitation Centers Technology: Fuel Cell, Semiconductor, Infrared, Optical Application: Alcohol Testing, Drug Screening, Health Monitoring, Safety Management |
| Companies Covered | Lifeloc Technologies, Quest Products, Drägerwerk AG & Co. KGaA, C4 Development, Alere, Intoximeters, BACtrack, Andatech Private Limited, Lion Laboratories Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point-Of-Care Breathalyzer Market Evolving Landscape
Point-of-care breathalyzer technology is converging with digital health infrastructure and evolving regulatory mandates, reshaping how accuracy, connectivity, and compliance interlock in device design and commercial strategy.
Infrared spectroscopy methods are displacing fuel cell oxidation in high-throughput occupational health screening environments where batch calibration and reduced consumable costs outweigh absolute specificity requirements. Corporate wellness providers and logistics fleet operators are adopting these systems for monthly compliance audits rather than incident-triggered testing. The shift is compressing average selling prices in the mid-tier segment while expanding total addressable volume.
Europe's MDR and F-Gas Regulation are tightening substance restrictions and clinical validation requirements for devices claiming medical use. Manufacturers must now document environmental impact across the device lifecycle and maintain post-market surveillance registries. German and Swiss diagnostic distributors are prioritizing suppliers with established notified body relationships, filtering out smaller competitors lacking regulatory infrastructure.
Hospital procurement committees are consolidating vendor relationships through multi-year managed service agreements that bundle hardware, calibration, and data analytics. These contracts displace spot purchasing through medical supply distributors in the United States and Australia. Occupational health departments in mining and construction verticals are driving this consolidation, seeking unified reporting platforms that integrate breathalyzer results with fitness-for-duty databases.
Point-Of-Care Breathalyzer Market Segmentation
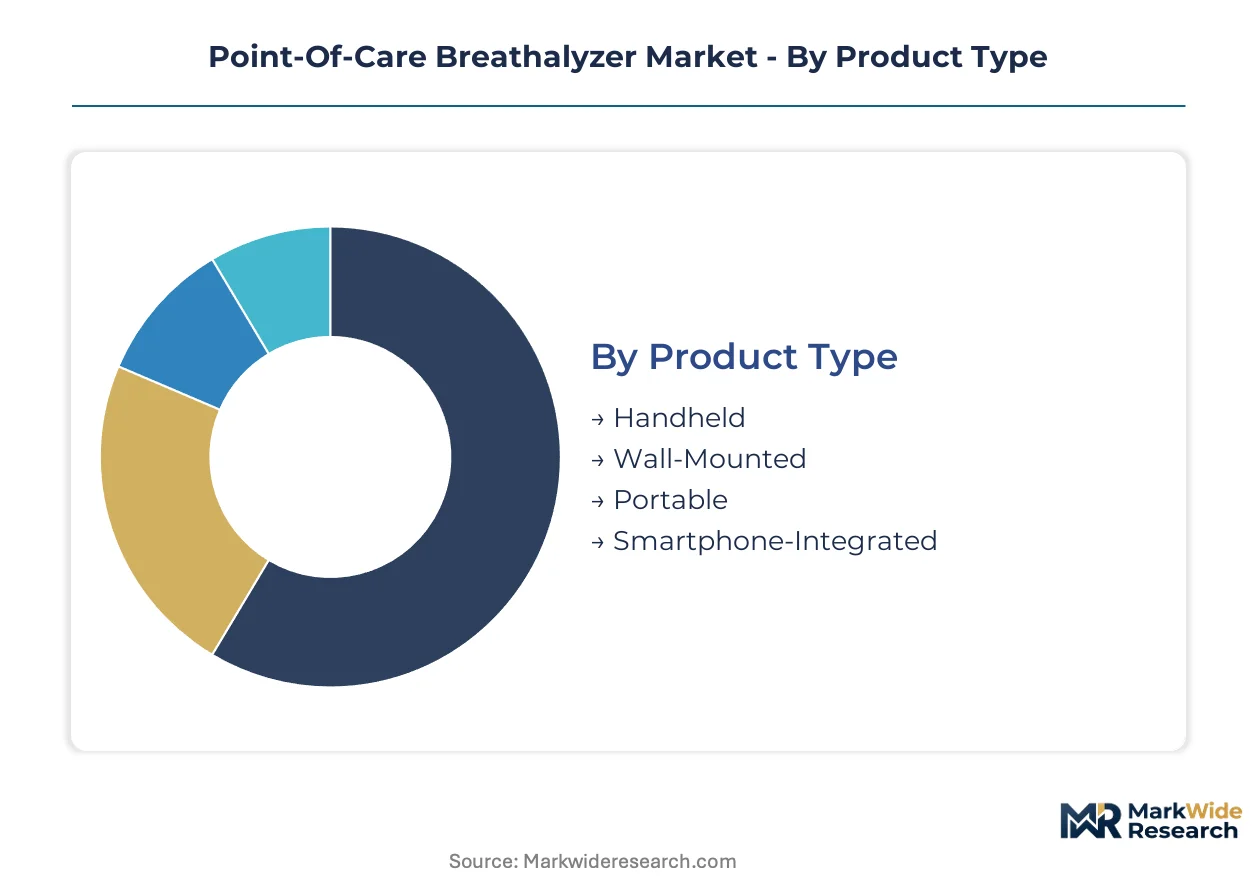
Point-of-care breathalyzer procurement splits across four distinct dimensions that reshape channel strategy. Product form factor determines whether devices flow through medical distributors, direct enterprise sales, or consumer retail. End-user concentration in regulated environments creates compliance-driven purchasing committees rather than individual buyers.
Product Type:
Channel mix varies sharply by form factor: handheld units dominate occupational health distributor networks, wall-mounted systems route through facility integrators, while smartphone-integrated models increasingly bypass traditional channels via telehealth platform partnerships.
- Handheld:Battery-operated units with fuel cell or semiconductor sensors designed for single-operator field use. Law enforcement agencies and construction site supervisors in Germany and Australia drive replacement demand as OSHA-type mandates expand accuracy requirements.
- Wall-Mounted:Fixed-installation units with automated calibration cycles and centralized data logging. Corporate wellness programs and logistics fleet depots in Japan favor these for high-throughput screening environments where supervisor presence is limited.
- Portable:Lightweight units balancing handheld mobility with enhanced connectivity features. Emergency medical services prioritize these for ambulance deployment where rapid BAC assessment guides triage decisions.
- Smartphone-Integrated:Compact sensors pairing with mobile applications for remote monitoring and telehealth integration. Substance use disorder clinics and post-operative care programs in the United States absorb these through digital health platform procurement.
By volume, handheld leads. By growth pace, smartphone-integrated is ahead.
End User:
Cost tier stratification separates premium medical-grade procurement from economy-tier bulk purchasing, with certification requirements acting as the primary pricing determinant.
- Clinics:Primary care and occupational health facilities requiring FDA 510(k) or KBA type-approved devices for diagnostic use. German and Swiss distributors prioritize suppliers with established notified body relationships.
- Emergency Services:Fire departments and ambulance operators demand ruggedized hardware with rapid 10-15 second response times. These buyers sustain premium pricing for fuel cell accuracy where incident liability exposure is acute.
- Law Enforcement:Police and highway patrol agencies operating under evidentiary standards requiring documented calibration chains and interferent suppression. Procurement concentrates through government tender processes with multi-year maintenance contracts.
- Rehabilitation Centers:Substance use disorder treatment facilities integrating breathalyzers into compliance monitoring programs. These facilities drive subscription-based calibration service adoption.
Law Enforcement commands the highest unit prices. Rehabilitation Centers are expanding most quickly.
Technology:
Application context determines technology selection: clinical and legal environments demand fuel cell specificity, while high-volume screening tolerates infrared throughput.
- Fuel Cell:Electrochemical oxidation of ethanol at platinum catalyst electrodes delivering 0.001% BAC precision with acetone interference suppression. Workplace safety programs and roadside law enforcement in the United States, Germany, and Japan mandate this technology for regulatory compliance.
- Semiconductor:Metal oxide sensors detecting alcohol through conductivity changes at lower manufacturing cost. Developing markets absorb these where price sensitivity outweighs accuracy requirements, though ketone interference restricts diabetic population deployment.
- Infrared:Spectroscopic absorption measurement enabling batch calibration and reduced consumable costs. Corporate wellness providers adopt these for monthly compliance audits rather than incident-triggered testing.
- Optical:Emerging photonic and colorimetric methods for multi-substance panel detection. Cannabis-impairment detection mandates are accelerating R&D investment in hybrid sensor arrays.
Fuel Cell dominates revenue. Infrared is gaining share fastest in occupational health screening.
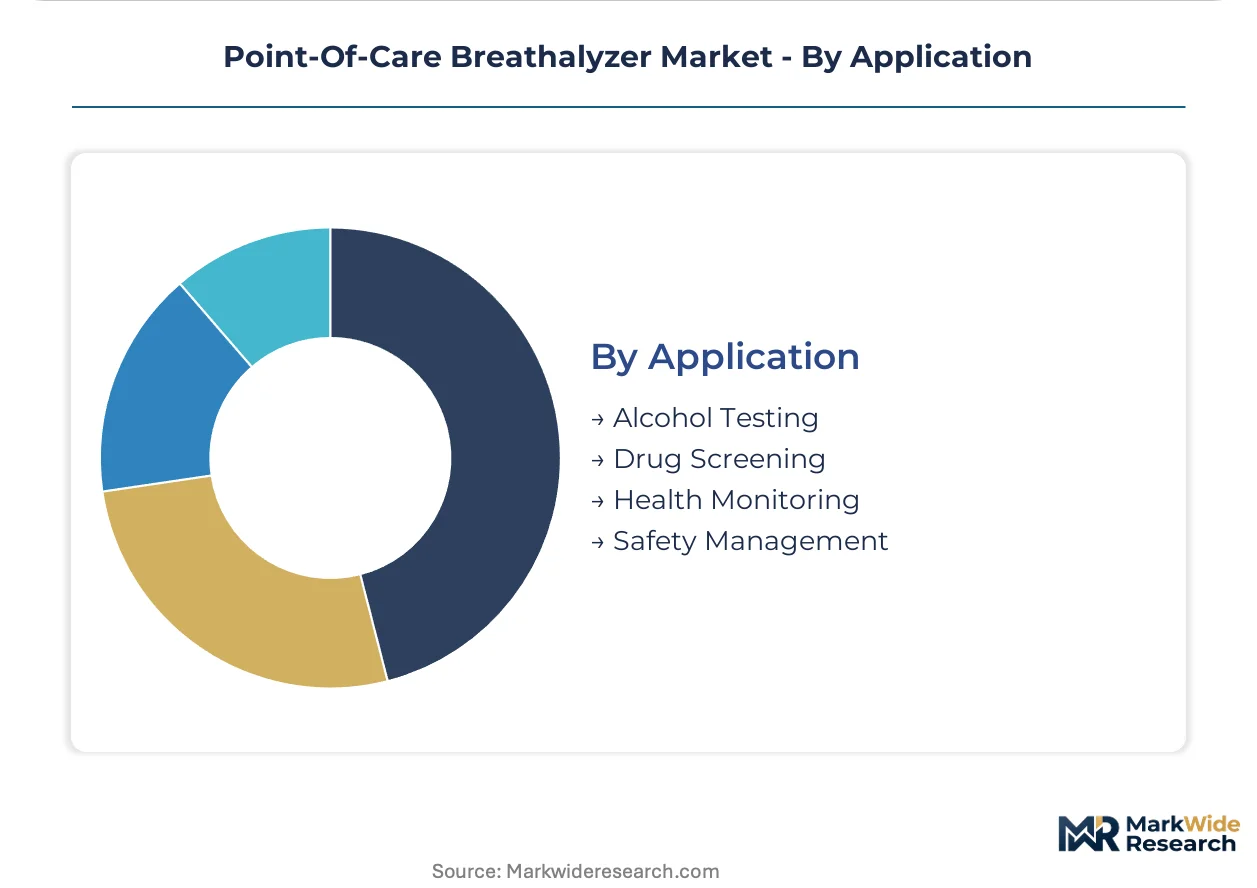
Application:
Customer maturity varies by use case: alcohol testing represents established compliance infrastructure, while drug screening and health monitoring require novel regulatory frameworks.
- Alcohol Testing:Blood concentration measurement for workplace safety, law enforcement, and clinical diagnostics. OSHA mandates and KBA standards sustain premium device procurement across the United States and Germany.
- Drug Screening:Expansion beyond alcohol to cannabis, opioids, and other impairing substances. Jurisdictions in Australia and Canada are piloting multi-substance point-of-care panels.
- Health Monitoring:Metabolic tracking and ketone assessment for diabetic management. Telehealth platforms absorb smartphone-integrated devices for remote patient monitoring.
- Safety Management:Fitness-for-duty protocols integrating breathalyzer results with broader occupational health databases. Mining and construction verticals in Australia drive unified reporting platform consolidation.
Alcohol Testing leads by installed base. Drug Screening shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's distribution hub for medical-grade breathalyzer imports across Central Europe, while the Trans-Siberian rail corridor enables Japanese and Australian manufacturers to reach Eurasian markets without maritime delays.
United States
OSHA workplace testing mandates and DOT roadside enforcement protocols drive replacement demand for fuel cell devices. FDA 510(k) clearance pathways filter out uncertified competitors, creating premium procurement tiers. Industrial clusters in the Midwest and Texas absorb volume through occupational health distributors serving manufacturing and logistics verticals.
Germany
KBA type-approval standards and MDR medical device regulations establish the strictest certification barriers in Europe. Bavarian engineering centers and Stuttgart's automotive corridor concentrate R&D talent for interferent suppression technologies. Workplace safety programs in the Ruhr industrial basin sustain high-throughput screening demand.
Japan
METI certification frameworks and corporate wellness mandates in the Tokyo-Osaka corridor prioritize medical-grade accuracy. The Nagoya industrial cluster hosts precision manufacturing for fuel cell electrodes and platinum catalyst assemblies. Prefectural police forces standardize on evidentiary-grade devices for roadside enforcement.
Australia
TGA medical device registration and state-level workplace safety codes drive premium device adoption in mining and construction. Perth and Brisbane serve as distribution nodes for Asia-Pacific resource extraction operations. Telehealth integration trials in Melbourne and Sydney accelerate smartphone-connected breathalyzer procurement.
Point-Of-Care Breathalyzer Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification depth, creating a tiered structure where medical-grade approval separates premium vendors from economy-tier suppliers. The vendor base clusters around three strategic archetypes: German engineering heritage firms dominating European clinical standards, smartphone-integrated specialists capturing telehealth workflows, and ruggedized hardware providers sustaining emergency services relationships. Competitive moves concentrate on M&A for regulatory infrastructure and strategic partnerships with telehealth platforms.
Within the medical-grade certification tier, Drägerwerk AG & Co. KGaA exemplifies the engineering heritage archetype through its German GmbH structure, while BACtrack occupies a position representing smartphone-integrated connectivity specialists. Intoximeters anchors the ruggedized hardware segment serving emergency services procurement channels. These three entities collectively illustrate how regulatory geography and end-user specialization fragment competitive positioning across the analysis window.
| Leading Market Players |
|---|
| Lifeloc Technologies |
| Quest Products |
| Drägerwerk AG & Co. KGaA |
| C4 Development |
| Alere |
| Intoximeters |
| BACtrack |
| Andatech Private Limited |
| Lion Laboratories Limited |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance pathways and Germany's KBA type-approval standards simultaneously gate supplier qualification and stratify price tiers, forcing manufacturers to absorb certification costs upfront while capturing returns through premium positioning in clinical and law enforcement channels. This regulatory scaffolding creates procurement committees that weight total cost of ownership over unit price, embedding calibration services and maintenance contracts into purchasing decisions.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with occupational health distributors negotiating fleet pricing for handheld fuel cell units while telehealth platforms absorb smartphone-integrated sensors through subscription-based calibration bundles. Price differentiation rests on certification grade and after-sales service depth, with FDA-cleared devices commanding substantial premiums over uncertified alternatives. Cost compression in the semiconductor sensor tier is intensifying as developing-market procurement shifts toward disposable units. Rehabilitation centers and substance use clinics exhibit highest price sensitivity, whereas emergency services prioritize accuracy over unit cost.
Supply Chain Analysis
Strategic stockpiling of platinum group metals anchors inventory strategy for fuel cell electrode manufacturers, mitigating commodity volatility that would otherwise disrupt fixed-price maintenance contracts. Component sourcing concentrates in Germany, Japan, and the United States, with precision machining of fuel cell housings feeding from Bavarian engineering clusters and platinum catalyst assemblies drawing from Nagoya industrial bases. Single-source vulnerability in platinum supply chains poses structural risk given South African and Russian concentration. Distribution runs through medical device distributors in regulated markets and direct enterprise sales in occupational health verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration-as-a-service revenue layers are expanding faster than hardware sales as hospital procurement committees consolidate vendor relationships through multi-year managed service agreements. This service-attach dynamic repositions breathalyzer economics toward recurring revenue streams.
For Market Incumbents: Consolidate regulatory infrastructure through acquisition of notified body relationships in Europe and TGA registration capabilities in Australia, defending against smartphone-integrated entrants lacking certification depth. Vertical integration into platinum catalyst recycling secures margin control against commodity volatility. Channel control through exclusive distributor arrangements in German and Japanese occupational health networks maintains pricing power.
For New Entrants and Emerging Players: Differentiate on telehealth platform integration and remote patient monitoring workflows, where software companion development barriers exceed hardware manufacturing complexity. The smartphone-integrated segment offers most penetrable white space, particularly in United States substance use disorder clinics and Australian post-operative care programs. Go-to-market through digital health platform partnerships bypasses traditional medical distributor gatekeeping.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized fuel cell sensor divisions lacking healthcare regulatory infrastructure. Long-term viability hinges on cannabis-impairment detection capabilities expanding addressable testing panels beyond alcohol. Watch for METI certification mandates in Japanese corporate wellness programs as inflection indicator for premium device demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | FDA 510(k) and KBA type-approval unlock premium clinical and law enforcement procurement channels. |
| Telehealth Platform Partnership | Smartphone-integrated sensor integration absorbs remote monitoring workflows in substance use clinics. |
| Calibration Service Subscription | Predictive maintenance contracts transform one-time hardware sales into recurring revenue streams. |
| Multi-Substance Sensor R&D | Cannabis-impairment detection mandates expand addressable testing panels beyond alcohol concentration. |
| Platinum Supply Security | Strategic stockpiling and recycling capabilities mitigate commodity volatility in fuel cell electrode production. |
Research Methodology
The analysis maps fuel cell oxidation, semiconductor sensor, infrared spectroscopy, and emerging optical detection sub-sectors, each validated through biomedical engineers, hospital purchasing committee members, occupational health program directors, and fuel cell electrode manufacturing specialists. Primary interviews with GPO contracts managers and telehealth platform procurement leads combined with secondary validation against FDA 510(k) filings, TGA medical device registries, KBA type-approval databases, and METI certification records. Bottom-up unit economics triangulated against top-down market sizing across technology and end-user dimensions.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for platinum group metal imports, hospital procurement database trends, and occupational health distributor sales disclosures. The analytical framework modeled product form factor, technology tier, end-user concentration, and regional regulatory cluster across the projection horizon. CAGRs derived from segmented growth rate analysis incorporating OSHA mandate expansion timelines, KBA certification backlog durations, and telehealth platform adoption curves in substance use disorder management.
Decision-makers should treat outputs as directional under stable regulatory enforcement and platinum price assumptions; material deviation in cannabis-impairment detection mandate timing or fuel cell electrode commodity spikes would warrant model refresh. Revision becomes warranted when METI or TGA certification requirement expansions cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
PCR and Real-Time PCR Molecular Diagnostics Market
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
Urine Analyzers Market
Diagnostic Devices
Procalcitonin Antibody Market