
 Rapid Infuser Market | 2026-2036
Rapid Infuser Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Infuser Market Outlook
The gap between premium systems with integrated fluid warming and commodity gravity-based infusers is repositioning procurement criteria across health systems. Smiths Medical leverages its anesthesia and critical care heritage to sustain engineering depth in pressurized delivery platforms. ZOLL Medical Corporation differentiates through emergency care channel control, while Belmont Medical Technologies anchors its position in military and trauma applications with ruggedized hardware.
A rapid infuser is a electromechanical or pressure-assisted device designed to deliver crystalloids, colloids, or blood products at controlled rates exceeding 500 mL/minute, incorporating warming elements to maintain fluid temperature between 37°C and 42°C and prevent hypothermia during massive transfusion or resuscitation. Adult rapid infusers dominate installed base volume but face margin compression as purchasing committees standardize on multi-patient platforms; portable infusers represent the fastest structural expansion as pre-hospital EMS agencies and field military units demand battery-operated, lightweight alternatives to hospital-tethered systems. Emergency procedures applications command premium pricing due to time-critical workflow requirements, while blood transfusion use cases benefit from integrated warming technology that reduces adverse event liability.
FDA 510(k) clearance requirements govern device safety and electromagnetic compatibility for US commercialization, while the EU Medical Device Regulation enforces stricter clinical evidence standards for CE marking of active therapeutic devices. Health Canada and TGA Australia maintain parallel approval frameworks that manufacturers must navigate for multi-jurisdiction product rollouts. Stakeholders should monitor how evolving warming technology performance standards and pre-hospital care protocol expansions reshape R&D investment priorities and partnership structures.
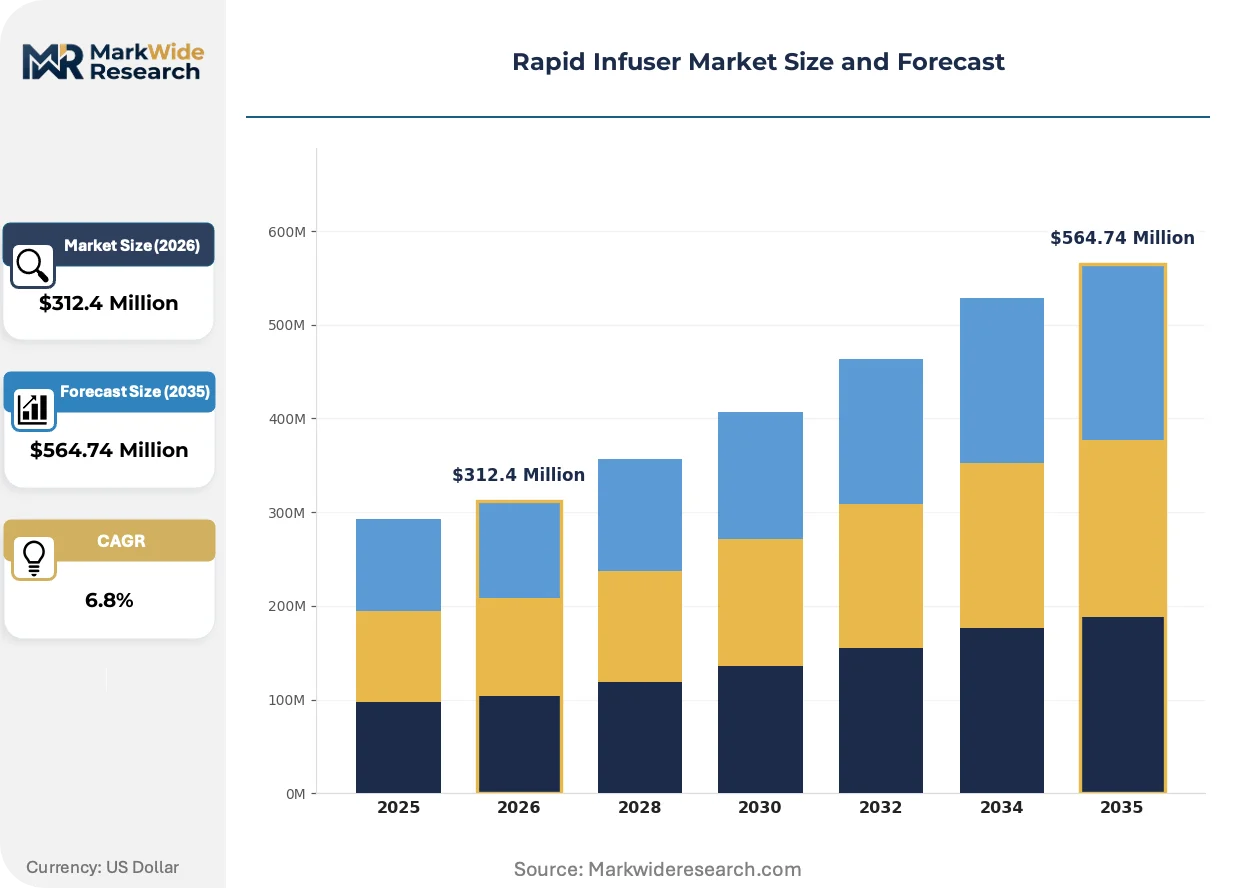
Market Dynamics
The divergence between pressure-driven warming systems and gravity-based alternatives is compressing margins on legacy hardware while rewarding vendors who integrate thermal regulation with portable power architectures. Hospital procurement committees now weight total cost of ownership against acquisition price.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance timelines for electromechanical devices with predicate equivalence accelerate commercialization cycles for pressure-assisted platforms targeting trauma centers.
- Massive transfusion protocol standardization:German hospital networks mandate integrated warming technology for Level I trauma activation, creating installed base expansion in emergency departments.
- Battery chemistry advances:Lithium-ion energy density improvements enable field-deployable rapid infusers that operate independently of hospital power grids for military and pre-hospital applications.
Market Restraints
- Precision component supply concentration:Ceramic heating elements and pressure sensors depend on specialized East Asian contract manufacturers, exposing production schedules to geopolitical friction.
- EU MDR clinical evidence burdens:Stricter post-market surveillance requirements for active therapeutic devices extend CE marking timelines and inflate regulatory compliance costs.
- Gravity-based substitute persistence:Commodity infusion sets without warming capability retain share in cost-constrained ambulatory surgery centers where hypothermia risk is deemed acceptable.
Strategic Opportunities
- Pre-hospital EMS channel penetration:Ground and air ambulance services in Australia represent underdeveloped demand for battery-operated, lightweight warming infusers with ruggedized housings.
- Dual-use military-civilian technology transfer:Combat casualty care protocols validated by US Department of Defense trauma research create regulatory precedents for civilian emergency medicine adoption.
- Integrated data connectivity:Convergence of fluid delivery systems with electronic health record platforms enables real-time transfusion documentation and adverse event tracking.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise combining thermodynamics, electromechanical design, and clinical workflow optimization remains concentrated among legacy anesthesia equipment specialists.
- 510(k) predicate device drift:FDA scrutiny of substantial equivalence claims for novel warming technologies extends submission review periods and requires additional bench testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Infuser Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Rapid Infuser, Pediatric Rapid Infuser, Portable Infuser, High-Volume Infuser End User: Hospitals, Emergency Medical Services, Surgical Centers, Military Medical Units Technology: Heating Technology, Pressure Infusion, Gravity Infusion, Fluid Warming Systems Application: Trauma Surgery, Blood Transfusion, Critical Care, Emergency Procedures |
| Companies Covered | 3M Health Care, Smiths Medical, ZOLL Medical Corporation, Belmont Medical Technologies, ICU Medical, Stryker Corporation, Teleflex Incorporated, Baxter International, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Infuser Market Strategic Shifts
Active thermal management is migrating from accessory status to core device architecture, with warming performance becoming a primary procurement discriminator rather than an optional upgrade module.
Portable battery-powered rapid infusers are expanding into pre-hospital emergency services and military field medicine, where tethered systems cannot operate. EMS agencies in North America and Australia are piloting lightweight units that maintain 37°C output without external power. This mobility is expanding into civilian trauma networks that previously restricted rapid infusion to fixed emergency departments.
The EU Medical Device Regulation enforces clinical performance documentation for active therapeutic devices that previous directives treated as low-risk. Manufacturers must generate post-market clinical follow-up data for CE-marked warming systems. German and French notified bodies are applying this most stringently to pressurized fluid delivery platforms with integrated heating elements.
Hospital purchasing committees are consolidating vendor relationships around multi-patient platforms that serve emergency, operating room, and intensive care environments. Single-use disposables and service contracts now generate recurring revenue that offsets capital equipment discounting. This bundling is most visible in US health systems pursuing standardization across affiliated trauma centers.
Rapid Infuser Market Segmentation
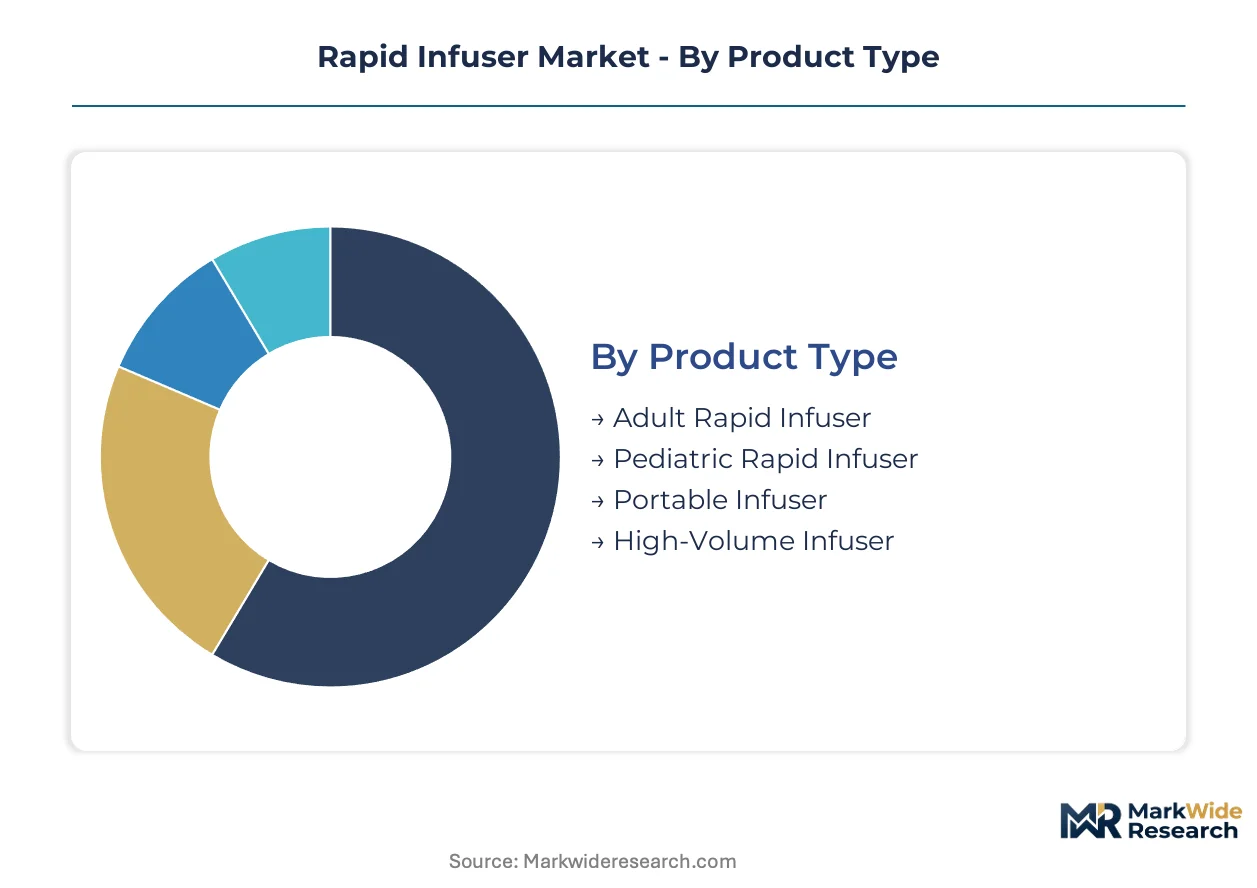
Rapid infuser procurement diverges sharply across care settings, with trauma centers prioritizing warming integration while military buyers demand battery autonomy. Technology choices here determine both patient safety outcomes and total cost of ownership calculations.
Product Type:
Hospital purchasing committees segment their budgets by patient acuity and mobility requirements, creating distinct performance tiers.
- Adult Rapid Infuser:Electromechanical platforms delivering crystalloids and blood products at rates exceeding 500 mL/minute with integrated 37-42°C warming. German Level I trauma centers drive installed base expansion through massive transfusion protocol mandates.
- Portable Infuser:Battery-operated, lightweight units with lithium-ion power architectures enabling field deployment without hospital grid dependence. EMS agencies in Australia and US air medical services represent the steepest expansion trajectory as pre-hospital warming protocols mature.
- Pediatric Rapid Infuser:Precision-calibrated flow control systems with reduced volume capacity and temperature safeguards for neonatal and pediatric populations.
- High-Volume Infuser:Pressurized delivery platforms engineered for sustained massive transfusion events exceeding 10 liters, common in combat casualty care and complex trauma surgery.
Adult rapid infusers lead volumes today; portable infusers are gaining share fastest.
End User:
Facility type dictates workflow integration depth and regulatory compliance burden.
- Hospitals:Integrated warming systems serving emergency departments, operating rooms, and intensive care units with EHR connectivity and multi-patient platform standardization. US health systems consolidate vendor relationships across affiliated trauma centers.
- Emergency Medical Services:Ground and air ambulance services requiring ruggedized housings, battery operation, and rapid deployment protocols. Australian EMS networks pilot lightweight warming units for extended transport scenarios.
- Surgical Centers:Cost-constrained ambulatory facilities where gravity-based substitutes retain share and hypothermia risk assessment drives selective warming adoption.
- Military Medical Units:Combat casualty care platforms validated by US Department of Defense trauma research, creating regulatory precedents for civilian emergency medicine technology transfer.
Hospitals dominate procurement value; military medical units show the sharpest technology adoption curve.
Technology:
Engineering architecture separates premium positioning from commodity alternatives.
- Heating Technology:Ceramic element and counter-current heat exchange systems maintaining fluid temperature within narrow therapeutic bands. FDA 510(k) clearance pathways govern electromagnetic compatibility and safety validation for US commercialization.
- Pressure Infusion:Electromechanical pressurization achieving controlled delivery rates independent of patient vascular access pressure. German hospital networks mandate this capability for Level I trauma activation protocols.
- Gravity Infusion:Passive delivery without warming capability, retaining cost-sensitive share in ambulatory surgery centers where procurement committees accept hypothermia risk trade-offs.
- Fluid Warming Systems:Modular or integrated thermal management accessories migrating from optional upgrades to core device architecture in premium system configurations.
Pressure infusion anchors premium tier positioning; heating technology integration is climbing the fastest as procurement criteria evolve.
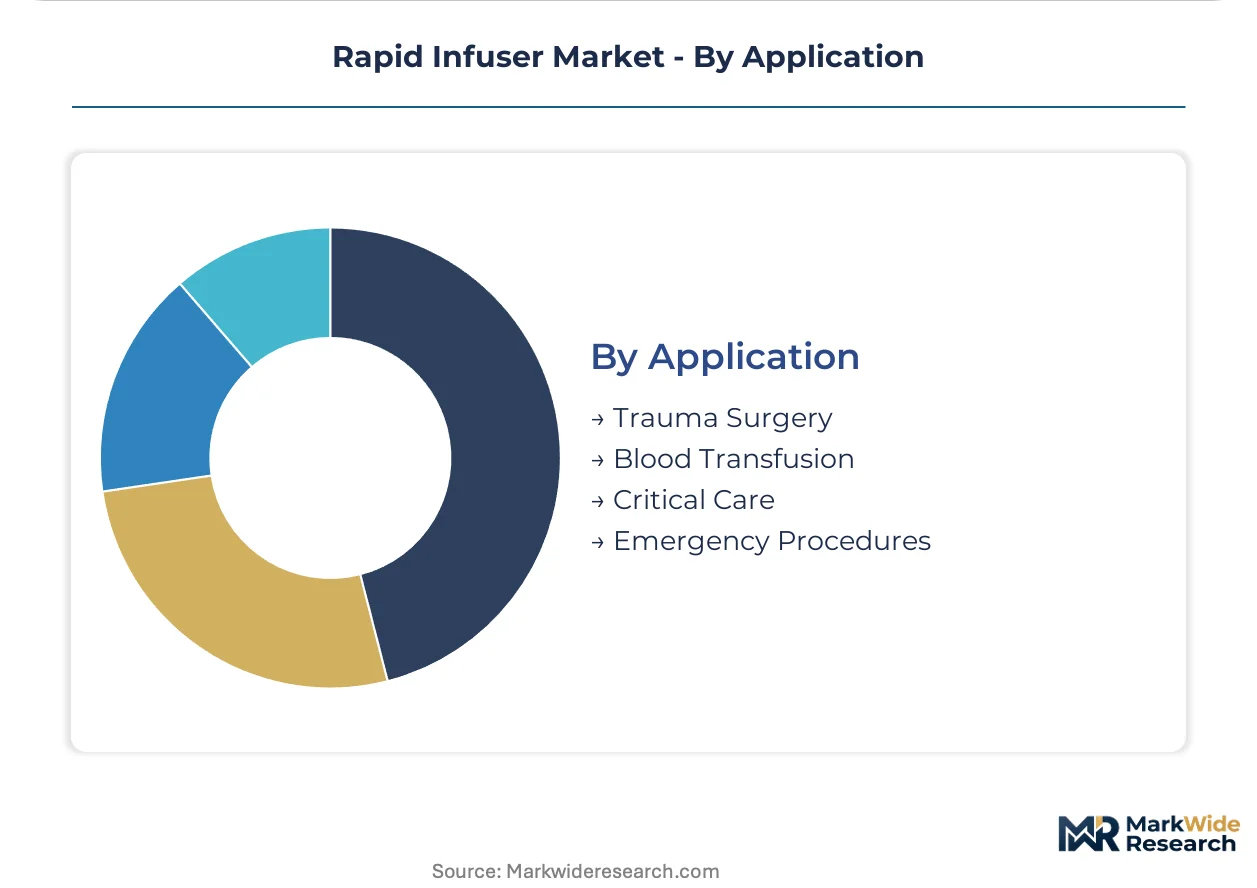
Application:
Clinical urgency and liability exposure shape pricing power across use cases.
- Trauma Surgery:Time-critical massive transfusion protocols requiring immediate warming capability to prevent coagulopathy and hypothermia-related mortality. Pressure-driven systems command premium pricing due to workflow integration demands.
- Emergency Procedures:Unstable patient resuscitation scenarios where fluid delivery speed and temperature maintenance directly impact survival metrics. US trauma centers expanding adoption of integrated warming technology drives segment growth.
- Blood Transfusion:Routine and massive transfusion protocols benefiting from integrated warming to reduce adverse event liability and improve patient outcomes documentation.
- Critical Care:Intensive care unit applications requiring sustained fluid therapy with precise thermal regulation for hemodynamically unstable patients.
Trauma surgery leads revenue concentration; emergency procedures demonstrate the most rapid protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent concentrates in legacy anesthesia equipment clusters across Germany, the United States, and Japan, anchoring regional competitive advantages in pressurized delivery platform development.
United States
Trauma centers in Texas, Florida, and California expand pressure-driven fluid warming systems to reduce hypothermia-related complications in emergency surgery. FDA 510(k) clearance pathways for Class II medical devices shape product development timelines and commercialization strategies. The Greater Boston medical device corridor sustains engineering depth in electromechanical pressurization systems.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia prioritize integrated warming technology for massive transfusion protocols. EU MDR clinical evidence standards enforce stricter post-market surveillance requirements for CE marking of active therapeutic devices. The Baden-Württemberg precision manufacturing belt supplies ceramic heating elements and pressure sensors for premium system configurations.
Japan
Academic medical centers in Tokyo and Osaka adopt multi-patient platforms standardizing across emergency, operating room, and intensive care environments. PMDA regulatory frameworks parallel FDA approval structures for electromechanical therapeutic devices. The Kansai biomedical engineering cluster develops compact thermal regulation systems for portable applications.
Australia
Ground and air ambulance services in New South Wales and Victoria pilot battery-operated, lightweight warming infusers for extended transport scenarios. TGA approval frameworks maintain parallel pathways to FDA and EU regulatory benchmarks. The Melbourne medical technology hub prototypes ruggedized housings for pre-hospital EMS deployment.
United Kingdom
NHS trauma networks in London and the Midlands consolidate vendor relationships around multi-patient platforms serving emergency departments. MHRA post-Brexit regulatory alignment with EU MDR standards extends CE marking timelines for UK commercialization. The Cambridge medical device corridor advances integrated data connectivity with electronic health record platforms.
Rapid Infuser Market Competitive Environment
Top-tier vendors anchor premium pressure-driven warming systems, while mid-tier specialists occupy portable battery-powered segments and commodity gravity-based alternatives. The vendor base stratifies across three performance tiers differentiated by warming integration depth, power architecture, and regulatory clearance breadth. Engineering-intensive archetypes concentrate in legacy anesthesia equipment heritage, emergency care channel control, and military-trauma ruggedization. Competitive moves center on multi-patient platform standardization and pre-hospital EMS channel penetration.
Within the emergency care channel control archetype, ZOLL Medical Corporation and Stryker Corporation exemplify positioning built on acute care workflow integration. Smiths Medical anchors the legacy anesthesia equipment heritage tier, drawing on critical care engineering depth. Belmont Medical Technologies occupies the military-trauma ruggedization vector, reflecting combat casualty care protocol validation.
| Leading Market Players |
|---|
| 3M Health Care |
| Smiths Medical |
| ZOLL Medical Corporation |
| Belmont Medical Technologies |
| ICU Medical |
| Stryker Corporation |
| Teleflex Incorporated |
| Baxter International |
| Fresenius Kabi |
| Others |
Value Chain & Pricing Dynamics
Hospital purchasing committees in Germany and the United States concentrate procurement authority for rapid infusers, driving a contract-based pricing model where capital equipment discounts trade against multi-year disposable and service bundles. This buyer concentration rewards vendors who integrate warming technology with recurring revenue streams rather than standalone hardware sales.
Pricing Analysis
Bundled service contracts now dominate rapid infuser transactions, separating premium pressure-driven warming platforms from unbundled gravity-based alternatives. Price differentiation rests on FDA 510(k) clearance tier and warming performance certification, with German Level I trauma centers showing lowest price sensitivity due to protocol mandates. Cost compression in the portable segment is intensifying as battery chemistry advances commoditize field-deployable power architectures. Ambulatory surgery centers remain most price-sensitive, accepting hypothermia risk trade-offs to avoid warming premiums.
Supply Chain Analysis
Reverse-logistics flows for refurbished pressure sensors and remanufactured ceramic heating elements are expanding as US health systems extend equipment life cycles under total cost of ownership frameworks. Component manufacturing concentrates in Germany, Japan, and South Korea, with the Baden-Württemberg precision belt supplying thermal regulation hardware. Production draws from specialized ceramic substrates, lithium-ion cells, and medical-grade pressure transducers. Single-source vulnerability in East Asian contract manufacturers for precision sensors creates geopolitical exposure. Distribution runs through hospital GPOs and military procurement channels with diverging service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rapid infuser market functions as a regulatory compounder, with EU MDR clinical evidence standards and FDA 510(k) pathway streamlining together accelerating premium system adoption while extending clearance timelines for novel entrants.
For Market Incumbents: Extend platform standardization across emergency, operating room, and intensive care environments to lock in multi-patient contracts before portable specialists capture pre-hospital share. Invest in backward integration into ceramic heating element production to defend margins against East Asian supply concentration. Deepen EHR connectivity partnerships to create switching costs that offset capital equipment discounting pressure from purchasing committees. For New Entrants and Emerging Players: FDA 510(k) pathway streamlining in the United States opens a window for predicate-equivalent pressure-assisted platforms targeting trauma centers with faster commercialization cycles than EU MDR routes permit. Target Australian EMS networks piloting battery-operated warming units for extended transport scenarios, the most penetrable geography for field-deployable architectures. Pursue dual-use military-civilian technology transfer partnerships to leverage US Department of Defense trauma research validation as regulatory precedent. For Investors and Strategic Acquirers: Emergency care channel consolidators are the most active acquirer in this space, seeking portable warming capabilities to complement fixed-hospital installed bases. The long-term viability window favors vendors who bridge pre-hospital and in-hospital workflows under unified data platforms. Monitor German hospital network massive transfusion protocol standardization as the inflection indicator for warming technology becoming non-discretionary procurement criteria.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Expedited clearance timelines accelerate commercialization for predicate-equivalent pressure-assisted platforms in US trauma centers. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend timelines but create regulatory moats for warming systems with post-market surveillance data. |
| Hospital System Partnership | Multi-patient platform standardization across emergency, OR, and ICU environments locks in recurring disposable revenue streams. |
| Software Companion Development | EHR integration enables real-time transfusion documentation and adverse event tracking that differentiates premium tier positioning. |
| Reimbursement Strategy | Coding alignment with massive transfusion protocols in German and US hospital networks converts clinical guidelines into procurement mandates. |
Study Parameters
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation against FDA 510(k) filings, EU MDR submission databases, and hospital procurement records; and customs data on ceramic heating element trade flows — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned clinicians in Level I trauma centers, EMS agency procurement officers, and military medical logistics specialists. Secondary sources included TGA approval registers, German hospital network protocol documentation, and US Department of Defense trauma research publications.
Historical shipment data cross-referenced against panel input from trauma center administrators and anesthesia equipment specialists anchored the analytical framework across the analysis window. Segmentation dimensions modeled included product mobility tier, end-user facility type, warming technology integration depth, and regional regulatory cluster. CAGRs were derived from installed base expansion rates weighted by protocol standardization timelines. Forecast inputs incorporated battery energy density improvement curves and EU MDR enforcement phase-in schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under supply chain disruption scenarios affecting East Asian sensor manufacturers or abrupt shifts in FDA predicate device scrutiny. Practitioners should monitor German massive transfusion protocol adoption rates and lithium-ion cell supply contract announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Tracheobronchial Stent Grafts Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Biological Microscope Market
Medical Devices
Pipetting Systems Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
Bone Cement Mixers Market
Medical Devices
Surgical AR Systems Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Latin America Implantable Medical Devices Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Breathing Circuits Market
Medical Devices
Batteries for Skin Patches Market