
 Continuous Cardiac Monitoring Systems Market | 2026-2036
Continuous Cardiac Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Cardiac Monitoring Systems Market Analytics
The EU Medical Device Regulation is pivoting procurement standards toward continuous clinical validation and post-market surveillance. Medtronic plc leverages its integrated care networks to sustain long-term device placement contracts across European health systems. Abbott Laboratories anchors its competitive position through catheter-based monitoring platforms that span hospital and ambulatory settings.
Continuous cardiac monitoring systems encompass wearable, implantable, and external devices that capture electrophysiological signals—typically sampling ECG at 250–1000 Hz or photoplethysmography at 100 Hz—for real-time or retrospective arrhythmia detection and hemodynamic assessment. Their primary purpose is to bridge diagnostic gaps between intermittent clinical encounters and episodic cardiac events, enabling earlier intervention and reduced emergency utilization. Wearable devices and mobile health solutions represent the fastest-expanding demand pools, while implantable monitors command premium pricing due to invasive placement protocols and extended multi-year monitoring horizons. ECG-based technology retains clinical authority in diagnostic workflows, though PPG modalities are gaining traction in consumer-accessible screening applications.
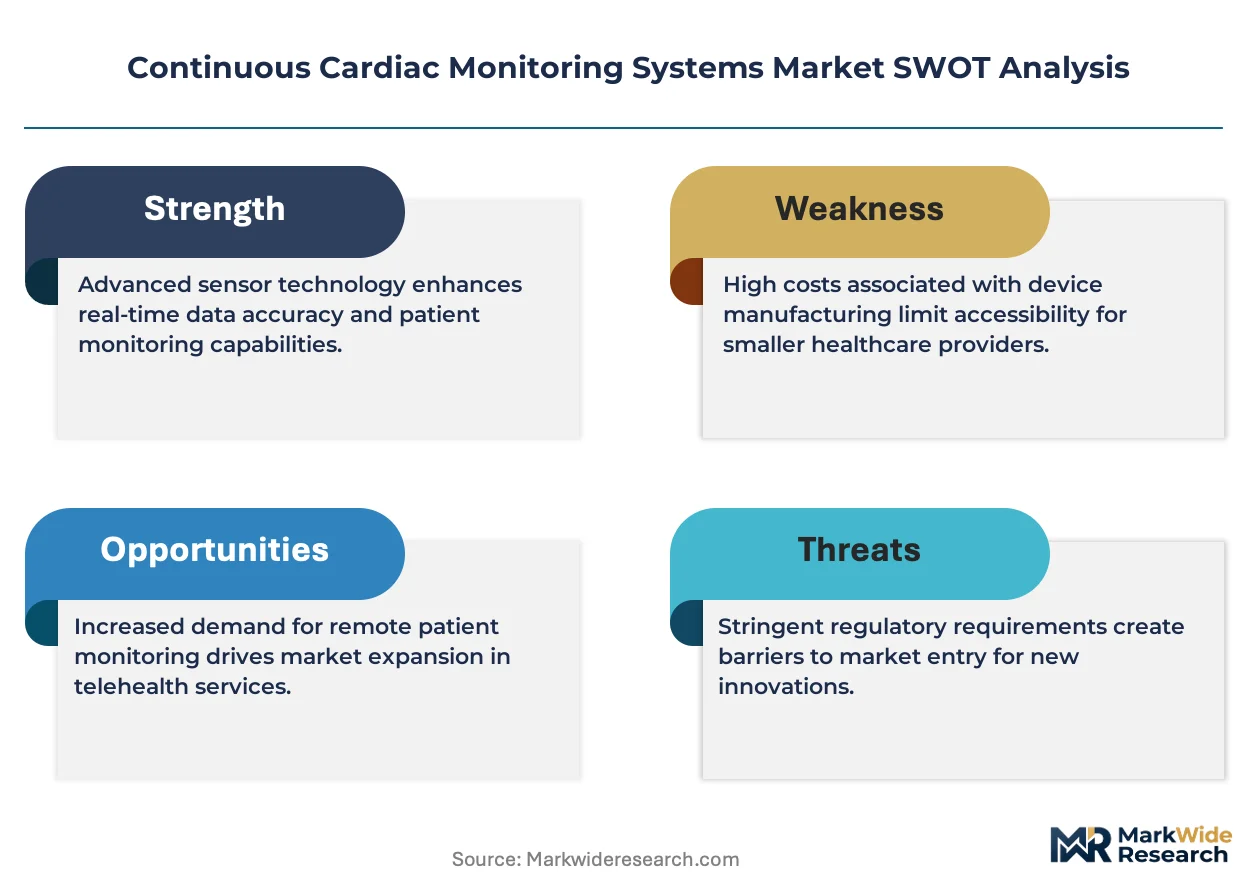
The FDA oversees premarket notification and breakthrough device pathways for novel cardiac sensors, while the EU MDR imposes stricter clinical evidence requirements for Class IIa and above devices. HIPAA in the United States and GDPR in Europe constrain cloud-based data architectures, shaping vendor investment in on-premise and hybrid installation configurations. Stakeholders must weigh regulatory compliance burdens against the scalability advantages of cloud-native analytics platforms as care delivery fragments across traditional and decentralized settings.
Market Dynamics
Hospital systems are consolidating vendor relationships around integrated cardiac monitoring platforms that span acute and ambulatory settings, compressing procurement cycles and favoring suppliers with full-stack capabilities.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway accelerates market entry for AI-enabled arrhythmia detection algorithms, reducing time-to-revenue for novel sensor developers.
- Medicare Reimbursement Expansion:Remote cardiac monitoring CPT codes now cover extended ambulatory surveillance, driving clinical adoption across US accountable care organizations.
- Photoplethysmography Miniaturization:Advances in optical sensor fabrication enable consumer-grade PPG devices to achieve diagnostic-grade signal fidelity for atrial fibrillation screening.
Market Restraints
- EU MDR Clinical Evidence Burden:Class IIa and above devices face extended post-market surveillance mandates, inflating regulatory compliance costs for smaller manufacturers.
- Semiconductor Supply Concentration:Discrete analog front-end components for ECG acquisition concentrate among Taiwanese and South Korean foundries, creating input vulnerability.
- Rechargeable Battery Degradation:Implantable loop recorders face technical limitations in power management that constrain multi-year monitoring horizons without replacement.
Strategic Opportunities
- India Preventive Cardiology Gap:Underpenetrated rural diagnostics infrastructure creates white space for low-cost wearable ECG devices paired with telemedicine networks.
- Machine Learning-ECG Convergence:Deep learning architectures trained on million-scale ECG databases enable automated left ventricular dysfunction detection from single-lead signals.
- Direct-to-Employer Distribution:Self-insured corporations are emerging as procurement channels for workforce cardiovascular screening programs, bypassing traditional hospital sales cycles.
Industry Challenges
- Electrophysiology Talent Scarcity:Interpretation of complex ambulatory ECG recordings requires specialized cardiologist training that health systems struggle to recruit.
- Legacy EMR Integration Friction:Proprietary data formats from implantable devices create interoperability barriers with Epic and Cerner installations, delaying clinical workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Cardiac Monitoring Systems Market |
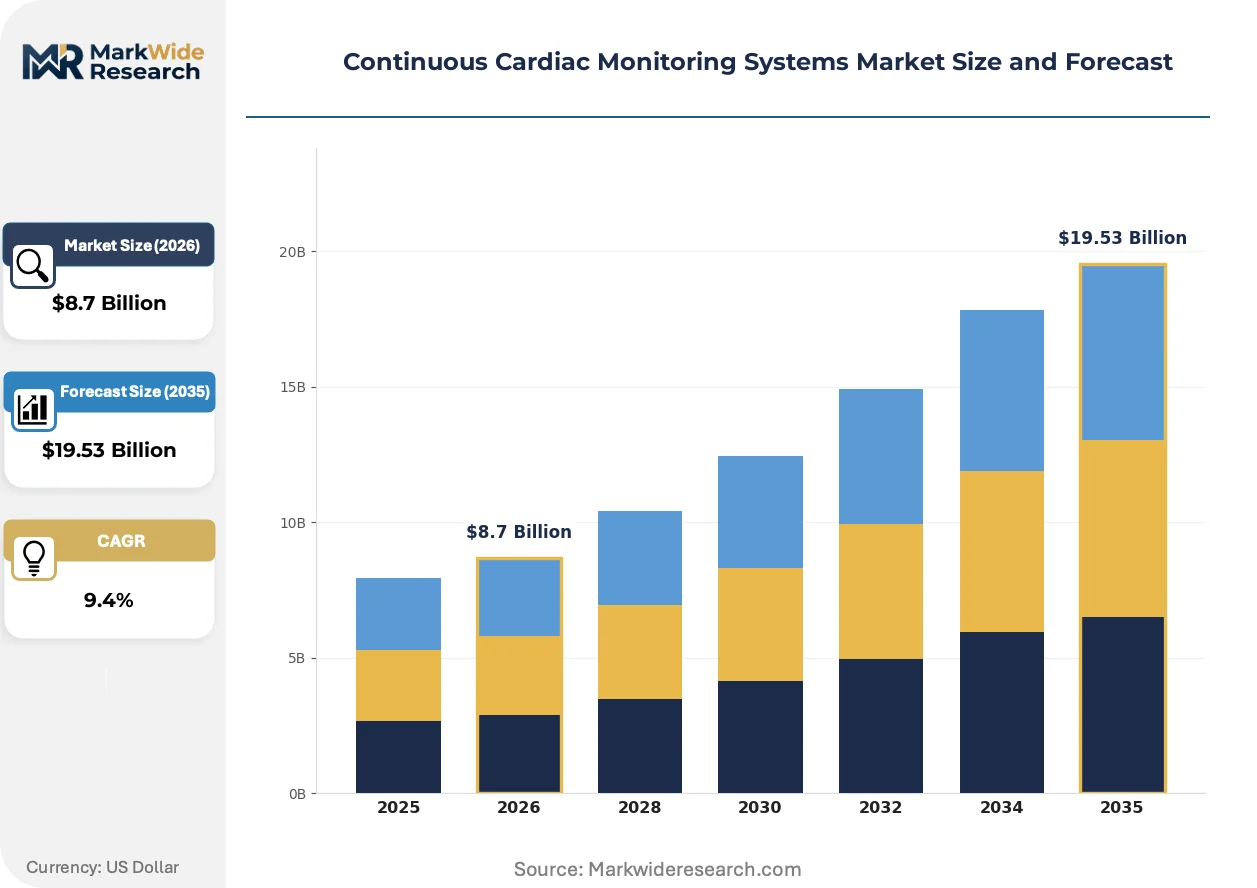
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implantable Monitors, Handheld Monitors, Smartphone Applications Technology: ECG, PPG, Holter Monitoring, Mobile Health Solutions End User: Hospitals, Home Care, Cardiology Clinics, Remote Patient Monitoring Installation: On-premise, Cloud-based, Hybrid Solutions, Standalone Systems |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, GE Healthcare, Koninklijke Philips N.V., Edwards Lifesciences, Abbott Laboratories, Canon Medical Systems Corporation, BIOTRONIK, iRhythm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Cardiac Monitoring Systems Market Evolving Landscape
Cardiac monitoring is pivoting from episodic hospital-based diagnostics toward continuous, algorithm-driven surveillance that embeds predictive analytics into routine care workflows.
Multi-lead ECG patches are integrating solid-state sensor arrays with onboard edge computing to enable real-time arrhythmia classification without cloud dependency. Hospital systems in Germany and the Netherlands are piloting these devices for post-discharge monitoring of heart failure patients. The technology is integrating diagnostic authority into wearable form factors previously limited to consumer wellness applications.
The EU AI Act's risk classification framework is imposing conformity assessment requirements on machine learning components embedded in Class IIa cardiac devices. Manufacturers must now document algorithmic performance across demographic subgroups prior to CE marking. European notified bodies are prioritizing review capacity for cardiovascular AI applications, creating regulatory queue advantages for early filers.
US health systems are unbundling device procurement from professional interpretation services, creating separate contracting lanes for hardware, software analytics, and clinical reading. This disintermediation favors specialized cardiac monitoring service organizations that aggregate interpretation across multiple hospital networks. The shift is most visible in Texas and Florida, where independent diagnostic testing facilities are capturing ambulatory ECG volume from integrated delivery networks.
Continuous Cardiac Monitoring Systems Market Segmentation
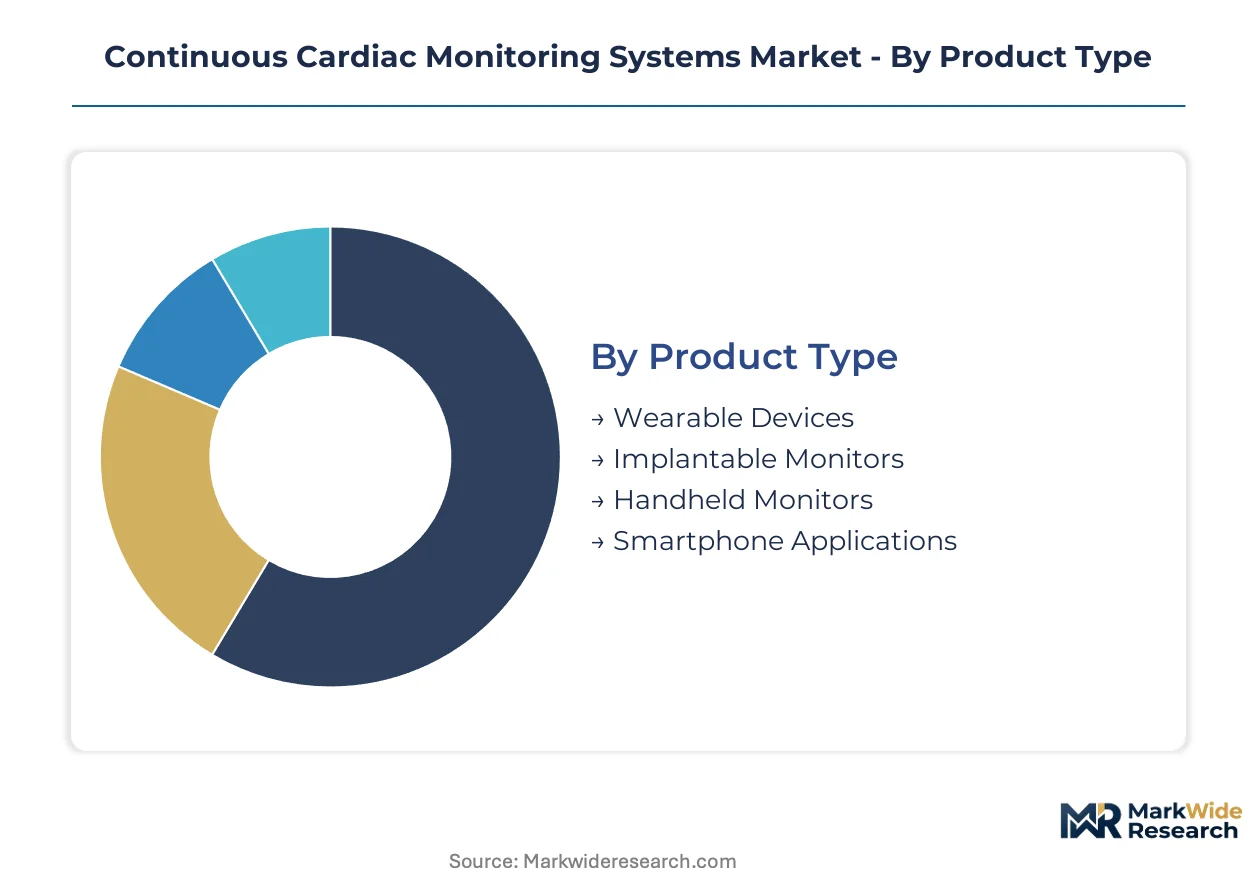
Continuous cardiac monitoring systems fragment across four distinct dimensions that shape procurement patterns, regulatory pathways, and margin structures. Each segmentation axis carries unique certification burdens and customer concentration profiles that determine vendor go-to-market strategy.
Product Type:
FDA premarket notification applies to wearable and handheld categories, while implantable monitors trigger PMA pathways and EU MDR Class III designation.
- Wearable Devices:Multi-lead ECG patches and wrist-worn optical sensors sample at 250–1000 Hz for ambulatory arrhythmia detection. Demand concentrates in US accountable care organizations seeking to reduce heart failure readmissions under CMS penalty programs. FDA breakthrough designation accelerates approvals for AI-enabled form factors.
- Implantable Monitors:Subcutaneous loop recorders capture continuous electrophysiological data across multi-year horizons via proprietary telemetry protocols. German and Dutch hospital systems anchor European demand for post-discharge heart failure surveillance. Invasive placement requirements sustain premium pricing tiers.
- Handheld Monitors:Portable single-lead ECG devices for point-of-care screening in resource-limited settings.
- Smartphone Applications:Consumer-accessible PPG algorithms for atrial fibrillation screening with diagnostic-grade claims.
Leading the category by volume: Wearable Devices. Growing fastest: Smartphone Applications.
Technology:
Signal acquisition methods diverge sharply in clinical authority versus consumer accessibility, with reimbursement eligibility hinging on diagnostic specificity.
- ECG:Surface electrode arrays measuring electrical depolarization patterns remain the gold standard for arrhythmia classification in cardiology workflows. US hospital systems consolidate procurement around ECG-integrated platforms that span acute and ambulatory settings. CMS reimbursement codes favor diagnostic-grade electrocardiography over optical alternatives.
- PPG:Photoplethysmography leverages green LED and infrared optical sensors at 100 Hz sampling for pulse waveform analysis. Miniaturization advances enable diagnostic-grade signal fidelity in consumer form factors. Direct-to-employer wellness programs drive volume for screening applications.
- Holter Monitoring:Extended 24–48 hour ambulatory ECG recording with retrospective analysis.
- Mobile Health Solutions:Cellular-connected platforms enabling real-time transmission to centralized monitoring centers.
ECG commands revenue concentration. PPG climbs the fastest as consumer screening expands.
End User:
Procurement authority shifts from centralized hospital supply chains toward fragmented home care and employer channels, altering sales cycle dynamics.
- Hospitals:Integrated delivery networks in Texas and Florida unbundle device procurement from interpretation services, creating separate contracting lanes. Epic and Cerner EMR integration requirements dominate vendor selection criteria.
- Home Care:Post-acute monitoring for discharged heart failure patients drives demand for cellular-connected patch devices.
- Cardiology Clinics:Independent diagnostic testing facilities capture ambulatory ECG volume through specialized interpretation services.
- Remote Patient Monitoring:Medicare reimbursement expansion for CPT codes covering extended surveillance accelerates clinical adoption.
Hospitals retain procurement value concentration. Remote Patient Monitoring gains share fastest as reimbursement frameworks mature.
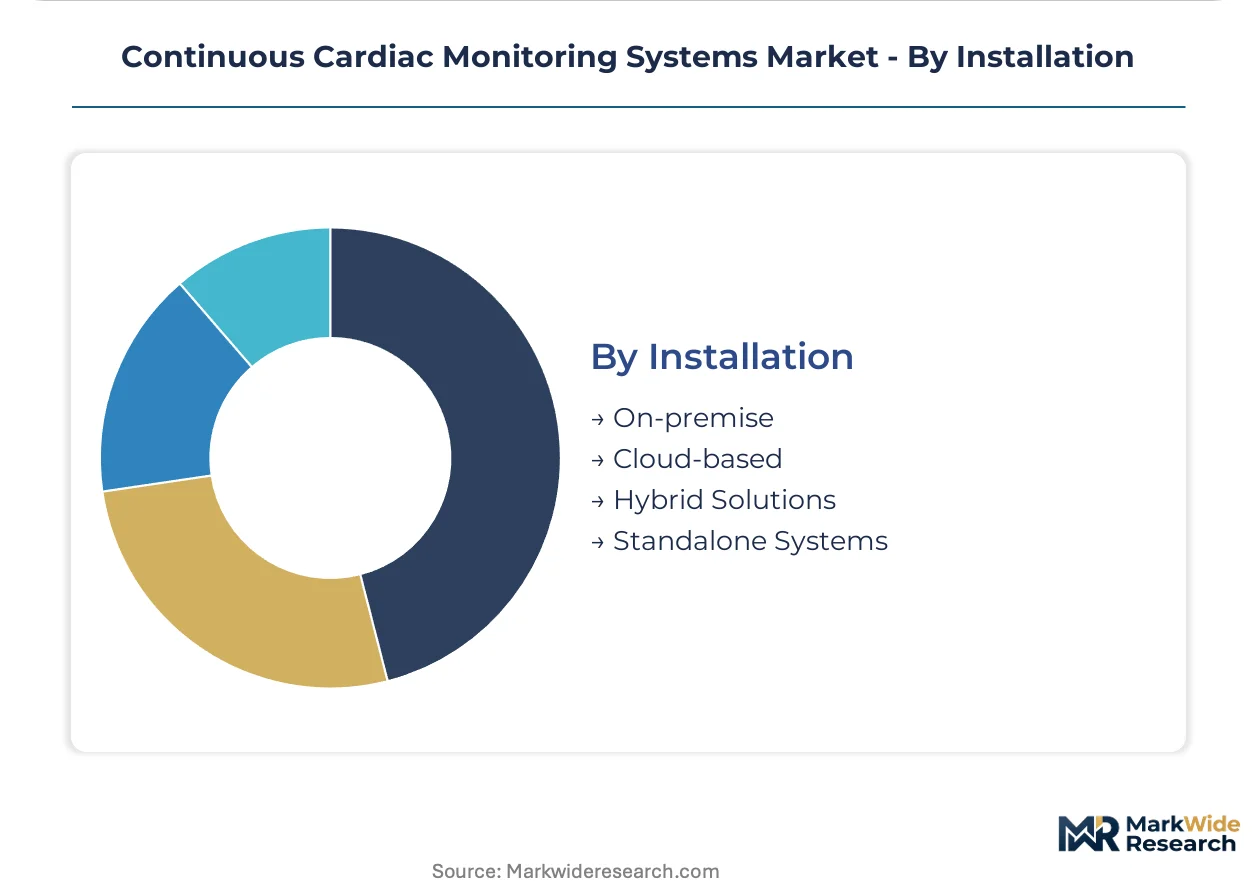
Installation:
Data architecture choices reflect tension between cloud scalability and HIPAA/GDPR compliance burdens, with hybrid configurations emerging as dominant design pattern.
- On-premise:Local server deployments satisfy stringent data residency requirements in German and Swiss health systems. Higher capital expenditure burdens limit adoption to large integrated networks with dedicated IT infrastructure.
- Cloud-based:Native SaaS analytics platforms enable rapid scaling across decentralized care delivery. GDPR Article 44 transfer restrictions and HIPAA security rule compliance inflate vendor development costs.
- Hybrid Solutions:Edge computing for real-time arrhythmia classification with cloud aggregation for longitudinal analytics.
- Standalone Systems:Disconnected devices for environments with limited connectivity infrastructure.
Hybrid Solutions lead adoption trajectory. Cloud-based architectures face steepest expansion constraints from regulatory friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in the United States, Germany, and Japan, while clinical consumption spreads across aging populations in Western Europe and North America. Taiwan and South Korean foundries supply critical analog front-end semiconductors, creating geographic dependency in the upstream supply chain.
United States
Medicare reimbursement expansion for remote cardiac monitoring CPT codes drives hospital procurement of ambulatory ECG platforms. FDA breakthrough device designation accelerates approvals for AI-enabled arrhythmia detection algorithms. Minneapolis anchors Medtronic's integrated care network operations, while Abbott Laboratories maintains catheter-based monitoring development in Illinois.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia pilot multi-lead ECG patches for post-discharge heart failure surveillance under statutory health insurance frameworks. EU MDR Class III designation for implantable monitors imposes extended clinical evidence requirements on domestic manufacturers. Berlin hosts BIOTRONIK's European regulatory affairs and post-market surveillance operations.
Netherlands
Integrated care networks in Amsterdam and Rotterdam deploy cellular-connected patch devices for remote patient monitoring programs. GDPR Article 44 transfer restrictions shape vendor investment in hybrid data architectures combining edge computing with localized analytics. Eindhoven's semiconductor ecosystem supports optical sensor fabrication for next-generation PPG devices.
Japan
PMDA regulatory pathways for novel cardiac sensors align with global harmonization initiatives, reducing time-to-market for multinational device developers. METI funding programs accelerate domestic production of medical-grade semiconductors to reduce import dependency. Tokyo and Osaka medical centers lead adoption of implantable loop recorders for extended arrhythmia surveillance.
India
Underpenetrated rural diagnostics infrastructure creates demand for low-cost wearable ECG devices paired with telemedicine networks. CDSCO medical device regulations are converging toward international standards, streamlining import pathways for multinational manufacturers. Karnataka's Bangalore cluster hosts emerging domestic device developers targeting preventive cardiology gaps in tier-2 and tier-3 cities.
Continuous Cardiac Monitoring Systems Market Competitive Landscape
The competitive structure tilts toward diversified medtech conglomerates with integrated care network relationships. Hospital procurement consolidation favors suppliers spanning acute and ambulatory settings, compressing vendor shortlists to full-stack platform providers. Three archetypes dominate: implantable device specialists with proprietary telemetry protocols, diversified cardiovascular conglomerates with catheter-based portfolios, and digital health pure-plays with AI-native analytics. Competitive moves center on unbundling device procurement from interpretation services and securing long-term placement contracts through integrated delivery network partnerships.
Among diversified cardiovascular conglomerates, Medtronic plc and Abbott Laboratories exemplify the integrated platform archetype, leveraging hospital system relationships across multiple continents. Boston Scientific Corporation occupies a position within the interventional cardiology specialist tier, while iRhythm Technologies represents the digital-native service model unbundling hardware from clinical interpretation. GE Healthcare and Koninklijke Philips N.V. anchor the imaging-to-monitoring convergence strategy, extending diagnostic equipment relationships into continuous surveillance contracts.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Edwards Lifesciences |
| Abbott Laboratories |
| Canon Medical Systems Corporation |
| BIOTRONIK |
| iRhythm Technologies |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up cardiac monitoring specialists have consolidated interpretation service platforms across US hospital networks, tightening pricing discipline on hardware vendors while amplifying volume leverage over Taiwanese foundries supplying analog front-end semiconductors.
Pricing Analysis
Margin tightening in implantable monitors reflects EU MDR Class III certification burdens and extended PMA timelines that inflate development amortization. Three-tier pricing structure across premium implantable, standard wearable, and economy handheld levels separates FDA breakthrough-designated AI devices from basic Holter monitors. Cost compression in consumer-facing PPG wearables accelerates because smartphone application developers bypass traditional hospital procurement cycles. Cardiology clinics exhibit highest price sensitivity due to unbundled contracting, while integrated delivery networks leverage long-term placement contracts for lowest net pricing.
Supply Chain Analysis
FDA and EU MDR quality system certifications gate supplier eligibility for ECG electrode arrays and implantable telemetry modules, constraining vendor pools to ISO 13485-registered manufacturers. Discrete analog front-end components concentrate among Taiwanese and South Korean foundries, while optical sensor fabrication clusters in Eindhoven and Japanese precision optics hubs. Semiconductor supply concentration creates single-source vulnerability for multi-channel ECG acquisition chips. Distribution runs through diversified medtech conglomerates with catheter-based portfolios and direct-to-hospital contracting arms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous cardiac monitoring is transitioning from intermittent diagnostic encounters toward algorithm-driven surveillance, with AI-enabled arrhythmia detection displacing retrospective Holter analysis in clinical workflows.
For Market Incumbents: Hedge against unbundling pressure by securing integrated delivery network placement contracts spanning acute and ambulatory settings. Deepen backward integration into proprietary telemetry protocols for implantable loop recorders. Invest in edge computing architectures that reduce cloud dependency amid GDPR Article 44 transfer restrictions. For New Entrants and Emerging Players: FDA breakthrough device designation in the United States opens a window for AI-native developers to compress time-to-revenue against established PMA pathways. Target underpenetrated rural diagnostics infrastructure in India with low-cost wearable ECG devices paired with telemedicine networks. Pursue direct-to-employer distribution channels for workforce cardiovascular screening programs. For Investors and Strategic Acquirers: Distressed-cycle entries favor digital health pure-plays with AI-native analytics capabilities in European markets facing EU MDR compliance cost inflation. Long-term viability hinges on reimbursement strategy execution across Medicare CPT code expansions. Monitor FDA breakthrough designation grant velocity as inflection indicator for algorithm-enabled market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates market entry for AI-enabled arrhythmia detection algorithms from developers like iRhythm. |
| EU MDR Class III Certification | Imposes extended clinical evidence requirements that inflate compliance costs for implantable monitor manufacturers. |
| Hospital System Partnership | Medtronic leverages integrated care networks to sustain long-term device placement contracts across European health systems. |
| Software Companion Development | Abbott anchors competitive position through catheter-based monitoring platforms spanning hospital and ambulatory settings. |
| Reimbursement Strategy | Medicare CPT code expansion for remote cardiac monitoring drives clinical adoption across US accountable care organizations. |
Research Methodology
Multi-period observation of FDA breakthrough designation grants, EU MDR notified body queue times, and Medicare CPT code reimbursement expansions anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at diversified cardiovascular conglomerates. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR CE marking databases, CMS Medicare claims data, and hospital procurement contract repositories. Bottom-up demand modeling triangulated against top-down market sizing across device categories.
Segment-weighting approaches distributed revenue projections across product type, technology, end user, and installation configuration dimensions. CAGRs derived from fitted growth curves incorporating reimbursement policy trajectories, regulatory approval velocity, and semiconductor supply capacity constraints. Forecast inputs included AI algorithm validation timelines and cloud data architecture adoption rates.
The model assumes a particular technology adoption path; alternative pathways for photoplethysmography miniaturization achieving diagnostic-grade ECG equivalence would alter the outlook. Forecasts reflect assumptions about FDA breakthrough pathway utilization rates and EU MDR notified body capacity expansion. A model refresh is warranted upon material change in Medicare remote monitoring reimbursement policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Global Aortic Valve Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
US Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Global Vascular Graft Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Cardiovascular Prosthetic Devices Market
Cardiovascular Devices
Global Coronary Stent Market