
 Implantable Infusion Pumps Market | 2026-2036
Implantable Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Infusion Pumps Market Outlook
Programmable precision tiers is reorganizing competitive dynamics across implantable infusion pumps. Medtronic plc leverages deep neuromodulation expertise to anchor its position in intrathecal delivery systems. Boston Scientific Corporation differentiates through targeted pain management portfolios that integrate with physician workflow platforms. Fresenius Kabi AG sustains manufacturing scale across European and Asian production nodes for oncology infusion applications.
Implantable infusion pumps are sealed, biocompatible drug delivery devices engineered with titanium or polymer housings, peristaltic or piston-driven mechanisms, and programmable flow rates typically spanning 0.1 to 1000 microliters per hour for precise chronic administration. These systems serve diabetes management, cancer treatment, and chronic pain management by maintaining therapeutic plasma concentrations without repeated percutaneous access. Smart pumps and programmable pumps command premium positioning as connectivity features and dose-error reduction software attract hospital procurement committees seeking liability mitigation. Continuous delivery systems occupy mature volume share while bolus delivery systems gain traction in patient-controlled analgesia protocols where on-demand dosing flexibility reduces opioid exposure.
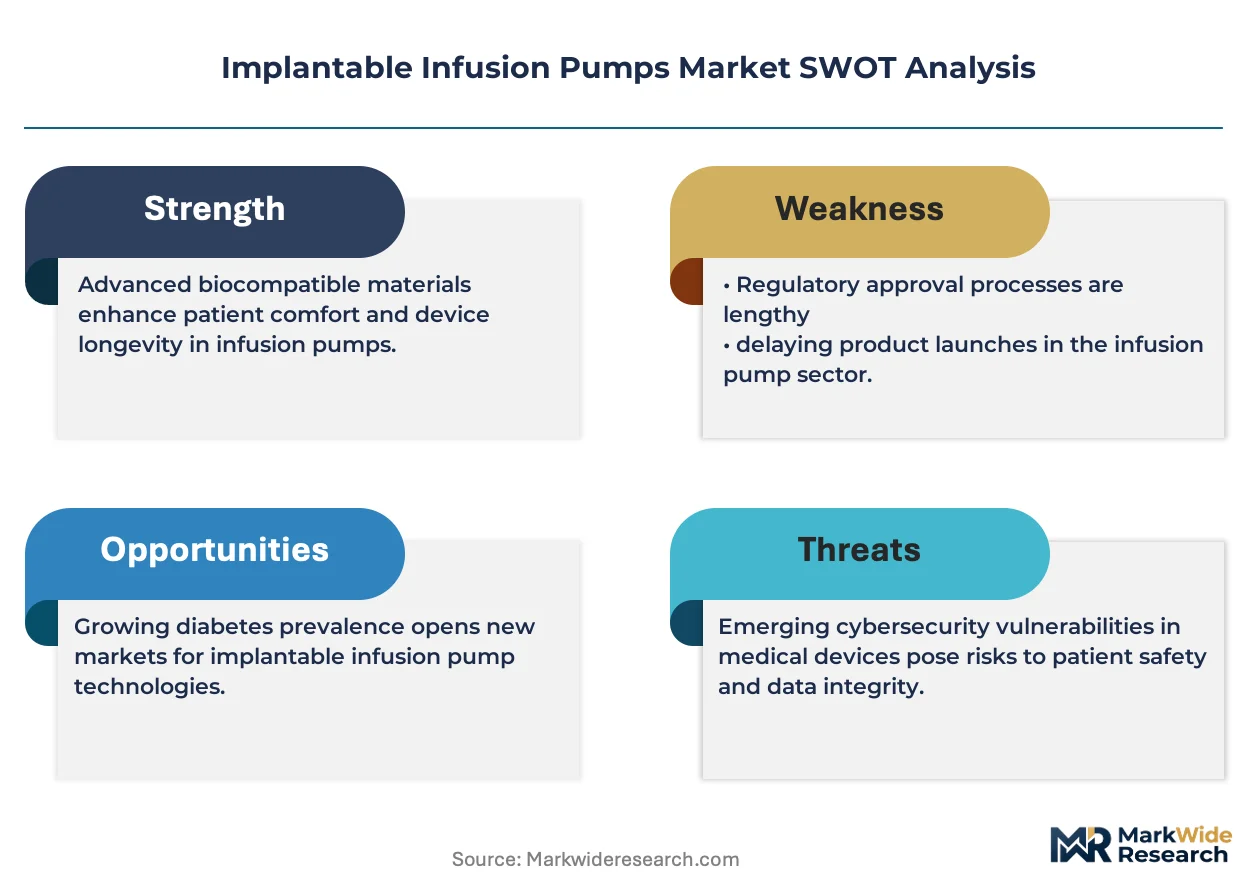
FDA premarket notification requirements, EU MDR technical documentation mandates, and ISO 13485 quality management standards collectively elevate barriers for new entrants while compelling incumbents to absorb compliance costs into pricing architectures. Japan's PMDA and China's NMPA impose additional clinical evidence thresholds that extend registration timelines for programmable architectures. Stakeholders must monitor evolving cybersecurity guidance from FDA and IEC as connected pump ecosystems expand attack surfaces requiring proactive risk management investment.
Market Dynamics
Programmable precision tiers are reorganizing competitive dynamics across implantable infusion pumps as connectivity features and dose-error reduction software attract hospital procurement committees seeking liability mitigation. This structural force is compressing margins for basic continuous delivery systems while elevating premium positioning for smart pump architectures.
Growth Catalysts
- EU MDR conformity requirements:Tightening safety benchmarks for programmable architectures are filtering out marginal competitors and consolidating procurement toward certified manufacturers with established technical documentation capabilities.
- Homecare settings:Patient preference for alternatives to prolonged hospitalization is expanding pump adoption outside acute care facilities, creating new service revenue streams for device vendors.
- Titanium housings:Biocompatibility and corrosion resistance properties are extending device longevity and reducing revision surgery rates, improving lifetime value calculations for payers.
Market Restraints
- Piston-driven mechanism precision:Manufacturing tolerance requirements for microliter-per-hour accuracy elevate production costs and yield losses, constraining price competitiveness against simpler peristaltic alternatives.
- Swiss and German component suppliers:Concentration of precision machining capacity in Alpine and Central European manufacturing clusters creates geographic supply risk and extended lead times for North American and Asian device assemblers.
- ISO 13485 quality management standards:Certification maintenance costs and audit frequency compel smaller entrants to absorb compliance expenditures that scale inefficiently at low production volumes.
Strategic Opportunities
- Brazil's ANVISA regulatory pathway:Underpenetrated chronic pain management infrastructure and expanding private insurance coverage create first-mover advantages for intrathecal delivery system entrants.
- Oncology bolus protocols:Patient-controlled analgesia applications in chemotherapy administration represent emerging demand for on-demand dosing flexibility that reduces systemic opioid exposure.
- Cybersecurity guidance convergence:Proactive FDA and IEC risk management investment requirements are creating service revenue opportunities for third-party verification and post-market surveillance providers.
Industry Challenges
- Embedded software validation:FDA premarket notification timelines for programmable flow rate algorithms extend development cycles and compress competitive windows for feature launches.
- Legacy hospital IT integration:Dose-error reduction software deployment requires costly interoperability testing against fragmented electronic health record systems, delaying connected pump rollout schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Infusion Pumps Market |
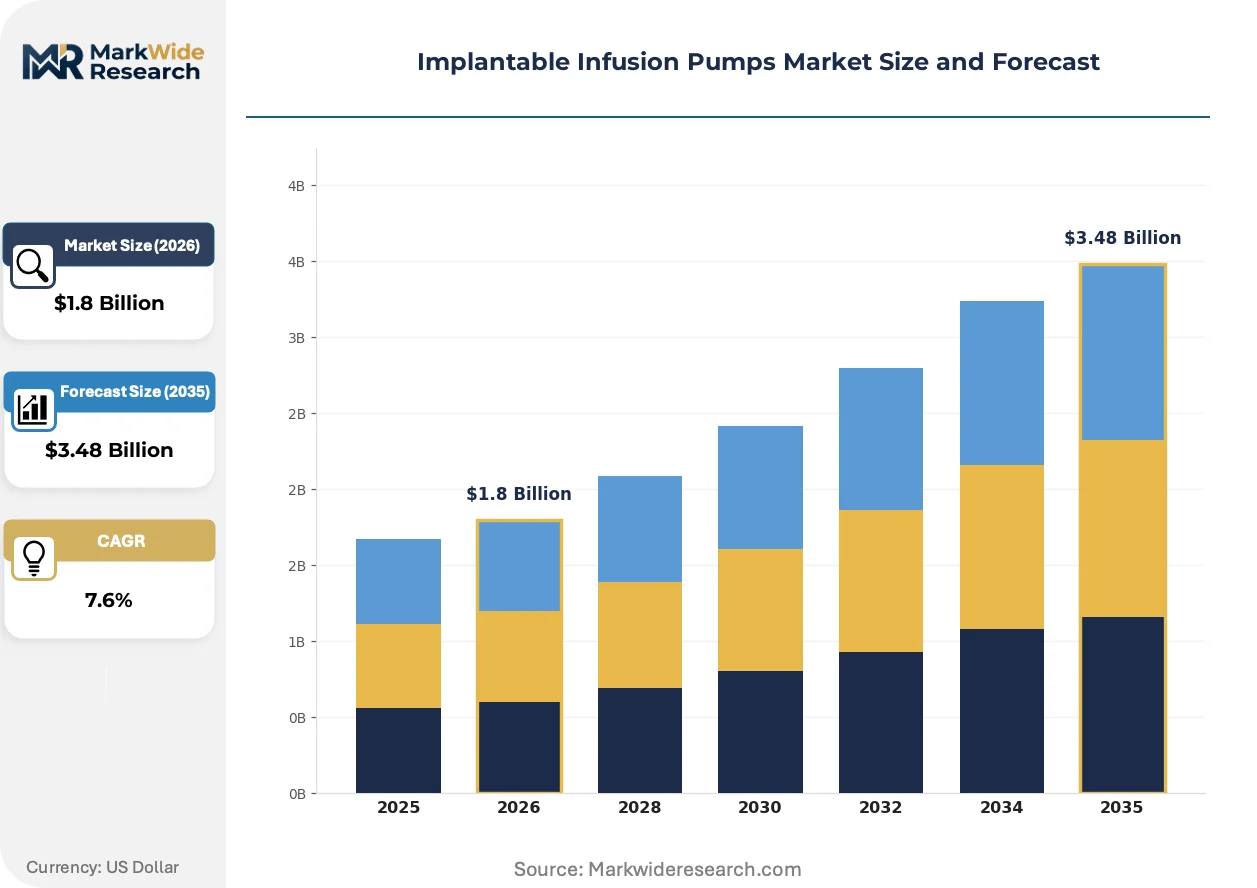
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Pain Management Pumps, Chemotherapy Pumps, Antibiotic Pumps Application: Diabetes Management, Cancer Treatment, Chronic Pain Management, Anesthesia End User: Hospitals, Homecare Settings, Specialty Clinics, Rehabilitation Facilities Technology: Smart Pumps, Programmable Pumps, Continuous Delivery Systems, Bolus Delivery Systems |
| Companies Covered | LivaNova PLC, B. Braun Melsungen AG, Medtronic plc, Smiths Medical, Fresenius Kabi AG, Boston Scientific Corporation, Baxter International Inc., Terumo Corporation, Nevro Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Infusion Pumps Market Strategic Shifts
Smart pump architectures are actively reshaping implantable infusion pump markets as connectivity ecosystems expand attack surfaces and demand proactive risk management investment. This evolution is compressing traditional hardware margins while elevating software and service revenue streams.
Closed-loop glucose sensing integration is supplanting open-loop insulin delivery paradigms in diabetes management applications. Endocrinology practices in Germany and Japan are adopting sensor-augmented pump systems at accelerated replacement cycles. This convergence is enabling real-time glycemic control while compressing demand for conventional programmable pumps lacking continuous glucose monitor interoperability.
EU MDR technical documentation mandates are elevating clinical evidence thresholds for Class III implantable devices across European Economic Area markets. Manufacturers must now submit post-market clinical follow-up protocols that extend registration timelines by twelve to eighteen months. Programmable pump portfolios face the most acute compliance burden, prompting consolidation of legacy product lines and accelerated end-of-life declarations for non-compliant architectures.
Hospital procurement committees are unbundling after-sales service contracts from device capital expenditure, creating transparent lifecycle cost comparisons between vendors. This behavior is disrupting traditional bundled pricing models in United States academic medical centers and German university hospitals. The shift is most visible in oncology infusion applications where total cost of ownership calculations now dominate vendor selection criteria over upfront capital outlay.
Implantable Infusion Pumps Market Segmentation
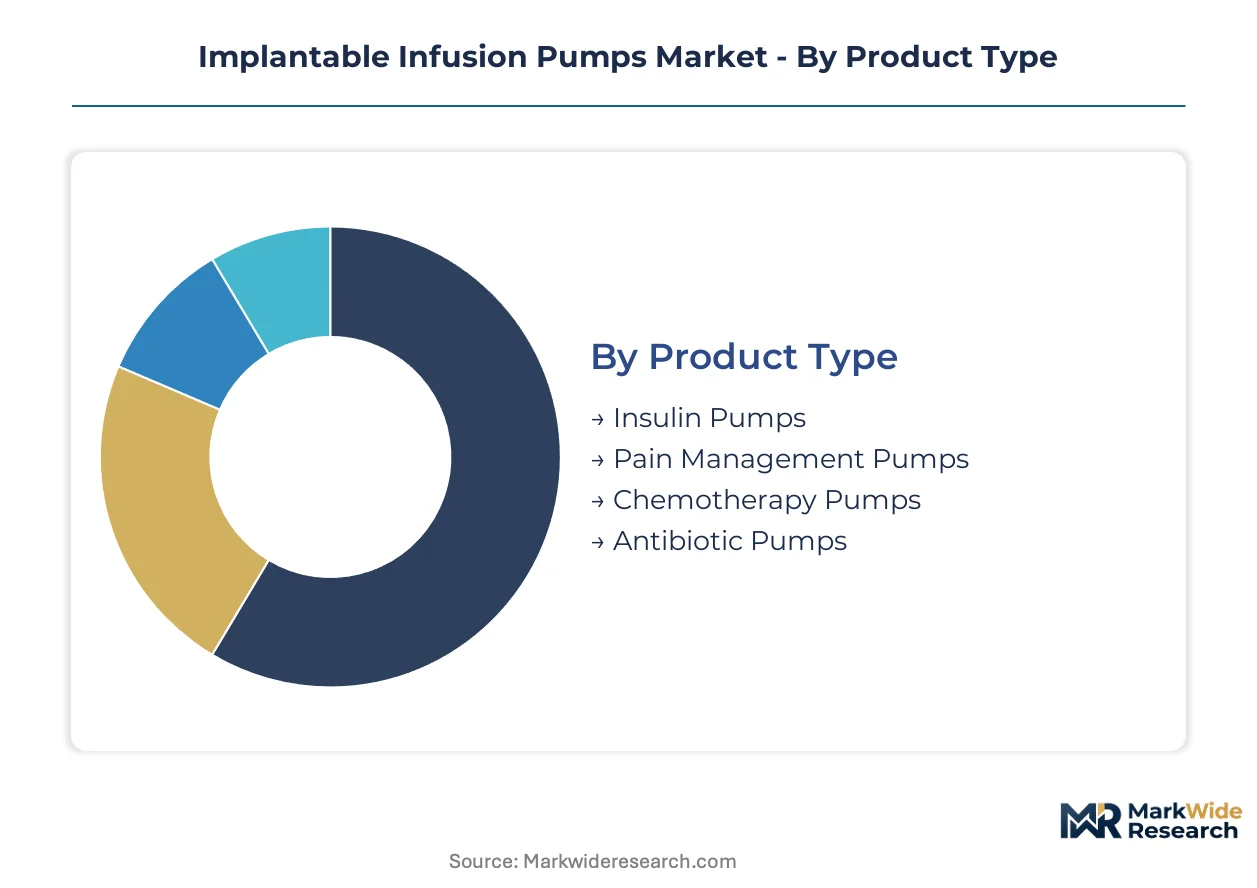
Segmentation in implantable infusion pumps reveals divergent margin structures across therapeutic applications and delivery architectures. Technology tiering and end-user setting selection determine procurement committee priorities and lifetime value calculations for device vendors.
Product Type:
Premium margin pools concentrate in systems requiring programmable precision and connectivity integration for complex chronic conditions.
- Insulin Pumps:Sealed titanium or polymer housings with peristaltic mechanisms deliver 0.1 to 1000 microliters per hour for precise glycemic control. Demand concentrates in Germany and Japan where endocrinology practices accelerate replacement cycles for sensor-augmented systems. Closed-loop glucose sensing integration compresses demand for conventional programmable architectures lacking continuous glucose monitor interoperability.
- Pain Management Pumps:Intrathecal delivery systems with piston-driven mechanisms target chronic pain management through precise opioid administration. United States academic medical centers drive procurement volume for programmable flow rate algorithms with dose-error reduction software. Medtronic plc anchors competitive positioning through deep neuromodulation expertise.
- Chemotherapy Pumps:Biocompatible reservoirs enable sustained cytotoxic agent delivery for oncology protocols. Fresenius Kabi AG sustains manufacturing scale across European and Asian production nodes for these applications.
- Antibiotic Pumps:Specialized housings accommodate antimicrobial formulations for resistant infection management. Smaller installed base reflects narrower therapeutic indications compared to metabolic and oncologic applications.
Insulin pumps hold installed capacity. Pain management pumps are rotating up the share rankings.
Application:
Volume distribution tracks chronic disease prevalence and reimbursement infrastructure maturity across national healthcare systems.
- Diabetes Management:Real-time glycemic control applications dominate replacement cycle velocity. Sensor-augmented pump systems from Germany and Japan demonstrate accelerated adoption patterns.
- Cancer Treatment:Sustained cytotoxic delivery maintains therapeutic plasma concentrations without repeated percutaneous access. Oncology bolus protocols represent emerging demand for on-demand dosing flexibility.
- Chronic Pain Management:Intrathecal opioid delivery reduces systemic exposure while maintaining analgesic efficacy. Brazil's ANVISA regulatory pathway creates first-mover advantages for underpenetrated infrastructure.
- Anesthesia:Perioperative delivery systems support controlled sedation and regional block protocols. Narrower addressable market reflects acute care setting concentration.
Diabetes management commands replacement frequency. Cancer treatment is climbing the fastest on protocol expansion.
End User:
Procurement authority and total cost of ownership calculations vary sharply between acute facilities and distributed care settings.
- Hospitals:Academic medical centers in the United States and German university hospitals unbundle after-sales service contracts from device capital expenditure. Transparent lifecycle cost comparisons now dominate vendor selection criteria.
- Homecare Settings:Patient preference for alternatives to prolonged hospitalization expands pump adoption outside acute care facilities. New service revenue streams emerge for device vendors managing remote monitoring infrastructure.
- Specialty Clinics:Focused endocrinology and pain management practices concentrate high-volume pump programming expertise.
- Rehabilitation Facilities:Post-acute settings manage pump titration for chronic pain patients transitioning from hospital-based care.
Hospitals retain capital expenditure authority. Homecare settings are gaining share fastest on patient preference shifts.
Technology:
Connectivity features and embedded software capabilities determine competitive tiering and pricing architecture differentiation.
- Smart Pumps:Dose-error reduction software and wireless connectivity ecosystems attract hospital procurement committees seeking liability mitigation. FDA and IEC cybersecurity guidance convergence demands proactive risk management investment.
- Programmable Pumps:Adjustable flow rate algorithms support individualized therapeutic protocols across multiple indications. EU MDR technical documentation mandates and FDA premarket notification requirements extend registration timelines.
- Continuous Delivery Systems:Mature volume share reflects established reliability in basal rate maintenance applications. Simpler architectures face margin compression from premium smart pump positioning.
- Bolus Delivery Systems:Patient-controlled analgesia protocols enable on-demand dosing flexibility. Emerging traction in chemotherapy administration reduces systemic opioid exposure.
Continuous delivery systems hold installed capacity. Smart pumps are rotating up the share rankings on connectivity premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-machined pump components to United States and Japanese device assemblers, creating a transatlantic trade corridor that concentrates high-value manufacturing in Alpine and Central European clusters while final assembly gravitates toward major healthcare procurement markets.
United States
FDA premarket notification pathways and chronic pain management reimbursement infrastructure sustain demand for programmable intrathecal delivery systems. Academic medical centers in Boston and Baltimore unbundle service contracts from capital expenditure, forcing transparent lifecycle cost comparisons. The Minneapolis-St. Paul corridor anchors neuromodulation device engineering talent pools.
Germany
EU MDR technical documentation mandates filter procurement toward certified manufacturers with established post-market clinical follow-up capabilities. Baden-Württemberg and Bavaria house precision machining suppliers serving piston-driven mechanism requirements. Stuttgart-based component fabricators extend lead times for North American assemblers seeking microliter-per-hour accuracy.
Japan
PMDA clinical evidence thresholds for programmable architectures extend registration timelines while accelerating replacement cycles for sensor-augmented insulin pumps. Tokyo and Osaka endocrinology practices adopt closed-loop glucose sensing integration at compressed intervals. Kansai region manufacturing nodes supply biocompatible titanium housings for regional device assembly.
Brazil
ANVISA regulatory pathways for intrathecal delivery systems attract first-mover investment amid underpenetrated chronic pain management infrastructure. Expanding private insurance coverage in São Paulo and Rio de Janeiro creates reimbursement momentum for implantable oncology infusion applications. Southeast Brazilian distributors build service networks for remote patient monitoring.
China
NMPA clinical evidence requirements for Class III implantable devices delay programmable pump registrations while sustaining demand for continuous delivery systems. Yangtze River Delta manufacturing clusters scale polymer housing production for export markets. Shanghai-based procurement committees prioritize total cost of ownership metrics in vendor selection.
Implantable Infusion Pumps Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory certification dimensions, creating a tiered structure where scale advantages in manufacturing collide with agility in niche therapeutic applications. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with neuromodulation portfolios, precision device specialists with concentrated infusion expertise, and diversified healthcare suppliers leveraging manufacturing scale across multiple delivery modalities. Consolidation pressure intensifies as EU MDR compliance costs favor entities with established technical documentation capabilities, while strategic partnerships between component suppliers and final assemblers reshape supply chain control points.
Within the diversified medical technology tier, Medtronic plc and Boston Scientific Corporation exemplify competitive positioning built on deep therapeutic specialization and physician workflow integration. Among European precision manufacturers, B. Braun Melsungen AG and Fresenius Kabi AG occupy positions anchored in manufacturing scale and oncology infusion applications. These entities represent how geographic clustering of regulatory expertise and component supply shapes strategic options.
| Leading Market Players |
|---|
| LivaNova PLC |
| B. Braun Melsungen AG |
| Medtronic plc |
| Smiths Medical |
| Fresenius Kabi AG |
| Boston Scientific Corporation |
| Baxter International Inc. |
| Terumo Corporation |
| Nevro Corp |
| Others |
Value Chain & Pricing Dynamics
Polymer housing substitution for titanium enclosures is redrawing procurement economics while compressing geographic supply options toward Yangtze River Delta manufacturing clusters. This material transition simultaneously lowers per-unit production costs and concentrates vendor qualification authority within Chinese NMPA regulatory frameworks.
Pricing Analysis
Next-generation smart pump architectures command substantial premiums over legacy continuous delivery systems and first-wave programmable alternatives. Three-tier pricing structure across premium connectivity-enabled, standard programmable, and economy continuous delivery levels reflects FDA certification grade and embedded software complexity. Pricing pressure stems from hospital procurement committees unbundling after-sales service contracts and demanding transparent lifecycle cost comparisons. Academic medical centers in the United States exhibit lowest price sensitivity due to liability mitigation priorities, while homecare settings in emerging markets drive hardest bargain negotiations.
Supply Chain Analysis
Strategic stockpiling of precision-machined piston components dominates inventory strategy given extended lead times from Baden-Württemberg and Bavarian suppliers. Manufacturing gravity centers on Germany for titanium housings and precision mechanisms, Japan for biocompatible polymer formulations, and China for scaled polymer housing production. Raw material dependencies encompass medical-grade titanium alloys, specialized antimicrobial polymers, and high-tolerance ceramic bearings. Single-source vulnerability concentrates in Alpine machining clusters serving microliter-per-hour accuracy requirements. Distribution runs through hospital procurement committees and GPO contracts in developed markets, with direct-to-clinic channels expanding in homecare settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Implantable infusion pumps sit at early-cycle expansion as homecare migration and closed-loop sensing integration open addressable demand beyond traditional hospital confines. Sensor-augmented diabetes management protocols in Germany and Japan demonstrate accelerated replacement velocity that validates penetration runway.
For Market Incumbents: Secure EU MDR technical documentation capabilities to filter procurement toward certified manufacturers as post-market clinical follow-up mandates extend registration timelines. Consolidate legacy product lines and accelerate end-of-life declarations for non-compliant architectures before compliance costs escalate. Absorb cybersecurity guidance investment into service revenue streams to offset hardware margin compression from smart pump connectivity premiums.
For New Entrants and Emerging Players: Lead with Brazil's ANVISA regulatory pathway for intrathecal delivery systems where chronic pain management infrastructure remains underpenetrated and private insurance coverage expands. Target oncology bolus protocols in chemotherapy administration as emerging demand for patient-controlled analgesia reduces systemic opioid exposure. Build service network partnerships with Southeast Brazilian distributors managing remote patient monitoring infrastructure.
For Investors and Strategic Acquirers: EU MDR convergence reshapes the acquisition landscape by favoring entities with established post-market clinical follow-up capabilities over asset-light challengers. Long-term viability hinges on software and service revenue streams displacing hardware-centric models across the analysis window. Target precision device specialists with concentrated infusion expertise and existing ISO 13485 certification. Watch FDA cybersecurity guidance enforcement thresholds as inflection indicator for connected pump ecosystem valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Notification Pathway | Accelerates programmable flow rate algorithm approvals for intrathecal delivery systems in United States academic medical centers. |
| CE Marking Pathway under EU MDR | Filters procurement toward certified manufacturers with post-market clinical follow-up capabilities across European Economic Area markets. |
| Hospital System Partnership | Unbundles after-sales service contracts from device capital expenditure in German university hospitals and United States academic centers. |
| Software Companion Development | Enables dose-error reduction software deployment against fragmented electronic health record systems for liability mitigation. |
| Reimbursement Strategy | Aligns intrathecal delivery system positioning with chronic pain management reimbursement infrastructure in Brazil's expanding private insurance markets. |
Study Parameters
Cross-validation between primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and endocrinology practice administrators anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up triangulation across therapeutic application segments and top-down validation against national healthcare expenditure patterns ensure analytical coherence.
Sensitivity analysis across programmable precision tiers, connectivity integration levels, and end-user setting distributions informs the analytical framework over the projection horizon. Segmentation dimensions encompass product type, application, technology architecture, and geographic regulatory cluster. CAGRs derive from replacement cycle velocity modeling and penetration rate assumptions calibrated against chronic disease prevalence trajectories. Industry-specific inputs include EU MDR registration timeline extensions and PMDA clinical evidence thresholds for programmable architectures.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement infrastructure expansion or cybersecurity guidance enforcement would require recalibration. Forecasts reflect assumptions regarding homecare migration velocity and closed-loop sensing adoption curves. Revision becomes warranted when FDA premarket notification timelines or EU MDR compliance cost absorption cross thresholds that alter competitive tier dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
Radiofrequency Balloon Catheter Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Cardiac Sutures Market
Cardiovascular Devices
Global Nitinol-Based Medical Devices Market
Cardiovascular Devices
Cardiovascular Prosthetic Devices Market
Cardiovascular Devices
Global Vascular Patch Market
Cardiovascular Devices
China Cardiovascular Devices Market
Cardiovascular Devices
Endovascular Therapy Devices Market