
 Intubation Accessories Market | 2026-2036
Intubation Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Intubation Accessories Market Foresight
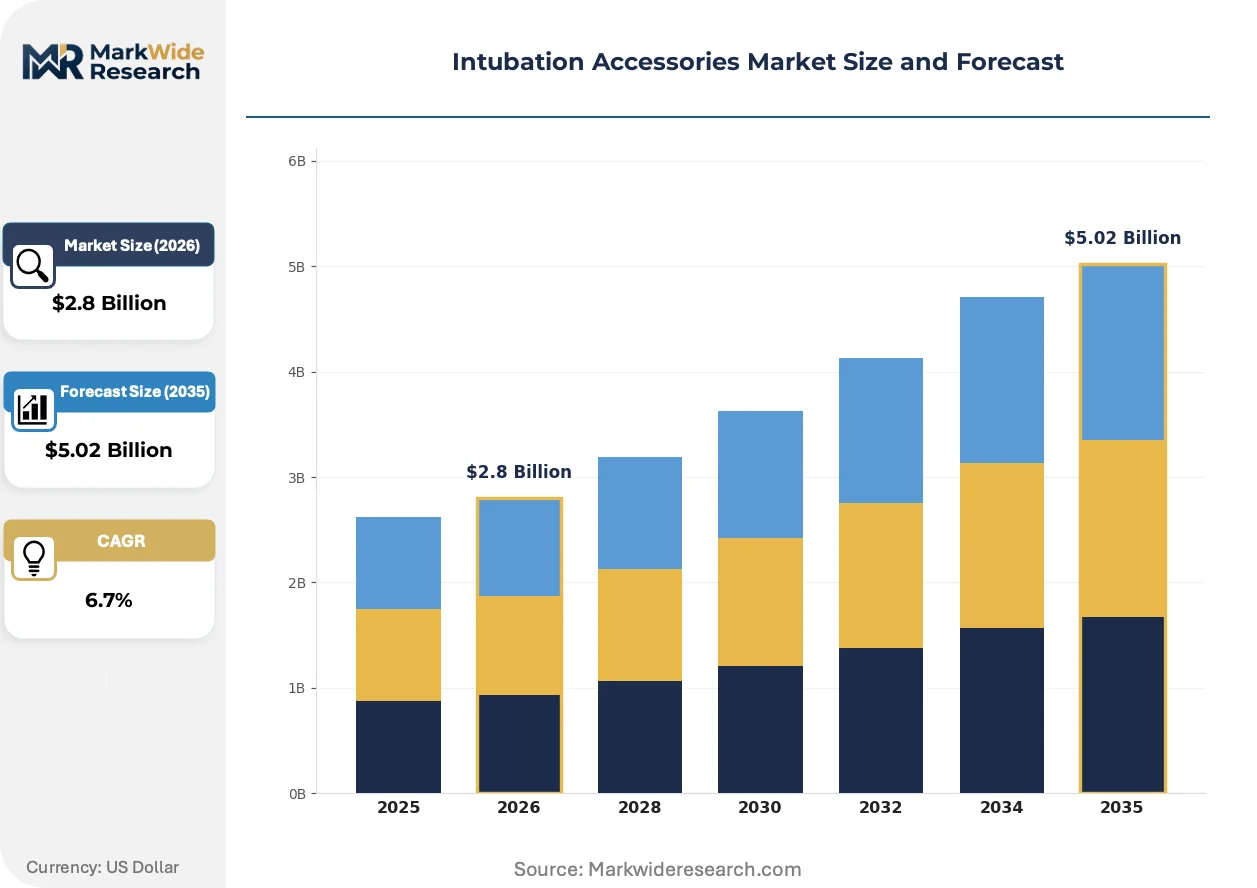
Leasing-based equipment procurement is reconfiguring capital deployment across acute care settings, allowing mid-tier hospitals to access advanced airway systems without full ownership burdens. Medtronic leverages its integrated critical care portfolio to sustain pricing power in bundled contracts. Teleflex Incorporated anchors its position through specialized laryngeal mask portfolios that dominate ambulatory surgical channels. Smiths Group differentiates via R&D intensity in silicone-based tube formulations that command premium placement.
Intubation accessories comprise the ancillary devices and consumables supporting artificial airway establishment and maintenance, including endotracheal tubes fabricated from medical-grade polyvinyl chloride or silicone with standardized cuff pressure mechanisms, laryngeal mask airways designed for supraglottic ventilation, and suction catheters engineered for tracheal secretion clearance. These products serve the primary purpose of securing patient ventilation during anesthesia induction, emergency resuscitation, and prolonged critical care management. Endotracheal tubes represent the mature revenue base with stable replacement cycles, while laryngeal masks capture faster expansion as ambulatory surgical centers favor supraglottic approaches that reduce intubation trauma. Single-use delivery modes are displacing reusable alternatives as infection control protocols tighten across hospital systems, concentrating margin pools in sterilized disposable formats.
FDA premarket notification requirements and EU MDR conformity assessment frameworks govern device safety and biocompatibility standards, compelling manufacturers to maintain extensive clinical documentation and quality management systems. ISO 10993 biological evaluation protocols further shape material selection and supplier qualification processes for polymer and silicone components. Stakeholders must monitor evolving reimbursement pathways for outpatient airway procedures and assess how sterilization validation costs redistribute competitive advantage across single-use and reusable product lines.
Market Dynamics
Single-use sterilization protocols are compressing reusable product lines across hospital supply chains, forcing manufacturers to reconfigure production capacity toward disposable formats. This shift is redistributing margin pools and reshaping supplier qualification requirements for polymer and silicone sourcing.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedural volume in United States ASCs is pulling demand toward supraglottic airway devices that reduce anesthesia recovery times. FDA 510(k) clearance pathways for laryngeal mask innovations are accelerating product cycles in this channel.
- EU MDR conformity upgrades:Stricter biocompatibility documentation requirements are elevating entry barriers for low-cost competitors. Incumbent manufacturers with established quality management systems are capturing displaced volume from non-compliant suppliers.
- Silicone formulation advances:Medical-grade silicone tubes with integrated pressure monitoring are commanding premium placement in critical care units. These materials reduce ventilator-associated pneumonia risk compared to standard polyvinyl chloride alternatives.
Market Restraints
- Polymer feedstock volatility:Medical-grade polyvinyl chloride and silicone raw material costs fluctuate with petrochemical indices. Manufacturers lack pricing power to pass through input spikes in contracted hospital purchasing agreements.
- Supply concentration in Southeast Asian molding:Contract manufacturers in Vietnam and Malaysia control substantial share of precision cuff assembly. Geopolitical friction or shipping disruption creates single-source vulnerability for Western brands.
- Reusable device residual demand:Some European health systems retain sterilization infrastructure that sustains multi-use tube economics. This installed base limits full conversion to premium single-use revenue models.
Strategic Opportunities
- India outpatient infrastructure buildout:Government hospital modernization programs under Ayushman Bharat are creating first-time demand for standardized airway management kits. CDSCO regulatory harmonization with ISO standards is reducing import friction for multinational suppliers.
- Integrated suction-catheter systems:Closed-loop secretion clearance devices that combine suction with pressure monitoring are opening new procedure categories. These systems address infection control mandates while capturing higher per-procedure revenue.
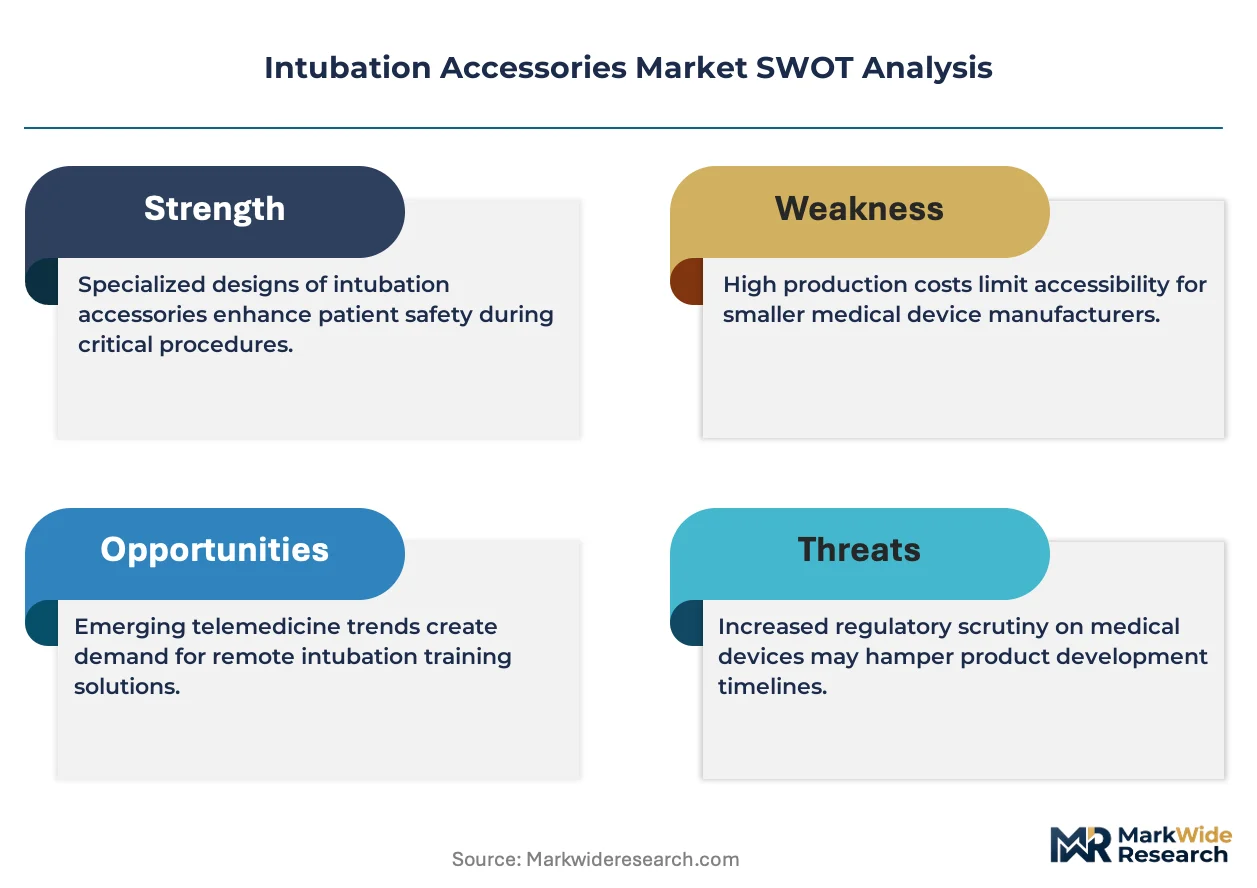
- Telemedicine-guided emergency intubation:Remote anesthesia consultation is extending advanced airway capability to rural emergency departments. This channel requires portable, pre-sterilized kit configurations that differ from traditional OR stocking models.
Industry Challenges
- ISO 10993 biological evaluation timelines:Extended cytotoxicity and sensitization testing for new silicone suppliers delays product launches by 12-18 months. Manufacturers must maintain parallel supplier qualification pipelines to ensure continuity.
- Legacy sterilization validation assets:Hospitals with embedded ethylene oxide or steam sterilization infrastructure resist full conversion to disposable-only supply contracts. Sales cycles require clinical economic justification that consumes specialist account management resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intubation Accessories Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endotracheal Tubes, Laryngeal Masks, Resuscitators, Suction Catheters Delivery Mode: Single-use, Reusable, Sterilized, Non-Sterilized End User: Hospitals, Emergency Services, Surgical Centers, Home Care Material: Polyvinyl Chloride, Silicone, Latex, Polyethylene |
| Companies Covered | Medtronic, Teleflex Incorporated, Smiths Group, Armstrong Medical, Vyaire Medical, BD, Bactiguard Holding, Hospiteknik Healthcare, SunMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intubation Accessories Market Shifts & Advancements
Material science breakthroughs and regulatory documentation requirements are simultaneously elevating product performance standards and consolidating competitive positions among manufacturers with robust quality infrastructure.
Subglottic suction endotracheal tubes with integrated above-the-cuff drainage ports are rendering obsolete standard uncuffed designs in prolonged ventilation cases. Intensive care units in United States academic medical centers are adopting these devices as core protocol. The technology is compressing ventilator-associated pneumonia incidence and associated length-of-stay costs, forcing competitors without suction-integrated portfolios into price-driven commodity segments.
EU MDR Article 10 technical documentation requirements are mandating clinical evidence portfolios that exceed previous Medical Device Directive thresholds. Manufacturers must now submit post-market surveillance data and periodic safety update reports for Class IIa airway devices. Small European specialists without regulatory affairs scale are exiting the market, concentrating supply among multinationals with dedicated MDR transition teams.
Hospital value analysis committees are consolidating purchasing authority previously dispersed across anesthesia, emergency medicine, and critical care departments. This buyer concentration is compressing vendor lists and demanding bundled pricing across tube, mask, and suction catheter categories. The shift is most visible in United States integrated delivery networks where standardization mandates override individual physician preference.
Intubation Accessories Market Segmentation
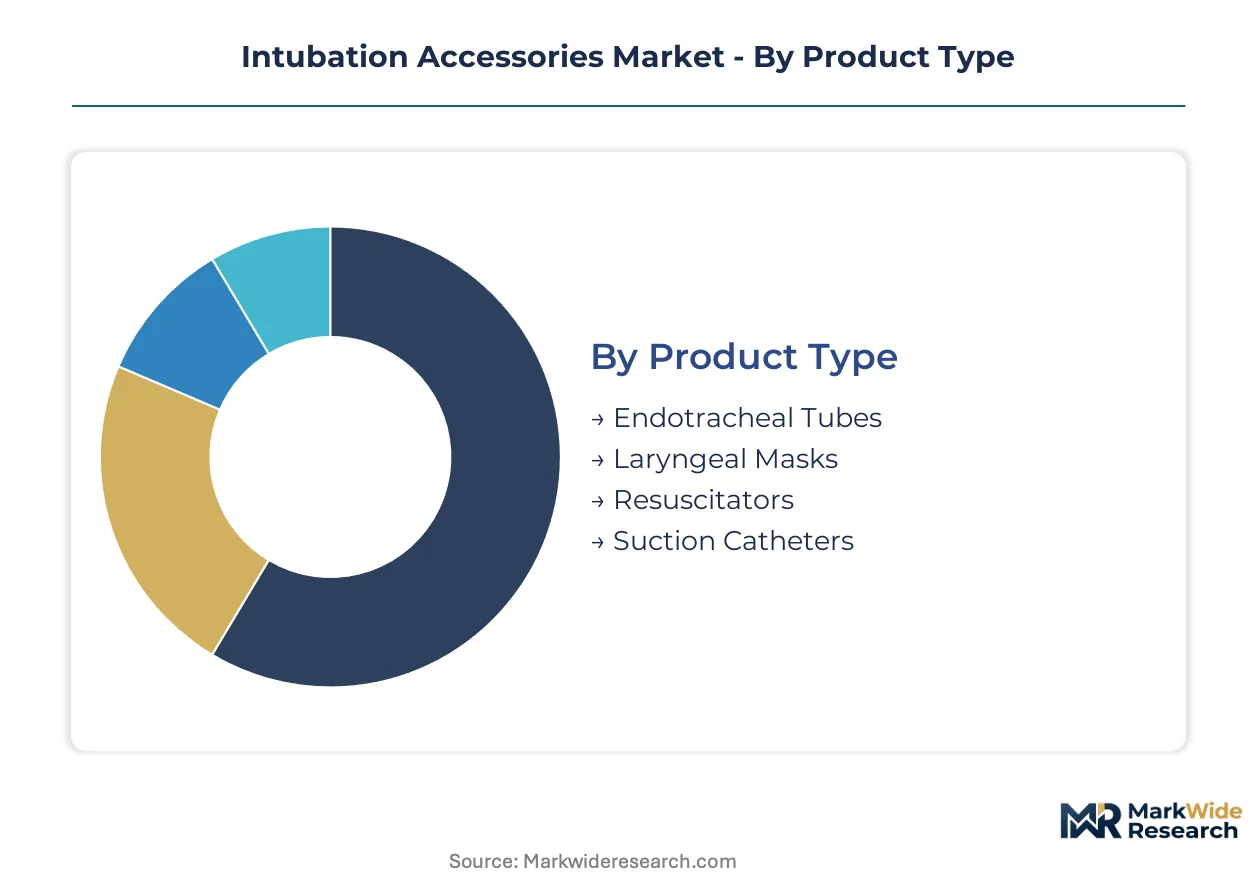
Intubation accessories serve distinct clinical workflows across anesthesia induction, emergency airway rescue, and prolonged mechanical ventilation. Segmentation reveals how material selection and delivery mode reshape procurement economics while end-user channel dynamics concentrate margin pools in specialized settings.
Product Type:
Mature airway devices anchor hospital purchasing contracts while emerging formats capture ambulatory surgical expansion through reduced procedural trauma.
- Endotracheal Tubes:Medical-grade polyvinyl chloride or silicone constructs with standardized cuff pressure mechanisms dominate prolonged ventilation scenarios. United States academic medical centers are adopting subglottic suction-integrated variants as core ICU protocol, compressing ventilator-associated pneumonia incidence and associated length-of-stay costs.
- Laryngeal Masks:Supraglottic ventilation devices eliminate direct laryngeal trauma during anesthesia induction. United States ambulatory surgical centers favor these formats for reduced recovery times, with FDA 510(k) clearance pathways accelerating product cycles in this channel.
- Resuscitators:Manual positive-pressure ventilation devices for emergency airway rescue and pre-hospital settings.
- Suction Catheters:Tracheal secretion clearance instruments, increasingly integrated with pressure monitoring in closed-loop configurations.
Endotracheal tubes retain volume leadership; laryngeal masks hold the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates premium sterilized disposables from capital-intensive reusable systems that retain residual demand in European infrastructure.
- Single-use:Pre-sterilized disposable formats concentrate margin pools as infection control protocols tighten across hospital systems. These products eliminate cross-contamination risk and reduce sterilization validation burdens for procurement departments.
- Reusable:Multi-cycle devices sustained by embedded ethylene oxide or steam sterilization infrastructure in select European health systems. These facilities resist full conversion to disposable-only supply contracts, requiring clinical economic justification that consumes specialist account management resources.
- Sterilized:Terminal sterilization by gamma irradiation or ethylene oxide meets FDA and EU MDR compliance requirements for immediate clinical deployment.
- Non-Sterilized:Unsterilized formats requiring hospital-based processing, increasingly limited to institutional customers with captive sterilization capacity.
Single-use formats command the premium tier; reusable alternatives defend position in installed-base accounts.
End User:
Customer type concentration shifts purchasing authority from individual physicians toward value analysis committees demanding bundled category pricing.
- Hospitals:Integrated delivery networks consolidate procurement across anesthesia, emergency medicine, and critical care departments. These systems mandate standardization that overrides individual physician preference, compressing vendor lists.
- Emergency Services:Pre-hospital and rural emergency departments require portable, pre-sterilized kit configurations. Telemedicine-guided intubation is extending advanced airway capability to these settings, demanding products suited for remote consultation workflows.
- Surgical Centers:Ambulatory facilities prioritize rapid turnover and reduced anesthesia recovery times, favoring supraglottic approaches.
- Home Care:Long-term ventilation patients and palliative care settings with intermittent airway support needs.
Hospitals dominate procurement volume; surgical centers are climbing the fastest.
Material:
Supply concentration in Southeast Asian polymer molding shapes sourcing economics for Western manufacturers.
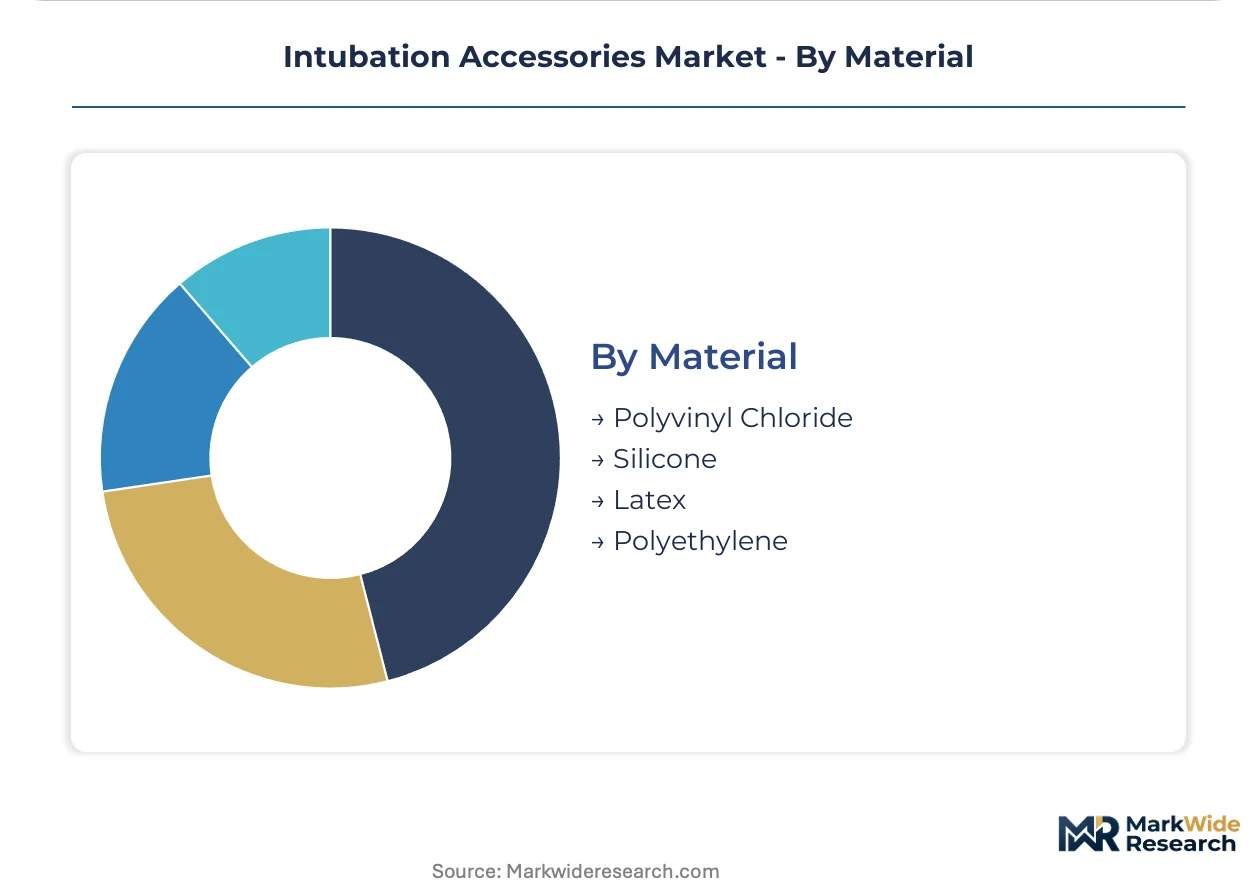
- Polyvinyl Chloride:Medical-grade PVC with plasticizer formulations for cuff flexibility represents the mature cost-optimized standard. Petrochemical feedstock volatility creates margin pressure that manufacturers struggle to pass through in contracted hospital agreements.
- Silicone:Medical-grade silicone tubes with integrated pressure monitoring command premium placement in critical care units. ISO 10993 biological evaluation protocols extend new supplier qualification timelines by 12-18 months, compelling parallel pipeline maintenance.
- Latex:Natural rubber formulations with declining utilization due to hypersensitivity concerns in patient populations.
- Polyethylene:Alternative polymer for specialized applications requiring distinct mechanical properties or chemical resistance profiles.
Polyvinyl chloride retains cost-driven volume leadership; silicone captures the steepest value expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States health systems modernizing anesthesia infrastructure, while procurement in India and Southeast Asia remains cost-sensitive despite volume expansion. This asymmetry redistributes margin pools toward Western markets while compressing returns in emerging economies.
United States
Ambulatory surgical centers and academic medical centers drive demand for subglottic suction-integrated tubes and laryngeal mask portfolios. FDA 510(k) clearance pathways accelerate product cycles for supraglottic devices. The Minneapolis-St. Paul corridor hosts critical care device clusters where integrated delivery networks consolidate purchasing authority across anesthesia and emergency medicine departments.
Germany
EU MDR conformity assessment requirements elevate entry barriers for airway device manufacturers, favoring incumbents with established quality management systems. The country's national pharmaceutical regulator enforces stricter biocompatibility documentation than previous Medical Device Directive thresholds. Baden-Württemberg's medical technology corridor concentrates sterilization validation expertise and polymer processing capabilities for silicone-based tube formulations.
India
Government hospital modernization programs under Ayushman Bharat create first-time demand for standardized airway management kits in outpatient infrastructure. CDSCO regulatory harmonization with ISO standards reduces import friction for multinational suppliers. Maharashtra's Mumbai-Pune pharmaceutical belt anchors domestic manufacturing of medical-grade polymer components for regional device assembly.
Japan
Aging demographics expand prolonged ventilation cases in critical care units, pulling demand toward silicone tubes with integrated pressure monitoring. METI industrial policy supports domestic production of high-value medical devices to reduce import dependency. The Osaka-Kobe medical device cluster specializes in precision cuff assembly and sterilization technologies for premium airway accessories.
Vietnam
Contract manufacturers in precision molding control substantial share of cuff assembly for Western brands, creating single-source vulnerability amid geopolitical friction. The country's national pharmaceutical regulator aligns with ASEAN medical device directive frameworks to facilitate export-oriented production. Ho Chi Minh City's industrial zones concentrate polymer feedstock processing and sterilized disposable format assembly for global supply chains.
Intubation Accessories Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material science and precision molding. The vendor base concentrates among multinationals with dedicated regulatory affairs scale for EU MDR transition and FDA quality system compliance. Three archetypes dominate: integrated critical care portfolios, specialized laryngeal mask developers, and silicone formulation innovators. Competitive moves center on bundled contract pricing across tube-mask-suction categories and backward integration into medical-grade polymer sourcing to offset feedstock volatility.
Among diversified medical technology conglomerates, Medtronic occupies a position exemplifying integrated critical care portfolio breadth. Teleflex Incorporated represents the specialized airway device archetype with concentrated laryngeal mask positioning. Smiths Group anchors the silicone formulation tier through R&D intensity in medical-grade tube materials. These three entities collectively illustrate how regulatory scale and material science capabilities partition competitive advantage in contracted hospital purchasing environments.
| Leading Market Players |
|---|
| Medtronic |
| Teleflex Incorporated |
| Smiths Group |
| Armstrong Medical |
| Vyaire Medical |
| BD |
| Bactiguard Holding |
| Hospiteknik Healthcare |
| SunMed |
| Others |
Supply & Pricing Matrix
Ho Chi Minh City's precision molding corridor concentrates cuff assembly capacity for Western brands, translating polymer feedstock volatility into margin compression that manufacturers struggle to pass through in contracted hospital purchasing agreements. This geographic concentration of sterilized disposable format production shapes downstream pricing power across United States integrated delivery networks and European hospital systems.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. FDA 510(k) clearance tier and ISO 10993 certification grade separate premium silicone tubes from standard PVC alternatives. Pricing pressure stems from petrochemical index fluctuations that manufacturers cannot fully recover in long-term GPO contracts. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with value analysis committees prioritize infection control outcomes over unit cost.
Supply Chain Analysis
Export control regimes on medical-grade silicone precursors limit flows from specialized chemical manufacturers to device assemblers. Vietnam, Malaysia, and China concentrate precision molding and terminal sterilization capacity. Supply rests on medical-grade PVC resin, silicone elastomer, and gamma irradiation services. Single-source vulnerability in Southeast Asian cuff assembly creates structural risk. Distribution runs through hospital GPOs and specialized medical device distributors to end-user procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as telemedicine-guided emergency intubation creates demand for portable kit configurations that differ from traditional OR stocking models. This channel divergence rewards specialized entrants over broadline incumbents.
For Market Incumbents: Entrench position through backward integration into medical-grade polymer sourcing to offset feedstock volatility. Expand sterilization validation capacity in Baden-Württemberg to capture EU MDR-compliant volume displaced from non-compliant competitors. Prioritize bundled contracts across tube-mask-suction categories to compress vendor lists before emerging players establish beachheads. For New Entrants and Emerging Players: Establish a beachhead in India's Ayushman Bharat outpatient infrastructure buildout where first-time demand for standardized airway kits outpaces incumbent supply coverage. Target rural United States emergency departments requiring telemedicine-compatible pre-sterilized configurations. Pursue CDSCO regulatory harmonization pathway to reduce import friction faster than multinational compliance timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors silicone formulation specialists with ISO 10993 documentation depth over commodity PVC manufacturers. Long-term viability hinges on infection control protocol permanence and single-use conversion irreversibility. Watch for EU MDR transition completion as inflection indicator for competitive consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates product cycles for supraglottic devices in ambulatory surgical channels. |
| CE Marking Pathway | EU MDR conformity assessment elevates entry barriers favoring quality-system incumbents. |
| Hospital System Partnership | Integrated delivery network standardization mandates compress vendor lists across categories. |
| Backward Integration into Silicone | In-house polymer sourcing insulates margins from petrochemical index volatility. |
| Reimbursement Strategy | Outpatient airway procedure coding shapes demand pull toward reduced-recovery formats. |
Research Methodology
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up volume estimates triangulate against top-down spending analysis across the analysis window.
Calibration against historical adoption curves for subglottic suction tubes and laryngeal mask airways shapes the analytical framework. Segmentation dimensions include product type, delivery mode, end-user channel, and material formulation across the projection horizon. CAGRs derive from procedure volume elasticity, price trajectory assumptions, and conversion rates from reusable to single-use formats. Silicone formulation adoption curves and ambulatory surgical center expansion rates serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in petrochemical indices, healthcare reimbursement policy, or trade route stability would shift the trajectory. Forecasts reflect documented assumptions regarding infection control protocol permanence and regulatory compliance timelines. Material shifts in EU MDR enforcement intensity or Southeast Asian manufacturing capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Intraosseous Devices Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Oxygenator Market
Medical Devices
Heating Pads Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Contrast Injection Lines Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Endoprosthesis Market
Medical Devices
Global Monopolar Electrosurgery Market
Medical Devices
Arthroscopy Procedures and Products Market
Medical Devices
Bone Power Tools Market
Medical Devices
Medical Smart Wearable Devices Market
Medical Devices
Laser BPH Devices Market
Medical Devices
Global Transcranial Magnetic Stimulators Market
Medical Devices
Water Bath Vaporizer Market