
 Radiofrequency Balloon Catheter Market | 2026-2036
Radiofrequency Balloon Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Radiofrequency Balloon Catheter Market Analytics
Polyurethane is expanding its share over nylon in balloon catheter construction, cutting profile thickness while maintaining burst pressure ratings above twelve atmospheres. Medtronic leverages captive extrusion capabilities to control material cost curves across its portfolio. Boston Scientific Corporation differentiates through temperature-sensing integration at the balloon-tissue interface. Abbott Laboratories anchors European electrophysiology lab contracts with bundled catheter-and-mapping system agreements.
A radiofrequency balloon catheter is a therapeutic device combining a compliant or semi-compliant balloon membrane with embedded electrode arrays that deliver controlled radiofrequency energy to cardiac tissue; the balloon achieves stable tissue contact via fluid inflation at two to five atmospheres while thermocouples or impedance sensors monitor lesion formation in real time. Single-lumen designs dominate ambulatory settings for cost containment, yet double-lumen configurations capture margin pools in academic medical centers where irrigation and sensing channels justify premium positioning. Electrophysiology technology leads procedure volumes, while cryoablation competes in pediatric and redo-ablation cases where tissue sparing matters.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements are extending product introduction cycles by twelve to eighteen months for novel electrode geometries. Japan's PMDA adds clinical trial obligations for first-in-class energy delivery patterns that exceed predicate device parameters. Stakeholders must monitor whether CMS national coverage determinations for persistent atrial fibrillation ablation expand beyond antiarrhythmic drug failure criteria, as this reimbursement boundary shapes addressable procedure volumes more directly than device innovation cycles.
Market Dynamics
Catheter ablation is displacing pharmaceutical management for persistent atrial fibrillation, forcing hospital systems to expand electrophysiology lab capacity and renegotiate device procurement frameworks around bundled service agreements rather than per-unit pricing.
Growth Catalysts
- EU MDR Technical Documentation:Tightened performance documentation requirements for novel electrode geometries are accelerating investment in validated manufacturing processes, advantaging incumbent suppliers with established quality management systems.
- Cardiac Electrophysiology Labs:Hospital systems in Germany, Japan, and the United States are expanding dedicated arrhythmia center infrastructure, concentrating procedure volumes and creating pull-through demand for integrated catheter-and-mapping platforms.
- Polyurethane Balloon Membranes:Thinner profile construction maintaining burst pressure ratings above twelve atmospheres is enabling transseptal access with reduced vascular complications, expanding treatable patient populations.
Market Restraints
- Input Cost Volatility:Specialized polyurethane and platinum-iridium electrode alloys face supply concentration risks from limited qualified polymer extruders and precious metal refiners, compressing gross margins during commodity price spikes.
- Regulatory Friction:FDA 510(k) clearance timelines and Japan PMDA clinical trial obligations for first-in-class energy delivery patterns are extending product introduction cycles by twelve to eighteen months, delaying revenue recognition for novel designs.
- Cryoablation Substitution:Balloon-based cryoenergy systems compete in pediatric and redo-ablation cases where tissue sparing priorities override radiofrequency lesion durability, capping addressable procedure volumes in these subsegments.
Strategic Opportunities
- Underpenetrated Tertiary Centers:Ambulatory surgical centers in the United States remain underserved for complex atrial fibrillation ablation, presenting white space for single-lumen catheter configurations optimized for cost containment.
- Technology Convergence:Integration of impedance sensing with temperature monitoring at the balloon-tissue interface is enabling real-time lesion assessment, differentiating premium double-lumen offerings in academic medical centers.
- CMS National Coverage Determinations:Potential expansion of Medicare reimbursement beyond antiarrhythmic drug failure criteria would reshape addressable procedure volumes more directly than incremental device innovation cycles.
Industry Challenges
- Electrophysiologist Training Bottlenecks:Specialized fellowship programs produce insufficient operators to match expanding lab capacity, creating procedural backlogs and underutilized capital equipment.
- Legacy Mapping System Integration:Catheter compatibility requirements with installed base platforms from competing vendors force redundant engineering investments and fragment R&D allocation across proprietary connector standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiofrequency Balloon Catheter Market |
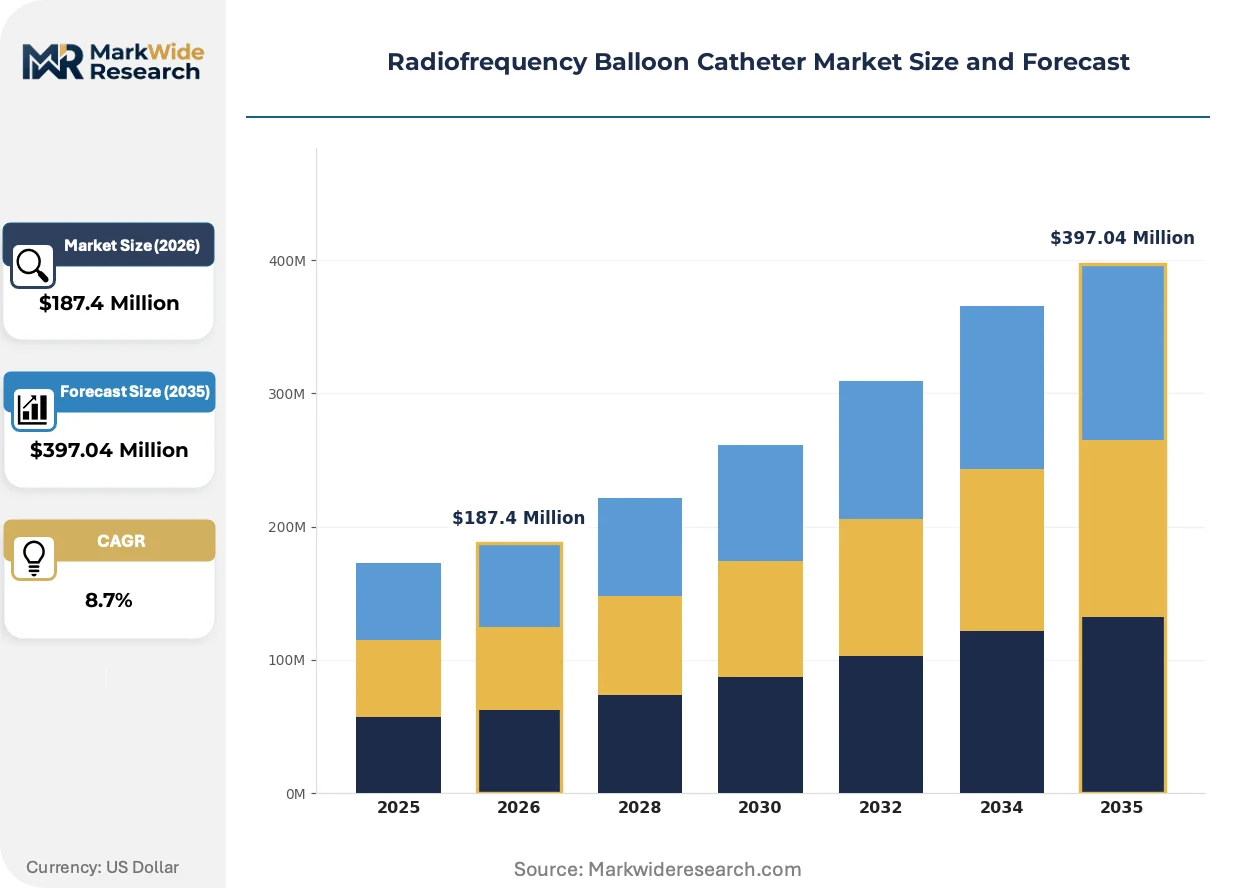
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lumen, Double-Lumen, Multi-Lumen, Accessories End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutes Technology: Electrophysiology, Temperature-Controlled, Pressure-Controlled, Cryoablation Application: Atrial Fibrillation, Supraventricular Tachycardia, Ventricular Tachycardia, Others |
| Companies Covered | Medtronic, Biosense Webster, Inc., Abbott Laboratories, Boston Scientific Corporation, Johnson & Johnson, Becton Dickinson and Company, Terumo Corporation, Stryker Corporation, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiofrequency Balloon Catheter Market Evolving Landscape
Temperature-sensing electrode arrays are compressing the feedback loop between energy delivery and lesion formation, while regulatory documentation burdens and procurement centralization are reshaping competitive positioning across the value chain.
Multi-electrode phased radiofrequency arrays are electrifying the precision of pulmonary vein isolation procedures. Tertiary arrhythmia centers in Germany and Japan are adopting these configurations for persistent atrial fibrillation cases within eighteen months of regulatory clearance. The technology is electrifying expectations for single-procedure success rates, pressuring manufacturers without integrated sensing capabilities into price-based competition.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up for Class III cardiac devices. Manufacturers must now maintain active implant registries and submit periodic safety updates, increasing compliance overhead disproportionately for smaller entrants. Double-lumen irrigation-sensing configurations face the steepest documentation burdens given their complexity, advantaging suppliers with established European notified body relationships.
Hospital procurement committees are consolidating vendor relationships around bundled catheter-and-mapping system agreements. Academic medical centers in the United States are replacing transactional device purchasing with multi-year performance contracts that tie reimbursement to procedure volume commitments. This concentration is most visible in integrated delivery networks where electrophysiology service line directors wield centralized authority over capital and consumable budgets.
Radiofrequency Balloon Catheter Market Segmentation
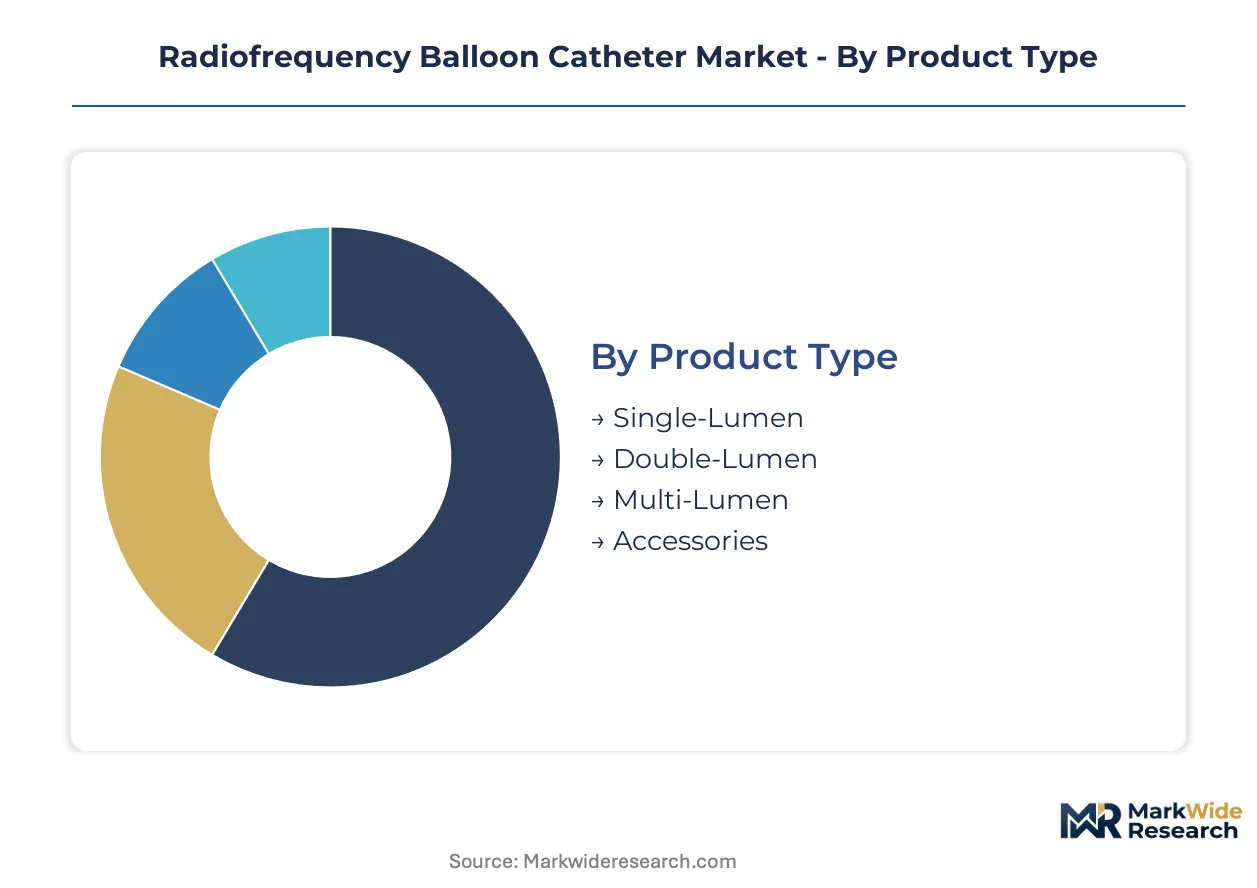
Procurement committees prioritize lumen configuration against procedure complexity and reimbursement tiers, while technology choices hinge on lesion durability requirements versus tissue preservation needs. Application segmentation tracks the shift from pharmaceutical management toward catheter-based intervention for persistent arrhythmias.
Product Type:
Hospital buyers weigh capital efficiency against clinical versatility when selecting lumen architectures for electrophysiology suites.
- Single-Lumen:Streamlined fluid inflation channel without integrated irrigation or sensing capabilities. Demand concentrates in ambulatory surgical centers across the United States where Medicare reimbursement constraints favor disposable cost containment over multifunctionality.
- Double-Lumen:Parallel channels enabling simultaneous irrigation and impedance monitoring during energy delivery. Academic medical centers in Germany and Japan absorb premium positioning for real-time lesion assessment in persistent atrial fibrillation cases.
- Multi-Lumen:Three or more discrete channels supporting phased electrode arrays and advanced thermocouple networks.
- Accessories:Introducer sheaths, transseptal needles, and balloon inflation syringes completing procedural kits.
Volume sits with Single-Lumen configurations; growth tilts toward Double-Lumen as sensing integration becomes standard in tertiary centers.
End User:
Site-of-care economics and case complexity determine device specification tiers across the care continuum.
- Hospitals:Integrated electrophysiology labs with dedicated arrhythmia centers performing high-volume pulmonary vein isolation. Germany's tertiary hospital systems anchor procurement through bundled catheter-and-mapping system agreements that lock in multi-year supply commitments.
- Clinics:Outpatient cardiology practices with limited ablation capability focusing on diagnostic electrophysiology studies.
- Ambulatory Surgical Centers:Freestanding facilities capturing lower-acuity atrial fibrillation cases under ASC-specific reimbursement codes in the United States.
- Research Institutes:Academic centers generating first-in-human data for novel electrode geometries under FDA and PMDA investigational device exemptions.
Procedure concentration favors Hospitals; expansion is climbing fastest in Ambulatory Surgical Centers as payors push site-of-care migration.
Technology:
Energy modality selection reflects the trade-off between lesion permanence and collateral tissue risk in specific patient populations.
- Electrophysiology:Radiofrequency energy delivery through compliant balloon electrodes with impedance-guided dosing. Japan's PMDA clinical trial obligations for first-in-class energy patterns are slowing introduction cycles for novel phased arrays in this dominant category.
- Temperature-Controlled:Closed-loop thermocouple feedback modulating power output to prevent steam pops.
- Pressure-Controlled:Contact force sensing integrated at the balloon-tissue interface to ensure stable energy transfer.
- Cryoablation:Balloon-based cryoenergy systems competing in pediatric and redo-ablation cases where tissue sparing overrides durability priorities.
Electrophysiology commands installed base; Cryoablation is gaining share fastest in pediatric subsegments where tissue preservation dictates modality choice.
Application:
Indication expansion tracks the displacement of antiarrhythmic pharmacotherapy by catheter intervention in guideline-directed care.
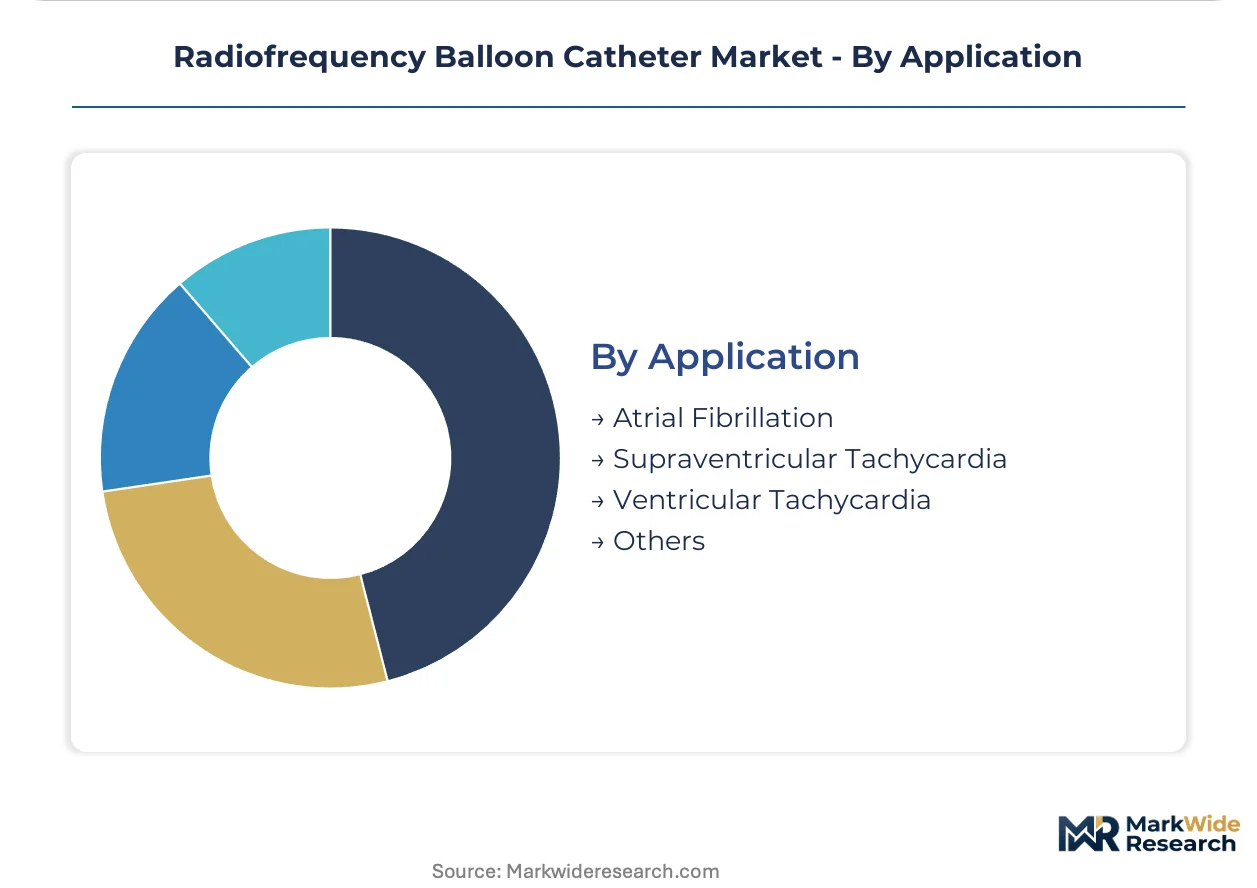
- Atrial Fibrillation:Pulmonary vein isolation and posterior wall ablation for paroxysmal and persistent forms. CMS national coverage determinations currently restricting reimbursement to antiarrhythmic drug failure cases are capping addressable volumes in United States Medicare populations.
- Supraventricular Tachycardia:Accessory pathway and atrioventricular nodal modification procedures.
- Ventricular Tachycardia:Substrate ablation in scar-related arrhythmias requiring higher energy delivery and longer procedure times.
- Others:Atypical atrial flutter, premature ventricular contraction ablation, and emerging indications.
Atrial Fibrillation drives procedure economics; Ventricular Tachycardia is expanding most quickly as substrate mapping integration improves safety profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in tertiary arrhythmia centers across Germany, Japan, and the United States, where integrated electrophysiology lab networks drive procurement of advanced catheter platforms. Hospital systems in these markets anchor volume through multi-year bundled agreements that lock in catheter-and-mapping system supply chains.
United States
Academic medical centers in Boston and Cleveland anchor domestic demand for double-lumen configurations with integrated sensing capabilities. FDA 510(k) clearance pathways shape product introduction timelines for novel electrode geometries. Medicare reimbursement policies from CMS currently restrict atrial fibrillation ablation coverage to antiarrhythmic drug failure cases, capping addressable procedure volumes in fee-for-service populations.
Germany
Tertiary hospital systems in Munich and Heidelberg drive procurement of multi-electrode phased radiofrequency arrays for persistent atrial fibrillation cases. EU MDR technical documentation requirements mandate systematic clinical follow-up and active implant registries for Class III cardiac devices. The country's electrophysiology service line directors wield centralized authority over capital and consumable budgets within integrated delivery networks.
Japan
PMDA clinical trial obligations for first-in-class energy delivery patterns extend product introduction cycles by twelve to eighteen months beyond FDA timelines. Tokyo and Osaka cluster the nation's highest-volume arrhythmia centers, where electrophysiologist training programs produce specialized operators for complex pulmonary vein isolation procedures. METI industrial policy supports domestic medical device manufacturing through targeted R&D subsidies.
United Kingdom
NHS England procurement frameworks favor single-lumen configurations in ambulatory settings where cost containment overrides multifunctionality requirements. The London cardiovascular cluster concentrates specialized fellowship programs that feed operator pipelines for expanding electrophysiology lab capacity. MHRA post-Brexit regulatory alignment with EU MDR documentation standards maintains continuity in device approval pathways.
Switzerland
Swissmedic oversight of high-risk cardiac devices maintains stringent quality management system requirements that advantage incumbent suppliers with established European notified body relationships. The Basel-Zurich corridor hosts concentrated medical technology R&D infrastructure supporting next-generation catheter platform development. Cantonal hospital networks procure through centralized tenders that bundle catheter supplies with mapping system maintenance contracts.
Radiofrequency Balloon Catheter Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device manufacturers commanding premium positioning in academic medical centers while specialized catheter fabricators serve cost-sensitive ambulatory settings. The vendor base organizes into three tiers: multinational conglomerates with captive extrusion capabilities, mid-scale electrophysiology-focused platforms, and regional OEM suppliers. Consolidation pressure is accelerating through strategic partnerships between mapping system vendors and catheter manufacturers, alongside backward integration into polymer supply chains.
Among diversified medical technology conglomerates, Medtronic, Boston Scientific Corporation, and Abbott Laboratories exemplify the integrated-platform archetype. Medtronic leverages in-house polymer extrusion to control material cost curves across its portfolio. Boston Scientific Corporation occupies a position defined by temperature-sensing integration at the balloon-tissue interface. Abbott Laboratories anchors European electrophysiology lab contracts through bundled catheter-and-mapping system agreements that tie multi-year supply commitments to procedure volume guarantees.
| Leading Market Players |
|---|
| Medtronic |
| Biosense Webster, Inc. |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Becton Dickinson and Company |
| Terumo Corporation |
| Stryker Corporation |
| Teleflex Incorporated |
| Others |
Value Network & Pricing Analysis
Captive polymer extrusion capabilities at Medtronic anchor both supply security and pricing power across the radiofrequency balloon catheter market, insulating integrated manufacturers from input cost volatility while forcing contract manufacturers into transactional competition on single-lumen configurations.
Pricing Analysis
Volume concentrates in single-lumen configurations where Medicare reimbursement constraints at United States ambulatory surgical centers enforce cost containment; academic medical centers in Germany and Japan absorb premium positioning for double-lumen sensing integration. Three-tier pricing structure across premium, standard, and economy levels separates phased electrode arrays with thermocouple feedback from basic fluid-inflation designs. Pricing pressure stems from cryoablation substitution in pediatric and redo-ablation segments. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks in Germany least.
Supply Chain Analysis
Refurbishment flows for mapping system consoles and catheter introducer sheaths create secondary supply channels that compete with new production in cost-sensitive segments. Specialized polyurethane resin production concentrates in Germany, Japan, and the United States; platinum-iridium electrode alloys draw from limited precious metal refiners. Single-source vulnerability pervades qualified polymer extruders serving Class III cardiac device specifications. Distribution runs through hospital procurement committees and group purchasing organizations with multi-year contract lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR technical documentation burdens and extended FDA 510(k) timelines are consolidating competitive position around incumbent suppliers with established quality management systems, forcing smaller entrants toward contract manufacturing or exit.
For Market Incumbents: Acquire specialized polymer extrusion assets to deepen captive supply control over polyurethane balloon membrane production. Secure backward integration into thermocouple sensor manufacturing to defend margin position against temperature-sensing integration demands from Boston Scientific Corporation's competitive positioning. Lock multi-year bundled catheter-and-mapping system agreements with Germany's integrated delivery networks before procurement centralization completes. For New Entrants and Emerging Players: Launch via ambulatory surgical center-focused distribution partnerships targeting United States Medicare reimbursement tiers underserved by premium double-lumen configurations. Concentrate initial penetration on single-lumen cost-optimized designs for lower-acuity atrial fibrillation cases. Pursue white space in Swiss and United Kingdom outpatient cardiology practices with limited ablation capability. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by mapping system vendors seeking catheter compatibility integration. The five-to-ten-year viability window favors electrophysiology-focused platforms with FDA 510(k) predicate device portfolios over diversified conglomerates. Target acquisition archetype: mid-scale catheter fabricators with established European notified body relationships. Monitor CMS national coverage determination expansion beyond antiarrhythmic drug failure criteria as inflection indicator for addressable procedure volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation for Class III cardiac devices mandates systematic clinical follow-up and active implant registries. |
| Hospital System Partnership | Bundled catheter-and-mapping system agreements with Germany's integrated delivery networks lock multi-year supply commitments. |
| Reimbursement Strategy | CMS national coverage determination expansion would reshape Medicare addressable volumes beyond antiarrhythmic drug failure criteria. |
| FDA Submission | 510(k) clearance timelines for novel electrode geometries extend product introduction cycles and delay revenue recognition. |
| Software Companion Development | Integration of impedance sensing with temperature monitoring at the balloon-tissue interface enables real-time lesion assessment differentiation. |
Research Methodology
Multi-period observation of catheter ablation procedure volumes, electrophysiology lab capacity expansion, and regulatory clearance timelines anchored the trend analysis, supplemented by interviews with electrophysiologists, hospital purchasing committee directors, biomedical engineers, and group purchasing organization contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement data, and hospital procurement records. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to converge volume and value outputs.
Input-output matrix framing structured the analytical approach across the projection horizon, modeling segmentation dimensions including lumen configuration, end-user site-of-care tier, energy delivery technology, and arrhythmia indication severity. CAGRs were derived from procedure volume trajectory analysis against device utilization rates per intervention. Industry-specific forecast inputs incorporated electrophysiologist training pipeline capacity and mapping system installed base evolution.
The model assumes a particular technology adoption path; alternative pathways for cryoablation substitution in pediatric and redo-ablation segments would alter the outlook. Forecasts reflect documented assumptions regarding CMS reimbursement expansion timing and EU MDR post-market surveillance compliance cost trajectories. Practitioners should monitor PMDA clinical trial obligation enforcement patterns and polyurethane resin supply concentration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
China Vascular Grafts Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Resuscitation Bags Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
Pulmonary Stents Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
Perfusion Systems Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Global Ventricular Assist Device Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market