
 Infusion System Market | 2026-2036
Infusion System Market Size, Share, and Industry Trends Forecast 2026-2036
Infusion System Market Outlook
Buyer concentration among hospital procurement networks is realigning how infusion system vendors structure their sales operations. Becton, Dickinson and Company leverages its broad portfolio to anchor contracts with integrated delivery networks across multiple geographies. Fresenius Kabi competes through specialized parenteral nutrition and fluid therapy systems that dominate European hospital tenders. Baxter International sustains its position via deep manufacturing scale in intravenous solutions and pump hardware.
An infusion system comprises electromechanical or gravity-driven apparatus designed to deliver fluids, medications, or nutrients into a patient's circulatory system with controlled flow rates measured in milliliters per hour. These systems integrate pumping mechanisms, disposable administration sets, and safety software to prevent dosing errors in acute and ambulatory care settings. Infusion pumps command the largest revenue share among product types due to recurring consumable attachments and software upgrade cycles. Smart infusion devices represent the fastest-growing technology segment as dose-error reduction software becomes mandatory for hospital accreditation. Home healthcare end users are expanding fastest structurally, though hospitals still capture the dominant margin pool through capital equipment purchases and long-term service agreements.
FDA premarket notification requirements and EU MDR technical documentation obligations shape product development timelines and market access barriers for infusion system manufacturers. ISO 80369 small-bore connector standards and IEC 60601 electrical safety protocols further constrain design choices while reducing interoperability risks across device ecosystems. Stakeholders must monitor evolving cybersecurity guidance from FDA and notified bodies as wireless connectivity and cloud-based dose libraries become standard features in next-generation pumps.
Market Dynamics
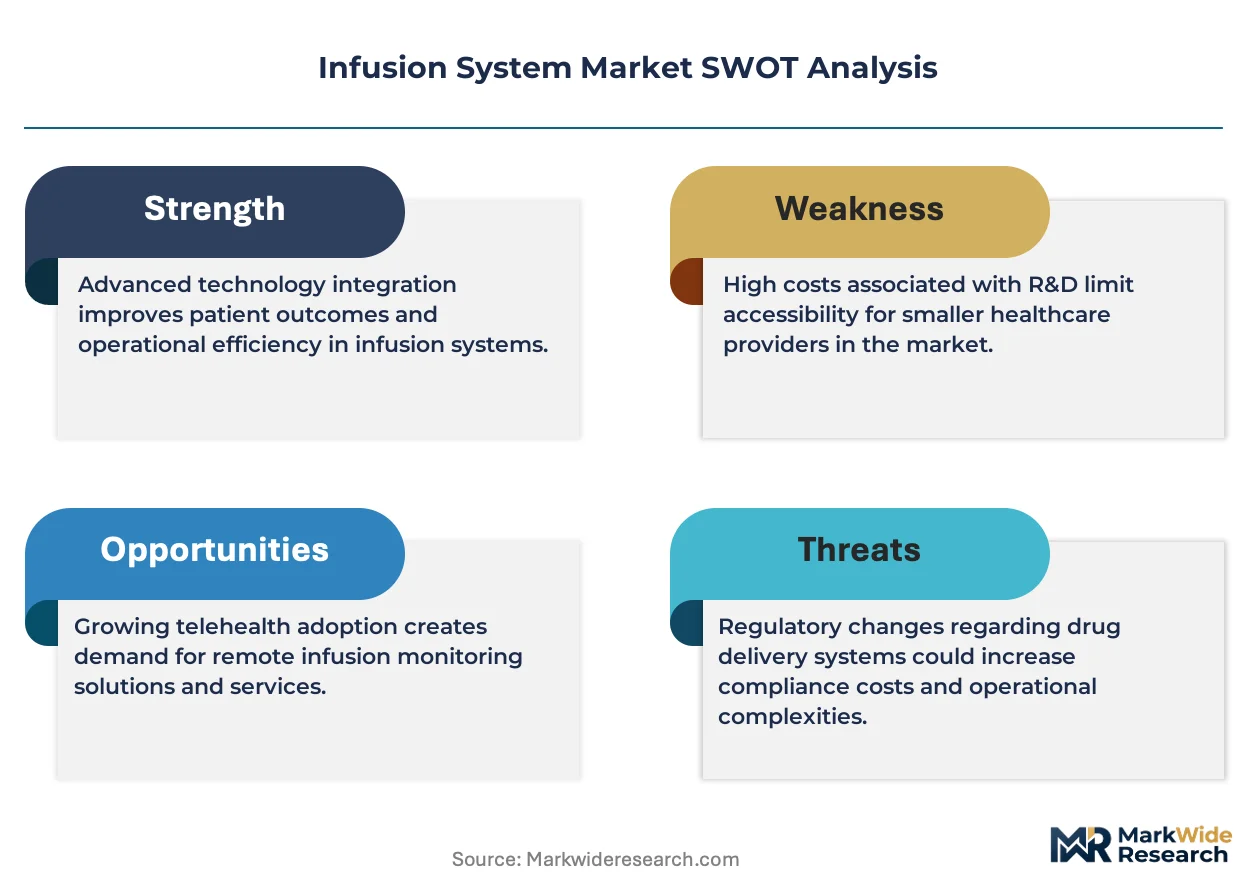
Smart infusion devices with dose-error reduction software are compressing the competitive window for legacy pump manufacturers as hospital accreditation standards harden. FDA premarket notification pathways and EU MDR technical documentation requirements are extending product development cycles while elevating barriers for new entrants.
Growth Catalysts
- FDA premarket notification (510(k)) requirements:Mandatory dose-error reduction software for hospital accreditation is accelerating replacement cycles for aging pump fleets across acute care networks.
- Home healthcare end users:Patient preference for alternatives to extended hospital stays is expanding ambulatory infusion pump demand through Medicare reimbursement pathways.
- ISO 80369 small-bore connector standards:Interoperability mandates are forcing standardization across device ecosystems, reducing switching costs for integrated delivery networks.
Market Restraints
- EU MDR technical documentation obligations:Extended conformity assessment timelines are delaying market access for novel infusion technologies by 12-24 months.
- Specialized polymer supply concentration:Medical-grade polycarbonate and polyurethane feedstock dependence on German and Japanese chemical suppliers creates input cost volatility.
- Gravity-driven infusion sets:Low-cost alternatives constrain pricing power for electromechanical pump systems in emerging market tenders.
Strategic Opportunities
- Japan's aging population:Chronic disease prevalence in the world's oldest society sustains procurement volumes for ambulatory chemotherapy and parenteral nutrition systems.
- Cloud-based dose library connectivity:Wireless pump networks enabling real-time drug library updates across hospital systems represent untapped recurring revenue streams.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are creating localized production hubs for export-oriented infusion component suppliers.
Industry Challenges
- Cybersecurity talent scarcity:FDA guidance on wireless device security is outpacing the availability of biomedical engineers with embedded systems security expertise.
- IEC 60601-1-2 electromagnetic compatibility testing:Fourth-edition compliance for wireless-enabled pumps requires capital-intensive anechoic chamber investments.
- Legacy hospital IT integration:HL7 FHIR interoperability with decades-old electronic health record architectures creates deployment friction for smart infusion platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infusion System Market |
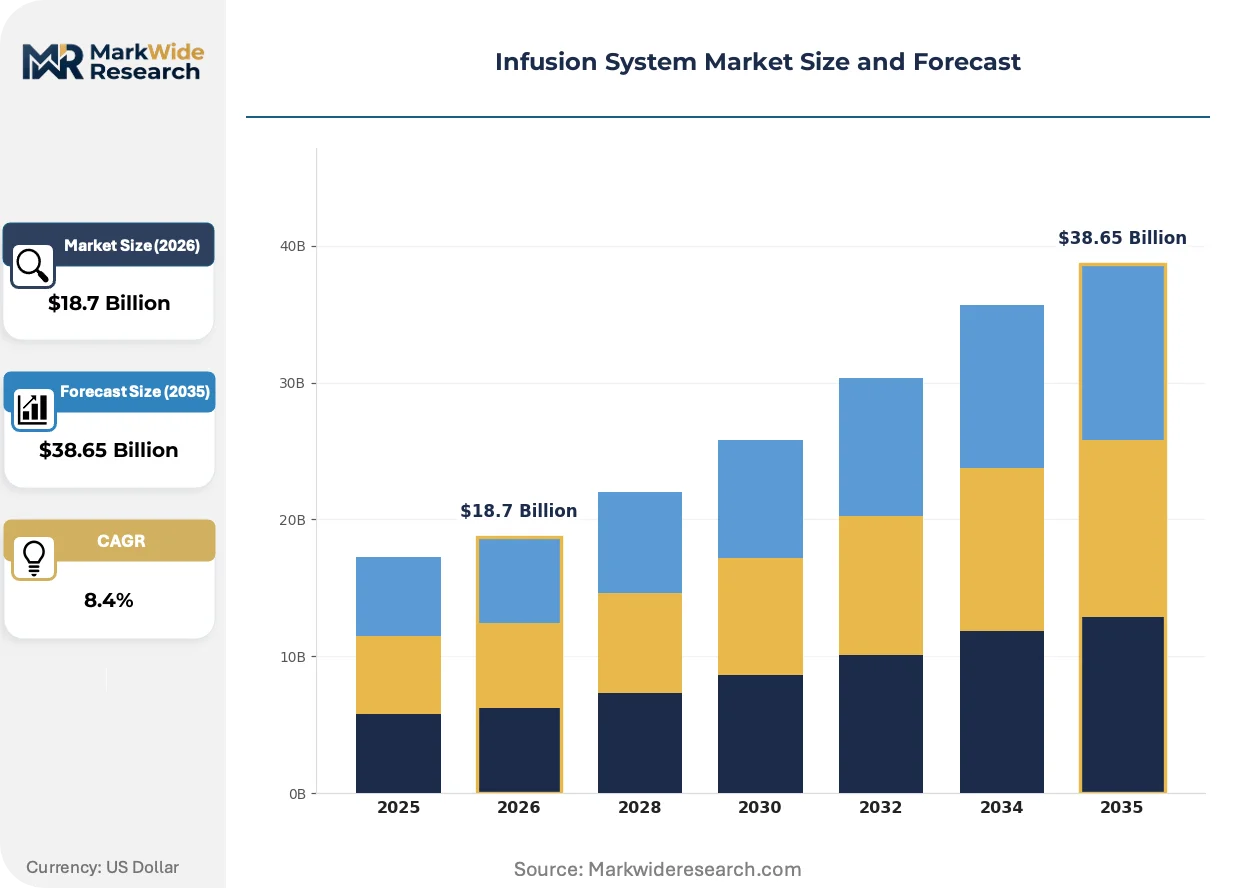
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Pumps, IV Sets, Implantable Devices, Blood Transfer Devices End User: Hospitals, Home Healthcare, Ambulatory Surgical Centers, Specialty Clinics Application: Chemo Therapy, Pain Management, Nutritional Support, Hydration Therapy Technology: Electronic Pumps, Gravity Systems, Smart Infusion Devices, Pressure-Driven Systems |
| Companies Covered | Becton, Dickinson and Company, B. Braun Melsungen, Baxter International, Medtronic, ICU Medical, Terumo Corporation, Fresenius Kabi, Smiths Medical, Tandem Diabetes Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infusion System Market Strategic Shifts
Software-defined dosing architectures are displacing hardware-centric pump designs across acute care settings. This transformation is compressing product lifecycles while expanding the addressable market for subscription-based clinical decision support.
Closed-loop infusion systems with integrated physiological sensors are consolidating anesthesia and intensive care workflows around single-vendor platforms. Academic medical centers in the United States are piloting these systems for insulin and vasopressor titration. The technology is consolidating purchasing authority within hospital pharmacy and anesthesiology departments away from general biomedical engineering.
EU MDR Article 10 post-market surveillance requirements are mandating systematic collection of real-world device performance data. Manufacturers must now maintain active implantable-style vigilance systems for Class IIa infusion pumps. German notified bodies are enforcing this through unannounced manufacturing site audits, compressing margins for firms with limited European regulatory affairs capacity.
Hospital procurement networks are unbundling capital equipment purchases from long-term service agreements. Integrated delivery networks in the United States now favor per-patient-per-day pricing models that transfer utilization risk to device vendors. This shift is most visible in multi-hospital systems across Texas and Florida where private equity-backed consolidation has centralized purchasing authority.
Infusion System Market Segmentation
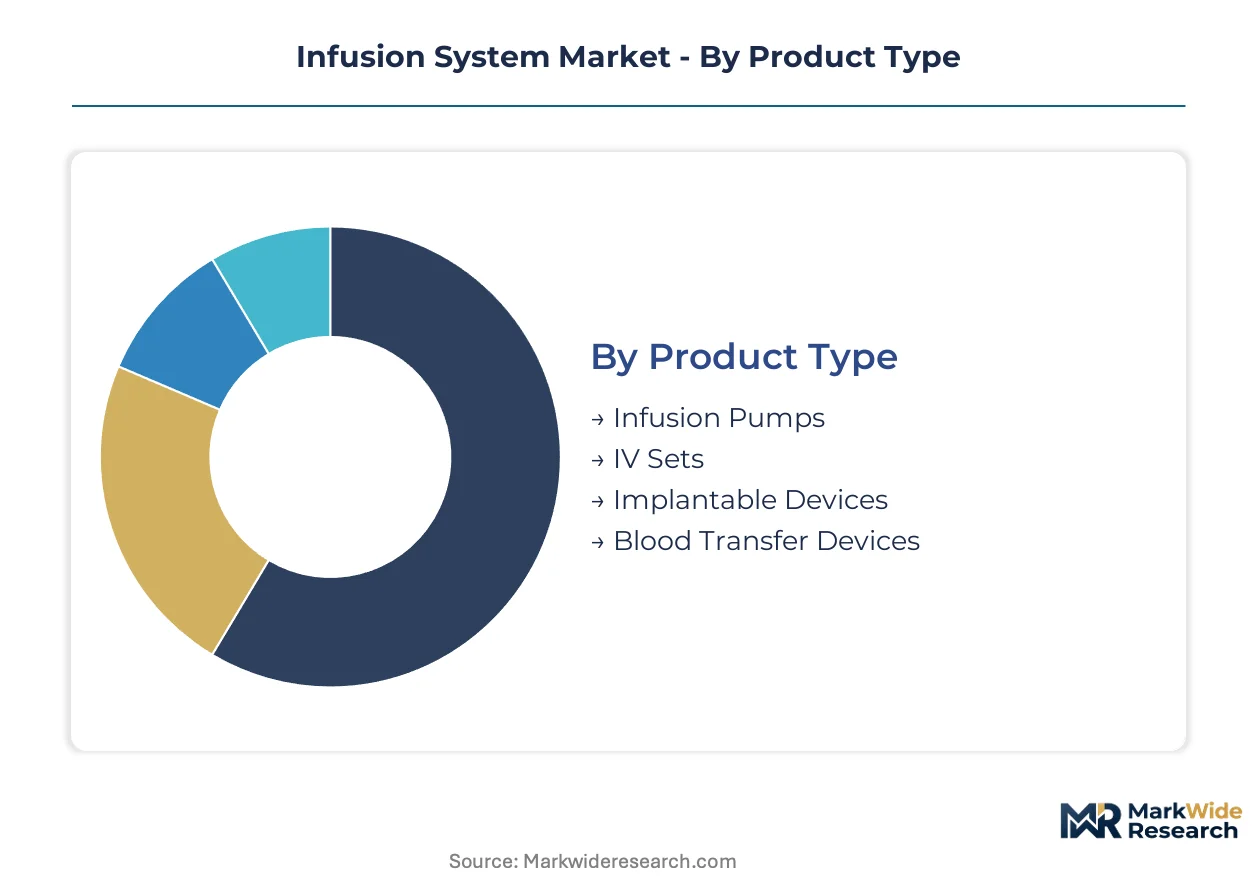
Infusion system procurement patterns diverge sharply across clinical settings and technological tiers. Understanding these segment boundaries reveals where replacement capital concentrates and which applications justify premium pricing for connectivity-enabled platforms.
Product Type:
Upgrade cycles for legacy electromechanical hardware are accelerating as FDA dose-error reduction mandates harden hospital accreditation standards.
- Infusion Pumps:Electromechanical devices with programmable flow rates measured in milliliters per hour, integrating peristaltic or syringe pumping mechanisms with disposable administration sets. Demand concentrates in United States integrated delivery networks replacing aging fleets to meet Joint Commission safety requirements; recurring revenue from consumable attachments and software subscriptions sustains vendor margins.
- IV Sets:Disposable tubing assemblies with drip chambers, roller clamps, and needle-free connectors for gravity or pump-assisted fluid delivery. German hospital procurement networks are standardizing on ISO 80369-3 compliant enteral connectors, forcing inventory turnover for legacy Luer designs.
- Implantable Devices:Subcutaneous ports and programmable pumps for long-term chemotherapy or pain management.
- Blood Transfer Devices:Specialized warming and filtration systems for transfusion medicine.
Volume placements concentrate in Infusion Pumps; the faster expansion belongs to Implantable Devices as oncology shifts toward ambulatory care models.
End User:
Cost-tier stratification separates capital-intensive hospital purchases from reimbursement-dependent home healthcare deployments.
- Hospitals:Acute care networks with centralized biomedical engineering departments managing multi-thousand-unit pump fleets. United States health systems in Texas and Florida are unbundling equipment purchases from service agreements, shifting toward per-patient-per-day pricing that transfers utilization risk to vendors.
- Home Healthcare:Medicare-reimbursed ambulatory infusion for chemotherapy, parenteral nutrition, and antibiotic therapy. Japan's aging population sustains procurement volumes for portable elastomeric and electronic pumps as patients seek alternatives to extended hospital stays.
- Ambulatory Surgical Centers:Same-day procedure facilities requiring compact, rapid-turnaround infusion platforms.
- Specialty Clinics:Dialysis and oncology centers with dedicated infusion workflows.
Margin concentration sits with Hospitals; Home Healthcare is climbing the fastest as reimbursement pathways mature and patient preference shifts.
Application:
Clinical outcome requirements determine whether basic gravity systems suffice or smart pumps with dose-error reduction software become mandatory.
- Chemo Therapy:High-risk vesicant administration requiring precise flow control and occlusion detection. Academic medical centers in the United States are piloting closed-loop systems with integrated physiological sensors for insulin and vasopressor titration, consolidating purchasing authority within pharmacy departments.
- Pain Management:Patient-controlled analgesia and epidural infusion with programmable bolus limits.
- Nutritional Support:Enteral and parenteral feeding systems for malabsorption and critical care.
- Hydration Therapy:Fluid resuscitation and maintenance protocols across emergency and surgical settings.
Regulatory scrutiny intensifies in Chemo Therapy; Pain Management is gaining share fastest as ambulatory surgical volumes expand.
Technology:
Supply concentration in semiconductor and sensor components is reshaping which technology platforms can achieve manufacturing scale.
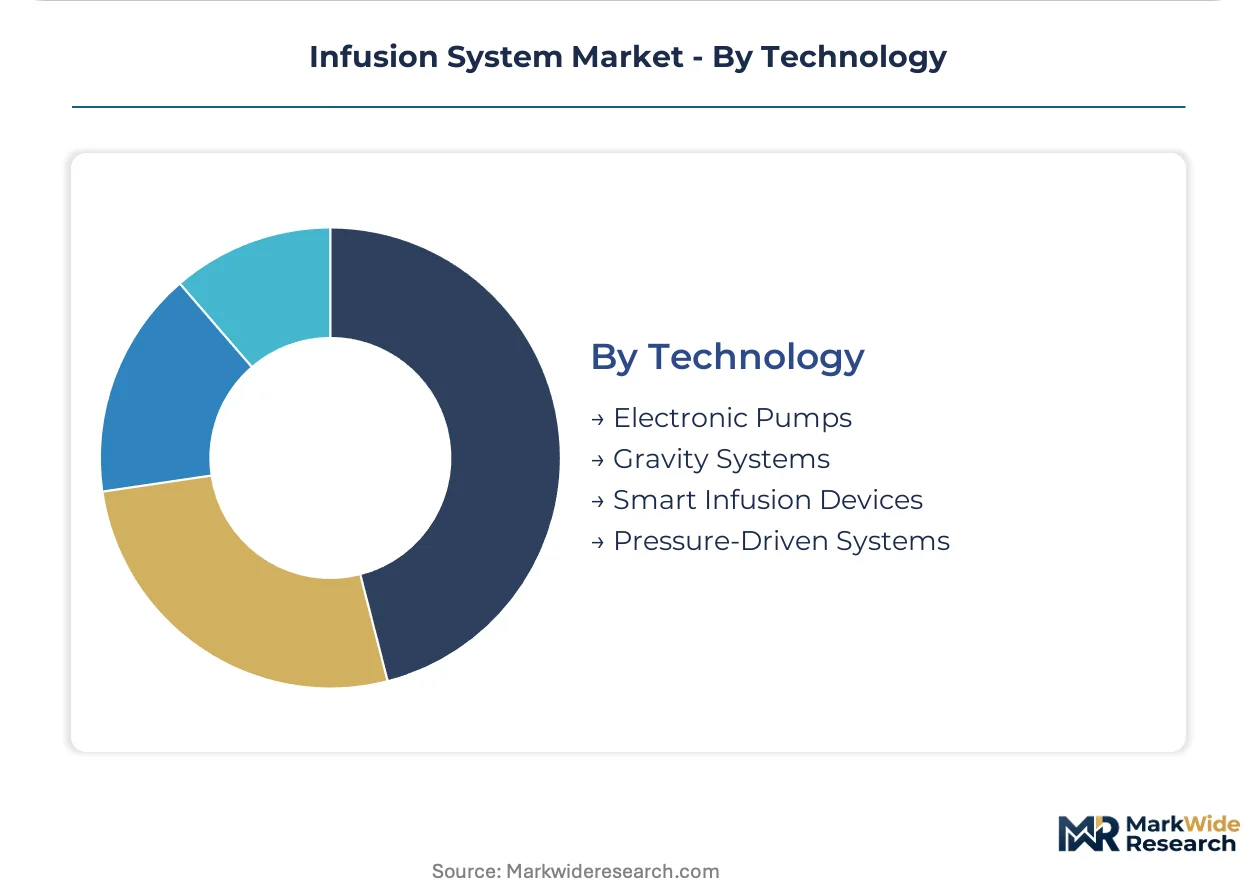
- Smart Infusion Devices:Wireless-enabled pumps with cloud-connected dose libraries, drug error reduction software, and real-time interoperability with electronic health records. FDA cybersecurity guidance and EU MDR post-market surveillance requirements are extending development timelines while elevating barriers for new entrants.
- Electronic Pumps:Microprocessor-controlled volumetric and syringe platforms with basic programming capabilities.
- Gravity Systems:Simple drip-rate regulators for cost-sensitive emerging market tenders and backup scenarios.
- Pressure-Driven Systems:Elastomeric balloon pumps for ambulatory chemotherapy and antibiotic delivery.
Installed base dominance remains with Electronic Pumps; Smart Infusion Devices show the steepest expansion trajectory as hospital accreditation standards mandate dose-error reduction capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for infusion systems concentrates in health systems with aging demographics and mature reimbursement frameworks. Procurement volumes track chronic disease prevalence and hospital consolidation patterns rather than population scale alone.
United States
Integrated delivery networks in Texas and Florida are unbundling equipment purchases from service agreements, shifting toward per-patient-per-day pricing models. FDA dose-error reduction mandates for Joint Commission accreditation are accelerating replacement cycles for aging pump fleets. The Boston-Cambridge corridor anchors development activity for closed-loop infusion systems with integrated physiological sensors.
Germany
German hospital procurement networks dominate European tenders for specialized parenteral nutrition and fluid therapy systems. EU MDR technical documentation obligations and unannounced manufacturing site audits by German notified bodies are compressing margins for firms with limited regulatory affairs capacity. The Rhine-Ruhr industrial cluster sustains concentration in medical-grade polymer feedstock supply.
Japan
The world's oldest society sustains procurement volumes for ambulatory chemotherapy and parenteral nutrition systems as patients seek alternatives to extended hospital stays. METI and PMDA oversight of software-enabled medical devices elevates barriers for wireless pump networks. The Kanto region around Tokyo anchors domestic manufacturing of portable elastomeric and electronic pumps.
India
Domestic manufacturing incentives under the PLI scheme for medical devices are creating localized production hubs for export-oriented infusion component suppliers. CDSCO medical device regulations are aligning with international standards for small-bore connector interoperability. The Maharashtra-Gujarat industrial corridor is consolidating contract manufacturing for gravity-driven infusion sets serving emerging market tenders.
United Kingdom
NHS procurement frameworks are standardizing on smart infusion devices with cloud-connected dose libraries across acute care networks. MHRA post-market surveillance requirements mirror EU MDR vigilance obligations for Class IIa infusion pumps. The Oxford-Cambridge-London golden triangle concentrates health technology assessment and early adoption of software-defined dosing architectures.
Infusion System Market Competitive Environment
United States producers anchor one tier of the market; German and Japanese specialists hold differentiated positions in precision fluid therapy and polymer-intensive disposable systems. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with broad hospital contracting leverage, specialized infusion therapy pure-plays with deep clinical workflow expertise, and emerging connectivity-focused platforms betting on subscription-based clinical decision support. Competitive moves concentrate on M&A to fill portfolio gaps in smart pump software and strategic partnerships with cloud infrastructure providers for wireless dose library deployment.
Among diversified conglomerates, Becton, Dickinson and Company and Baxter International occupy positions defined by scale and integrated delivery network penetration. Fresenius Kabi represents the specialized European archetype with concentrated strength in parenteral nutrition systems. These three anchors exemplify how competitive positioning stratifies between breadth-focused contract winners and depth-focused clinical specialists.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| B. Braun Melsungen |
| Baxter International |
| Medtronic |
| ICU Medical |
| Terumo Corporation |
| Fresenius Kabi |
| Smiths Medical |
| Tandem Diabetes Care |
| Others |
Value Chain & Pricing Dynamics
EU MDR post-market surveillance mandates and FDA cybersecurity guidance for wireless-enabled devices gate access to premium-tier pricing for infusion system manufacturers. These compliance requirements concentrate qualified supply among vendors with established regulatory affairs capacity, while hospital procurement networks exploit this concentration to compress margins through per-patient-per-day pricing models.
Pricing Analysis
Volume placements concentrate in electronic pumps while margins accrue to smart infusion devices with dose-error reduction software. Three-tier pricing structure across premium smart pumps, standard electronic platforms, and economy gravity systems reflects FDA certification tier and software connectivity depth. Pricing pressure stems from integrated delivery networks unbundling capital purchases from service agreements in United States hospital systems. Home healthcare buyers exhibit highest price sensitivity due to Medicare reimbursement caps, whereas academic medical centers accept premium pricing for closed-loop systems with integrated physiological sensors.
Supply Chain Analysis
ISO 80369 small-bore connector compliance and IEC 60601 electrical safety certification gate supplier qualification for electromechanical pump assembly. Medical-grade polycarbonate and polyurethane feedstock concentrates in German and Japanese chemical manufacturing clusters, with semiconductor sensor components sourcing from Taiwanese and South Korean fabrication facilities. Single-source vulnerability in specialized polymer supply creates input cost volatility during feedstock allocation cycles. Distribution runs through hospital procurement networks and group purchasing organizations in United States acute care markets, with direct-to-provider channels dominating European tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU MDR technical documentation obligations and FDA premarket notification requirements create barrier-to-entry moats favoring established players with dedicated regulatory affairs infrastructure.
For Market Incumbents: Deploy cloud-based dose library connectivity as a recurring revenue lever to offset capital equipment margin compression from per-patient-per-day pricing models. Consolidate manufacturing scale in intravenous solutions and pump hardware to defend against emerging connectivity-focused platforms. Deepen hospital system partnerships through long-term service agreements that transfer utilization risk while locking out replacement vendors. For New Entrants and Emerging Players: The premium-to-economy price gap in ambulatory surgical center infusion platforms offers white-space entry for compact, rapid-turnaround systems without full smart-pump certification. Target India's PLI scheme for medical devices to establish localized production hubs serving emerging market tenders for gravity-driven infusion sets. Pursue software companion development partnerships with established pump hardware manufacturers to circumvent capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Unannounced manufacturing site audits by German notified bodies enforcing EU MDR Article 10 requirements is the leading indicator that regulatory affairs capacity will determine acquisition premiums across the next decade. Target mid-cap infusion therapy pure-plays with deep clinical workflow expertise and existing notified body relationships. Watch for FDA cybersecurity guidance finalization as the signal that wireless pump network deployment will accelerate consolidation toward software-defined dosing architectures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Premarket notification for dose-error reduction software accelerates hospital fleet replacement cycles under Joint Commission mandates. |
| CE Marking Pathway | EU MDR technical documentation compliance extends market access timelines while elevating barriers for non-European competitors. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and Florida consolidate purchasing authority through per-patient-per-day pricing models. |
| Software Companion Development | Cloud-connected dose libraries enable real-time drug library updates across hospital wireless pump networks. |
| Reimbursement Strategy | Medicare pathway expansion for home healthcare ambulatory infusion sustains procurement volumes for portable elastomeric pumps. |
Study Parameters
Independent corroboration across hospital procurement databases, FDA 510(k) filings, and EU MDR notified body documentation underwrites the qualitative findings in this analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs directors at infusion system manufacturers were combined with secondary validation from CMS Medicare reimbursement data, hospital capital expenditure disclosures, and medical device trade flow records. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates across product type, end user, application, and technology tiers.
Rate-of-change decomposition across installed base replacement cycles, software upgrade adoption curves, and reimbursement pathway maturation anchors the analytical framework. Segmentation dimensions modeled include pump mechanism type, care setting intensity, clinical application risk tier, connectivity architecture, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to smart infusion device penetration patterns and hospital capital equipment budget trajectories. Forecast inputs incorporate FDA dose-error reduction mandate compliance deadlines and EU MDR transition timeline constraints.
Inputs from hospital procurement databases and notified body audit schedules were available through the study window; gaps in real-time wireless pump network deployment metrics introduce uncertainty bands around smart device adoption trajectories. Forecasts reflect assumptions regarding Joint Commission accreditation standard evolution and Medicare reimbursement stability for home healthcare infusion. A model refresh is warranted upon material change in FDA cybersecurity guidance finalization or EU MDR post-market surveillance enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Artificial Blood Vessels Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Cardiovascular Surgical Devices Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
Vascular Screening Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market