
 Global Portable Magnetic Resonance Imaging Market | 2026-2036
Global Portable Magnetic Resonance Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Magnetic Resonance Imaging Market Foresight
Chinese magnet manufacturers and Korean component suppliers is hardening around cryogen-free architectures, tightening supply availability for Western OEMs. Siemens Healthineers leverages its superconducting legacy to dominate high-specification installations in tertiary hospitals. GE HealthCare anchors its position through backward integration into gradient coil production, shielding margins from rare-earth volatility. Hyperfine Inc. differentiates via software-defined radiofrequency pathways that slash power requirements for bedside deployment.
Portable magnetic resonance imaging denotes self-contained MRI systems engineered for transport between clinical settings, typically operating below 1.5 Tesla with total system weights under 500 kilograms and power draw compatible with standard wall outlets; these units enable diagnostic imaging at the point of care without fixed infrastructure requirements. Compact MRI and cryogen-free variants are capturing disproportionate investment as helium scarcity and site preparation costs drive procurement criteria away from conventional superconducting platforms. Permanent magnet technology occupies the largest installed base, though zero helium MRI architectures represent the fastest-expanding margin pool as health systems prioritize total cost of ownership over acquisition price.
FDA 510(k) pathways for low-field devices and the EU MDR's strengthened clinical evidence requirements for novel imaging modalities are bifurcating market access timelines between the United States and Europe. China's NMPA has accelerated review tracks for domestically manufactured compact systems, tilting competitive dynamics toward local producers in the world's second-largest imaging market. Stakeholders must monitor regulatory divergence on AI-assisted reconstruction algorithms, as divergent approval standards threaten to fragment software ecosystems across jurisdictions.
Market Dynamics
The portable MRI market pivots on helium supply disruption and cryogen-free magnet maturation, forcing procurement criteria toward total lifecycle cost rather than upfront capital expenditure.
Growth Catalysts
- Rural hospital network expansion:China's county-level healthcare infrastructure buildout creates procurement pull for compact, cryogen-free systems that operate without specialized facilities.
- FDA 510(k) pathway evolution:Streamlined clearance protocols for low-field devices accelerate product development timelines for manufacturers targeting bedside deployment scenarios.
- Permanent magnet reliability:Advances in rare-earth magnet stabilization enable consistent field homogeneity without cryogenic cooling infrastructure.
Market Restraints
- Gradient coil supply concentration:Korean and Chinese component suppliers control rare-earth processing and coil winding capacity, exposing Western OEMs to input volatility.
- Image resolution ceiling:Low-field architectures face inherent signal-to-noise limitations that constrain diagnostic confidence for certain neurological and musculoskeletal applications.
- EU MDR clinical evidence requirements:Strengthened post-market surveillance mandates for novel imaging modalities extend market access timelines relative to United States pathways.
Strategic Opportunities
- India's tertiary hospital procurement:Government insurance expansion and medical tourism investment create demand for point-of-care diagnostics in tier-2 cities.
- AI-assisted reconstruction algorithms:Machine learning compensation for low-field signal gaps opens diagnostic equivalence with conventional high-field systems.
- Emergency medical services integration:Pre-hospital stroke and trauma protocols in Germany and Japan create new channel demand for ambulance-compatible imaging.
Industry Challenges
- Specialized field service engineer scarcity:Superconducting and cryogen-free architectures require distinct maintenance skill sets that training pipelines have not matched.
- PACS integration complexity:Legacy hospital information systems demand costly middleware development for seamless portable MRI data flow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Magnetic Resonance Imaging Market |
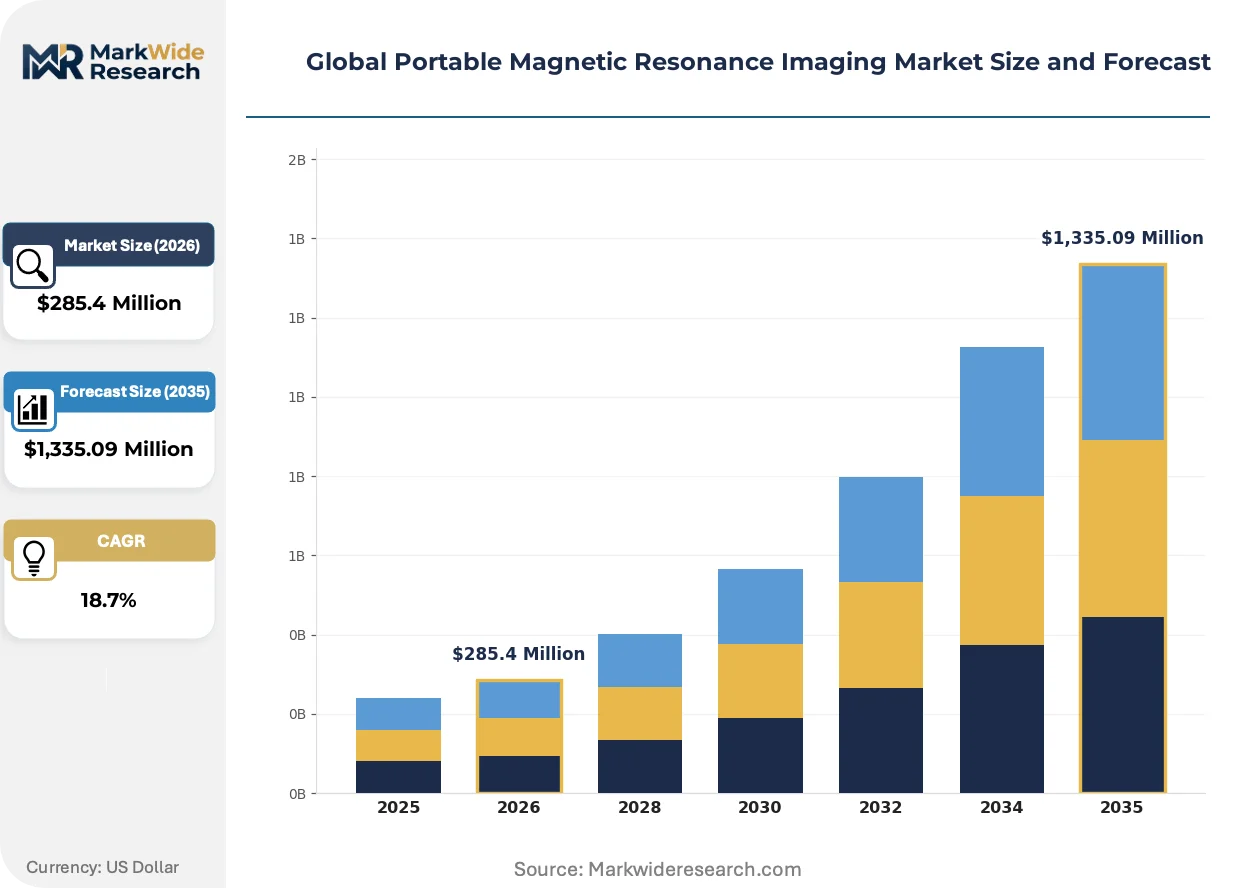
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,335.09 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Field MRI, Ultra-Low-Field MRI, Cryogen-Free MRI, Compact MRI Technology: Permanent Magnet, Resistive Magnet, Superconducting Magnet, Zero Helium MRI Application: Neurology, Musculoskeletal Imaging, Cardiology, Oncology End User: Diagnostic Centers, Mobile Clinics, Research Institutes, Emergency Medical Services |
| Companies Covered | Hyperfine Inc., Siemens Healthineers, Canon Medical Systems, Voxelgrids Innovations Pvt. Ltd., GE HealthCare, Koninklijke Philips N.V., Aspect Imaging Ltd., PrizMed Imaging Solution Inc., Esaote SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Magnetic Resonance Imaging Market Shifts & Advancements
Software-defined radiofrequency architectures and permanent magnet stabilization are compressing the boundary between fixed-site and portable diagnostic capability.
Zero-helium MRI is modularizing system design by eliminating cryogenic infrastructure requirements. Emergency departments and intensive care units adopt these architectures fastest, drawn by plug-and-play installation timelines measured in hours rather than weeks. The technology is modularizing supply chains as magnet, gradient, and RF subsystems become independently sourceable and field-replaceable.
China's NMPA has accelerated review tracks for domestically manufactured compact systems, compressing regulatory timelines for local producers versus imported competitors. This bifurcation pressures multinational OEMs to establish in-country manufacturing or risk exclusion from provincial procurement tenders. Domestic producers respond by prioritizing NMPA submissions over FDA or CE marking sequences.
Acute care facilities now bundle imaging hardware with per-scan service fees rather than capital purchase models. This unbundling displaces traditional equipment financing in United States health systems facing reimbursement compression. The shift is most visible in stroke network hospitals where bed-day economics favor rapid deployment over throughput maximization.
Global Portable Magnetic Resonance Imaging Market Segmentation
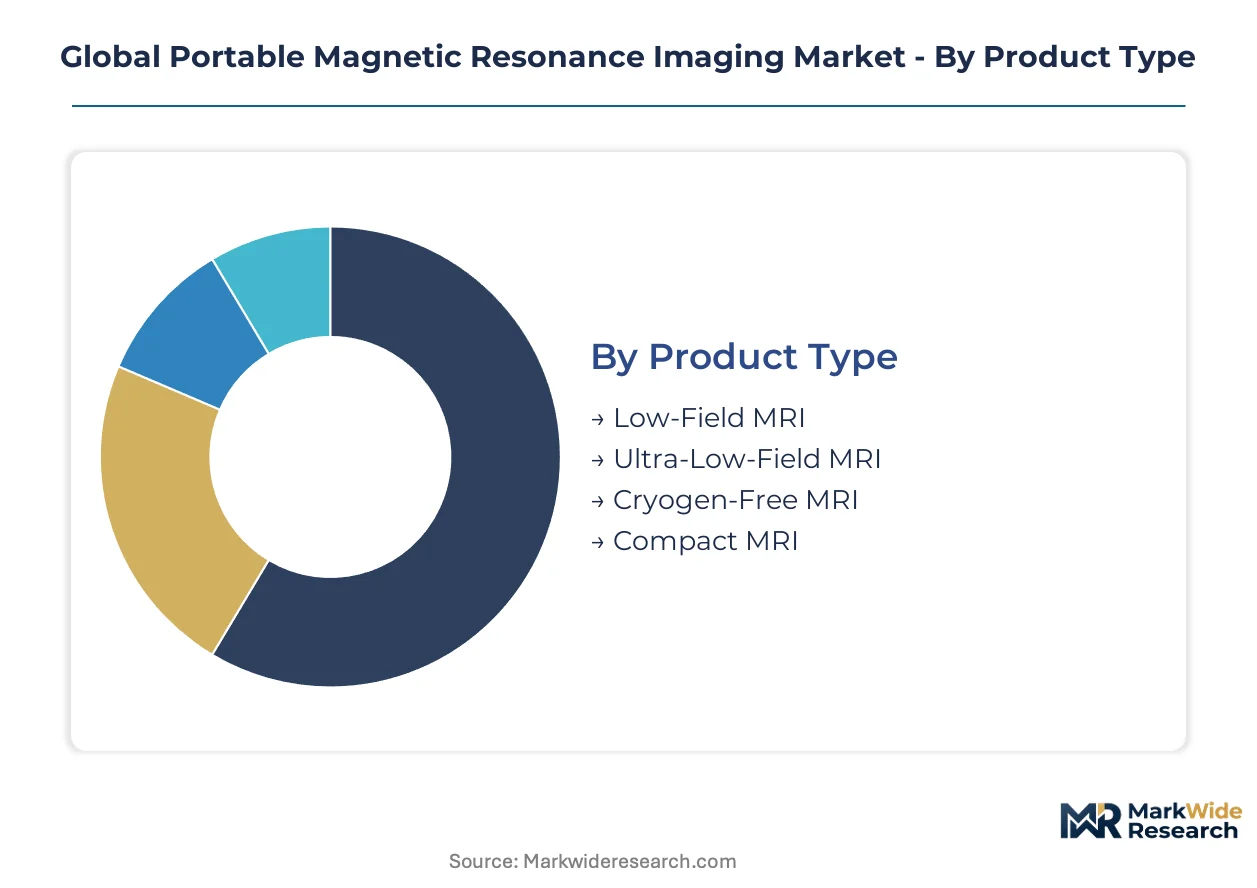
Portable MRI segmentation reflects divergent technical architectures competing to replace fixed-site systems. Procurement criteria increasingly weight total lifecycle cost against diagnostic performance thresholds.
Product Type:
Upgrade cycles accelerate where cryogen-free designs eliminate helium dependency and site preparation burden.
- Low-Field MRI:Systems operating between 0.2 and 0.5 Tesla with permanent or resistive magnets. China's county hospitals favor these units for rapid deployment without specialized infrastructure.
- Cryogen-Free MRI:Eliminates liquid helium cooling through conduction-cooled superconducting or advanced permanent magnet designs. Emergency departments in Germany and Japan adopt these fastest due to plug-and-play installation timelines.
- Ultra-Low-Field MRI:Operates below 0.1 Tesla using earth-field compensation or specialized coil arrays. Research institutes deploy these for novel contrast mechanisms.
- Compact MRI:Self-contained units under 500 kilograms with shielded designs for standard electrical supply. Mobile clinics across India procure these for tier-2 city outreach.
Volume placements concentrate in Low-Field MRI; the faster expansion belongs to Cryogen-Free MRI.
Technology:
Cost tier stratification separates mature permanent magnet supply chains from emerging zero-helium architectures commanding premium positioning.
- Zero Helium MRI:Conduction-cooled superconducting or high-temperature superconductor designs eliminating cryogenic fluid management. Tertiary hospitals in Saudi Arabia and UAE prioritize these for sustainability compliance.
- Permanent Magnet:Rare-earth alloy assemblies requiring no active cooling infrastructure. Diagnostic centers across Brazil and Mexico standardize on these for reliability in variable power environments.
- Superconducting Magnet:Traditional liquid helium-cooled niobium-titanium coils. Research institutes maintain installed base despite helium supply volatility.
- Resistive Magnet:Copper or aluminum electromagnets with active cooling. Mobile clinics in South Africa deploy these for lowest capital entry points.
Permanent Magnet dominates current installed base; Zero Helium MRI climbs the fastest as health systems prioritize operational autonomy.
Application:
Customer type differentiation separates high-throughput neurology protocols from point-of-care musculoskeletal screening.
- Neurology:Brain and spinal cord imaging requiring highest field homogeneity and motion compensation. Stroke networks across the United States deploy portable units for pre-hospital triage.
- Musculoskeletal Imaging:Joint, soft tissue, and bone marrow assessment tolerating lower field strength. Sports medicine clinics in Australia adopt bedside systems for immediate injury evaluation.
- Cardiology:Cardiac morphology and function assessment with ECG-gated sequences. Research institutes in Switzerland pursue these for novel contrast agents.
- Oncology:Tumor characterization and treatment monitoring protocols. Cancer centers in South Korea integrate portable systems for radiation therapy planning.
Musculoskeletal Imaging captures broadest volume; Neurology gains share fastest as stroke protocol decentralization accelerates.
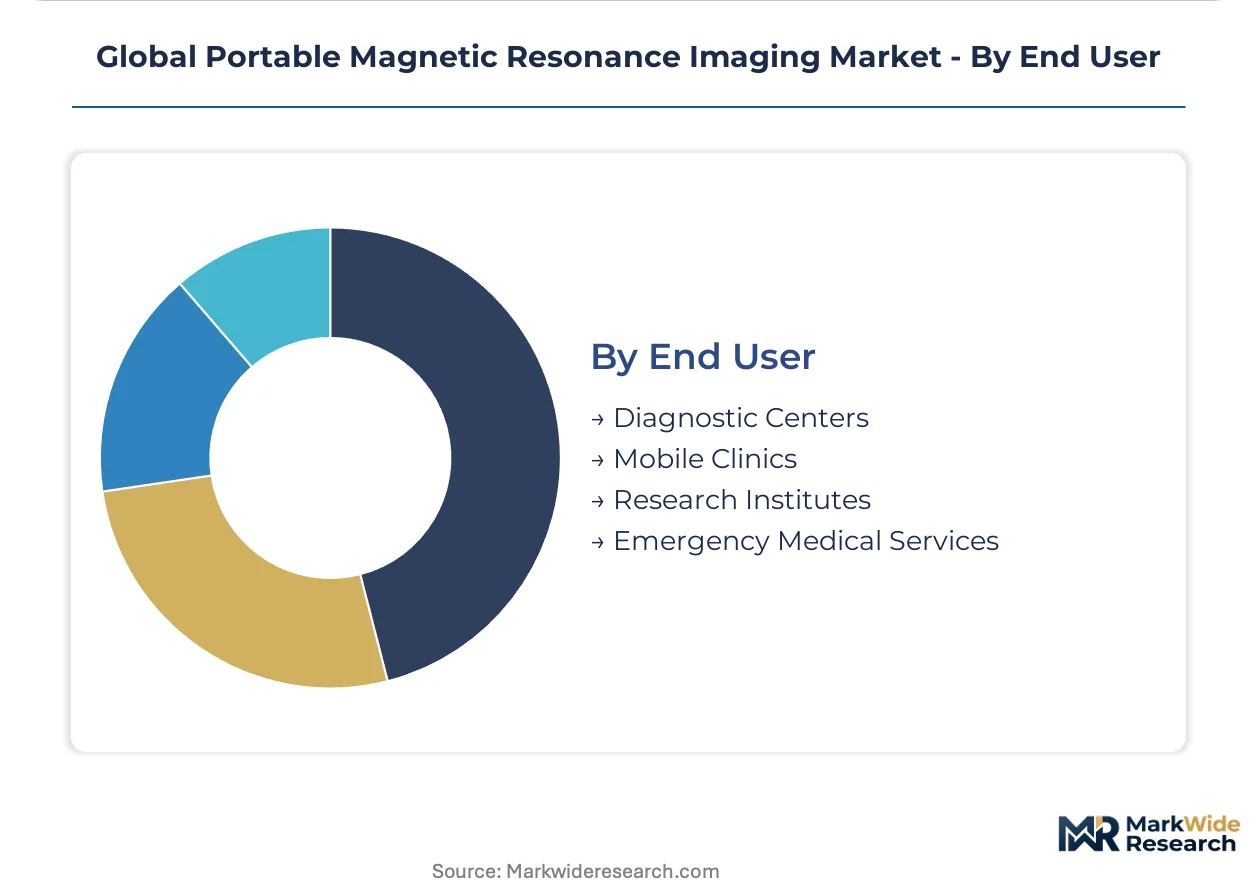
End User:
Supply concentration around cryogen-free architectures favors end users with limited infrastructure investment capacity.
- Emergency Medical Services:Ambulance and pre-hospital deployment requiring shock-hardened designs and battery operation. EMS systems in Japan and Germany lead procurement for stroke and trauma protocols.
- Diagnostic Centers:Fixed outpatient facilities seeking throughput flexibility without construction. India's tier-2 cities drive demand as government insurance expansion broadens access.
- Mobile Clinics:Vehicle-mounted or transportable units for rural and remote outreach. Operators across Indonesia and Philippines deploy these for archipelago coverage.
- Research Institutes:Academic and clinical trial sites requiring protocol flexibility. Institutions in the United Kingdom and Netherlands pursue these for methodology development.
Diagnostic Centers anchor current volume; Emergency Medical Services represents the steepest expansion trajectory as pre-hospital protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet processing in China's Jiangxi and Inner Mongolia provinces anchors upstream supply for cryogen-free architectures, while helium refining in the United States and Qatar shapes superconducting system availability.
United States
Stroke network decentralization and rural hospital consolidation drive procurement of bedside-compatible systems. FDA 510(k) pathway evolution accelerates clearance timelines for low-field devices targeting emergency departments. The Texas Medical Center in Houston hosts multiple pilot deployments validating pre-hospital imaging protocols.
Germany
Pre-hospital stroke care standardization and medical device export manufacturing anchor demand. EU MDR clinical evidence requirements extend market access timelines relative to United States pathways. The Munich-Stuttgart corridor concentrates gradient coil engineering talent and precision manufacturing capacity.
China
County-level hospital network expansion into rural provinces creates procurement pull for cryogen-free systems. NMPA accelerated review tracks for domestically manufactured compact systems compress regulatory timelines versus imported competitors. Shenzhen and Suzhou industrial clusters host magnet stabilization and RF subsystem production.
Japan
Ambulance-compatible imaging for aging population emergency protocols drives adoption of shock-hardened designs. METI medical device innovation programs subsidize point-of-care diagnostic development. The Kansai region around Osaka maintains concentrated MRI component supply chain relationships.
India
Government health insurance expansion and tier-2 city medical tourism investment create demand for mobile diagnostic platforms. CDSCO streamlined clearance for compact imaging devices accelerates product registration timelines. Gujarat and Karnataka host emerging domestic assembly operations for permanent magnet systems.
Global Portable Magnetic Resonance Imaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined architectures and cryogen-free magnet designs. The vendor base stratifies across superconducting legacy manufacturers, permanent magnet specialists, and zero-helium technology developers. Three archetypes dominate: diversified imaging conglomerates with backward integration into gradient production; venture-backed disruptors commercializing low-field bedside systems; and regional fabricators serving price-sensitive procurement channels. Competitive moves concentrate on M&A for RF subsystem capabilities and strategic partnerships for rare-earth supply security.
Among diversified imaging conglomerates, Siemens Healthineers and GE HealthCare exemplify scale-driven positioning through captive magnet and coil production. Hyperfine Inc. represents the venture-backed disruptor archetype pursuing software-defined radiofrequency pathways. These three anchors illustrate the competitive tension between legacy infrastructure optimization and novel architecture commercialization reshaping procurement criteria.
| Leading Market Players |
|---|
| Hyperfine Inc. |
| Siemens Healthineers |
| Canon Medical Systems |
| Voxelgrids Innovations Pvt. Ltd. |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Aspect Imaging Ltd. |
| PrizMed Imaging Solution Inc. |
| Esaote SpA |
| Others |
Supply & Pricing Matrix
Sovereign-backed magnet fabricators in China's Jiangxi province and family-owned Korean coil specialists anchor upstream ownership patterns that compress margin flexibility for Western OEMs while sustaining premium pricing for cryogen-free architectures. Procurement officers at county-level Chinese hospitals and emergency medical services fleets in Germany face divergent total-cost-of-ownership calculations as helium scarcity and field service scarcity reshape supplier pricing power.
Pricing Analysis
Warranty and field service bundling separates premium cryogen-free system vendors from unbundled permanent magnet suppliers competing on capital expenditure alone. Three-tier pricing structure across premium, standard, and economy levels reflects gradient coil origin, NMPA versus FDA regulatory clearance tier, and software reconstruction capability depth. Cost compression in economy-tier permanent magnet units is intensifying because Chinese domestic producers leverage accelerated NMPA tracks to undercut import duties. Emergency medical services buyers exhibit highest price sensitivity due to fleet-scale procurement constraints, while tertiary stroke networks in the United States demonstrate lowest sensitivity given bed-day economics favoring rapid deployment.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Siemens Healthineers and GE HealthCare, while specialized distributors serve mid-tier diagnostic centers and mobile clinic operators. Rare-earth magnet processing concentrates in China, gradient coil winding in South Korea, and helium refining in the United States and Qatar. The supply chain draws from niobium-titanium superconducting wire, rare-earth permanent magnet alloys, and specialized RF subsystem components. Single-source vulnerability in conduction-cooled superconducting magnet assemblies threatens production continuity for zero-helium architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 510(k) pathway evolution and EU MDR clinical evidence requirements erect regulatory moats favoring incumbents with established quality management systems and post-market surveillance infrastructure.
For Market Incumbents: Anchor market position through captive gradient coil production and NMPA-first submission sequencing that locks out multinational competitors from Chinese provincial tenders. Defend against venture-backed bedside MRI disruptors by accelerating software-defined RF pathway development and securing exclusive rare-earth offtake agreements with Jiangxi processors.
For New Entrants and Emerging Players: County-level hospital procurement officers in China's interior provinces represent an underserved buyer archetype seeking cryogen-free systems without import premium pricing. Mobile clinic operators across Indonesia and the Philippines offer secondary white-space entry. Pursue CDSCO-fasttracked compact system registration paired with local assembly partnerships in Gujarat to bypass established OEM distribution.
For Investors and Strategic Acquirers: Distressed-cycle entries favor permanent magnet specialists with established Brazilian and Mexican installed bases facing helium-driven obsolescence pressure. Long-term viability hinges on AI-assisted reconstruction algorithm differentiation bridging low-field signal gaps. Watch FDA breakthrough device designation velocity for low-field neurological applications as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Accelerated Review Track Exploitation | Domestic Chinese producers compress regulatory timelines versus FDA-first competitors. |
| Software-Defined RF Architecture Development | Hyperfine Inc. demonstrates power reduction enabling true bedside deployment. |
| Gradient Coil Backward Integration | GE HealthCare shields margins from rare-earth volatility through captive production. |
| Helium-Free Magnet Supply Security | Siemens Healthineers leverages superconducting legacy for high-specification tertiary installations. |
| AI Reconstruction Algorithm Partnership | Machine learning compensation opens diagnostic equivalence with conventional high-field stroke protocols. |
Research Methodology
SEC 10-K filings, NMPA registration databases, and EU MDR notified body documentation formed the secondary backbone, supplemented by customs records tracking rare-earth magnet and gradient coil trade flows. Primary interviews with biomedical engineers at stroke network hospitals, GPO contracts managers, and field service operations directors at OEMs validated installed base estimates and procurement timeline assumptions. Bottom-up unit shipment modeling triangulated against top-down healthcare capital expenditure surveys across the analysis window.
Historical trendline analysis of permanent magnet versus cryogen-free system shipments informed penetration curve assumptions across the projection horizon. Segmentation dimensions modeled include magnet technology tier, application specialty, end-user facility type, and regional regulatory cluster. CAGRs derived from curve-fitting procedures applied to validated base-year estimates. Industry-specific forecast inputs encompassed helium spot price volatility indices and NMPA review track velocity differentials.
Revisions become necessary when FDA low-field guidance shifts materially, Chinese rare-earth export controls tighten, or AI reconstruction algorithms achieve breakthrough device designation. Forecasts reflect documented assumptions regarding regulatory pathway stability and rare-earth supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Global Dental Panoramic Radiography Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
Spectroscopy Intravascular Imaging System Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Optical Coherence Tomography Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
Mexico Digital X-Ray Devices Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
Retinal Imaging Devices Market