
 Zeolite Molecular Sieve Market | 2026-2036
Zeolite Molecular Sieve Market Size, Share, and Industry Trends Forecast 2026-2036
Zeolite Molecular Sieve Market Intelligence
Buyer concentration in the petrochemical sector is pivoting toward integrated refinery-petrochemical complexes that demand higher-performance separation media. Tosoh Corporation leverages its synthetic zeolite expertise to serve Asian ethylene producers with tailored catalyst supports. BASF anchors European supply through its Ludwigshafen production hub, while Clariant competes on specialty activated zeolites for pharmaceutical drying applications.
Zeolite molecular sieves are crystalline aluminosilicates with uniform pore diameters typically ranging from 3 to 10 angstroms, engineered for selective adsorption based on molecular size and polarity. Their primary commercial purpose centers on gas separation, catalysis, and desiccation across process industries where thermal and chemical stability under cyclic regeneration defines performance. Synthetic zeolite commands the dominant value share due to reproducible pore architecture and tunable silica-to-alumina ratios, while zeolite membrane represents the fastest-expanding frontier with potential to displace energy-intensive cryogenic distillation in select separations. Gas separation applications concentrate margin pools in oxygen-nitrogen and hydrogen purification systems for steel and chemical producers.
The EPA enforces Maximum Achievable Control Technology standards that compel petrochemical operators to retrofit volatile organic compound recovery systems with advanced molecular sieve beds. REACH in Europe restricts certain binder chemistries used in zeolite pelletization, redirecting formulation R&D toward compliant aluminophosphate alternatives. OSHA crystalline silica exposure limits further shape workplace handling protocols and dust containment investments across the value chain. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost calculus for imported synthetic zeolite versus regional production.
Market Dynamics
Refinery-petrochemical integration is compressing procurement cycles for high-performance separation media, forcing molecular sieve suppliers to align product development with FCC unit upgrades and hydrogen purification retrofits simultaneously.
Growth Catalysts
- EPA Maximum Achievable Control Technology:Petrochemical operators in the United States face mandated VOC recovery system upgrades, accelerating replacement of aging adsorbent beds with advanced zeolite formulations.
- Steel industry hydrogen purification:Direct reduced iron facilities are expanding molecular sieve-based PSA units to meet metallurgical-grade hydrogen specifications for carbon-neutral steelmaking.
- China's eastern seaboard petrochemical corridor:State-led ethylene capacity additions concentrate demand for catalytic cracking catalysts and process drying media in integrated complexes from Dalian to Ningbo.
Market Restraints
- Alumina and sodium silicate cost volatility:Synthetic zeolite production depends on petrochemical-derived feedstocks and energy-intensive alkali processing, exposing margins to input price swings.
- REACH restriction on binder chemistries:European pelletization formulations face phased constraints on certain aluminosilicate binders, forcing R&D redirection toward compliant aluminophosphate alternatives.
- Zeolite membrane technical immaturity:Industrial-scale membrane fabrication yields remain below crystalline adsorbent reliability thresholds, limiting displacement of cryogenic distillation in bulk gas separations.
Strategic Opportunities
- India's petrochemical expansion:Reliance Industries and Indian Oil are building integrated refinery-petrochemical complexes that lack domestic high-performance molecular sieve supply, creating import substitution potential.
- Carbon border adjustment mechanisms:The EU's CBAM creates cost advantages for regional synthetic zeolite production over imports from carbon-intensive manufacturing jurisdictions.
- Pharmaceutical lyophilization drying:Activated zeolite demand for sterile API processing is outpacing supply from specialty chemical producers focused on industrial gas applications.
Industry Challenges
- Crystalline silica handling compliance:OSHA exposure limits for synthetic zeolite dust require capital-intensive containment systems and worker protection protocols that elevate operating costs.
- Membrane-to-module integration complexity:Zeolite membrane suppliers struggle to achieve reliable sealing and thermal cycling performance in commercial-scale separation modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zeolite Molecular Sieve Market |
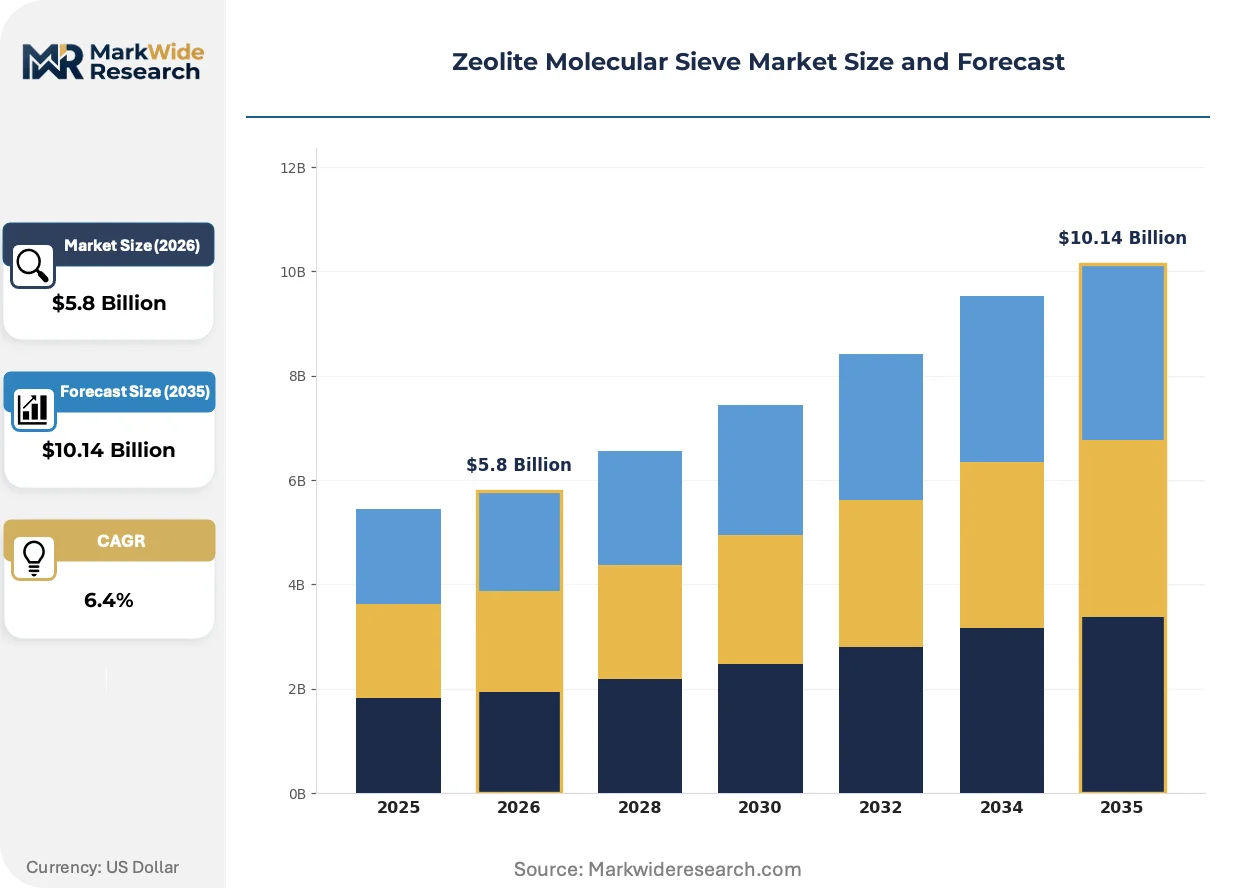
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Zeolite, Synthetic Zeolite, Activated Zeolite, Zeolite Membrane Application: Gas Separation, Catalysis, Water Treatment, Air Purification End User: Petrochemical, Pharmaceutical, Agriculture, Water Treatment Facilities Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Tosoh Corporation, Zeolyst International, BASF, UOP LLC, Zeochem, Clariant, W. R. Grace & Co., Arkema, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zeolite Molecular Sieve Market Strategic Shifts & Innovations
Digital process control and materials informatics are compressing zeolite development cycles, enabling faster optimization of pore architectures for specific hydrocarbon separations than traditional hydrothermal synthesis methods permitted.
Machine learning-guided zeolite synthesis is automating the screening of silica-to-alumina ratios and cation exchange protocols that previously required months of laboratory iteration. BASF and academic consortia in Germany are deploying these platforms to accelerate FCC catalyst optimization for heavy crude processing. The technology is compressing time-to-market for tailored molecular sieves from years to months.
REACH authorization procedures for aluminosilicate binders are forcing European pellet manufacturers to reformulate with aluminophosphate and hybrid organic-inorganic matrices. The regulatory pressure is redirecting R&D budgets away from performance optimization toward compliance verification. Specialty activated zeolites for pharmaceutical applications face the most severe certification timeline extensions.
Integrated refinery-petrochemical operators are consolidating molecular sieve procurement under single-source framework agreements that bundle catalytic cracking, hydrogen purification, and process drying media. Trading houses and regional distributors are losing share to direct supplier relationships in the Middle East and Asia-Pacific. Saudi Aramco's Jazan and SATORP complexes exemplify this concentration pattern.
Zeolite Molecular Sieve Market Segmentation
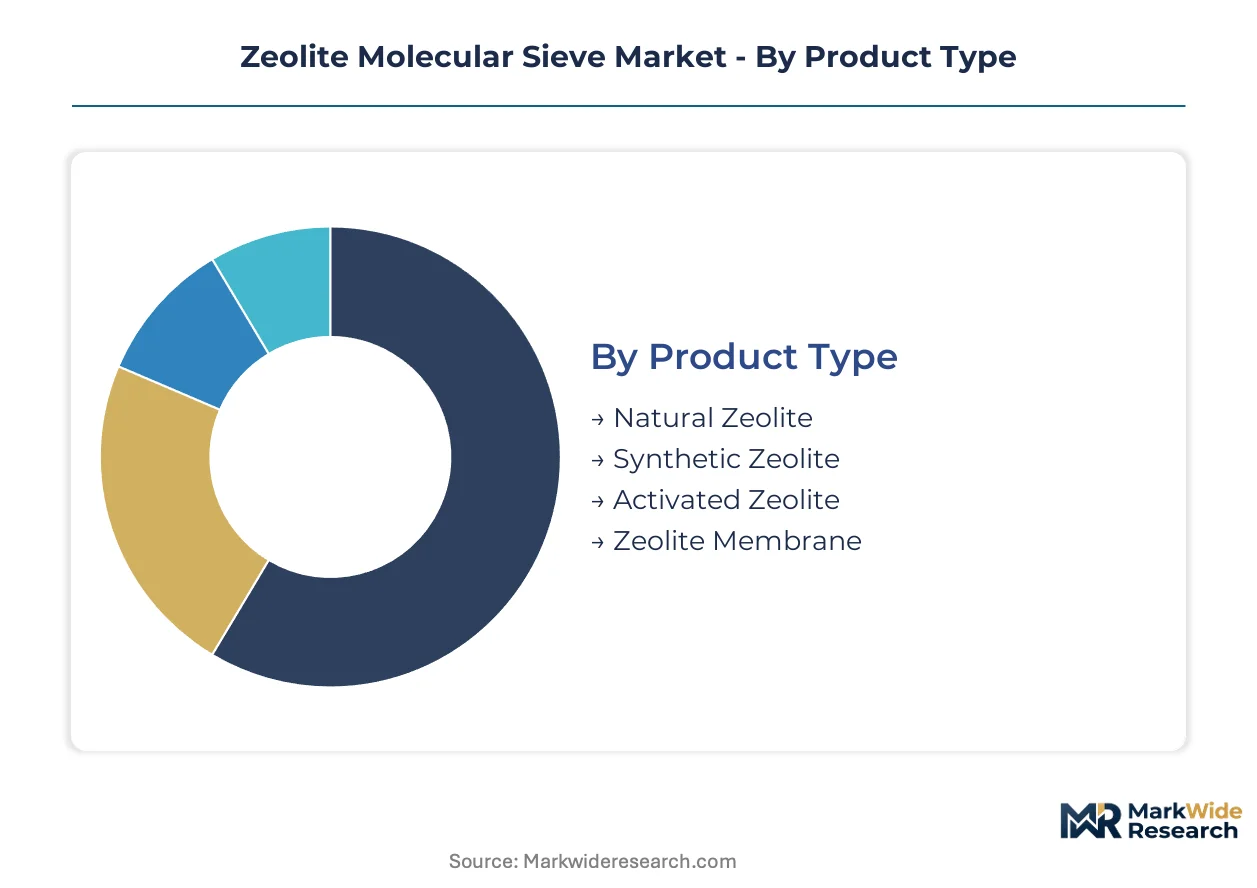
Segmentation in the zeolite molecular sieve market reveals how capital deployment, technical specifications, and regulatory exposure fragment purchasing behavior across process industries. Procurement patterns diverge sharply between bulk synthetic zeolite buyers seeking volume contracts and specialty activated zeolite purchasers prioritizing batch certification.
Product Type:
Capital intensity varies dramatically across product categories, with zeolite membrane fabrication requiring specialized hydrothermal synthesis equipment and cleanroom assembly infrastructure that synthetic zeolite pelletization plants do not need.
- Synthetic Zeolite:Manufactured through controlled alkali fusion and hydrothermal crystallization, synthetic zeolite delivers reproducible pore architectures with tunable silica-to-alumina ratios. Petrochemical refiners in China and the United States concentrate procurement for fluid catalytic cracking and hydrogen purification units, driven by EPA Maximum Achievable Control Technology mandates for VOC recovery retrofits.
- Zeolite Membrane:Thin-film crystalline layers supported on ceramic or metallic substrates enable energy-efficient molecular separations without thermal cycling. Direct reduced iron facilities in Europe and Asia are piloting membrane modules for metallurgical-grade hydrogen production, constrained by fabrication yield thresholds below crystalline adsorbent reliability.
- Natural Zeolite:Mined aluminosilicate deposits with inherent pore heterogeneity serve cost-sensitive agricultural and construction applications where performance consistency matters less than unit economics.
- Activated Zeolite:Thermally and chemically treated to maximize surface area and cation exchange capacity, this grade commands pharmaceutical and food-grade certifications that extend production timelines.
Most installed capacity flows through synthetic zeolite. Expansion is steepest in zeolite membrane.
Application:
Application selection correlates with margin structure, where gas separation systems for steel and chemical producers capture premium pricing over commodity water treatment deployments.
- Gas Separation:Pressure swing adsorption and vacuum swing adsorption systems separate oxygen-nitrogen mixtures and purify hydrogen streams using molecular size-selective zeolite beds. Steel industry decarbonization projects in Germany, Japan, and South Korea are expanding PSA unit orders for direct reduced iron processes.
- Catalysis:Zeolite acid sites and shape-selective pores enable hydrocarbon cracking, isomerization, and alkylation in petrochemical conversion. Refinery-petrochemical integration along China's eastern seaboard from Dalian to Ningbo concentrates demand for FCC catalyst optimization.
- Water Treatment:Ion exchange and adsorption applications remove heavy metals, ammonia, and radionuclides from municipal and industrial effluent streams.
- Air Purification:Desiccant drying and VOC capture protect sensitive manufacturing environments and comply with emissions regulations.
Gas separation commands the highest unit margins. Catalysis delivers the largest absolute volume.
End User:
End user concentration determines contract structure, with petrochemical procurement teams negotiating multi-year framework agreements that pharmaceutical buyers resist due to batch-specific certification requirements.
- Petrochemical:Integrated refinery-petrochemical complexes consume molecular sieves across catalytic cracking, hydrogen purification, and process drying functions. Saudi Aramco's Jazan and SATORP complexes exemplify consolidated procurement under single-source agreements.
- Pharmaceutical:Sterile API lyophilization and final drug product drying demand activated zeolite with validated endotoxin and particulate specifications. REACH authorization delays for aluminosilicate binders are extending European supply lead times.
- Agriculture:Soil amendment and slow-release fertilizer applications utilize natural zeolite for cation retention and moisture management.
- Water Treatment Facilities:Municipal and industrial plants deploy zeolite for ammonia removal and heavy metal capture in regions with stringent discharge permits.
Petrochemical buyers consolidate purchasing power fastest. Pharmaceutical specifications are tightening most rapidly.
Distribution Channel:
Channel selection reflects buyer scale and technical support needs, with direct relationships displacing intermediaries where application engineering complexity is highest.
- Direct Sales:Supplier technical service teams configure molecular sieve specifications for FCC unit upgrades and PSA system retrofits. Middle Eastern and Asia-Pacific integrated complexes are shifting procurement away from trading houses toward direct manufacturer relationships.
- Distributors:Regional inventory and logistics support smaller water treatment and agriculture customers with standardized product grades.
- Online Retail:E-commerce platforms serve research institutions and small-scale industrial buyers with catalog zeolite products.
- Wholesalers:Bulk aggregation of natural zeolite supplies construction and agricultural markets with minimal technical differentiation.
Direct sales capture the largest contract values. Distributor relationships are compressing fastest in specialty grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates zeolite molecular sieve procurement through state-led petrochemical expansion, while the United States enforces stricter emissions controls that accelerate adsorbent bed replacements. Germany anchors European supply through integrated chemical production hubs. India's emerging refinery-petrochemical complexes lack domestic high-performance supply.
United States
Petrochemical refiners expand catalytic cracking capacity to process heavier crude slates. The EPA enforces Maximum Achievable Control Technology standards that mandate VOC recovery system upgrades with advanced molecular sieve beds. Gulf Coast integrated complexes from Houston to Port Arthur drive concentrated demand for hydrogen purification retrofits.
China
State-led ethylene capacity additions along the eastern seaboard concentrate demand for process drying media and catalyst supports. MEE regulations on industrial emissions tighten compliance timelines for air separation unit operators. Integrated complexes from Dalian to Ningbo consolidate procurement under single-source framework agreements.
Germany
Steel industry decarbonization projects expand PSA unit orders for direct reduced iron processes requiring metallurgical-grade hydrogen. REACH authorization procedures for aluminosilicate binders force reformulation toward aluminophosphate alternatives. The Ludwigshafen chemical production hub anchors regional synthetic zeolite supply.
India
Reliance Industries and Indian Oil construct integrated refinery-petrochemical complexes that lack domestic high-performance molecular sieve supply. BIS standards for industrial chemicals create certification barriers for imported formulations. Gujarat and Maharashtra coastal clusters generate import substitution opportunities for specialty activated grades.
Saudi Arabia
Saudi Aramco's Jazan and SATORP complexes exemplify consolidated procurement patterns across catalytic cracking and hydrogen purification functions. The country's national industrial regulator enforces emissions controls that align with international petrochemical standards. Eastern Province industrial cities concentrate demand for direct supplier relationships displacing trading intermediaries.
Zeolite Molecular Sieve Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across distinct margin tiers in the zeolite molecular sieve market. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with captive zeolite production, specialty adsorbent specialists serving pharmaceutical and food-grade certifications, and regional manufacturers supplying cost-sensitive natural zeolite applications. Dominant competitive moves include backward integration into synthetic zeolite feedstock production and strategic partnerships with refinery-petrochemical operators for long-term supply agreements.
Among Japanese chemical conglomerates, Tosoh Corporation occupies a position exemplifying synthetic zeolite expertise tailored for Asian ethylene producers. BASF SE anchors the European tier through its Ludwigshafen production hub, representing the integrated chemical conglomerate archetype with captive supply capabilities. Clariant AG sits within the specialty activated zeolite segment, occupying a position aligned with pharmaceutical drying applications facing stringent certification requirements.
| Leading Market Players |
|---|
| Tosoh Corporation |
| Zeolyst International |
| BASF |
| UOP LLC |
| Zeochem |
| Clariant |
| W. R. Grace & Co. |
| Arkema |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
Alumina and sodium silicate feedstock costs cascade through synthetic zeolite production tiers, compressing margins for pellet manufacturers serving commodity petrochemical buyers while specialty activated grades retain pricing power through pharmaceutical certification premiums.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade synthetic zeolite, forcing European and North American producers toward premium-mid-economy pricing differentiation based on REACH-compliant binder formulations and validated FCC catalyst performance. Price differentiation hinges on silica-to-alumina ratio precision and EPA MACT certification status. Cost compression in commodity grades is intensifying because of energy-intensive alkali processing exposure. Water treatment facilities exhibit highest price sensitivity; pharmaceutical API producers show least.
Supply Chain Analysis
Single-source vulnerability sits with Chinese state-led petrochemical complexes that internalize molecular sieve procurement through direct supplier relationships, bypassing traditional trading intermediaries. Manufacturing concentrates in China, Germany, and the United States. Production draws from bauxite-derived alumina, sodium silicate, and rare earth cation exchange media. Tariff exposure on ceramic membrane substrates threatens zeolite membrane fabrication economics. Distribution runs through direct technical service teams for integrated refinery-petrochemical operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
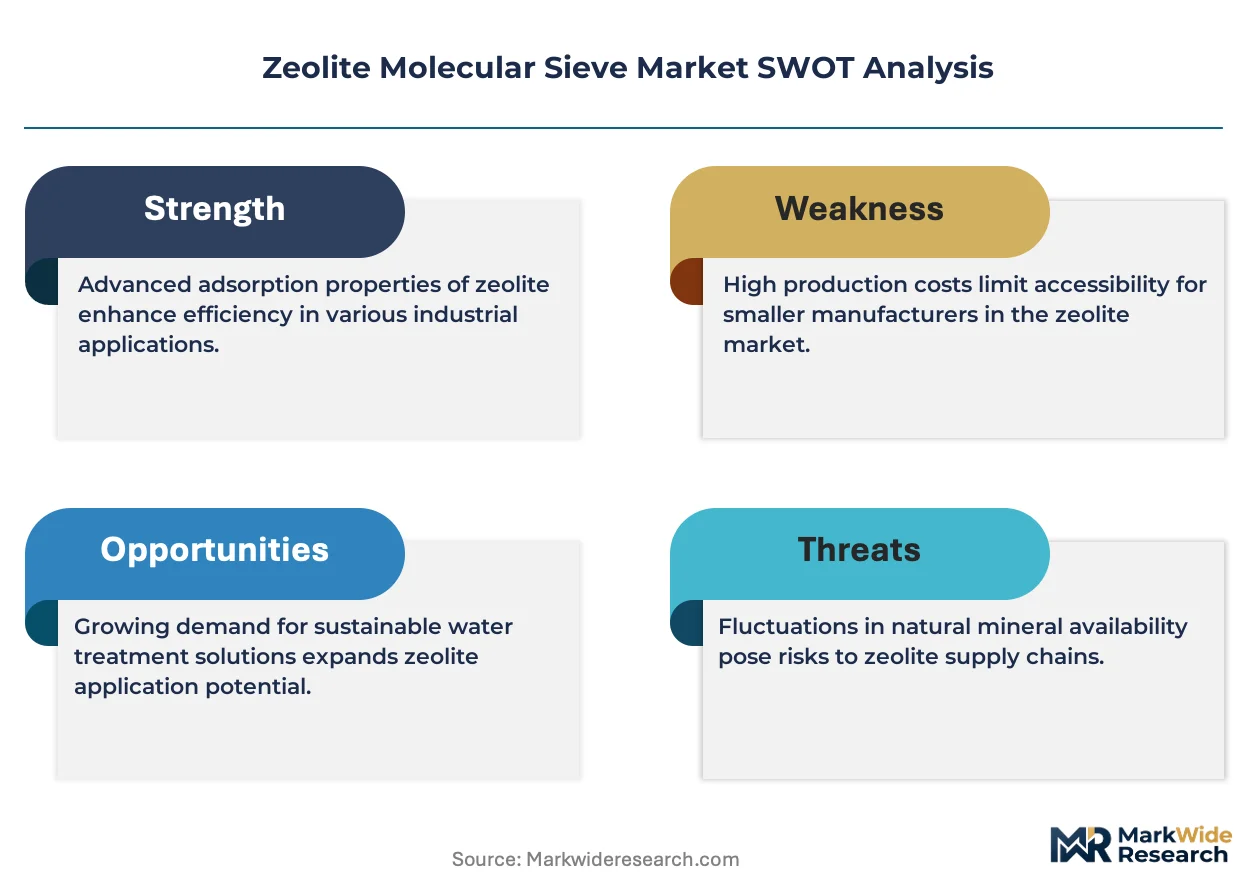
This market rewards geographic arbitrage between carbon-intensive synthetic zeolite production jurisdictions and EU CBAM-compliant regional manufacturing, exploiting regulatory cost differentials that widen with each phased carbon border adjustment mechanism expansion.
For Market Incumbents: Hedge against zeolite membrane displacement of PSA systems by deepening captive supply of high-purity hydrogen separation media and securing long-term framework agreements with Saudi Aramco-scale integrated complexes before membrane fabrication yields mature. Prioritize aluminophosphate binder R&D to preempt REACH authorization bottlenecks. For New Entrants and Emerging Players: Direct-to-technical-buyer digital platforms offer low-friction entry into India's import-dependent refinery-petrochemical corridor, where Reliance Industries and Indian Oil lack domestic high-performance supply. Target pharmaceutical lyophilization drying as the most penetrable segment, exploiting REACH-extended European lead times with BIS-certified activated zeolite formulations. For Investors and Strategic Acquirers: Roll-up economics work for specialty activated zeolite specialists because pharmaceutical batch certification creates sticky customer relationships and high switching costs that compound through acquisition scale. Long-term viability favors producers with dual petrochemical-pharmaceutical grade capabilities. Watch zeolite membrane fabrication yield thresholds as the inflection signal for cryogenic displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Supply | Captive feedstock production insulates margins from bauxite price volatility affecting synthetic zeolite pelletization. |
| REACH-Compliant Binder Reformulation | Aluminophosphate alternatives to restricted aluminosilicate binders preserve European market access for pellet manufacturers. |
| Long-term Supply Agreement with Integrated Complexes | Direct relationships with Saudi Aramco's Jazan and SATORP complexes displace trading house intermediaries. |
| Zeolite Membrane Module Development | Thin-film crystalline layers on ceramic substrates target metallurgical-grade hydrogen purification for direct reduced iron facilities. |
| Pharmaceutical Certification Investment | Validated endotoxin and particulate specifications for sterile API lyophilization capture premium pricing over industrial grades. |
Research Approach
Coverage spans the United States, China, Germany, India, and Saudi Arabia, with primary inputs from each combining interviews with petrochemical procurement directors, FCC unit process engineers, pharmaceutical quality assurance managers, and zeolite membrane R&D leads with secondary validation through EPA MACT enforcement records, REACH authorization databases, ECHA substance registry filings, and customs trade data. Bottom-up capacity estimates triangulate against top-down petrochemical expansion project announcements.
Rate-of-change decomposition separates volume growth from price realization across synthetic zeolite, zeolite membrane, natural zeolite, and activated zeolite product tiers; gas separation, catalysis, water treatment, and air purification applications; and petrochemical, pharmaceutical, agriculture, and water treatment end users. CAGRs derive from segmented demand modeling incorporating steel industry hydrogen purification retrofit timelines, China's eastern seaboard ethylene capacity additions, and pharmaceutical lyophilization drying equipment installations.
The model assumes a particular technology adoption path; alternative pathways for zeolite membrane fabrication yield breakthroughs would alter the outlook for cryogenic distillation displacement in bulk oxygen-nitrogen separations. Forecasts reflect assumptions about REACH authorization timelines, EPA MACT enforcement intensity, and carbon border adjustment mechanism scope expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Secondary Reforming Catalyst Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Polyurethane Catalysts Market
Catalysts
Hydrodesulfurization Catalyst Market
Catalysts
Syngas to Ethylene Glycol Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
Catalase Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market
Catalysts
Hydrotreating Catalyst Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
FCC Catalyst Additive Market